
 Global Reflux Testing Products Market | 2026-2036
Global Reflux Testing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reflux Testing Products Market Intelligence
Hospital-based gastroenterology departments is unwinding toward ambulatory care centers and specialty clinics as the primary procurement channel for reflux testing systems. Medtronic PLC leverages its integrated catheter and monitoring platform to sustain institutional contracts across North American and European health networks. Laborie Medical Technologies Corp. anchors its position through specialized high-resolution manometry systems that dominate academic medical center purchasing committees.
Reflux testing products encompass impedance-pH monitors, wireless capsule systems, and multichannel intraluminal impedance catheters designed to quantify acid exposure, bolus transit, and esophageal motility across 24- to 48-hour monitoring windows. These devices serve the primary commercial purpose of objectively diagnosing gastroesophageal reflux disease and distinguishing esophageal from extraesophageal symptom origins. Wireless capsule technology captures the fastest-growing segment position as patient tolerance and procedure throughput outpace stationary system economics. Impedance-pH monitors occupy the mature revenue core where replacement cycles and software upgrades defend incumbent supplier relationships. Catheter-based systems concentrate margin pools in disposable consumables that lock purchasing into single-vendor ecosystems.
FDA 510(k) premarket notification requirements and the EU MDR technical documentation standards shape product development timelines and market access costs for impedance-pH and wireless capsule manufacturers. The EPA regulates disposal pathways for catheter materials containing electronic components, adding compliance layers to end-of-life product stewardship. Stakeholders must monitor how reimbursement coding revisions for ambulatory reflux monitoring interact with capital equipment budgeting cycles in hospital outpatient departments.
Market Dynamics
Wireless capsule technology is fragmenting the traditional impedance-pH monitor installed base as ambulatory care centers prioritize patient throughput over stationary diagnostic throughput. This shift compresses capital equipment replacement cycles while expanding disposable consumable revenue pools for catheter-based systems.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States exhibit expanding GERD diagnostic volumes as populations over 65 drive endoscopy referral pathways and ambulatory monitoring demand.
- FDA 510(k) pathway streamlining:Predicate device clearance for wireless capsule systems accelerates time-to-market for manufacturers with established impedance-pH portfolios.
- Reimbursement expansion:Hospital outpatient departments in the United States secure Category I CPT coding for prolonged pH monitoring, validating capital investment in wireless platforms.
Market Restraints
- EU MDR technical documentation burden:Impedance-pH manufacturers face extended conformity assessment timelines and notified body capacity constraints for legacy device recertification.
- Single-use catheter supply concentration:Polymer sourcing for multichannel intraluminal impedance catheters clusters with specialty extrusion houses in Germany and Switzerland, creating input vulnerability.
- Capsule retrieval failure rates:Wireless systems exhibit non-negligible spontaneous detachment events requiring repeat procedures, limiting adoption in pediatric and elderly populations.
Strategic Opportunities
- India diagnostic infrastructure buildout:Tier-2 city hospital networks lack reflux testing penetration, creating first-mover positioning for portable impedance-pH systems with simplified software interfaces.
- AI-integrated waveform analysis:Machine learning classification of bolus transit patterns converges with impedance-pH hardware to reduce specialist interpretation burden and expand community hospital deployment.
- Direct-to-specialist distribution:Bypassing traditional hospital procurement committees through gastroenterology society purchasing cooperatives unlocks faster wireless capsule adoption in United States ambulatory surgery centers.
Industry Challenges
- Electrophysiology technician scarcity:Impedance-pH catheter placement and troubleshooting demand specialized nursing competency that academic medical centers struggle to retain against device industry recruiters.
- Legacy system integration:Wireless capsule data platforms require HL7 FHIR connectivity investments that strain IT budgets in mid-sized European hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reflux Testing Products Market |
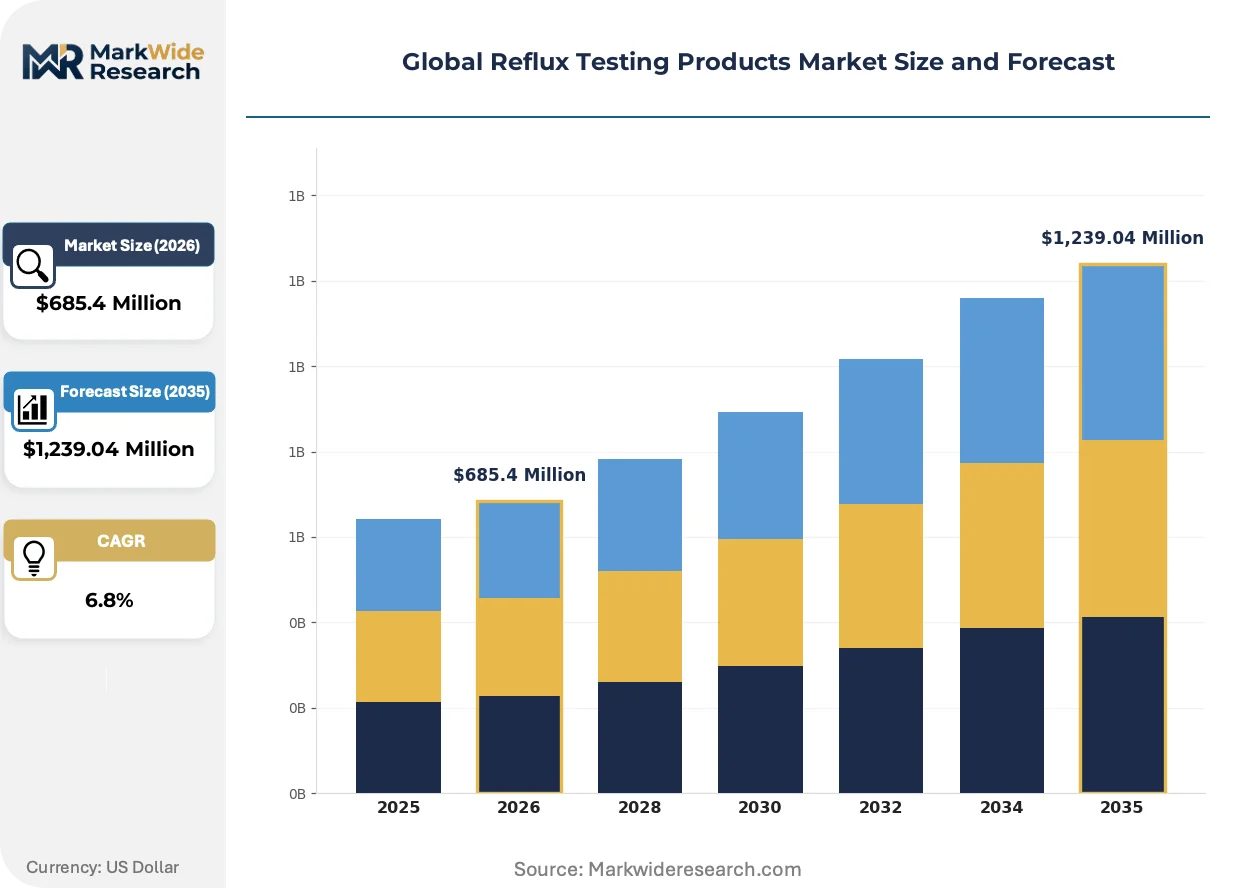
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impedance-pH Monitors, Wireless Capsule, Catheters, Portable Recorders, Software Systems Technology: Ambulatory Monitoring, Stationary Systems, Multichannel Intraluminal Impedance, High-Resolution Manometry, Digital Signal Processing Application: Gastroesophageal Reflux Disease Diagnosis, Laryngopharyngeal Reflux Detection, Barrett's Esophagus Monitoring, Extraesophageal Symptom Assessment, Acid Exposure Measurement End User: Specialty Clinics, Diagnostic Labs, Research Institutions, Ambulatory Care Centers, Clinical Hospitals |
| Companies Covered | Medical Measurement Systems BV, Sierra Instruments, Inc., Medtronic PLC, DRG Instruments GmbH, Ethicon, Inc., Laborie Medical Technologies Corp., Respiratory Technology Corporation, AstraZeneca PLC, Diversatek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reflux Testing Products Market Strategic Shifts & Innovations
Reflux testing hardware is bifurcating into disposable-centric wireless platforms and software-augmented stationary systems, with artificial intelligence insertion reshaping both diagnostic accuracy and operational economics across procurement channels.
Catheter-based impedance-pH monitoring is decomposing into modular sensor arrays and detachable data transmitters. Academic medical centers in Germany and Japan adopt these hybrid configurations to preserve capital equipment while refreshing disposable technology cycles. This architecture compresses per-procedure hardware amortization and enables single-vendor lock-in through proprietary catheter-electronics pairing protocols.
The EU MDR post-market surveillance requirements impose systematic clinical follow-up obligations on wireless capsule manufacturers that exceed FDA 510(k) periodic reporting. European notified bodies mandate real-world performance registries for esophageal pH capsules, elevating compliance costs and favoring incumbent suppliers with established quality management systems. Small-cap entrants redirect development resources toward United States premarket notification pathways where predicate device strategies remain viable.
Hospital procurement committees now unbundle capital equipment acquisition from multi-year disposable supply agreements, reversing the bundled contracting that protected impedance-pH incumbents for decades. Ambulatory surgery centers in the United States exploit this fragmentation to source wireless capsules through group purchasing organizations while negotiating direct software licensing for data interpretation platforms. This purchasing pattern concentrates price transparency pressure on catheter consumable margins in North American outpatient settings.
Global Reflux Testing Products Market Segmentation
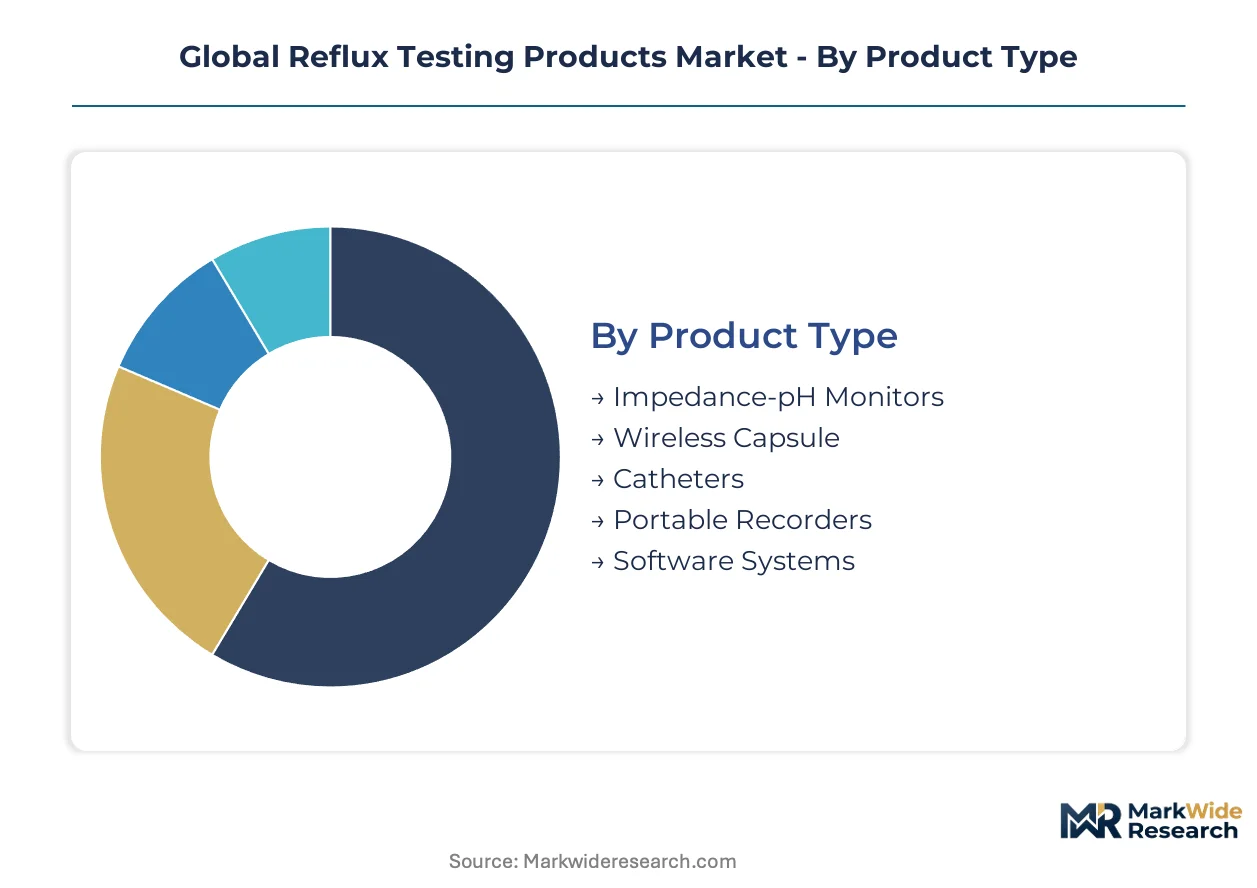
Reflux testing products fragment across hardware, software, and service layers that each carry distinct procurement cycles and margin structures. Understanding these divisions clarifies where capital investment concentrates versus where disposable revenue pools accumulate.
Product Type:
Domestic production clusters in the United States and Germany for catheter-based systems, while wireless capsule manufacturing spreads across Swiss and Japanese contract houses serving export markets.
- Impedance-pH Monitors:Stationary bedside units combine pH electrodes with impedance sensors to quantify acid and non-acid reflux episodes. Demand concentrates in German and Japanese academic medical centers where replacement cycles for legacy hardware drive recurring revenue.
- Wireless Capsule:Battery-powered esophageal pH capsules transmit data to portable receivers, eliminating catheter discomfort. Export-led growth runs through United States ambulatory surgery centers prioritizing patient throughput over stationary diagnostic economics.
- Catheters:Multichannel intraluminal impedance catheters with embedded sensors dominate disposable consumable revenue.
- Portable Recorders:Belt-worn data loggers pair with catheter or capsule systems for ambulatory monitoring.
- Software Systems:Waveform analysis platforms with automated scoring algorithms reduce specialist interpretation burden.
Impedance-pH Monitors command the established base. The steepest expansion runs through Wireless Capsule.
Technology:
Cost tiering separates premium high-resolution manometry from standard ambulatory monitoring, with digital signal processing modules commanding software licensing premiums.
- Ambulatory Monitoring:Wearable systems enabling 24- to 48-hour pH and impedance recording outside clinical settings. United States specialty clinics drive volume as Category I CPT reimbursement validates capital deployment.
- Stationary Systems:Bedside reflux testing hardware tethered to hospital IT networks. Japanese clinical hospitals retain installed base for inpatient GERD workups despite ambulatory migration.
- Multichannel Intraluminal Impedance:Catheter-based bolus transit detection spanning liquid, gas, and mixed reflux events.
- High-Resolution Manometry:Pressure topography mapping for esophageal motility assessment concurrent with reflux testing.
- Digital Signal Processing:Embedded algorithms filtering artifact and automating episode detection.
Ambulatory Monitoring captures volume leadership. High-Resolution Manometry claims the premium tier.
Application:
Volume concentrates in GERD diagnosis while margin pools form around Barrett's surveillance protocols requiring longitudinal monitoring.
- Gastroesophageal Reflux Disease Diagnosis:Objective quantification of acid exposure time and symptom association probability. German gastroenterology departments anchor demand as statutory reimbursement covers ambulatory pH monitoring.
- Laryngopharyngeal Reflux Detection:Hypopharyngeal pH monitoring for extraesophageal symptoms including chronic cough and hoarseness. United States otolaryngology practices drive adoption as dual-specialty referral pathways expand.
- Barrett's Esophagus Monitoring:Longitudinal acid exposure tracking for dysplasia surveillance protocols.
- Extraesophageal Symptom Assessment:Reflux attribution for asthma, dental erosion, and atypical chest pain.
- Acid Exposure Measurement:Standard pH-only monitoring for uncomplicated GERD confirmation.
Gastroesophageal Reflux Disease Diagnosis commands the established base. Laryngopharyngeal Reflux Detection shows the steepest expansion trajectory.
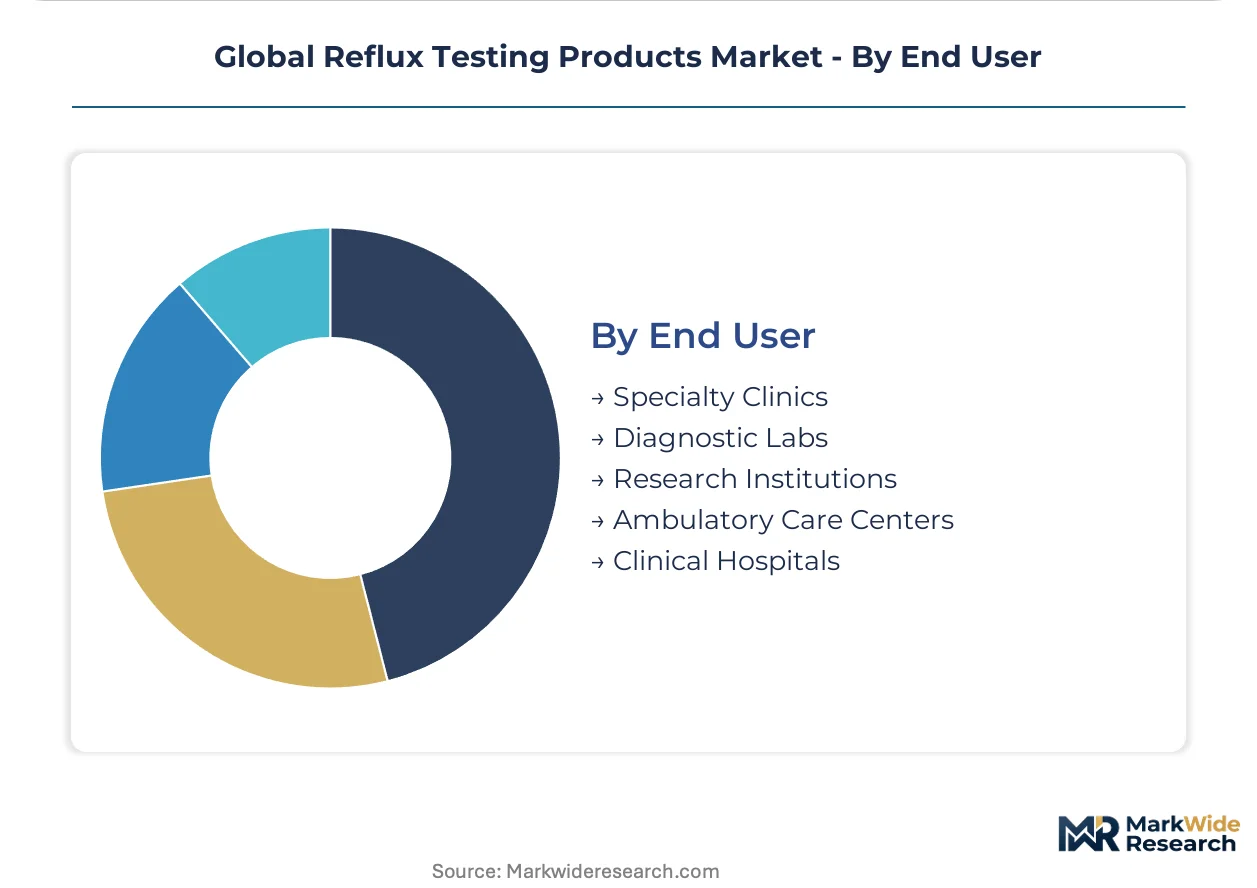
End User:
Procurement authority is shifting from hospital committees toward ambulatory care center administrators with distinct capital budgeting constraints.
- Specialty Clinics:Gastroenterology-focused outpatient facilities with direct physician equipment purchasing. United States independent practice associations aggregate buying power through group purchasing organizations.
- Diagnostic Labs:Centralized testing facilities processing referred pH studies. German laboratory networks exploit regional density for equipment utilization rates exceeding hospital benchmarks.
- Research Institutions:Academic centers validating novel biomarkers and monitoring protocols.
- Ambulatory Care Centers:Same-day surgery facilities prioritizing wireless capsule throughput.
- Clinical Hospitals:Integrated health systems with legacy impedance-pH installed base requiring maintenance contracts.
Clinical Hospitals command the established base. Ambulatory Care Centers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catheter manufacturers supply impedance-pH systems to Japanese academic medical centers, establishing the primary trans-Atlantic trade corridor for reflux testing hardware.
United States
Ambulatory surgery centers in Texas and Florida drive wireless capsule procurement as Category I CPT reimbursement validates capital deployment. FDA 510(k) predicate device pathways accelerate clearance timelines for established manufacturers. The Minneapolis medical device cluster anchors production of disposable multichannel catheters serving domestic outpatient networks.
Germany
Statutory health insurance covers prolonged pH monitoring, sustaining demand from Bavarian gastroenterology departments. EU MDR technical documentation requirements extend conformity assessment timelines for legacy impedance-pH systems. The Baden-Württemberg precision engineering corridor concentrates specialty polymer extrusion for catheter sensor arrays.
Japan
PMDA post-market surveillance obligations shape wireless capsule registration strategies for foreign entrants. METI funding supports domestic production of high-resolution manometry systems for regional export. The Kansai medical technology cluster around Osaka maintains installed bases of stationary reflux monitors despite ambulatory migration trends.
India
Tier-2 city hospital networks in Maharashtra and Gujarat lack reflux testing penetration, creating positioning opportunities for portable systems. CDSCO medical device rules impose registration requirements on imported impedance-pH hardware. The Delhi-NCR diagnostic corridor sees emerging demand from corporate hospital chains expanding gastroenterology service lines.
Switzerland
Swissmedic quality system inspections favor incumbent suppliers with established MDR compliance infrastructure. Private clinics in Zurich and Geneva prioritize wireless capsule throughput for insured patient populations. The Basel pharmaceutical-device convergence zone supports contract manufacturing of pH-sensitive polymers for capsule sensors.
Global Reflux Testing Products Market Key Industry Players
Listed leaders compete with private specialists across capital equipment and disposable consumable segments. The vendor base exhibits tiered concentration, with integrated health technology conglomerates anchoring institutional contracts while mid-cap specialists dominate academic purchasing committees. Two archetypes prevail: diversified medical device platforms leveraging catheter-monitor integration, and focused diagnostics players exploiting high-resolution manometry specialization. Competitive moves concentrate on M&A for wireless capsule technology access and strategic partnerships for AI-integrated waveform software.
Within the diversified platform tier, Medtronic PLC and Laborie Medical Technologies Corp. exemplify contrasting scale strategies. Medtronic anchors North American health network relationships through integrated system offerings. Laborie occupies a specialized position in academic medical center procurement channels. Among European-focused specialists, DRG Instruments GmbH represents the mid-cap fabrication archetype serving regional diagnostic laboratory networks. Medical Measurement Systems BV sits within the Benelux-centered distribution specialist tier, while Diversatek, Inc. exemplifies the United States-based ambulatory care-focused supplier model.
| Leading Market Players |
|---|
| Medical Measurement Systems BV |
| Sierra Instruments, Inc. |
| Medtronic PLC |
| DRG Instruments GmbH |
| Ethicon, Inc. |
| Laborie Medical Technologies Corp. |
| Respiratory Technology Corporation |
| AstraZeneca PLC |
| Diversatek, Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day catheter inventory cycles in German extrusion houses concentrate margin pressure on disposable consumable suppliers while amplifying pricing power for integrated monitor-catheter platforms. Wireless capsule manufacturers exploit this polymer sourcing bottleneck to justify premium positioning against stationary system incumbents locked into legacy hardware replacement economics.
Pricing Analysis
Next-generation wireless capsule systems command 40-60% premiums over stationary impedance-pH monitors, while prior-generation catheter-based platforms face commoditization in outpatient procurement channels. Three-tier pricing structure across premium wireless, standard ambulatory, and economy stationary levels stratifies by FDA 510(k) clearance tier and software analytics bundling. Pricing pressure stems from unbundled procurement patterns in United States ambulatory surgery centers, where group purchasing organizations extract transparency on consumable margins. Academic medical centers in Japan exhibit lowest price sensitivity due to statutory reimbursement coverage, while Indian tier-2 hospitals drive hardest negotiation on portable system hardware.
Supply Chain Analysis
Specialty polymer extrusion capacity in Baden-Württemberg and Basel anchors multichannel impedance catheter production, creating single-source vulnerability for sensor array inputs. Swiss contract houses and Japanese precision manufacturers feed wireless capsule assembly lines with pH-sensitive polymers and miniaturized transmitters. Supply chain risk concentrates in EU MDR notified body bottlenecks extending conformity assessment timelines for legacy device recertification. Distribution runs through hospital procurement committees fragmenting toward ambulatory care center administrators and gastroenterology society purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless capsule penetration in ambulatory settings sits at early-cycle expansion as Category I CPT reimbursement validates capital deployment ahead of stationary system replacement waves.
For Market Incumbents: Consolidate catheter-monitor integration advantages through exclusive supply agreements with German polymer extrusion houses, locking in sensor array sourcing against emerging wireless competitors. Defend installed base revenue by accelerating software licensing unbundling to match ambulatory surgery center procurement preferences, while investing in AI-integrated waveform platforms to preserve interpretation value capture. For New Entrants and Emerging Players: FDA 510(k) predicate device fast-tracks for wireless capsule systems offer 12-18 month clearance advantages over EU MDR pathways, enabling first-mover positioning in United States outpatient networks. Target laryngopharyngeal reflux detection applications where otolaryngology practices lack established vendor relationships, deploying direct-to-specialist distribution through society purchasing cooperatives to bypass hospital procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring-revenue play because disposable catheter and capsule replacement cycles generate predictable cash flows decoupled from capital equipment volatility. Acquisition targets should exhibit established FDA 510(k) portfolios with predicate device strategies and locked polymer supply agreements. Monitor reimbursement coding revisions for ambulatory reflux monitoring as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Device Clearance | Accelerates wireless capsule market entry leveraging established impedance-pH portfolios against MDR-delayed competitors. |
| AI-Integrated Waveform Software Development | Reduces specialist interpretation burden enabling community hospital deployment beyond academic medical centers. |
| Exclusive Polymer Supply Agreements | Locks multichannel catheter sensor sourcing against emerging wireless capsule manufacturers in German extrusion corridor. |
| Direct-to-Specialist Distribution Partnerships | Bypasses fragmented hospital procurement committees through gastroenterology society purchasing cooperatives. |
| Reimbursement Strategy Investment | Secures Category I CPT coding validation for prolonged pH monitoring in United States outpatient settings. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with biomedical engineers, gastroenterology department heads, GPO contracts managers, and regulatory affairs specialists at impedance-pH and wireless capsule manufacturers. Secondary validation drew from CMS Medicare reimbursement data, notified body conformity assessment records, and polymer supply chain trade documentation. Bottom-up procedure volume modeling triangulated against top-down capital equipment replacement cycle analysis.
Variance decomposition across product type, technology generation, application severity, and end-user procurement authority shaped analytical framework development over the projection horizon. CAGRs derived from weighted average of replacement cycle velocity, reimbursement expansion trajectories, and ambulatory migration penetration curves. Forecast inputs incorporated PMDA post-market surveillance obligation timelines and METI domestic production funding allocations for high-resolution manometry systems.
Underlying assumptions cover statutory reimbursement stability in Germany and Japan, FDA 510(k) pathway continuity, and polymer supply concentration persistence, with deviation risk concentrated in EU MDR notified body capacity constraints and capsule retrieval failure rate variability. Practitioners should keep alternative scenarios live as reimbursement coding revisions and wireless capsule safety registries evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Electrical and Electronic Test Equipment Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Duct Integrity Tester (DIT) Market