

Advanced Probe Card and Wafer Probing Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Probe Card and Wafer Probing Test Systems Market Insights
IEC 60749 qualification for semiconductor device reliability is reorganizing supplier tiers in probe card manufacturing, elevating vendors that certify across thermal cycling and mechanical stress protocols. FormFactor leverages vertical integration into MEMS cantilever fabrication to sustain margin control against Asian competitors. Technoprobe anchors its position through dominant share of advanced memory test sockets in South Korea. Micronics Japan specializes in high-pin-count vertical probe cards for logic devices at sub-7nm nodes.
Advanced probe cards and wafer probing test systems comprise electromechanical interfaces that establish temporary electrical connections between test equipment and semiconductor wafers, typically achieving contact resistances below 50 milliohms and pitch resolutions down to 35 micrometers for advanced node validation. These systems enable parametric testing, burn-in screening, and functional verification before die singulation, directly determining yield economics for integrated circuit production. Vertical probe cards capture the dominant share of revenue due to their compatibility with high-density DRAM and NAND flash pad arrays, while MEMS-based technology segments are expanding fastest as probe tip geometries shrink to accommodate heterogeneous integration and chiplet architectures. Cantilever probe cards retain relevance in mature-node analog and power semiconductor testing where cost-per-touch metrics favor simpler mechanical structures.
FDA oversight of semiconductor-based medical devices indirectly shapes probe card specifications for diagnostic chip foundries, while EPA hazardous substance rules govern the plating chemistries used in probe tip metallization. Taiwan's Industrial Development Bureau enforces local content requirements that steer procurement toward domestically certified probe card vendors for strategic semiconductor investments. Stakeholders must monitor how export control classifications from multiple jurisdictions reshape the geographic distribution of probe card manufacturing capacity and customer qualification pathways.
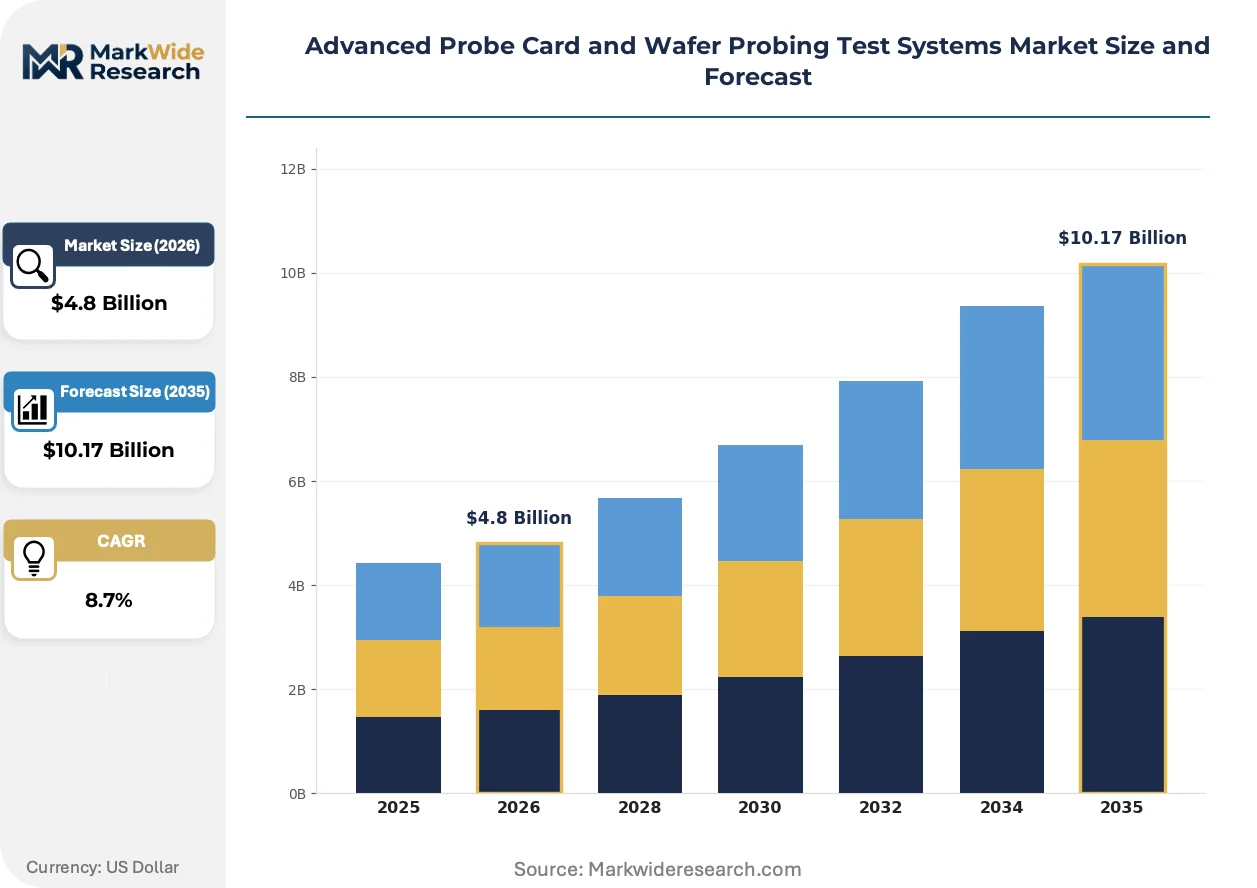
Market Dynamics
Probe card demand is concentrating in Taiwan's Hsinchu Science Park cluster, where TSMC and allied foundries anchor the world's densest consumption base for advanced packaging validation equipment.
Growth Catalysts
- Advanced packaging test intensity:Foundries now require multiple probe touch-downs per wafer for heterogeneous integration and chiplet architectures, expanding equipment utilization rates.
- IEC 60749 thermal cycling protocols:Semiconductor device reliability qualification is reorganizing supplier tiers, elevating vendors that certify across mechanical stress validation standards.
- China's dual carbon targets:Domestic semiconductor self-sufficiency mandates are redirecting capital expenditure toward local probe card procurement for strategic wafer fabrication investments.
Market Restraints
- Platinum-group metal volatility:Probe tip metallization depends on palladium and ruthenium alloys, exposing manufacturers to commodity price swings that compress margin predictability.
- MEMS cantilever supply concentration:Precision microfabrication capacity clusters in South Korea and Japan, creating geographic single-source vulnerability for advanced vertical probe cards.
- EPA hazardous substance rules:Plating chemistry restrictions on hexavalent chromium and cadmium compounds extend qualification timelines for new probe tip formulations.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fab incentives are creating first-mover advantage for probe card vendors establishing local calibration and service infrastructure.
- Photonics-electronics convergence:Silicon photonics wafer testing requires hybrid electrical-optical probe interfaces, opening specialized equipment categories with limited incumbent competition.
- Outcome-based maintenance contracts:Foundries are unbundling probe card refurbishment from capital purchases, enabling recurring revenue streams for technical service providers.
Industry Challenges
- Sub-7nm alignment precision:Probe tip placement tolerances now approach single-digit micrometers, straining metrology capabilities and yield engineering expertise.
- Multi-jurisdiction export control navigation:Dual-use technology classifications from US Commerce, EU dual-use regulations, and Japan's foreign exchange law fragment customer qualification pathways.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Probe Card and Wafer Probing Test Systems Market Trends and Innovations
Wafer probing architectures are splitting between high-volume memory test platforms and precision logic validation systems, with divergent technical requirements reshaping vendor specialization.
MEMS-based probe technology is bifurcating the advanced node segment. Microelectromechanical cantilever arrays achieve pitch resolutions down to 35 micrometers for sub-7nm logic device validation. Leading DRAM and NAND manufacturers are transitioning probe card fleets to MEMS architectures at accelerated replacement cycles. This technology compression is eliminating mechanical probe card viability at nodes below 10nm while extending cantilever relevance in mature analog applications.
REACH substance restrictions are forcing metallurgical reformulation across European probe card supply chains. The ECHA authorization list now covers several legacy probe tip plating chemistries used in high-current power semiconductor testing. German automotive semiconductor foundries are accelerating qualification of alternative palladium-nickel alloys to maintain CE marking compliance for exported test equipment.
Consolidated procurement through foundry-level master service agreements is displacing individual fab purchasing autonomy. TSMC and Samsung Foundry now negotiate enterprise probe card contracts covering multiple wafer fabrication sites. Taiwan's Industrial Development Bureau local content requirements are steering these centralized awards toward domestically certified vendors for strategic investments.
Advanced Probe Card and Wafer Probing Test Systems Market Segmentation
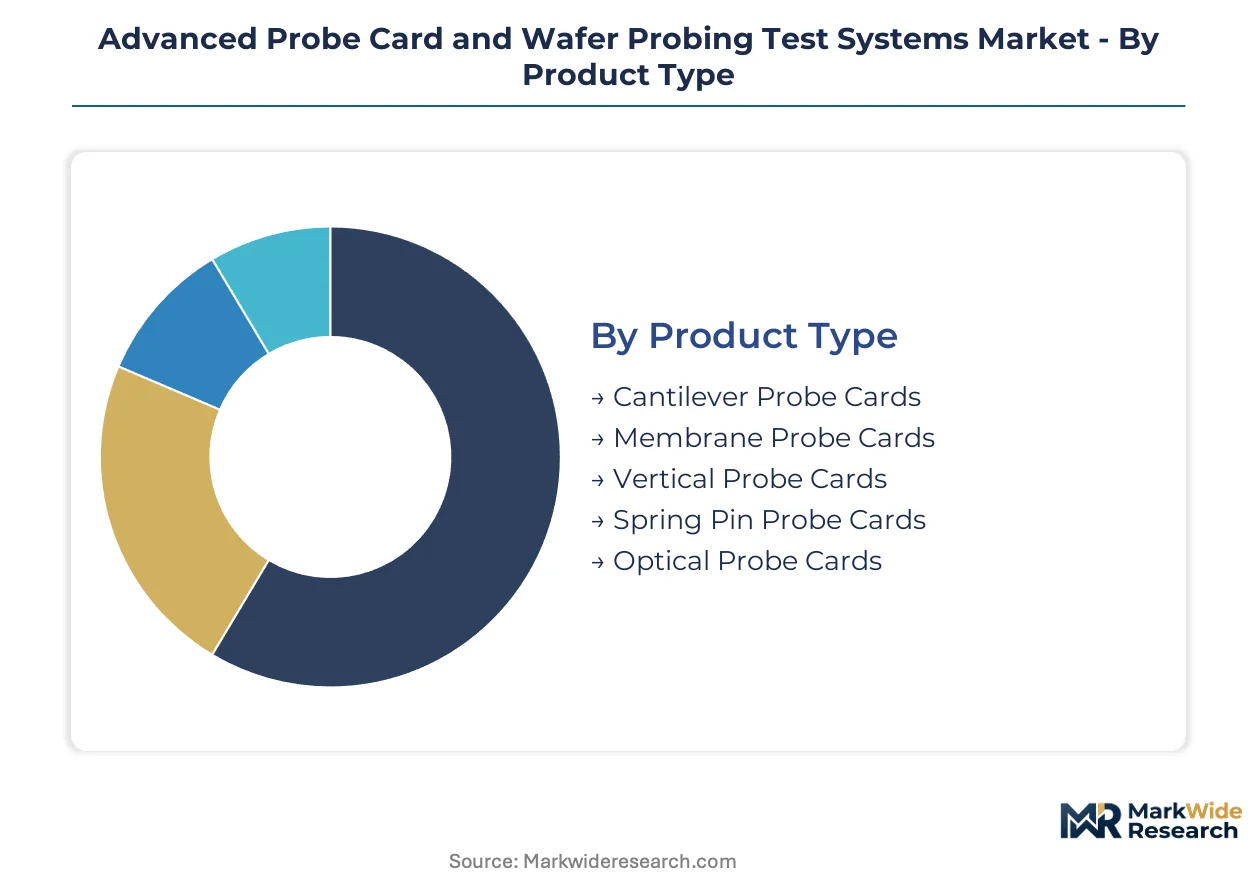
Probe card segmentation reveals how test interface architectures diverge across memory versus logic validation workflows. Technology choices and end-user procurement patterns reshape vendor specialization and channel economics.
Product Type:
Vertical probe cards flow through foundry-level master service agreements, while cantilever architectures distribute through equipment vendor bundling and OSAT spot procurement.
- Vertical Probe Cards:High-density cantilever arrays achieve sub-50 milliohm contact resistance for DRAM and NAND flash pad arrays. TSMC and Samsung Foundry procurement concentrates in Taiwan's Hsinchu cluster and South Korea's Giheung complex, driven by advanced packaging test intensity requirements.
- Cantilever Probe Cards:Simpler mechanical structures optimize cost-per-touch metrics for mature-node analog and power semiconductor validation. Demand localizes in China's Yangtze River Delta fabs under domestic self-sufficiency mandates, constrained by platinum-group metal price volatility in probe tip alloys.
- Membrane Probe Cards:Polyimide-based flexible circuits serve high-frequency RF device testing with reduced signal loss.
- Spring Pin Probe Cards:Coiled contact mechanisms address burn-in screening applications with extended mechanical cycle life.
- Optical Probe Cards:Hybrid electrical-optical interfaces enable silicon photonics wafer validation with limited incumbent competition.
Vertical probe cards dominate installed base. Optical probe cards are where expansion concentrates.
Technology:
Cost tier stratification separates MEMS architectures at premium pricing from micromechanical alternatives serving economy segments.
- MEMS:Microelectromechanical cantilever arrays achieve 35-micrometer pitch resolution for sub-7nm logic validation. FormFactor's captive fabrication and Technoprobe's South Korean manufacturing anchor supply, with IEC 60749 thermal cycling certification now table stakes for foundry qualification.
- Micromechanical:Conventional precision machining supports mature-node applications at lower capital intensity. China's domestic probe card procurement redirects toward locally certified micromechanical vendors under dual carbon-aligned capex mandates.
- Optical:Fiber-aligned probe interfaces address photonics-electronics convergence testing requirements.
- Thermal:Temperature-controlled contact systems enable burn-in screening across extended temperature ranges.
- Electrical:Impedance-matched signal paths support high-speed digital protocol validation.
- Magnetic:Inductive coupling architectures serve specialized non-contact test scenarios.
Micromechanical technologies retain volume leadership. MEMS architectures command the steepest expansion trajectory.
Application:
Customer type determines procurement rhythm: foundries negotiate enterprise contracts while R&D testing flows through research institute grant funding.
- Semiconductor Manufacturing:Parametric and functional verification at wafer level before die singulation. Taiwan's Industrial Development Bureau local content requirements steer procurement toward domestically certified vendors for strategic fab investments.
- Chip Packaging:Heterogeneous integration and chiplet architectures demand multiple probe touch-downs per wafer. Advanced packaging validation concentrates in Taiwan and South Korea, with EPA plating chemistry rules extending qualification timelines.
- Failure Analysis:Diagnostic probing of yield excursions and defect localization.
- Quality Assurance:Statistical process control sampling across production lots.
- R&D Testing:Process development and new device architecture validation.
Semiconductor manufacturing commands the largest revenue pool. Chip packaging is climbing the fastest.
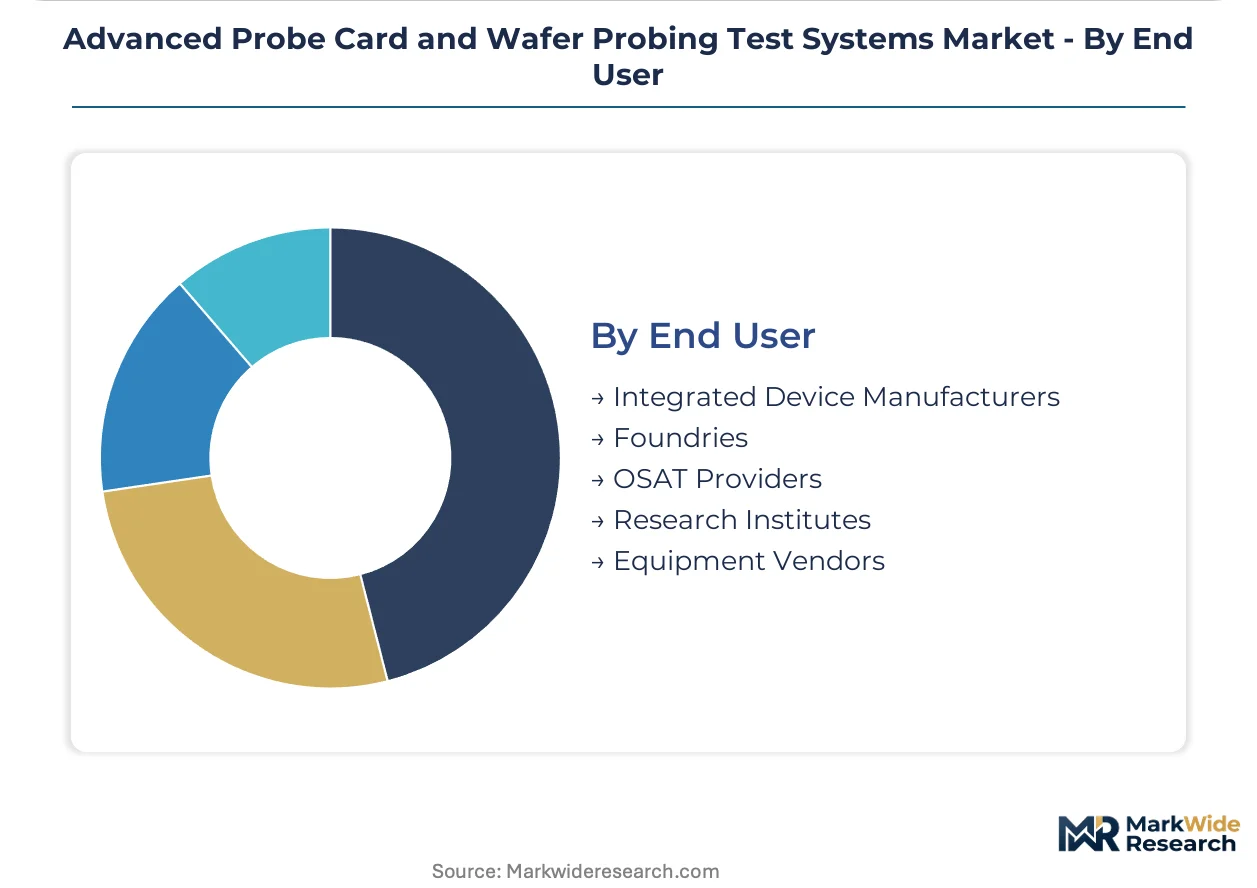
End User:
Margin profiles diverge sharply: foundries extract volume discounts while research institutes accept premium pricing for technical flexibility.
- Foundries:TSMC and Samsung Foundry consolidated procurement displaces individual fab autonomy. Enterprise probe card contracts now cover multiple wafer fabrication sites, with India's PLI scheme creating first-mover opportunities for calibration infrastructure.
- OSAT Providers:Outsourced assembly and test houses optimize equipment utilization rates across customer portfolios. Spot procurement patterns dominate, with REACH substance restrictions forcing metallurgical reformulation in European supply chains.
- Integrated Device Manufacturers:Captive fab operations with integrated test capabilities.
- Research Institutes:Academic and government laboratory procurement for process development.
- Equipment Vendors:Test system OEMs bundling probe cards with capital equipment sales.
Foundries dominate installed base. OSAT providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Probe card procurement concentrates where foundry capital expenditure clusters, with Taiwan, South Korea, China, Japan, and the United States hosting the densest buyer bases for advanced packaging validation equipment.
Taiwan
TSMC and allied foundries drive the world's highest probe card consumption intensity for heterogeneous integration testing. The Industrial Development Bureau enforces local content requirements that steer strategic semiconductor investments toward domestically certified vendors. Hsinchu Science Park anchors this demand concentration, with advanced packaging test protocols requiring multiple touch-downs per wafer.
South Korea
Samsung Foundry and SK Hynix dominate memory probe card procurement for DRAM and NAND flash validation. MFDS oversight of semiconductor manufacturing equipment indirectly shapes qualification pathways for diagnostic systems. The Giheung complex represents the primary geographic concentration, where MEMS cantilever supply chains cluster alongside foundry operations.
China
Domestic self-sufficiency mandates under dual carbon goals redirect capital expenditure toward locally certified probe card vendors for strategic wafer fabrication. MIIT standards govern equipment qualification for imported test systems. Yangtze River Delta fabs concentrate procurement activity, though platinum-group metal volatility constrains margin predictability for domestic manufacturers.
Japan
Specialized logic device testing at sub-7nm nodes sustains demand for high-pin-count vertical probe architectures. METI industrial policy supports precision microfabrication capacity for advanced cantilever arrays. Tokyo-Osaka corridor facilities anchor production gravity for probe tip metallization chemistries subject to REACH substance restrictions.
United States
Silicon photonics wafer testing creates hybrid electrical-optical probe interface demand with limited incumbent competition. EPA hazardous substance rules govern plating chemistries used in probe tip metallization, extending qualification timelines. Arizona and Texas fab investments concentrate emerging procurement, with FDA oversight of semiconductor-based medical devices indirectly shaping specifications for diagnostic chip foundries.
Advanced Probe Card and Wafer Probing Test Systems Market Competitive Landscape
Player mix skews toward precision microfabrication specialists with captive MEMS capacity and diversified test equipment conglomerates with probe card divisions. Market structure exhibits tiered concentration, with three to five vendors commanding advanced node qualifications while regional specialists serve mature-node analog segments. Strategic archetypes include vertically integrated cantilever fabricators, foundry-captive service providers, and optical-electrical hybrid interface developers. Competitive moves center on IEC 60749 thermal cycling certification acquisition and geographic calibration infrastructure expansion.
Among precision microfabrication specialists, FormFactor, Technoprobe, and Micronics Japan occupy positions representing distinct strategic archetypes. FormFactor exemplifies the vertically integrated model with in-house MEMS cantilever production. Technoprobe anchors the foundry-captive service tier through dominant positioning in advanced memory test sockets. Micronics Japan represents specialization in high-pin-count architectures for logic device validation. These three entities collectively illustrate how vendor positioning diverges across memory versus logic testing workflows, with each archetype commanding distinct margin profiles and customer qualification pathways.
| Leading Market Players |
|---|
| FormFactor |
| Technoprobe |
| Micronics Japan |
| Japan Electronic Materials |
| MPI Corporation |
| FEINMETALL |
| SV Probe |
| Advantest |
| Korea Instrument |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week lead times for MEMS cantilever substrates compress pricing power at the high-performance tier while amplifying margin capture for captive fabricators. This inventory-to-delivery gap concentrates procurement leverage among foundries with enterprise master service agreements, leaving spot buyers exposed to palladium-alloy cost pass-throughs.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange palladium and ruthenium benchmarks dominate high-volume DRAM probe card procurement. Three-tier pricing structure across IEC 60749-certified premium, standard qualification, and economy micromechanical tiers separates TSMC-level enterprise discounts from OSAT spot premiums. Pricing pressure stems from platinum-group metal volatility compressing margin predictability for non-integrated vendors. OSAT providers exhibit highest price sensitivity due to equipment utilization optimization mandates, while foundries accept premium positioning for thermal cycling certification guarantees.
Supply Chain Analysis
Tsugaru Strait maritime transit underwrites just-in-time delivery of precision-machined probe substrates from northern Japan to Hsinchu packaging facilities. Supply concentration clusters in Taiwan, South Korea, and Japan for MEMS cantilever fabrication, micromechanical substrate machining, and probe tip metallization chemistries respectively. Raw material dependencies center on palladium-nickel alloys, polyimide flexible circuits, and photoresist formulations for sub-7nm patterning. Single-source vulnerability concentrates in South Korean MEMS foundry capacity. Distribution runs through foundry-level master service agreements with embedded refurbishment clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Probe card procurement is consolidating toward platform-ecosystem models where IEC 60749 certification interoperability determines vendor switching costs. This shift rewards suppliers embedding thermal cycling validation into recurring service architectures rather than transactional hardware sales.
For Market Incumbents: Compound defensive positioning through backward integration into MEMS cantilever captive supply and IEC 60749 certification pre-qualification at emerging India fab sites. FormFactor's vertical model demonstrates margin protection against Asian competitors, while Technoprobe's memory socket dominance illustrates channel lock-in value. Priority lever rests on calibration infrastructure density in Taiwan's Hsinchu corridor.
For New Entrants and Emerging Players: IEC 60749 fast-track certification partnerships with Taiwan's Industrial Development Bureau create qualification shortcuts for strategic fab investments. India's PLI scheme for semiconductors represents the most penetrable geography for first-mover calibration and service infrastructure. Photonics-electrical hybrid probe interfaces for silicon photonics testing offer limited incumbent competition as go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because foundries are unbundling probe card refurbishment from capital purchases. Acquisition targets should emphasize captive MEMS fabrication capacity and established IEC thermal cycling certification. Signal to watch: TSMC and Samsung Foundry master service agreement renewal cycles indicating vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60749 Certification Acquisition | Thermal cycling protocol compliance elevates vendors into TSMC and Samsung enterprise contract tiers. |
| MEMS Cantilever Captive Fabrication | In-house microelectromechanical production insulates margin control from South Korean supply concentration. |
| India Calibration Infrastructure Buildout | PLI scheme incentives create first-mover advantage for probe card service localization. |
| Photonics-Electrical Hybrid Interface Development | Silicon photonics wafer testing opens specialized equipment categories with limited incumbent competition. |
| Outcome-Based Maintenance Contract Structuring | Refurbishment unbundling from capital purchases enables recurring revenue streams for technical service providers. |
Research Methodology
A spread of perspectives from probe card engineering directors, foundry procurement leads, OSAT equipment managers, and semiconductor test system integrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings, Taiwan Stock Exchange disclosures, SEMI equipment market data, and customs trade records. Bottom-up probe card shipment aggregation and top-down foundry capex allocation triangulation anchored volume estimates.
Segmentation dimensions modeled include product architecture, MEMS versus micromechanical technology tier, memory versus logic application split, and foundry versus OSAT end-user channel. CAGRs derived from equipment intensity ratios per wafer start, advanced packaging test touchdown multipliers, and regional fab investment pipelines across the projection horizon. Forecast inputs incorporated platinum-group metal price trajectory assumptions and IEC certification adoption curves.
Underlying assumptions cover sustained advanced packaging test intensity, palladium alloy supply continuity, and dual-use export control stability, with deviation risk concentrated in MEMS cantilever supply disruption and REACH substance restriction acceleration. Practitioners should keep alternative scenarios live as China's domestic procurement mandates and EPA plating chemistry rule evolution reshape vendor qualification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.