
 United States Plant Protein Market | 2026-2036
United States Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Plant Protein Market Analytics
Supermarket shelf allocation for plant-based proteins is fragmenting as legacy grocers and specialty retailers compete for category space. Archer Daniels Midland Company leverages its Midwest grain origination network to anchor domestic soy protein supply. Kerry Group differentiates through flavor-mask technologies that broaden application scope for pea and hemp isolates.
Plant protein denotes extracted, concentrated, or isolated protein fractions derived from legumes, oilseeds, or cereals, typically processed through wet or dry fractionation to achieve protein contents ranging from 50% to 90% by weight. These ingredients function as functional binders, emulsifiers, and nutritional fortifiers in formulated foods. Pea protein leads volume due to its neutral flavor profile and absence of major allergens, while hemp protein occupies a premium niche driven by omega-3 content and clean-label positioning. Snacks represent the fastest-expanding application as extrusion technologies improve textural mimicry of conventional products.
The USDA enforces standards of identity that constrain how plant-based products label themselves relative to animal-derived counterparts. FDA allergen labeling requirements and GRAS self-affirmation pathways shape ingredient approval timelines and reformulation costs. State-level clean-label mandates in California and New York add compliance layers that favor suppliers with established regulatory affairs capabilities. Stakeholders must track evolving positions from the FTC on environmental marketing claims to avoid greenwashing exposure.
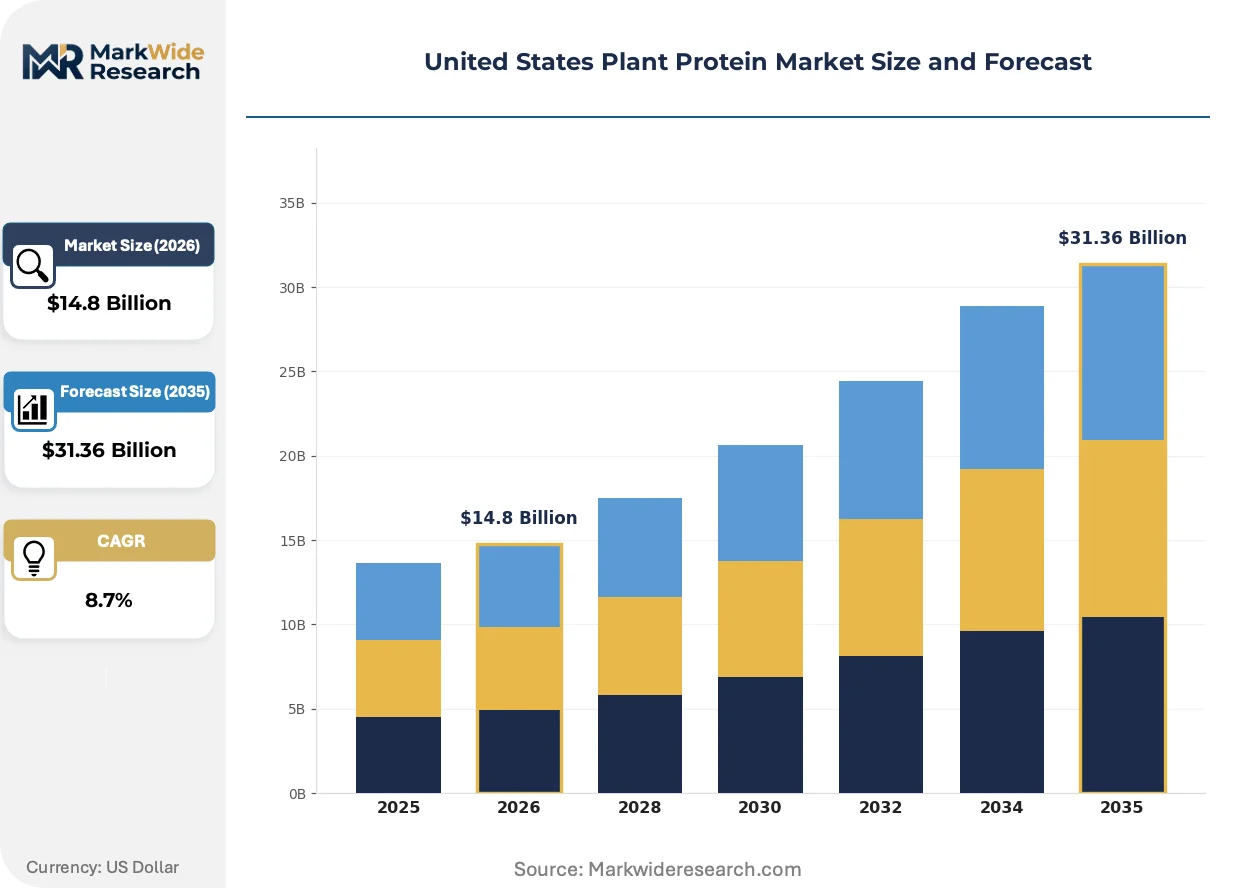
Market Dynamics
USDA standards of identity enforcement is compressing labeling flexibility for plant-based meat analogs while simultaneously accelerating investment in clean-label extraction technologies that bypass chemical processing claims.
Growth Catalysts
- FDA GRAS Self-Affirmation:Streamlined ingredient approval pathways reduce time-to-market for novel protein isolates, particularly mung bean and fava concentrates entering snack formulations.
- Midwest Processing Belt Concentration:Proximity to corn and soybean origination infrastructure lowers inbound logistics costs for wet-fractionation facilities operating at scale.
- Extrusion Technology Maturation:High-moisture extrusion systems now achieve fibrous textures comparable to whole-muscle poultry, unlocking foodservice contract opportunities.
Market Restraints
- Input Cost Volatility:Yellow pea protein concentrate faces margin pressure from drought-induced crop yield variability in North Dakota and Montana growing regions.
- Supply Concentration Risk:Over half of domestic hemp protein processing capacity sits within Colorado's Front Range corridor, creating single-point-of-failure exposure.
- Technical Limitation:Current enzymatic debittering protocols for canola protein retain residual phenolic compounds that limit application in neutral-flavor beverages.
Strategic Opportunities
- School Nutrition Programs:USDA National School Lunch Program protein quota revisions create institutional procurement windows for blended plant-animal products.
- Cellular Agriculture Convergence:Hybrid formulations combining precision-fermented heme with pea protein isolates offer pathway to reduced-cost cultivated meat precursors.
- Direct-to-Consumer Subscription:Replenishment models for powdered protein bypass conventional retail slotting fee structures and capture lifetime value data.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Shortage of professionals fluent in both FDA food additive petitions and USDA Process Verified Program protocols delays market entry timelines.
- Capex Intensity:Commercial-scale membrane filtration systems for protein isolation require eight-figure capital commitments with five-year depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Plant Protein Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein Application: Dairy Alternatives, Meat Alternatives, Protein Supplements, Snacks End User: Households, Fitness Enthusiasts, Food Manufacturers, Restaurants Distribution Channel: Supermarkets, Online Retailers, Health Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, Bunge Limited, International Flavors & Fragrances, Kerry Group, Glanbia, Ingredion, Axiom Foods, SunOpta, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Plant Protein Market Evolving Landscape
Precision fermentation and enzymatic modification are converging to dismantle traditional boundaries between commodity protein ingredients and high-value functional additives.
High-pressure processing is collapsing the functional gap between raw pulse flours and purified isolates by enabling cold denaturation control that preserves solubility without chemical adjuncts. Sports nutrition manufacturers are adopting these systems at pilot scale ahead of broader foodservice rollout. The technology is collapsing price premiums previously commanded by spray-dried isolates in beverage applications.
The FDA's updated guidance on labeling of plant-based alternatives to animal-derived foods tightens comparative nutritional claim requirements for protein quality scores. This regulatory friction is forcing reformulation toward complete amino acid profiles through strategic blending. Plant-based dairy alternatives face the steepest compliance burden as PDCAAS disclosure becomes mandatory.
Foodservice operators are consolidating supplier relationships around vertically integrated processors capable of certifying regenerative agriculture sourcing through the USDA's Partnerships for Climate-Smart Commodities program. This procurement concentration favors suppliers with captive farm networks over merchant traders. The shift is most visible in California's institutional feeding contracts where carbon accounting now influences award criteria.
United States Plant Protein Market Segmentation
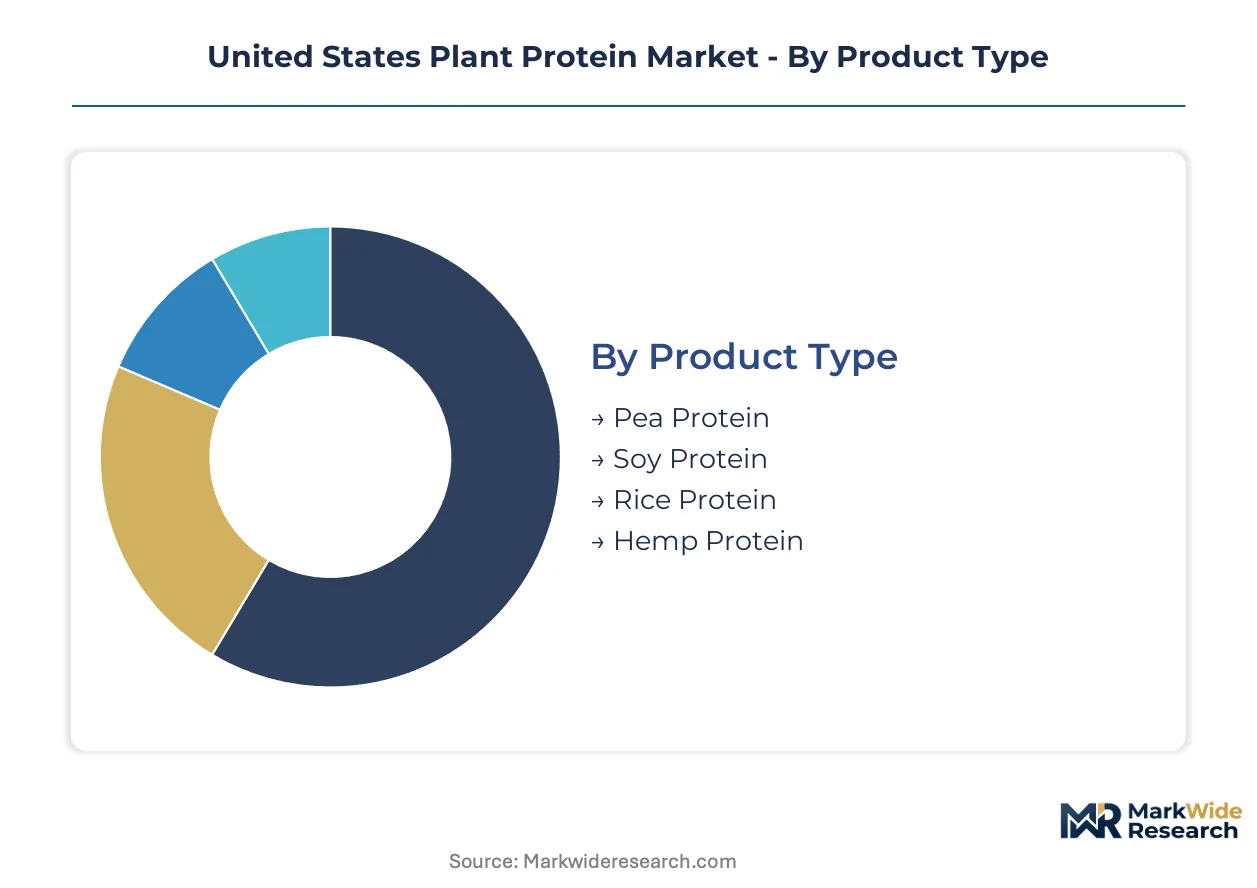
Plant protein segmentation in the United States reflects divergent technical requirements across end-use applications. Manufacturers configure extraction protocols and functional specifications differently for beverage fortification versus texturized meat analogs.
Product Type:
Cost tiers separate commodity isolates from premium concentrates with specialized functional profiles.
- Pea Protein:Yellow and green split pea isolates achieve protein concentrations of 80-90% through wet fractionation and membrane filtration. Demand concentrates in California's dairy alternative manufacturing corridor, where neutral flavor compatibility with oat milk bases drives procurement decisions. FDA GRAS status for major suppliers accelerates formulation timelines versus novel protein entrants.
- Soy Protein:Defatted soy flour and isolated soy protein retain dominant volume through Midwest processing infrastructure anchored near origination networks. Illinois and Iowa wet-milling facilities supply textured concentrates to meat alternative producers facing USDA labeling compliance costs.
- Rice Protein:Brown rice concentrates offer hypoallergenic positioning for pediatric nutrition and clean-label applications. Processing in Arkansas and Louisiana leverages existing cereal grain infrastructure.
- Hemp Protein:Cold-pressed hemp seed cake yields protein at 50% concentration with retained omega fatty acids. Colorado's Front Range hosts concentrated processing capacity serving premium sports nutrition brands.
The dominant share belongs to soy protein, while pea protein is closing the gap fastest.
Application:
Volume concentration varies sharply between mature beverage categories and emerging extruded formats.
- Dairy Alternatives:Protein fortification of almond, oat, and coconut milk alternatives requires high solubility and heat stability. Major processors in California's Central Valley integrate directly with co-packing networks serving national retail distribution.
- Meat Alternatives:High-moisture extrusion of pea and soy isolates achieves fibrous textures for burger and sausage applications. Midwest food manufacturers dominate contract manufacturing for foodservice and retail private label.
- Protein Supplements:Powdered concentrates and ready-to-drink formulations serve fitness enthusiasts through direct-to-consumer subscription models and specialty retail. Flavor-mask technologies determine supplier selection.
- Snacks:Extruded puffs, chips, and bars incorporate protein concentrates for nutritional positioning. Texas and Georgia processing facilities lead scale-up of texturized inclusions for CPG brands.
Dairy alternatives command the largest application share, with snacks expanding most quickly.
End User:
Customer type dictates formulation complexity and regulatory documentation requirements.
- Households:Retail purchasers drive demand for recognizable ingredient declarations and single-serve convenience formats. E-commerce replenishment models capture recurring revenue with reduced slotting fee burdens.
- Fitness Enthusiasts:Performance-oriented consumers prioritize leucine content and amino acid completeness in post-workout formulations. Sports nutrition brands source isolates with third-party certification for banned substance testing.
- Food Manufacturers:Industrial buyers require consistent functional specifications for emulsification, water binding, and gelation across batch scales. Technical service capabilities influence long-term supply agreements.
- Restaurants:Foodservice operators seek pre-hydrated or pre-seasoned protein systems to reduce kitchen labor and variability. National chain procurement favors suppliers with USDA Process Verified Program credentials.
Food manufacturers represent the largest end user segment, while restaurants are gaining share fastest.
Distribution Channel:
Channel economics determine margin retention and brand control for protein suppliers.
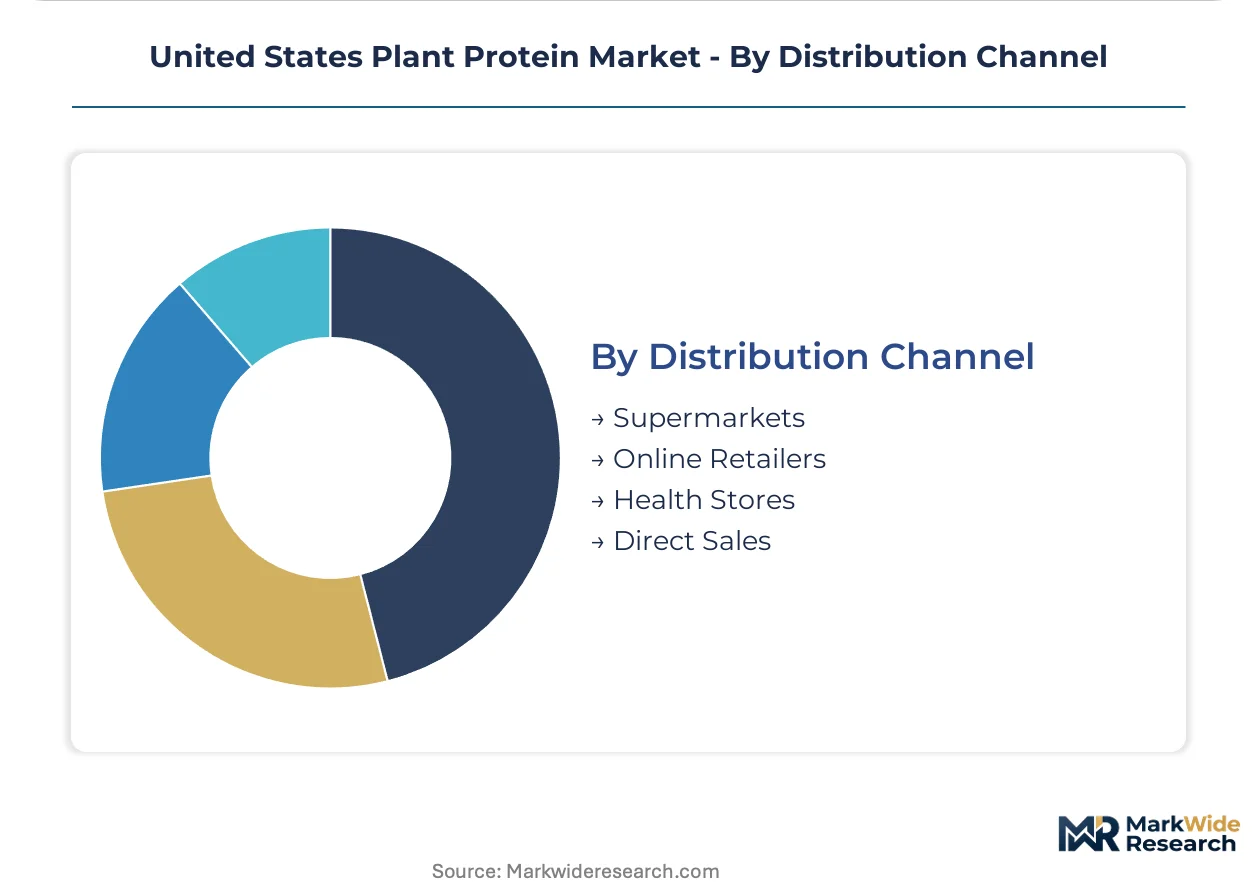
- Supermarkets:Conventional and natural grocers allocate expanding shelf space to plant-based proteins as category management shifts from specialty to mainstream positioning. Slotting fees and promotional allowances compress net margins for emerging brands.
- Online Retailers:Amazon and specialized health platforms enable direct consumer relationships with subscription pricing and review-driven discovery. Fulfillment infrastructure requirements favor suppliers with established case-pack configurations.
- Health Stores:Specialty retailers emphasize organic certification, non-GMO verification, and novel protein sources for educated consumers. Staff training and sampling programs drive trial conversion.
- Direct Sales:Manufacturer-owned channels bypass retail markups and capture first-party consumption data. Capital requirements for customer acquisition limit this model to well-capitalized entrants.
Supermarkets retain the dominant channel position, while online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Partnerships for Climate-Smart Commodities program funding is redirecting processing capacity toward carbon-accounted supply chains. State-level clean-label mandates in California and New York compress formulation timelines for national brands. Sub-regional specialization concentrates wet-fractionation infrastructure near origination networks while extrusion technology clusters serve foodservice contract manufacturing.
California
Dairy alternative manufacturing in the Central Valley drives pea protein procurement for oat milk fortification. California's state-level clean-label mandates exceed federal baselines, forcing reformulation toward chemical-free extraction protocols. Bay Area precision fermentation startups are converging with legacy processors in Los Angeles County to develop hybrid protein systems.
Midwest Processing Belt
Illinois and Iowa wet-milling facilities anchor domestic soy protein supply through proximity to corn and soybean origination networks. USDA standards of identity enforcement accelerates investment in clean-label extraction technologies that bypass chemical processing claims. Chicago-based food manufacturers dominate high-moisture extrusion contract manufacturing for national retail private label.
Colorado Front Range
Premium sports nutrition brands source hemp protein from concentrated cold-pressing capacity along the Front Range corridor. State cannabis regulatory frameworks create specialized inspection protocols for hemp-derived ingredients. Denver-area processors are expanding omega-3 retention capabilities to serve clean-label positioning demands.
Texas and Georgia
Extruded snack processing facilities in Texas and Georgia lead scale-up of texturized protein inclusions for CPG brands. FDA GRAS self-affirmation pathways for novel protein isolates reduce time-to-market for regional formulators. Atlanta and Dallas logistics hubs enable just-in-time delivery to Southeast and Southwest retail distribution centers.
Pacific Northwest
Arkansas and Louisiana rice protein processing leverages existing cereal grain infrastructure for hypoallergenic ingredient production. Regional procurement for pediatric nutrition applications prioritizes brown rice concentrates with third-party allergen certification. Portland and Seattle specialty retailers drive demand for organic-certified protein powders through direct-to-consumer subscription models.
United States Plant Protein Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated grain processors with captive origination networks and specialized extraction technology providers. The vendor base stratifies into three archetypes: commodity-scale agricultural conglomerates with wet-fractionation assets, mid-cap ingredient specialists with flavor-mask and functional modification capabilities, and precision fermentation startups developing novel protein expressions. Dominant competitive moves include backward integration into regenerative agriculture sourcing and strategic partnerships with foodservice operators seeking USDA Process Verified Program credentials.
Within the commodity-scale tier, Archer Daniels Midland Company and Cargill exemplify agricultural conglomerates with Midwest grain origination dominance. Kerry Group occupies a position among mid-cap specialists with differentiated flavor technologies. These three entities represent the spectrum from upstream supply control to downstream formulation partnership, illustrating how competitive positioning in this market depends on proximity to origination infrastructure versus technical service capabilities in application development.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Bunge Limited |
| International Flavors & Fragrances |
| Kerry Group |
| Glanbia |
| Ingredion |
| Axiom Foods |
| SunOpta |
| Others |
Value Network & Pricing Analysis
Overcapacity in Colorado's hemp protein processing corridor is compressing spot pricing for cold-pressed concentrates while simultaneously forcing suppliers toward long-term offtake contracts with sports nutrition brands to defend margin structures.
Pricing Analysis
Volume-discount tiering structures separate spot market transactions from multi-year supply agreements with national food manufacturers. Pricing stratifies across premium, standard, and economy tiers based on protein concentration purity and USDA Process Verified Program certification status. Cost compression in standard-grade pea protein concentrates is intensifying because drought-induced crop yield variability in North Dakota and Montana growing regions has tightened feedstock availability. National retail chains exhibit the highest price sensitivity due to slotting fee structures and promotional allowance demands, while direct-to-consumer subscription brands absorb modest premiums for organic-certified isolates.
Supply Chain Analysis
Upstream feedstock origination draws from Illinois and Iowa soybean networks, North Dakota and Montana yellow pea growing regions, and Colorado hemp cultivation corridors. The supply chain rests on defatted soy flour, split pea isolates, and cold-pressed hemp seed cake as primary inputs. Single-source vulnerability concentrates in Colorado's Front Range hemp processing corridor where over half of domestic capacity sits within a narrow geographic band. Distribution runs through Midwest wet-milling facilities to Chicago-based extrusion contract manufacturers, then onward to California dairy alternative producers and Texas snack processing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA GRAS self-affirmation pathways and USDA standards of identity compliance create multi-year barriers that favor incumbents with established regulatory affairs capabilities.
For Market Incumbents: Insulate margin structures through backward integration into regenerative agriculture sourcing certified under USDA's Partnerships for Climate-Smart Commodities program. Expand wet-fractionation capacity in Iowa and Illinois to capture origination cost advantages against emerging precision fermentation substitutes. Prioritize technical service capabilities that lock food manufacturers into specification-dependent supply agreements.
For New Entrants and Emerging Players: Geographic underpenetration in the Pacific Northwest pediatric nutrition segment offers a viable beachhead for hypoallergenic rice protein concentrates with third-party allergen certification. Target direct-to-consumer subscription models for powdered protein to bypass supermarket slotting fee structures and capture lifetime value data. Lead with clean-label extraction protocols that satisfy California's state-level mandates exceeding federal baselines.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap ingredient specialists with differentiated flavor-mask technologies and established FDA regulatory affairs teams. Long-term viability hinges on convergence capabilities between plant protein isolates and precision-fermented functional additives. Monitor USDA National School Lunch Program protein quota revisions as an inflection signal for institutional procurement volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Buildout | FDA GRAS self-affirmation expertise accelerates novel protein isolate approval timelines versus petition pathways. |
| Backward Integration into Regenerative Sourcing | USDA Partnerships for Climate-Smart Commodities certification unlocks foodservice contract preference in California institutional feeding. |
| High-Moisture Extrusion Scale-Up | Chicago-based contract manufacturers with fibrous texture capabilities capture national retail private label volumes. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models bypass supermarket slotting fees and capture first-party consumption data for formulation feedback. |
| Hybrid Protein System Development | Precision fermentation convergence with pea isolates offers reduced-cost pathways to cultivated meat precursor applications. |
Research Methodology
Operator-level perspectives from plant protein extraction facility managers, food manufacturer procurement directors, flavor technology R&D leads, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA GRAS notification filings, USDA Process Verified Program audit records, SEC 10-K disclosures by agricultural conglomerates, and customs trade data on yellow pea and soybean imports. Bottom-up volume modeling triangulated against top-down addressable market sizing across product type, application, and end-user dimensions.
Scenario-bracketing framed sensitivity analysis around input cost volatility, regulatory enforcement intensity, and precision fermentation substitution rates across the projection horizon. Segmentation modeling captured protein source, functional specification tier, and regional processing cluster variations. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs included drought probability indices for North Dakota and Montana growing regions and FDA guidance timeline assumptions for plant-based dairy alternative labeling.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or cellular agriculture hybrid formulators would shift outcomes beyond modeled ranges. Cross-checking against USDA National Agricultural Statistics Service crop yield projections and FDA GRAS notification approval velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Global Textured Vegetable Protein Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Plant Based Breads Market