
 United Kingdom Plant Protein Market | 2026-2036
United Kingdom Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Plant Protein Market Analytics
Modular portion packs and single-serve sachets are expanding across retail and foodservice channels, unbundling traditional bulk formats into flexible, trial-friendly configurations. Kerry Group PLC leverages its taste and nutrition portfolio to anchor clean-label protein solutions for British manufacturers. Cargill Incorporated competes through its supply chain control over North American and European pea protein origination. Tate & Lyle differentiates with texturizing systems that mask off-notes in high-concentration plant isolates.
United Kingdom plant protein encompasses extracted, concentrated, or isolated protein fractions derived from legumes, oilseeds, and cereals, typically achieving 80-90% protein content on a dry-weight basis through wet or dry fractionation, then applied as functional ingredients in food matrices requiring emulsification, gelation, or foaming capacity. Protein Powder occupies the deepest margin pool due to sports nutrition brand premiums and subscription-channel stickiness, while Meat Alternatives sustains the fastest volume trajectory as British retailers expand chilled and frozen own-label ranges. Dairy Alternatives commands stable penetration through oat-soy blends in barista formulations, though hemp-sourced variants remain niche.
The Food Standards Agency governs novel food pre-market authorization, compelling ingredient developers to submit comprehensive toxicology dossiers before commercialization, while the Department for Environment, Food & Rural Affairs shapes sustainable sourcing claims through its developing environmental labeling framework. British Retail Consortium standards additionally constrain supplier hygiene and allergen management protocols. Stakeholders must monitor how evolving precision-fermentation regulations and potential gene-editing policy relaxations could redraw competitive boundaries between extractive and biomanufactured protein pathways.
Market Dynamics
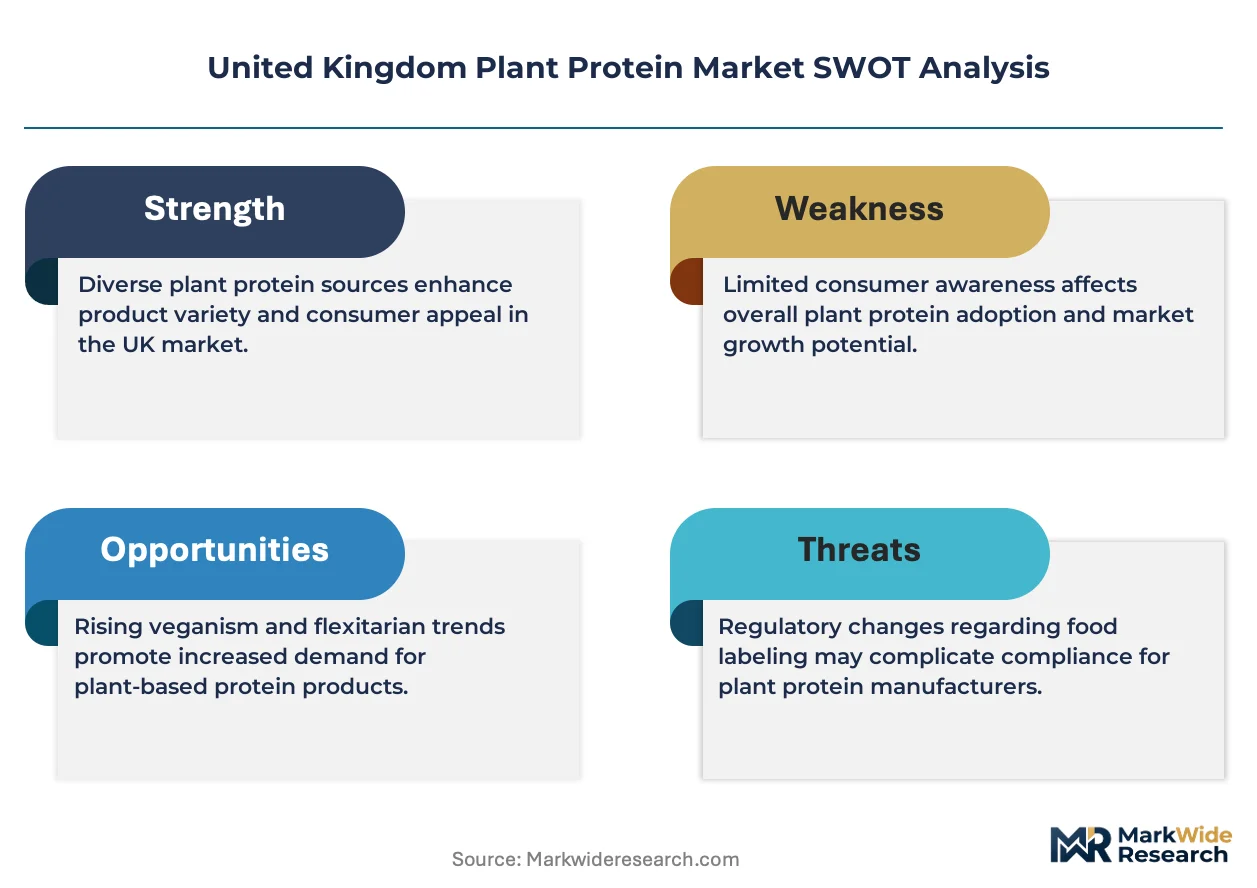
The Food Standards Agency's novel food authorization pathway is compressing time-to-market for emerging protein sources while simultaneously raising compliance barriers for smaller ingredient developers. This regulatory acceleration is converging with food-tech clustering in London and Manchester to reshape competitive access.
Growth Catalysts
- Flexitarian population density:Urban centers in the Scottish Central Belt and Greater Manchester are generating concentrated demand for hybrid meat-plant formulations. Retailers are responding with expanded chilled own-label ranges.
- Clean-label ingredient innovation:Wet fractionation advances are enabling 85%+ protein isolates with reduced off-flavor carryover. Bakery and ready-meal manufacturers are reformulating around these functional concentrates.
- DEFRA environmental labeling framework:The developing sustainability claims infrastructure is creating first-mover advantage for British suppliers with verified carbon accounting. Premium positioning is consolidating around demonstrable sourcing transparency.
Market Restraints
- Pea protein origination concentration:Supply control over North American and European yellow pea crops sits with a limited processor tier. British formulators face margin compression during origination shortages.
- Novel food dossier costs:The FSA's toxicology submission requirements demand six-figure investment per new protein source. Development-stage companies without pharma-grade testing partnerships are excluded from commercialization.
- Texturizing system dependency:High-concentration isolates require specialized masking and mouthfeel engineering. Formulators lacking in-house hydrocolloid expertise remain tethered to ingredient supplier portfolios.
Strategic Opportunities
- Precision fermentation regulatory evolution:Potential gene-editing policy relaxations under review by DEFRA could redraw boundaries between extractive and biomanufactured proteins. Early regulatory engagement is securing pathway clarity.
- Single-serve sachet channel expansion:Modular portion formats are penetrating foodservice trial programs and subscription-box channels. Unbundling from bulk is capturing hesitant first-time buyers.
- Scottish Central Belt production clustering:Underdeveloped processing capacity in Edinburgh-Glasgow corridor presents greenfield site potential. Proximity to malting and brewing byproduct streams offers feedstock integration.
Industry Challenges
- Allergen management protocol complexity:British Retail Consortium standards mandate segregated handling for legume-derived proteins. Multi-product facilities face capex-intensive line isolation requirements.
- Sensory scientist scarcity:Formulation expertise bridging protein chemistry and consumer taste preference is concentrated among a handful of consultancy networks. In-house capability building requires 18-24 month recruitment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Plant Protein Market |
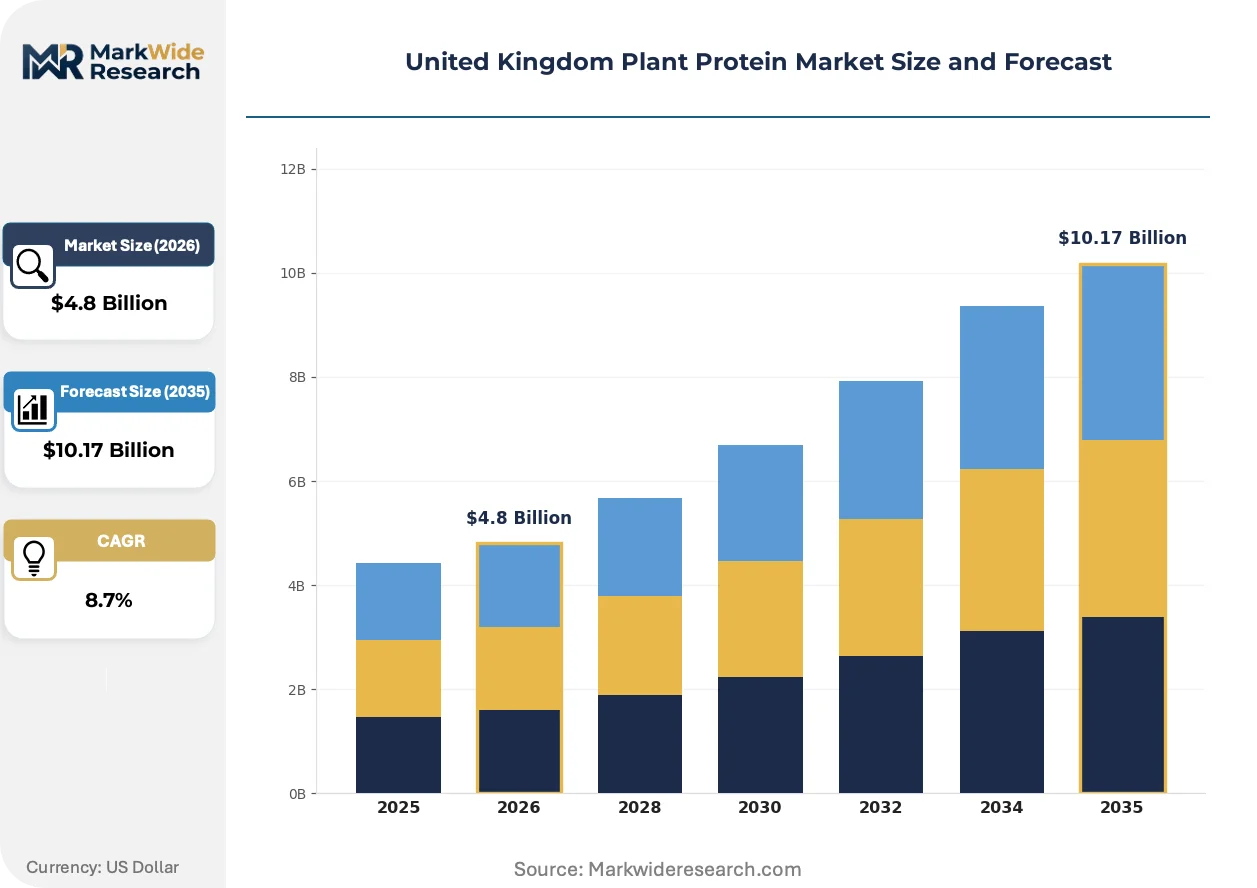
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powder, Meat Alternatives, Dairy Alternatives, Snacks Source: Pea, Soy, Rice, Hemp End User: Fitness Enthusiasts, Vegans, Vegetarians, General Consumers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Kerry Group PLC, Roquette Frères, Glanbia PLC, Tate & Lyle, DSM-Firmenich, International Flavors & Fragrances Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Plant Protein Market Evolving Landscape
Protein extraction and application technologies are advancing through convergence with adjacent food science disciplines, while regulatory frameworks and procurement behaviors are simultaneously restructuring market access patterns.
High-moisture extrusion is converging with shear-cell processing to produce whole-muscle analogues without traditional cooling die limitations. Ready-meal manufacturers in the UK are piloting these systems at commercial scale. The technology is compressing equipment footprint requirements and enabling retrofit of existing pasta extrusion lines.
The FSA's evolving guidance on precision-fermentation-derived proteins is creating compliance clarity gaps that advantage dossier-ready incumbents. Ingredient developers with pre-submitted toxicology packages are securing provisional market access. Dairy alternative formulators are most affected, accelerating partnerships with biomass fermentation specialists.
Subscription-channel stickiness in sports nutrition is displacing traditional retail replenishment cycles. Direct-to-consumer protein powder brands are capturing lifetime value through flavor-curation algorithms. This behavioral shift is most visible in Greater London, where delivery density supports same-day fulfillment economics.
United Kingdom Plant Protein Market Segmentation
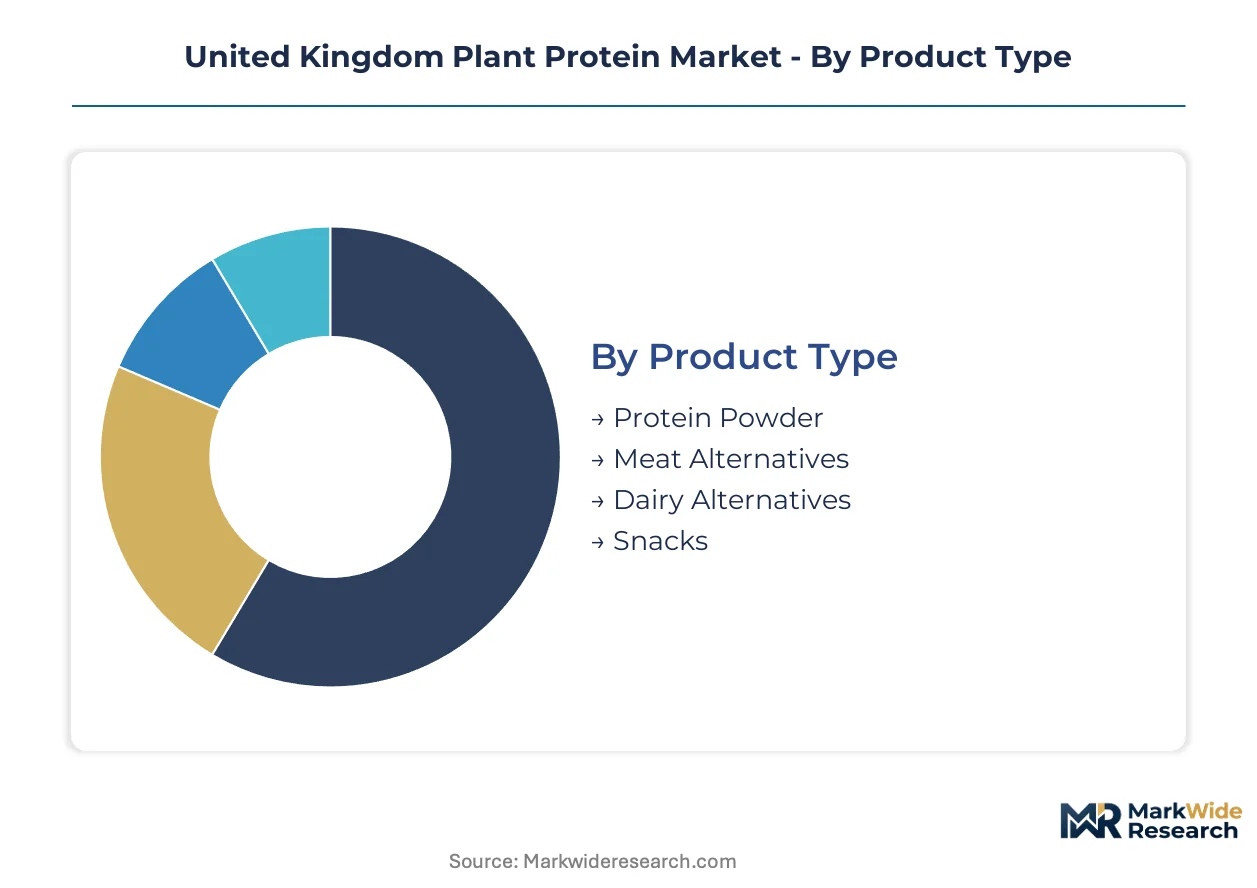
Segmentation in the United Kingdom plant protein market reveals how supply concentration, formulation complexity, and channel economics fragment commercial opportunity. Understanding these divisions exposes where margin pools deepen and where volume expansion accelerates.
Product Type:
Supply concentration among wet-fractionation specialists determines which product formats capture functional premium and which compete on commodity throughput.
- Protein Powder:Dry-blended isolates and concentrates achieving 80-90% protein content dominate sports nutrition formulations. Demand clusters around Greater London subscription channels where flavor-curation algorithms drive repeat purchase and lifetime value accumulation.
- Meat Alternatives:High-moisture extruded and shear-cell processed whole-muscle analogues require specialized texturizing systems. British retailers in Manchester and the Scottish Central Belt are expanding chilled and frozen own-label ranges, compressing branded shelf space.
- Dairy Alternatives:Oat-soy blends in barista formulations command stable penetration through coffee shop chains.
- Snacks:Extruded puffs and baked clusters incorporating protein isolates serve trial-friendly consumption occasions.
Today's leader: Protein Powder. Tomorrow's challenger: Meat Alternatives.
Source:
Origination geography and fractionation maturity create tiered cost structures that cascade through formulation economics.
- Pea:Yellow pea protein from North American and European origination dominates isolate supply. Wet-fractionation advances achieving 85%+ protein with reduced off-flavor carryover are enabling bakery and ready-meal reformulation across British manufacturing facilities.
- Soy:Mature dry-fractionation infrastructure and established supply chains support cost-competitive concentrate production. Allergen labeling requirements under British Retail Consortium standards constrain multi-product facility handling.
- Rice:Hypoallergenic positioning serves specialized pediatric and sports nutrition applications with premium pricing.
- Hemp:Limited fractionation scale and regulatory complexity around novel food status restrict commercial penetration to niche positioning.
Pea commands current volume leadership. Rice is gaining share fastest among allergen-sensitive formulation segments.
End User:
Consumer motivation intensity and price elasticity separate premium subscription stickiness from mass retail trial behavior.
- Fitness Enthusiasts:High-consumption users prioritizing leucine content and amino acid completeness drive protein powder premium tiers. Direct-to-consumer brands capture this segment through personalized nutrition algorithms and same-day fulfillment in London delivery zones.
- Vegans:Ethical sourcing verification and complete protein combining requirements create formulation complexity. DEFRA's developing environmental labeling framework is consolidating demand around suppliers with verified carbon accounting.
- Vegetarians:Flexitarian transition behavior generates hybrid meat-plant formulation demand in ready-meals and chilled retail.
- General Consumers:Trial-driven purchase patterns favor single-serve sachets and modular portion formats in supermarket channels.
Fitness Enthusiasts anchor current margin pools. General Consumers represent the steepest expansion trajectory as format innovation reduces trial barriers.
Distribution Channel:
Channel economics and inventory velocity determine which protein formats achieve scale and which remain specialty positioned.
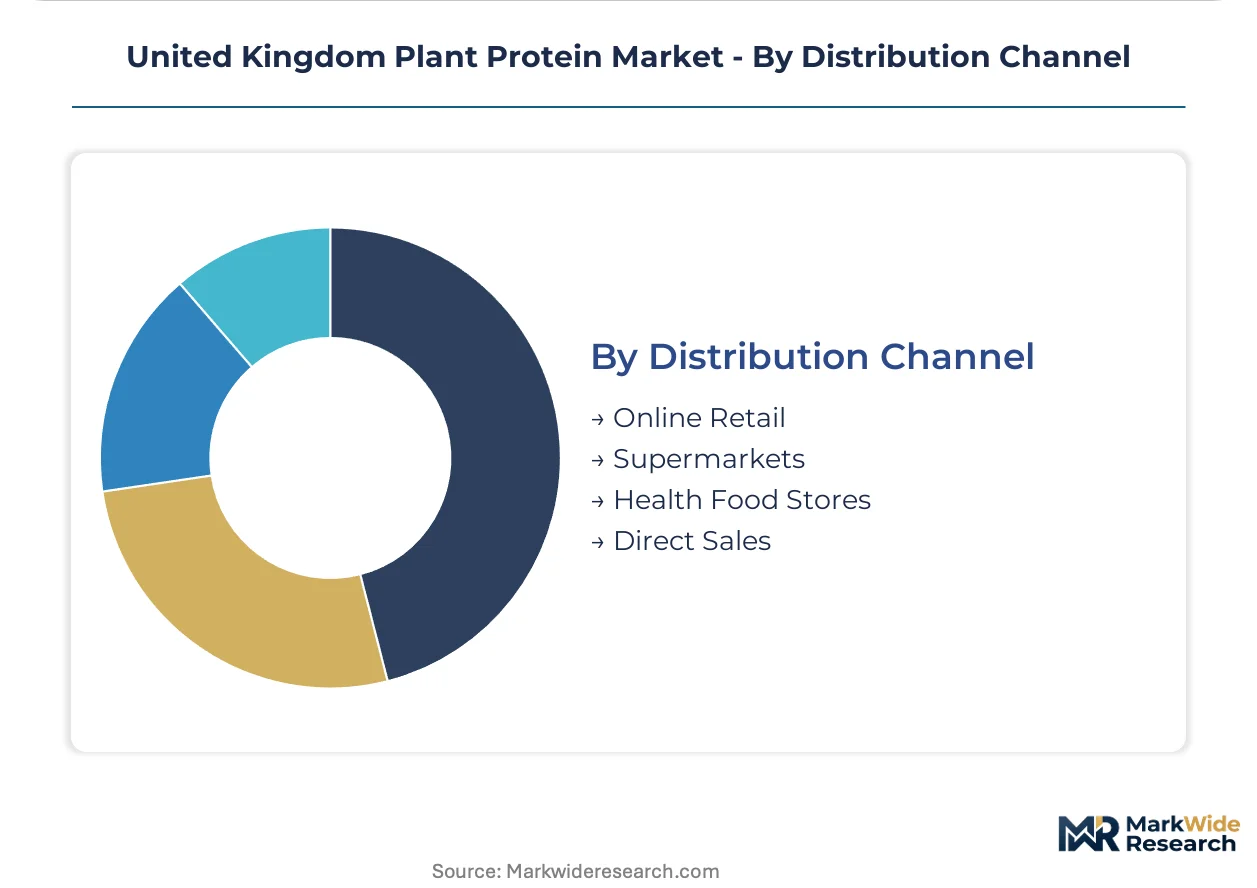
- Online Retail:Subscription-channel stickiness and flavor-curation algorithms displace traditional replenishment cycles. Same-day fulfillment density in Greater London supports premium pricing capture.
- Supermarkets:Chilled and frozen own-label range expansion by British retailers is compressing branded shelf space in Manchester and Scottish Central Belt locations.
- Health Food Stores:Specialist positioning for hemp and rice protein variants serves allergen-sensitive and ethical-sourcing motivated consumers.
- Direct Sales:Foodservice trial programs and B2B ingredient sampling support manufacturer relationship building with British formulators.
Supermarkets dominate current volume throughput. Online Retail is climbing the fastest as subscription economics reshape purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom plant protein industry traces its commercial roots to mid-20th century soy processing facilities established around Liverpool and Manchester, with contemporary expansion driven by wet-fractionation advances and food-tech clustering in southern England and Scotland.
London and the Southeast
Greater London anchors subscription-channel protein powder demand through same-day fulfillment density and flavor-curation algorithm adoption. The Food Standards Agency headquarters in London accelerates novel food dossier processing for emerging protein developers. White City and Shoreditch food-tech clusters host precision-fermentation startups engaging early regulatory pathway discussions.
Midlands
Birmingham and Nottingham manufacturing corridors concentrate ready-meal reformulation activity around pea isolate texturizing systems. DEFRA's developing environmental labeling framework is piloting carbon accounting verification with Midlands-based suppliers. Derbyshire and Staffordshire malt processing byproduct streams offer feedstock integration opportunities for emerging fractionation facilities.
North England
Greater Manchester generates concentrated flexitarian demand for hybrid meat-plant formulations across chilled retail channels. British Retail Consortium standards enforcement through Manchester-based auditing firms shapes supplier hygiene protocol investments. Oldham and Bolton extrusion equipment retrofits are piloting shear-cell processing for whole-muscle analogue production.
Scotland
The Edinburgh-Glasgow corridor presents greenfield processing capacity potential with underdeveloped wet-fractionation infrastructure. Scottish Enterprise innovation funding supports food-tech clustering around alternative protein development. Aberdeen and Dundee brewing byproduct streams offer localized feedstock for emerging protein extraction ventures.
Wales
South Wales manufacturing zones concentrate oat and hemp protein blending for dairy alternative barista formulations. Welsh Government food and drink strategy prioritizes sustainable protein supply chain development. Cardiff and Newport logistics hubs support distribution into Bristol and Birmingham retail networks.
United Kingdom Plant Protein Market Competitive Landscape
Premium-margin players sit above commodity-margin players across functional ingredient specialization, with taste-masking and texturizing expertise commanding formulation service premiums while origination-heavy processors compete on throughput scale. The vendor base stratifies into three tiers: integrated nutrition houses with flavor-technology portfolios, agricultural processors controlling pea and soy origination, and specialist texturizing system suppliers. Consolidation pressure is intensifying through strategic partnerships between extrusion equipment manufacturers and isolate producers, alongside capacity expansion into Scottish and Midlands greenfield sites.
Within the integrated nutrition tier, Kerry Group PLC and Tate & Lyle exemplify British-headquartered players leveraging taste and texturizing expertise to anchor clean-label formulation partnerships. Cargill Incorporated represents the origination-control archetype, with supply chain positioning over North American and European yellow pea crops. Roquette Frères and DSM-Firmenich occupy the specialist functional ingredient segment, with French and Swiss-registered structures reflecting continental European protein technology heritage.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Group PLC |
| Roquette Frères |
| Glanbia PLC |
| Tate & Lyle |
| DSM-Firmenich |
| International Flavors & Fragrances Inc. |
| Others |
Value Network & Pricing Analysis
Fitness enthusiasts concentrated in Greater London's subscription-channel economy anchor premium pricing capture through flavor-curation algorithm stickiness and same-day fulfillment premiums. This buyer archetype concentration reinforces a three-tier pricing structure across premium, standard, and economy levels, with formulation complexity and texturizing system integration determining tier placement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sports nutrition subscription brands from supermarket own-label ranges and bulk ingredient supply. Price differentiation rests on certification grade under British Retail Consortium standards and volume scale in procurement contracts. Cost compression in standard-tier isolates is intensifying because North American yellow pea origination shortages concentrate supply control among limited processors. General consumers in supermarket channels exhibit highest price sensitivity, while fitness enthusiasts demonstrate lowest elasticity due to personalized nutrition algorithm lock-in.
Supply Chain Analysis
DEFRA's developing environmental labeling framework and potential gene-editing policy relaxations are reshaping sourcing decisions around demonstrable carbon accounting and local feedstock integration. Geographic supply concentration centers on Canada, France, and Ukraine for yellow pea origination, with wet-fractionation capacity clustering in the Netherlands and Germany. Raw material dependencies include malting and brewing byproduct streams from Scottish and Midlands facilities, specialized hydrocolloid texturizing systems, and high-protein isolate concentrates. Single-source vulnerability runs through North American pea protein processors during crop yield variability. Distribution feeds from ingredient manufacturers through British formulators to retail and foodservice endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom plant protein market functions as a regulatory compounder where Food Standards Agency novel food authorization acceleration continuously redraws competitive access boundaries. DEFRA's environmental labeling framework milestone is consolidating demand around verified carbon accounting, creating sustained premium positioning for compliant suppliers.
For Market Incumbents: Anticipate precision-fermentation regulatory evolution by securing early pathway clarity through FSA engagement before gene-editing policy relaxations materialize. Consolidate formulation service relationships around taste-masking and texturizing expertise to defend against biomass fermentation specialists entering dairy alternative segments. Backward integration into Scottish Central Belt greenfield processing capacity captures underdeveloped wet-fractionation infrastructure proximity to brewing byproduct feedstocks.
For New Entrants and Emerging Players: Begin with single-serve sachet and modular portion format innovation targeting hesitant general consumers in supermarket trial programs. The Scottish Central Belt presents the most penetrable geography given underdeveloped processing infrastructure and Scottish Enterprise innovation funding availability. A direct-to-consumer flavor-curation algorithm approach, proven in Greater London sports nutrition, offers transferable go-to-market architecture for plant-based ready-meal partnerships.
For Investors and Strategic Acquirers: Agricultural processors with origination control over North American and European pea crops are the most active acquirer in this space, seeking downstream formulation capabilities to capture margin expansion. Long-term viability across the analysis window favors specialists bridging protein chemistry and consumer taste preference, given sensory scientist scarcity and 18-24 month recruitment cycles. Watch FSA precision-fermentation guidance finalization as the inflection signal distinguishing extractive from biomanufactured protein pathway winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Submission Engagement | FSA dossier-ready positioning secures provisional market access before competitors complete toxicology packages. |
| Scottish Central Belt Capacity Expansion | Greenfield wet-fractionation sites leverage Edinburgh-Glasgow brewing byproduct proximity for feedstock integration. |
| Flavor-Curation Algorithm Development | Direct-to-consumer subscription stickiness in Greater London displaces traditional retail replenishment economics. |
| Precision Fermentation Partnership | Dairy alternative formulators accelerate biomass fermentation alliances amid FSA compliance clarity gaps. |
| Environmental Labeling Certification | DEFRA carbon accounting verification creates first-mover premium positioning for British suppliers with transparent sourcing. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with food manufacturers, retail category buyers, ingredient procurement leads, and regulatory affairs specialists at the Food Standards Agency combined with secondary validation against FSA novel food authorization databases, British Retail Consortium audit records, DEFRA environmental labeling framework consultations, and customs trade data for pea and soy protein imports. Triangulation across these sources ensures demand-side consumption patterns align with supply-side origination and fractionation capacity.
Input-output matrices map protein isolate and concentrate flows from North American and European origination through British formulators to end-use applications across sports nutrition, meat alternatives, dairy alternatives, and bakery segments. Segmentation dimensions include product type, protein source, end-user motivation, and distribution channel, with CAGRs derived from elasticity-adjusted consumption trajectories and capacity expansion pipelines. Forecast inputs incorporate wet-fractionation yield improvements, extrusion equipment retrofit adoption, and subscription-channel penetration velocity.
Caveats apply where FSA precision-fermentation regulatory finalization, DEFRA gene-editing policy relaxation timing, or North American crop yield volatility could materially shift the outlook. Forecasts reflect documented assumptions around consumer flexitarian transition rates and retail own-label expansion commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Tempeh Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Vegan Food Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Vegan Flour Market