
 Plant-Based Wafer Biscuits Market | 2026-2036
Plant-Based Wafer Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Wafer Biscuits Market Insights
The EU Green Deal's Farm to Fork strategy is repositioning ingredient procurement standards across European snack manufacturing. Nestlé leverages its European R&D network to reformulate wafer fillings around oat and chickpea bases. Mondelez International anchors its plant-based portfolio through dedicated production lines in the Netherlands and Belgium. Hippeas competes by specializing in legume-derived crisp textures that differentiate from conventional wheat wafers.
Plant-based wafer biscuits are thin, layered crisp products manufactured without dairy, egg, or animal-derived ingredients, typically employing vegetable oils, plant proteins, and natural emulsifiers to achieve structural integrity and mouthfeel comparable to conventional wafers. The production process relies on controlled baking temperatures between 160°C and 200°C to create the characteristic honeycomb structure while maintaining clean-label ingredient declarations. Chocolate coated variants occupy the dominant margin pool due to premium positioning and longer shelf stability, while gluten-free ingredient types are registering the fastest volume trajectory as coeliac and low-FODMAP diet adherence expands. Supermarkets control the primary distribution channel for branded volumes, though online platforms are capturing disproportionate growth in subscription-based snack boxes targeting health-conscious individuals.
EFSA's novel food authorization pathways and the EU's deforestation regulation are tightening supply chain documentation requirements for palm oil and cocoa derivatives entering wafer formulations. REACH compliance on food-contact substances and Germany's Lebensmittel- und Futtermittelgesetzbuch set baseline thresholds for contaminant limits and labeling precision. Stakeholders must monitor evolving national transpositions of the EU Packaging and Packaging Waste Regulation as recycled content mandates reshape flexible film specifications for biscuit wrappers.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is restructuring ingredient procurement across European wafer manufacturing, forcing reformulation of emulsifiers and binding agents while tightening documentation requirements for palm oil and cocoa derivatives.
Growth Catalysts
- REACH compliance on food-contact substances:Manufacturers investing in clean-label emulsifier alternatives gain preferential shelf placement in German and UK retail chains.
- Coeliac disease prevalence:Low-FODMAP diet adherence in Northern Europe accelerates demand for gluten-free oat and chickpea-based wafer formulations.
- Private-label acceleration:Supermarket chains in Germany and the United Kingdom are expanding dedicated plant-based confectionery aisles, creating volume anchors for certified suppliers.
Market Restraints
- Cocoa derivative price volatility:Chocolate-coated variants face margin compression from concentrated West African supply and EU deforestation regulation compliance costs.
- Technical binding limitations:Plant proteins lack the thermal stability of egg-based emulsifiers, requiring precise temperature control between 160°C and 200°C that increases scrap rates.
- EFSA novel food pathways:Legume-derived protein isolates face extended authorization timelines that delay product launches by 18-24 months.
Strategic Opportunities
- Subscription snack boxes:Online platforms targeting health-conscious consumers in the United Kingdom offer recurring revenue models with higher per-unit margins than supermarket distribution.
- EU Packaging and Packaging Waste Regulation:Recycled content mandates for flexible films create first-mover advantage for manufacturers with certified circular packaging partnerships.
- Legume crisp texture specialization:Chickpea and lentil-derived honeycomb structures differentiate from conventional wheat wafers in the premium segment.
Industry Challenges
- Clean-label formulation expertise:Food technologists skilled in plant protein thermal behavior and natural emulsifier synergy command premium salaries that strain mid-tier producers.
- Production line reconfiguration:Dedicated allergen-free facilities require capital outlays for segregated baking and coating equipment to prevent cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Wafer Biscuits Market |
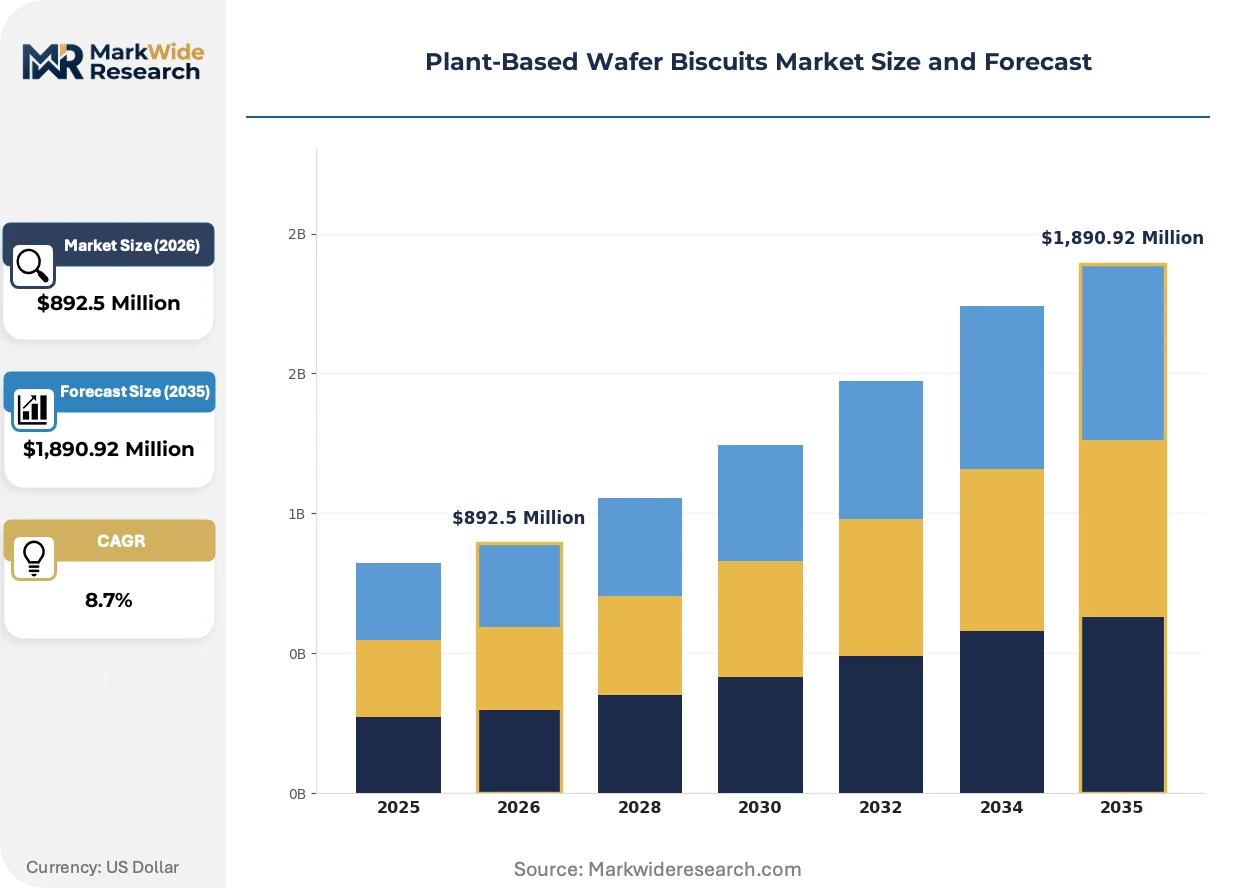
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,890.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet, Savory, Chocolate Coated, Nut Filled Ingredient Type: Gluten-Free, Whole Grain, Organic, Non-GMO Distribution Channel: Online, Supermarkets, Health Food Stores, Convenience Stores Consumer Type: Vegans, Vegetarians, Health-Conscious Individuals, Snack Enthusiasts |
| Companies Covered | Mondelez International, Nestlé, PepsiCo, Hippeas, Beanfields, Eat Real, Clearspring, Diva Nutritional Products, Nairn's Oatcakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Wafer Biscuits Market Trends and Innovations
Reformulation around legume-derived proteins and natural binding systems is compressing development cycles while regulatory pressure on supply chain documentation accelerates digital traceability investments.
Pulse protein extrusion technology is electrifying wafer manufacturing by enabling chickpea and lentil bases to achieve structural integrity comparable to wheat without gluten networks. German and UK health-conscious consumers are adopting these variants at twice the rate of conventional plant-based alternatives. This technology is compressing the premium-mass market gap by delivering clean-label credentials at standard price points.
EFSA's tightened novel food authorization pathways are extending time-to-market for innovative protein sources while increasing documentation burdens on suppliers. Manufacturers are responding by concentrating R&D investment on oat and chickpea bases with established safety profiles rather than experimental legumes. Chocolate-coated variants face the steepest compliance costs due to cumulative cocoa derivative and emulsifier scrutiny.
Subscription-based snack box curation is displacing impulse supermarket purchases among millennial and Gen Z demographics in the United Kingdom. Direct-to-consumer platforms leverage algorithmic personalization to match dietary restrictions with certified products, bypassing traditional retail slotting fees. This channel shift is most visible in London and Manchester metropolitan clusters where delivery density supports unit economics.
Plant-Based Wafer Biscuits Market Segmentation
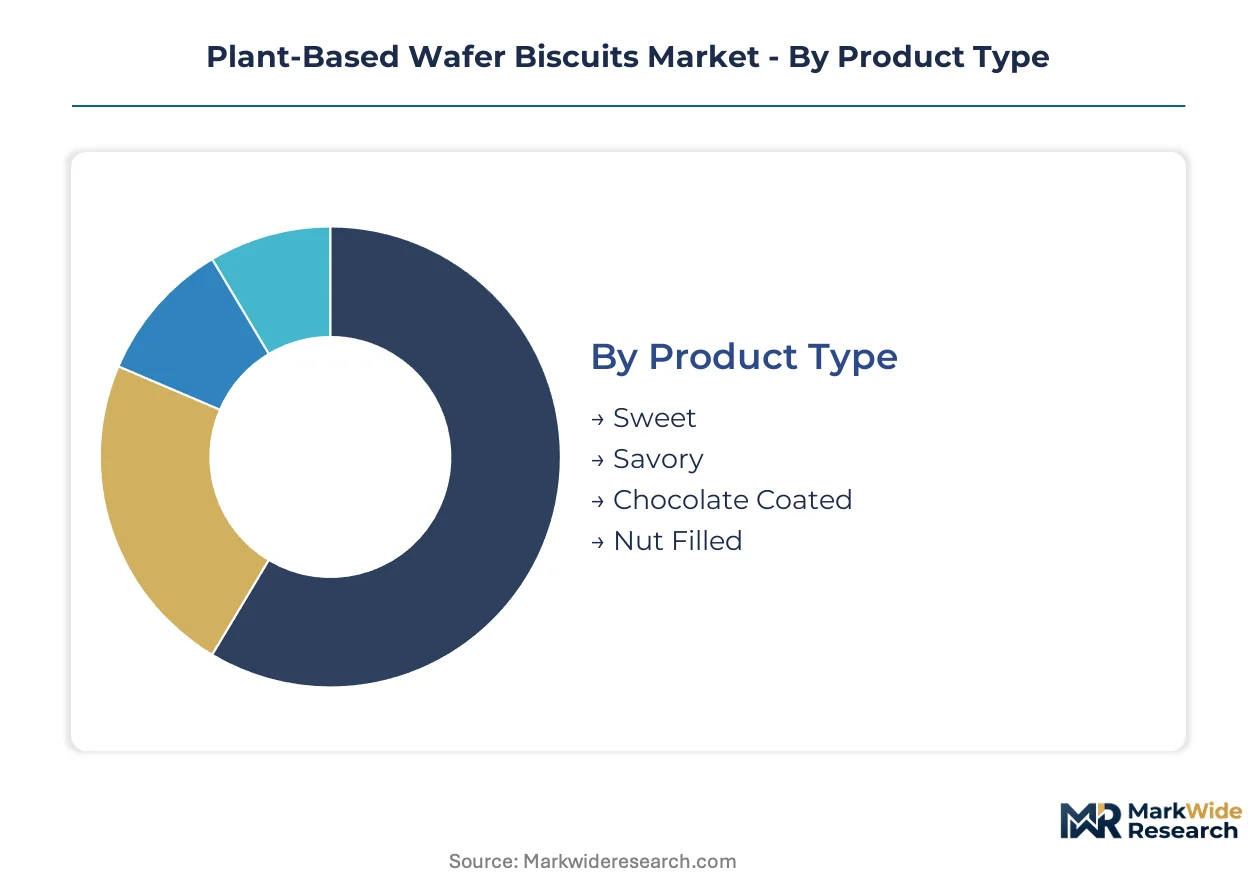
Wafer biscuit segmentation reveals divergent margin structures across taste profiles and dietary positioning. Manufacturers optimize formulation investments by matching production complexity to channel-specific price elasticity and certification requirements.
Product Type:
Volume concentrates in mass-market sweet variants while premium positioning clusters around chocolate-coated and nut-filled specialty lines.
- Chocolate Coated:These variants combine cocoa butter-based shells with plant-derived cream fillings to achieve extended shelf stability. German and UK supermarket chains allocate disproportionate shelf space to certified sustainable cocoa variants. EFSA's tightened emulsifier documentation compresses margins for mid-tier producers lacking direct bean-to-bar partnerships.
- Sweet:Standard vanilla and fruit-flavored wafers dominate unit economics through high-throughput production lines. Private-label programs in British and German retail chains source these variants at scale, prioritizing oat and chickpea bases with established clean-label credentials. REACH compliance on food-contact substances favors suppliers with integrated allergen-free facilities.
- Savory:Herb and vegetable-infused formulations target low-sodium positioning for health-conscious snacking occasions.
- Nut Filled:Hazelnut and almond cream variants command specialty positioning through premium ingredient sourcing.
Today's leader: Sweet. Tomorrow's challenger: Chocolate Coated.
Ingredient Type:
Certification tiers stratify procurement costs and retail slotting access across European distribution networks.
- Gluten-Free:Oat, chickpea, and lentil bases replace wheat flour through controlled extrusion at 160°C to 200°C baking temperatures. Northern European coeliac and low-FODMAP diet adherence concentrates demand in Germany and Scandinavia. EFSA novel food pathways for experimental legume proteins delay competitive entry by 18-24 months.
- Organic:EU organic certification mandates 95% organic agricultural ingredients and prohibits synthetic emulsifiers. German Bio-Siegel and UK Soil Association standards create dual compliance burdens for pan-European suppliers. The EU Green Deal's Farm to Fork strategy tightens residue testing thresholds.
- Whole Grain:Bran-inclusive formulations target fiber content claims for digestive health positioning.
- Non-GMO:Identity-preserved supply chains document genetic modification absence through batch-level traceability systems.
Organic commands current premium shelf placement. Gluten-free is climbing the fastest as dietary restriction prevalence expands.
Distribution Channel:
Channel selection determines margin capture through slotting fee exposure versus direct customer relationship ownership.
- Supermarkets:Branded volume anchors concentrate in German and UK retail chains expanding dedicated plant-based confectionery aisles. Private-label acceleration creates volume commitments for certified suppliers with segregated allergen-free production lines. The EU Packaging and Packaging Waste Regulation's recycled content mandates reshape flexible film specifications for biscuit wrappers.
- Online:Subscription-based snack boxes target health-conscious millennials and Gen Z demographics in London and Manchester metropolitan clusters. Algorithmic personalization matches dietary restrictions with certified products, bypassing traditional retail slotting fees. Direct-to-consumer platforms capture recurring revenue models with higher per-unit margins.
- Health Food Stores:Specialty retailers prioritize certified organic and gluten-free variants for ingredient-transparent positioning.
- Convenience Stores:Impulse-oriented single-serve packaging targets immediate consumption occasions with limited SKU depth.
Supermarkets dominate branded volume today. Online subscription models represent the steepest expansion trajectory for emerging challenger brands.
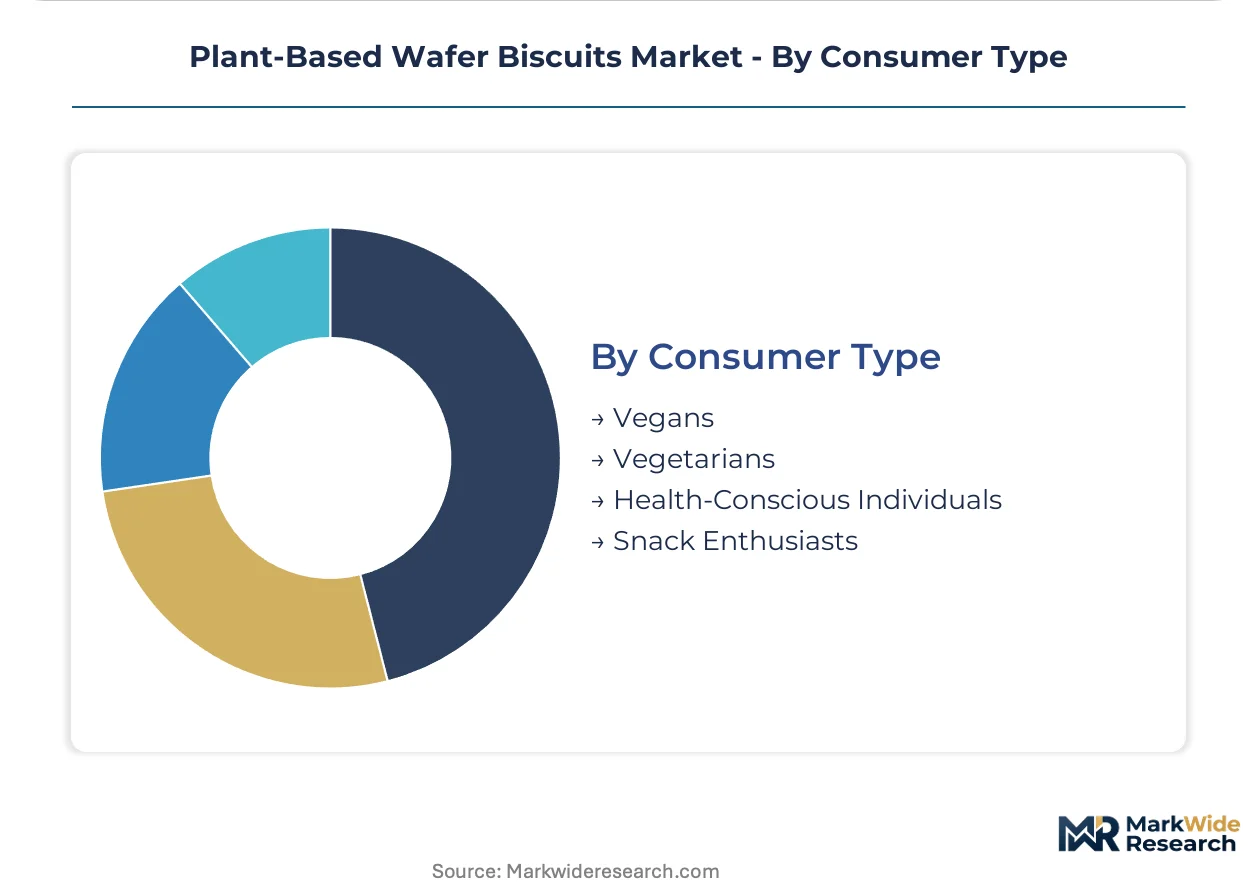
Consumer Type:
Dietary identity drives formulation specificity and marketing communication strategy across European markets.
- Vegans:Strict plant-based adherence requires exclusion of all animal-derived ingredients including honey, dairy traces, and egg-based emulsifiers. German vegan society certifications and UK Vegan Society trademarks create recognized trust markers for shelf navigation. Manufacturers reformulate around oat and chickpea bases with natural binding systems to achieve structural integrity.
- Health-Conscious Individuals:Clean-label preference prioritizes short ingredient declarations and recognizable whole food sources. Low-FODMAP and reduced-sugar positioning concentrates in UK and German urban markets. Pulse protein extrusion technology enables legume-derived crisp textures that differentiate from conventional wheat wafers.
- Vegetarians:Lacto-ovo flexibility permits dairy-derived fillings while excluding meat and fish ingredients.
- Snack Enthusiasts:Taste-driven purchase decisions prioritize flavor intensity and textural satisfaction over dietary restriction compliance.
Health-Conscious Individuals anchor current premium positioning. Vegans are gaining share fastest as ethical consumption scales beyond niche demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial wafer baking originated in Central European confectionery traditions during the late nineteenth century, with Austrian and German manufacturers pioneering the layered crisp technology that defines modern plant-based variants.
Germany
Private-label acceleration in Rewe and Edeka chains concentrates procurement power among certified oat-base suppliers. The Lebensmittel- und Futtermittelgesetzbuch enforces strict contaminant thresholds that favor integrated allergen-free facilities. Production clusters in Bavaria and North Rhine-Westphalia host dedicated lines for chickpea-derived honeycomb structures.
United Kingdom
Subscription snack box penetration in London and Manchester metropolitan areas displaces traditional supermarket impulse purchasing. The UK Vegan Society trademark program creates recognized shelf navigation markers for reformulated emulsifier-free variants. Midlands-based co-manufacturers scale pulse protein extrusion capacity to serve direct-to-consumer platforms.
Netherlands
Rotterdam port logistics anchor sustainable cocoa derivative imports for chocolate-coated premium lines. REACH compliance on food-contact substances drives investment in natural binding system R&D. Eindhoven-region equipment fabricators supply controlled-temperature baking systems to pan-European wafer producers.
Belgium
Bean-to-bar chocolate integration in Flemish processing corridors secures margin capture for coated variants. EU deforestation regulation documentation requirements concentrate sourcing relationships among vertically integrated cocoa handlers. Antwerp distribution hubs channel certified organic volumes into German retail chains.
France
Île-de-France health-conscious demographics adopt low-FODMAP positioning at rates exceeding European averages. ANSM oversight of novel food notifications delays legume protein isolate launches by standard EFSA timelines. Lyon-area traditional biscuit manufacturers retrofit heritage equipment for gluten-free oat base production.
Plant-Based Wafer Biscuits Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the plant-based wafer landscape. Dedicated baking facilities with segregated allergen lines require substantial capital outlays, while brand architects outsource manufacturing to certified co-packers. Three archetypes dominate: multinational confectionery conglomerates with European R&D networks, challenger brands built on single-ingredient transparency narratives, and private-label suppliers with integrated oat and chickpea sourcing. Competitive moves concentrate on portfolio diversification into chocolate-coated premium tiers and backward integration into pulse protein supply.
Within the multinational tier, Mondelez International and Nestlé anchor scale-driven positioning through dedicated production infrastructure in the Netherlands and Belgium. Hippeas exemplifies the challenger archetype with legume-derived crisp texture specialization that differentiates from conventional wheat formulations. These three occupy positions spanning mass-market volume capture through premium-mid-economy pricing stratification.
| Leading Market Players |
|---|
| Mondelez International |
| Nestlé |
| PepsiCo |
| Hippeas |
| Beanfields |
| Eat Real |
| Clearspring |
| Diva Nutritional Products |
| Nairn's Oatcakes |
| Others |
Pricing and Supply Chain Analysis
Private-label suppliers with integrated oat and chickpea sourcing anchor pricing discipline through captive ingredient supply and volume commitments to German and UK retail chains. Their backward integration into pulse protein supply insulates margin positions against cocoa derivative volatility while compressing price premiums for clean-label certification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium chocolate-coated variants with EU organic certification and bean-to-bar cocoa documentation command shelf price multiples over standard private-label oat-base formats. Cost compression in mid-tier sweet variants is intensifying because REACH compliance investments on food-contact substances concentrate among integrated producers. Health-conscious subscription box subscribers show least price sensitivity, while German supermarket private-label buyers extract maximum volume discounts.
Supply Chain Analysis
Freight cost differentials between Rotterdam port cocoa imports and overland oat flour distribution from Bavaria and North Rhine-Westphalia shape regional production clustering. Supply concentrates in the Netherlands for chocolate-coated premium lines, Germany for oat and chickpea base manufacturing, and Belgium for bean-to-bar integration. Raw material dependencies include West African cocoa derivatives, Baltic region oat supplies, and Mediterranean chickpea sources. Single-source vulnerability in novel legume protein isolates creates EFSA authorization bottlenecks. Distribution runs through supermarket chain direct procurement for branded volumes and algorithmic curation platforms for subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulse protein extrusion technology diffusion enables margin expansion through clean-label premium capture at standard production costs. Reformulation around established oat and chickpea bases avoids EFSA novel food delays while positioning for EU Green Deal procurement preference.
For Market Incumbents: Lock in segregated allergen-free facility access through long-term co-manufacturer contracts before capacity scarcity intensifies. Defend against challenger brand texture differentiation by securing exclusive pulse protein extrusion equipment allocations from Eindhoven-region fabricators. Prioritize backward integration into Baltic oat sourcing to preempt EU deforestation regulation documentation burdens on secondary suppliers. For New Entrants and Emerging Players: Capture algorithmic curation platform relationships in London and Manchester metropolitan clusters where delivery density supports unit economics. Target health-conscious millennial and Gen Z demographics through subscription snack box positioning with certified gluten-free and low-FODMAP credentials. Lead with legume-derived crisp texture narratives that differentiate from incumbent wheat wafer formulations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier private-label suppliers with integrated oat sourcing and underutilized segregated production capacity. The five-to-ten year viability window favors certified suppliers with established EFSA safety profiles over experimental legume protein ventures. Monitor EFSA novel food authorization timelines as the critical inflection signal for competitive entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pulse Protein Extrusion Scale-Up | Chickpea and lentil honeycomb structures differentiate from conventional wheat wafers in German premium aisles. |
| Segregated Allergen-Free Facility Investment | Integrated production lines command preferential shelf placement under Germany's Lebensmittel- und Futtermittelgesetzbuch contaminant thresholds. |
| Bean-to-Bar Cocoa Integration | Vertically controlled supply secures margin capture for chocolate-coated variants facing EU deforestation compliance costs. |
| Subscription Platform Partnership | Algorithmic personalization bypasses supermarket slotting fees while capturing recurring revenue from UK health-conscious consumers. |
| Certified Circular Packaging Transition | Recycled content mandates under EU Packaging and Packaging Waste Regulation create first-mover advantage for flexible film specifications. |
Research Methodology
Coverage spans Germany, the United Kingdom, the Netherlands, Belgium, and France, with primary inputs from each national market. The approach combines executive interviews with plant-based category managers at retail chains, procurement directors at co-manufacturing facilities, and food technology R&D leads with secondary validation through EU regulatory filings, customs trade data on cocoa and pulse imports, and Nielsen retail audit data. Bottom-up volume triangulation across product type, ingredient certification tier, and distribution channel intersects with top-down value estimation anchored to disclosed production capacity and slotting fee structures.
Rate-of-change decomposition separates volume trajectory from price evolution across the analysis window. Segmentation modeling incorporates product type differentiation, ingredient certification tier, distribution channel economics, and consumer dietary identity clustering. CAGRs derive from fitted growth curves applied to production capacity expansion timelines and retail space allocation shifts. Industry-specific forecast inputs include EFSA novel food authorization pipeline status and EU Green Deal procurement policy implementation schedules.
EFSA regulatory delays, cocoa derivative price volatility, and subscription platform churn rates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on authorization timelines and consumer adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Noodles Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Global Tofu Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market