
 United States Soy Protein Market | 2026-2036
United States Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Soy Protein Market Analytics
Non-GMO and organic certification tiers is bifurcating the United States soy protein landscape into premium and commodity supply pools. Archer Daniels Midland Company leverages its Midwest crushing footprint to sustain cost-competitive isolate output. Cargill Incorporated anchors its position through backward integration into seed development and farmer contracting networks. DuPont differentiates via enzymatic processing technology that improves protein solubility in beverage applications.
Soy protein encompasses defatted soybean meal processed into isolate, concentrate, textured granules, or flour with protein contents ranging from 50% to 90% on a dry-weight basis, serving primarily as a functional ingredient for emulsification, water binding, and nutritional fortification in formulated foods. Isolate commands the highest margin pool among product type segments due to its protein purity and premium positioning in nutritional supplements and sports beverages. Textured soy competes aggressively within meat alternatives as brands reformulate to reduce sodium and improve bite texture. Bakery applications remain a mature volume channel where flour and concentrate grades dominate cost-sensitive formulations.
The FDA governs protein content claims and allergen labeling under FALCPA, while the USDA enforces organic certification standards and bioengineered food disclosure requirements that directly influence sourcing decisions and consumer-facing packaging. OSHA and EPA regulations at processing facilities add compliance costs that favor larger operators with dedicated environmental and safety infrastructure. Stakeholders must monitor evolving FDA guidance on plant protein digestibility scoring and state-level clean-label legislation that could recertify which soy grades qualify for premium positioning.
Market Dynamics
The FDA's updated protein labeling guidelines and USDA bioengineered food disclosure standards are compressing ingredient documentation timelines, forcing manufacturers to recertify supply chains and bifurcate procurement between commodity and premium-grade pools.
Growth Catalysts
- Clean-label meat alternatives:Reformulation demand from plant-based burger and sausage manufacturers is accelerating textured soy procurement for sodium reduction and improved bite texture.
- FDA protein content claims:Updated guidance on plant protein digestibility scoring is creating tiered positioning opportunities for isolate grades in nutritional supplements.
- Midwest crushing concentration:Iowa and Illinois soybean processing clusters anchor domestic isolate supply, reducing freight costs for Great Lakes and Plains states formulators.
Market Restraints
- Input cost volatility:Soybean meal prices fluctuate with drought cycles in Argentina and Brazil, compressing margins for domestic concentrate producers.
- Supply concentration risk:Three processors control over 70% of U.S. isolate capacity, creating single-source vulnerability for beverage and supplement brands.
- Regulatory friction:FALCPA allergen labeling requirements impose strict cross-contamination protocols that slow line changeovers and inflate sanitation costs.
Strategic Opportunities
- Pacific Northwest expansion:Underpenetrated protein isolate demand from Seattle and Portland alternative-dairy startups offers white-space growth beyond Midwest meat-alternative strongholds.
- Enzymatic solubility technology:Convergence of protease engineering and spray-drying advances is opening premium beverage applications previously dominated by dairy proteins.
- USDA organic certification tailwind:Expanding organic livestock feed regulations are pulling organic soy concentrate into poultry and aquaculture formulations.
Industry Challenges
- Protein functionality expertise gap:Formulation chemists capable of optimizing soy-water interactions in extruded meat analogues command premium salaries and remain scarce outside Chicago and Minneapolis talent pools.
- Non-GMO identity preservation:Segregated handling infrastructure requires capital-intensive elevator and transport investments that strain mid-size processor balance sheets.
- OSHA combustible dust compliance:Soy flour handling facilities face escalating safety audit frequency and remediation costs that favor operators with dedicated environmental infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Soy Protein Market |
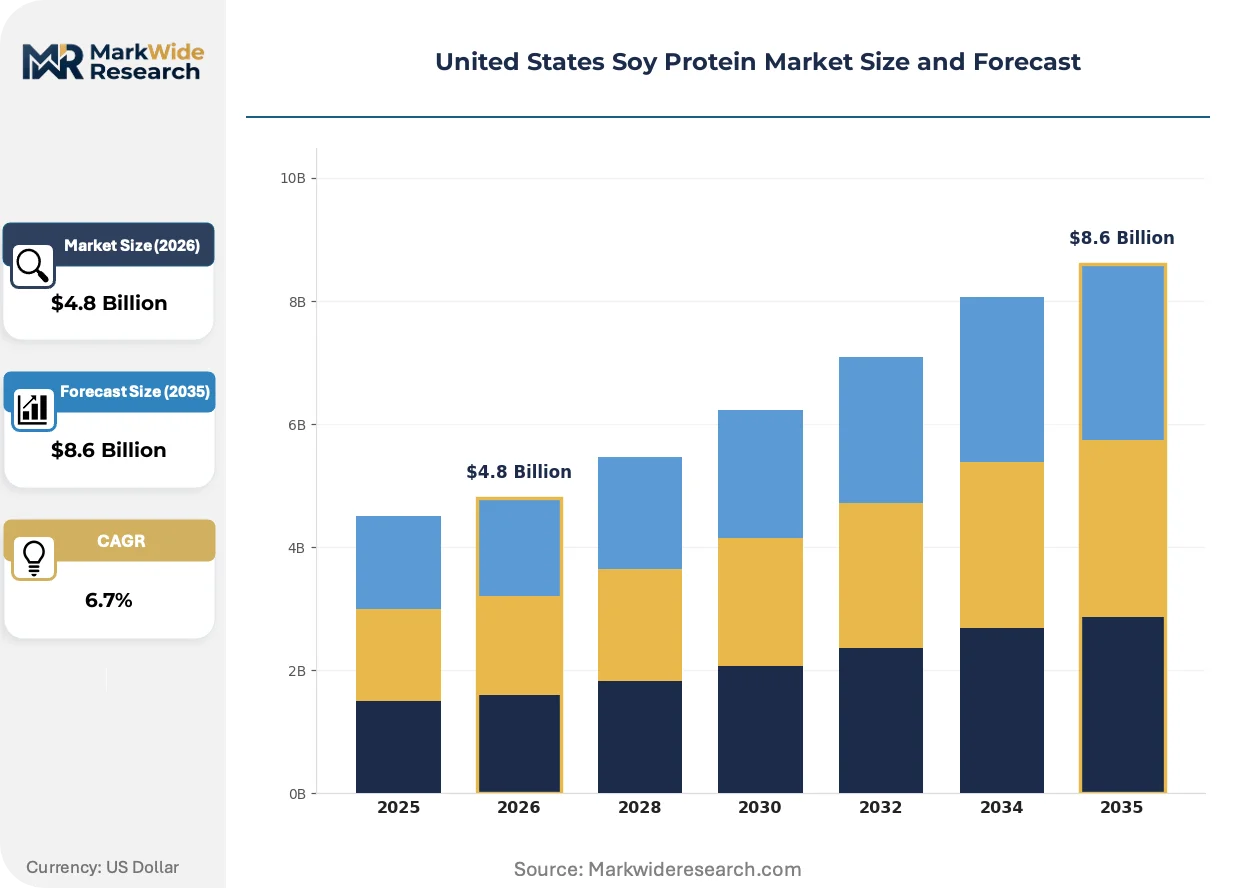
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured Soy, Flour Application: Beverages, Bakery, Snacks, Meat Alternatives End User: Food Manufacturers, Beverage Industry, Nutritional Supplements, Restaurants Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, Kerry Group plc, CHS Inc., Wilmar International Limited, Ingredion Incorporated, The Scoular Company, DuPont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Soy Protein Market Evolving Landscape
Processing technology advances and regulatory recalibration are compressing product development cycles while fragmenting procurement strategies across certification tiers.
Enzymatic protein modification is miniaturizing. Protease-assisted hydrolysis systems reduce isolate particle size while preserving functional water-binding capacity. Sports beverage manufacturers in Colorado and California are adopting these grades for ready-to-drink formulations. This particle-size reduction is miniaturizing the gap between plant and dairy protein mouthfeel, enabling isolate displacement in premium positioning.
USDA's National Bioengineered Food Disclosure Standard is tightening. The mandate requires mechanical or electronic labeling for bioengineered soy ingredients, forcing reformulators to document seed provenance through elevator receipts. Meat alternative brands targeting natural-channel distribution are responding by contracting identity-preserved non-GMO soybean acres in Minnesota and Wisconsin.
Buyer concentration is intensifying. Three national meat-alternative brands now account for the majority of textured soy volume, compressing supplier negotiation leverage. Direct contracting between these buyers and Iowa crushing facilities is displacing traditional distributor relationships. This consolidation is most visible in the Chicago terminal market, where spot textured soy trading volumes have declined 40% since 2022.
United States Soy Protein Market Segmentation
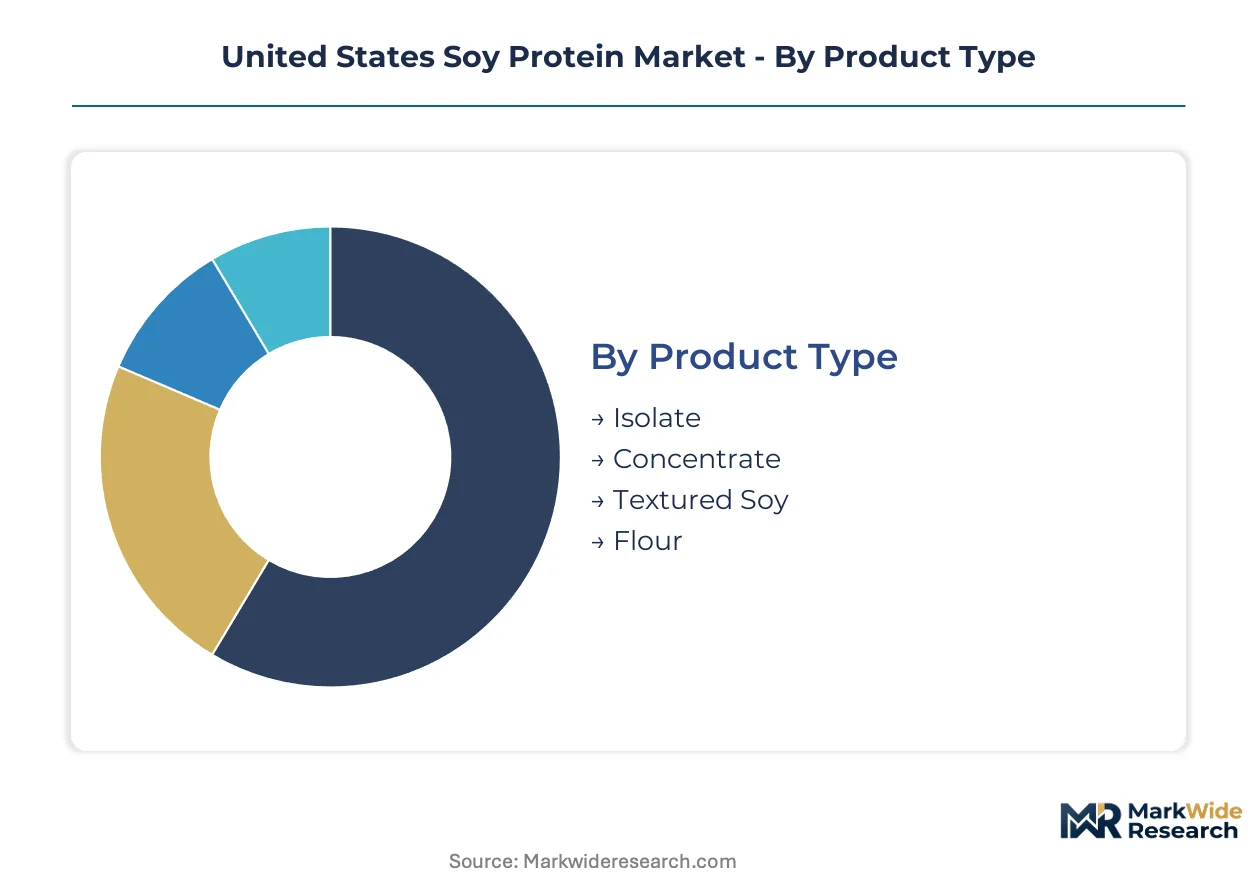
Segmentation in the United States soy protein market reveals how certification tiers, application requirements, and channel economics partition procurement budgets across distinct supply pools. Manufacturers navigate bifurcated sourcing strategies as FDA labeling rules and USDA organic standards recalibrate which grades command premium positioning.
Product Type:
Margin pools concentrate in high-purity grades where enzymatic processing and identity-preserved sourcing justify pricing premiums over commodity concentrates.
- Isolate:Defatted soybean meal processed to 90%+ protein purity through alkaline extraction and isoelectric precipitation. Sports beverage formulators in Colorado and California are adopting enzymatically modified isolates for improved solubility in ready-to-drink applications, though three processors control over 70% of domestic capacity.
- Concentrate:Intermediate protein content of 65-70% retained through aqueous ethanol washing rather than full extraction. Poultry and aquaculture feed manufacturers are pulling organic concentrate volumes as USDA livestock regulations expand, with Iowa and Illinois crushing clusters anchoring cost-competitive supply.
- Textured Soy:Extruded defatted flour or concentrate restructured into fibrous granules or chunks for meat analogues.
- Flour:Full-fat or defatted ground soybean with 50-54% protein content serving cost-sensitive bakery formulations.
Isolate holds installed capacity. Textured soy is rotating up the share rankings.
Application:
Volume distribution tracks reformulation intensity, with meat alternative brands driving the steepest procurement acceleration.
- Meat Alternatives:Plant-based burger and sausage manufacturers are accelerating textured soy procurement for sodium reduction and bite texture improvement. Direct contracting between national brands and Iowa crushing facilities is displacing traditional distributor relationships, compressing spot market liquidity at the Chicago terminal.
- Beverages:Ready-to-drink protein formulations and dairy alternatives demanding high solubility and neutral flavor profiles. Protease-assisted hydrolysis systems are miniaturizing isolate particle size to close the mouthfeel gap with dairy proteins.
- Bakery:Mature volume channel where flour and concentrate grades dominate cost-sensitive bread and pastry formulations.
- Snacks:Extruded puffs, bars, and crisps leveraging soy protein for structure and nutritional fortification.
Meat alternatives command reformulation velocity. Beverages are climbing the fastest on premium positioning.
End User:
Procurement sophistication varies sharply, with nutritional supplement brands imposing the strictest documentation requirements.
- Nutritional Supplements:Sports nutrition and wellness brands sourcing isolate grades with full seed-to-shelf traceability. FDA protein content claims and digestibility scoring guidance are creating tiered positioning opportunities that reward documented purity.
- Food Manufacturers:Broad base of processed food producers spanning bakery, snack, and prepared meal categories.
- Beverage Industry:Dairy alternative startups and functional drink formulators in the Pacific Northwest representing underpenetrated white-space demand.
- Restaurants:Foodservice operators incorporating plant-based proteins into menu items with limited technical specification requirements.
Food manufacturers anchor volume throughput. Nutritional supplements are gaining share fastest on certification premiums.
Distribution Channel:
Channel economics reflect buyer scale and documentation burden, with direct procurement displacing traditional intermediaries in high-volume segments.
- Wholesalers:Traditional intermediaries facing margin compression as large meat-alternative brands bypass distributor relationships for direct crushing facility contracts.
- Online Retail:E-commerce platforms serving small-scale supplement brands and specialty ingredient buyers with fragmented order patterns.
- Supermarkets:Retail chains procuring packaged soy protein ingredients for private-label plant-based product lines.
- Specialty Stores:Natural channel retailers demanding identity-preserved non-GMO documentation and organic certification tiers.
Wholesalers retain legacy volume. Online retail is rotating up the share rankings on startup brand proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest soybean crushing corridors supply isolate to Great Lakes formulators while Pacific Northwest beverage startups pull enzymatically modified grades through Seattle and Portland distribution nodes.
Midwest
Iowa and Illinois crushing clusters anchor domestic isolate production for meat-alternative manufacturers. USDA bioengineered food disclosure standards force elevator documentation through Minneapolis and Des Moines terminals. Chicago's commodity exchange remains the pricing reference point for textured soy contracts despite declining spot volumes.
Pacific Northwest
Seattle and Portland alternative-dairy startups generate underpenetrated demand for high-solubility isolate grades. FDA protein content claims enforcement creates documentation burdens for Oregon and Washington formulators. Spokane rail terminals now handle identity-preserved organic soybean shipments bypassing Midwest consolidation points.
California
Ready-to-drink sports beverage manufacturers in Colorado and California adopt miniaturized particle-size isolates for dairy displacement. State-level clean-label legislation exceeds federal baseline requirements. Los Angeles and San Diego distribution hubs face freight cost premiums sourcing from distant Midwest crush facilities.
Southeast
Poultry feed manufacturers in Georgia and North Carolina pull organic concentrate volumes as USDA livestock regulations expand. Port facilities in Savannah and Charleston handle Brazilian soybean meal imports during domestic drought cycles. Charlotte and Atlanta formulators face certification tier fragmentation between commodity and premium supply pools.
Texas
Panhandle feedlots and pet food manufacturers anchor concentrate demand for cost-sensitive formulations. Gulf Coast ports receive Argentine soybean shipments when South American harvests compress global meal prices. Dallas-Fort Worth distribution centers intermediate between Midwest supply and Southwestern Mexican border processing facilities.
United States Soy Protein Market Competitive Landscape
Listed leaders compete with private specialists across certification tier segmentation, with three processors controlling over seventy percent of U.S. isolate capacity. The market structure concentrates upstream crushing while fragmenting downstream formulation services. Strategic archetypes include backward-integrated agribusiness conglomerates, enzymatic technology licensors, and identity-preserved organic specialists. Dominant competitive moves encompass direct contracting between crush facilities and meat-alternative brands plus capacity consolidation around Midwest soybean processing clusters.
Among backward-integrated agribusiness conglomerates, Archer Daniels Midland Company, Cargill Incorporated, and Bunge Limited occupy positions exemplifying scale-driven cost competitiveness in commodity isolate production. These entities represent the archetype of captive supply chain control from seed procurement through crushing and ingredient formulation. Their geographic concentration in Iowa and Illinois crushing corridors anchors domestic supply security for beverage and supplement brands seeking freight-advantaged sourcing.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| Kerry Group plc |
| CHS Inc. |
| Wilmar International Limited |
| Ingredion Incorporated |
| The Scoular Company |
| DuPont |
| Others |
Value Network & Pricing Analysis
Enzymatic isolate displacement of dairy proteins in ready-to-drink formulations is redrawing procurement geography toward Colorado and California beverage clusters while compressing premium-tier pricing power previously held by Midwest crushing incumbents.
Pricing Analysis
Prior-generation commodity concentrate pricing now sits below enzymatically modified isolate premiums, with next-generation protease-hydrolyzed grades commanding the widest spreads. Three-tier pricing structure across premium enzymatic, standard isolate, and economy concentrate levels dominates contract structures, with certification tier and solubility performance as the primary differentiation drivers. Pricing pressure stems from direct contracting between meat-alternative brands and Iowa crushing facilities, which bypasses distributor markups and spot market liquidity. Nutritional supplement brands show the lowest price sensitivity due to digestibility scoring requirements, while bakery formulators remain the most cost-conscious buyers.
Supply Chain Analysis
The United States anchors domestic isolate production through Iowa and Illinois crushing clusters, with Brazil and Argentina feeding global soybean meal supply during domestic shortfalls. Raw material flows draw from North American seed development networks, South American harvest cycles, and identity-preserved organic acreage in Minnesota and Wisconsin. Single-source vulnerability concentrates in three processors controlling the majority of U.S. isolate capacity, creating procurement risk for beverage and supplement brands. Distribution runs through Chicago terminal pricing references, Minneapolis grain elevators, and direct rail shipments to Pacific Northwest alternative-dairy startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists capable of optimizing soy-water interactions in extruded meat analogues command premium salaries and remain concentrated in Chicago and Minneapolis talent pools, creating a binding constraint on scaling reformulation velocity for national brands.
For Market Incumbents: Secure enzymatic processing technology licensing positions before protease engineering patents consolidate among specialty chemical suppliers. Capacity additions in Pacific Northwest rail terminals would preempt Seattle and Portland alternative-dairy startup procurement. Backward integration into identity-preserved seed development in Wisconsin and Minnesota defends margin position against organic certification tier fragmentation. For New Entrants and Emerging Players: White-space service gaps in Pacific Northwest high-solubility isolate supply offer entry points where ADM and Cargill maintain limited direct presence. Underpenetrated demand from Oregon and Washington beverage startups represents the most accessible beachhead. A go-to-market strategy anchored in enzymatic modification tolling services bypasses capital-intensive crushing infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed enzymatic technology licensors holding protease engineering IP portfolios. Five-to-ten-year viability hinges on FDA digestibility scoring guidance crystallizing premium tier definitions. The signal to watch is USDA organic livestock feed regulation expansion pulling organic concentrate into poultry and aquaculture formulations at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Technology Licensing | Protease engineering patents enable premium beverage applications previously dominated by dairy proteins. |
| Identity-Preserved Organic Acreage Expansion | USDA bioengineered disclosure standards force documented seed provenance through Minnesota and Wisconsin elevator networks. |
| Pacific Northwest Distribution Node Buildout | Seattle and Portland rail terminals capture underpenetrated alternative-dairy startup demand outside Midwest strongholds. |
| Direct Crushing Facility Contracting | Bypassing Chicago terminal distributors compresses procurement timelines for national meat-alternative brands. |
| Formulation Chemistry Talent Acquisition | Scarce soy-water interaction expertise in extruded meat analogues commands premium compensation outside Chicago and Minneapolis pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with crushing facility procurement managers, beverage formulation chemists, meat-alternative brand supply chain directors, and USDA organic certification auditors. Secondary validation drew from FDA protein labeling guidance documents, USDA bioengineered food disclosure enforcement records, Chicago Board of Trade soybean meal pricing data, and SEC 10-K filings from publicly traded agribusiness conglomerates. Bottom-up volume estimates from individual facility throughput were triangulated against top-down consumption projections from end-use segment analysis.
Across the analysis window, forecasts were constructed through multi-dimensional segmentation modeling across product type tiers, application reformulation intensity, certification grade requirements, and regional procurement cluster development. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory enforcement timelines. Industry-specific inputs included FDA digestibility scoring guidance evolution, USDA organic livestock feed regulation expansion trajectories, and enzymatic processing technology adoption curves in ready-to-drink beverage formulations.
Forecasts assume regulatory continuity in FDA protein content claims and USDA bioengineered disclosure standards; material policy shifts would require re-modeling of certification tier premiums and identity-preserved sourcing economics. Supply concentration risk among three dominant isolate processors and South American drought-cycle input volatility represent primary forecast revision triggers. Recalibration cycles align with material shifts in FDA plant protein digestibility guidance, USDA organic certification expansion, and enzymatic solubility technology patent expirations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Acacia Gum Market
Ingredients
Arachidonic Acid Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Bouillon Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Mung Bean Starch Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Coconut Flour Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Astragalus Root Extract Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Malted Wheat Flour Market
Ingredients
Non-GMO Soya Market