
 Europe Plant-Based Meal Kit Market | 2026-2036
Europe Plant-Based Meal Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant-Based Meal Kit Market Foresight
Buyer fragmentation across flexitarian households is expanding the addressable base beyond traditional vegan consumers. HelloFresh leverages its logistics infrastructure to control last-mile delivery density in Northern Europe. Gousto competes through recipe personalization algorithms that reduce food waste per shipment. Nestlé S.A. anchors its position with proprietary plant protein formulations developed through sustained R&D spending.
Europe plant-based meal kits are pre-portioned food packages containing plant-derived proteins, fresh produce, and calibrated seasonings designed for home preparation within 15-40 minutes. These kits typically maintain cold-chain integrity through insulated packaging and target reduction of household food waste through precise ingredient scaling. Ready-to-Cook offerings dominate volume due to lower per-unit logistics costs and broader household penetration, while Snack Kits capture premium margins among younger urban demographics seeking convenience without full meal commitment. Biodegradable Packaging segments face margin pressure from EU-wide sustainability mandates even as consumer willingness-to-pay for certified compostable materials strengthens.
EMA food-contact material guidelines, EFSA novel food authorization pathways, and the EU Green Deal carbon labeling requirements collectively shape product formulation and cross-border market access for kit providers. REACH compliance for packaging adhesives and inks adds testing overhead that favors scaled operators with dedicated regulatory affairs teams. Stakeholders must monitor evolving national transpositions of the EU Packaging and Packaging Waste Regulation to anticipate mandatory reuse quotas that could reshape distribution economics.
Market Dynamics
The EU Green Deal and Farm to Fork Strategy are compressing sourcing and packaging compliance timelines for kit providers, forcing rapid adaptation of supply chains and cold-chain infrastructure across Northern and Western Europe.
Growth Catalysts
- EU Green Deal carbon labeling:Mandatory disclosure requirements are creating competitive differentiation for providers with verified low-carbon sourcing, pulling investment into supply chain traceability systems.
- Flexitarian household expansion:Health-conscious urban households in Germany and France are driving volume beyond traditional vegan segments, broadening the addressable base for mid-tier offerings.
- Biodegradable packaging mandates:National transpositions of the EU Packaging and Packaging Waste Regulation are accelerating certified compostable material adoption, favoring operators with dedicated sustainability R&D.
Market Restraints
- REACH compliance overhead:Testing requirements for packaging adhesives and inks impose fixed costs that disadvantage smaller operators lacking dedicated regulatory affairs teams.
- Plant protein input concentration:Sourcing of specialized protein isolates concentrates among a limited supplier base in the Netherlands and Germany, creating vulnerability to price volatility.
- EFSA novel food authorization:Extended approval timelines for emerging protein sources delay product pipeline expansion and compress first-mover advantage windows.
Strategic Opportunities
- Snack Kit segment white space:Younger urban demographics in France seeking convenience without full meal commitment represent an underpenetrated premium margin opportunity.
- Recipe personalization convergence:Integration of algorithmic waste reduction with dynamic dietary preference matching enables subscription stickiness improvements in competitive urban markets.
- Reuse quota preparation:Early investment in returnable packaging infrastructure ahead of mandatory EU reuse quotas creates structural cost advantages for scaled operators.
Industry Challenges
- Cold-chain talent scarcity:Specialized logistics expertise for temperature-controlled last-mile delivery is concentrating among incumbent food distributors, constraining independent kit provider expansion.
- Cross-border formulation complexity:Divergent national transpositions of EMA food-contact material guidelines create product adaptation costs for multi-country operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant-Based Meal Kit Market |
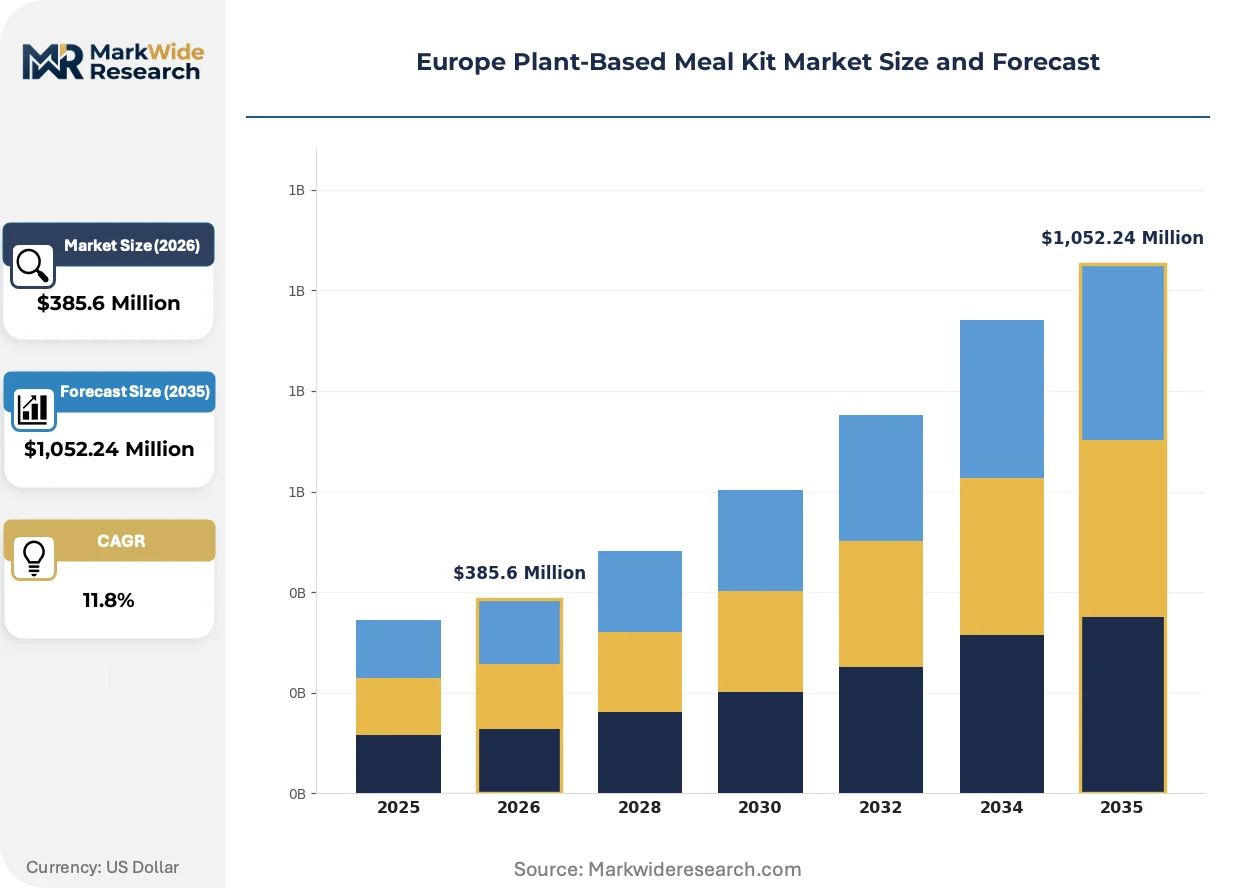
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,052.24 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Cook, Pre-Cooked, Snack Kits, Meal Prep Customer Type: Health Conscious, Vegans, Flexitarians, Busy Professionals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets Packaging Type: Reusable Containers, Biodegradable Packaging, Vacuum Sealed, Paper Bags |
| Companies Covered | Gousto, Beyond Meat Inc., Nestlé S.A., Green Chef, Amy's Kitchen, Inc., HelloFresh, Marley Spoon, Oatly Group AB, Danone S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant-Based Meal Kit Market Shifts & Advancements
Recipe personalization algorithms and sustainable packaging chemistry are compressing operational margins while creating new differentiation vectors for scaled providers across the region.
Precision ingredient scaling technology is automating portion calibration across kit assembly lines. Mid-tier providers in Germany are deploying computer vision systems for real-time weight verification. This automation is compressing labor cost differentials between established operators and emerging entrants.
The EU Green Deal carbon labeling requirements are mandating supply chain emissions disclosure across all packaged food categories. Kit providers must now integrate farm-level data capture into procurement systems. Ready-to-Cook segments face the steepest compliance costs due to ingredient complexity.
Subscription fatigue among urban households is shortening commitment cycles and elevating cancellation risk. Direct-to-consumer channels are losing ground to grocery retail partnerships in France and the Netherlands. This channel rotation is most visible among younger demographics seeking trial flexibility without upfront payment obligation.
Europe Plant-Based Meal Kit Market Segmentation
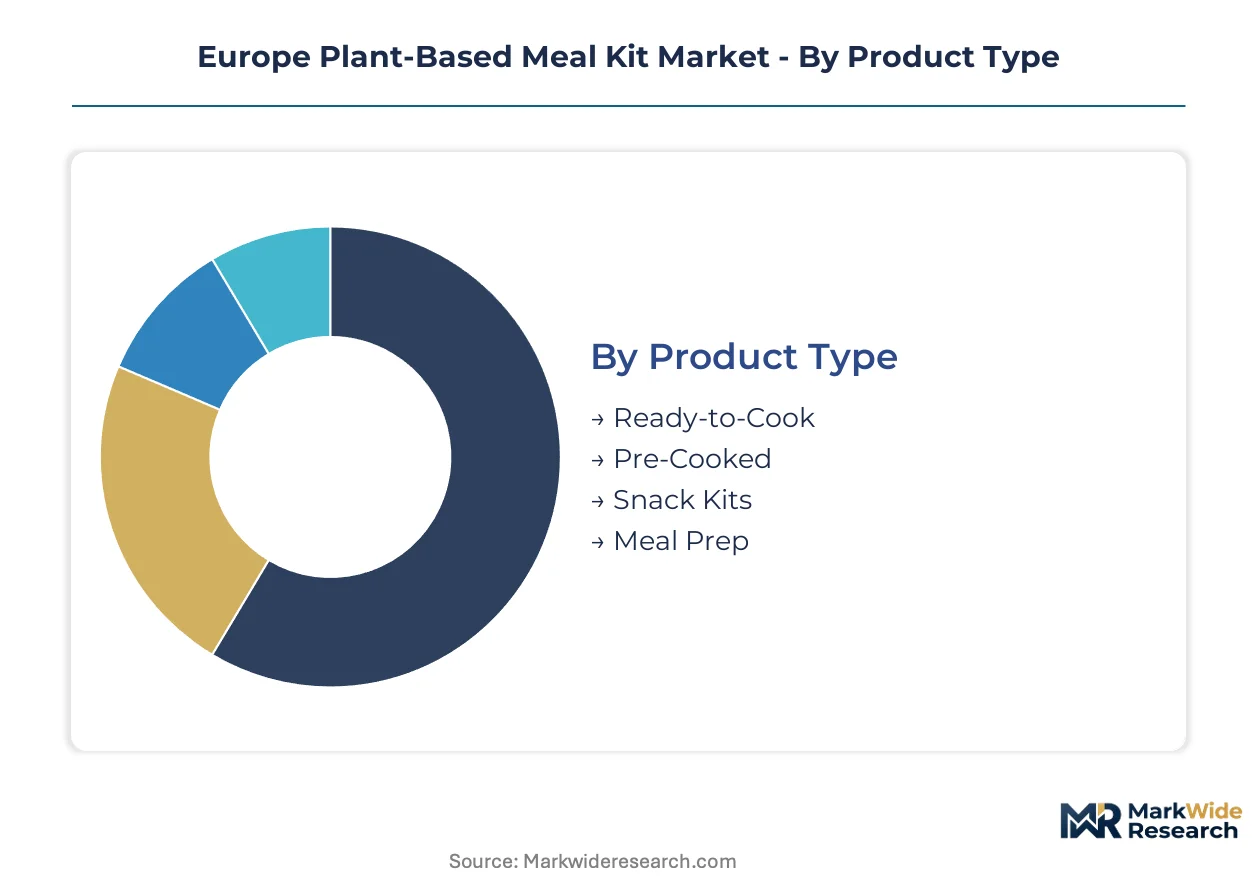
Segmentation in the Europe plant-based meal kit market reveals divergent capital requirements across production formats and customer acquisition strategies. Kit providers must align infrastructure investments with the specific technical and regulatory demands of each segment.
Product Type:
Capital intensity varies sharply across production formats, with cold-chain infrastructure and perishability management driving upfront investment requirements.
- Ready-to-Cook:These kits contain raw plant proteins, fresh produce, and calibrated seasonings requiring continuous cold-chain integrity from assembly through last-mile delivery. Demand concentrates among health-conscious urban households in Germany, where subscription density justifies dedicated fulfillment center investments. EFSA novel food authorization timelines for emerging protein sources compress product pipeline velocity for this segment.
- Pre-Cooked:Shelf-stable or refrigerated prepared meals demand retort or modified atmosphere packaging infrastructure alongside HACCP-certified production facilities. Flexitarian households in France favor this format for weekday convenience, though EU Green Deal carbon labeling requirements impose supply chain traceability costs that favor scaled operators with farm-level data capture systems.
- Snack Kits:Smaller-portion offerings targeting younger urban demographics seeking convenience without full meal commitment.
- Meal Prep:Bulk ingredient packages designed for multi-portion cooking sessions, appealing to time-optimized households.
Ready-to-Cook absorbs the bulk of installed capacity; Snack Kits are expanding most quickly.
Customer Type:
Customer acquisition economics differ substantially across dietary commitment levels, with flexitarian segments demanding broader recipe variety and higher churn management costs.
- Health Conscious:These buyers prioritize nutritional transparency and ingredient provenance over price sensitivity, driving demand for organic certification and supply chain disclosure. Urban households in the Netherlands concentrate here, with EMA food-contact material compliance for premium packaging tiers adding margin pressure.
- Flexitarians:The largest addressable base, these consumers alternate between plant-based and conventional proteins, requiring recipe personalization algorithms to maintain engagement. German cities show highest subscription density, though cancellation risk elevates customer lifetime value uncertainty.
- Vegans:Committed plant-based consumers with established brand loyalty and lower price elasticity.
- Busy Professionals:Time-constrained urban workers prioritizing preparation speed and delivery reliability over customization depth.
Flexitarians command the largest marketing spend allocation; Health Conscious delivers the highest per-subscription margins.
Distribution Channel:
Channel selection determines working capital intensity, with direct-to-consumer models requiring inventory risk absorption that retail partnerships transfer to grocery operators.
- Online Retail:Subscription-based direct sales demand proprietary logistics infrastructure or third-party cold-chain partnerships, with last-mile delivery density in Northern Europe determining unit economics. REACH compliance for packaging adhesives and inks adds fixed testing overhead that disadvantages smaller entrants lacking dedicated regulatory affairs teams.
- Supermarkets:Brick-and-mortar retail partnerships shift inventory risk to grocery chains while compressing margins through slotting fees and promotional fund requirements. French and Dutch grocery retailers are expanding dedicated plant-based sections, creating shelf space competition.
- Specialty Stores:Curated retail environments targeting premium positioning and educated consumer bases.
- Farmers' Markets:Localized direct sales with minimal packaging compliance burden but limited scalability.
Online Retail retains the highest revenue concentration; Supermarkets are gaining share fastest.
Packaging Type:
Sustainability R&D spending varies dramatically across material categories, with EU regulatory timelines forcing accelerated investment in certified compostable solutions.
- Biodegradable Packaging:Certified compostable materials face margin pressure from EU-wide sustainability mandates even as consumer willingness-to-pay strengthens. National transpositions of the EU Packaging and Packaging Waste Regulation are accelerating adoption, favoring operators with dedicated sustainability chemistry teams.
- Reusable Containers:Returnable packaging infrastructure requires reverse logistics systems and deposit management, with early investment ahead of mandatory EU reuse quotas creating structural cost advantages for scaled operators.
- Vacuum Sealed:Extended shelf-life technology reducing spoilage rates in cold-chain distribution.
- Paper Bags:Lower-cost conventional packaging with limited barrier properties suitable for dry ingredients only.
Biodegradable Packaging captures the dominant sustainability investment flow; Reusable Containers show the steepest regulatory-driven expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based plant protein isolate suppliers anchor upstream sourcing for European kit providers, with Rotterdam and Amsterdam logistics hubs enabling cold-chain distribution density across Northern Europe.
Germany
Health-conscious urban households in Berlin and Munich drive subscription volume for Ready-to-Cook formats. The country's national packaging regulator enforces strict transpositions of EU Packaging and Packaging Waste Regulation reuse quotas. Bavaria's food-tech cluster around Munich hosts multiple kit assembly facilities upgrading to precision ingredient scaling automation.
France
Flexitarian households in Paris and Lyon favor Pre-Cooked weekday convenience offerings. ANSM food-contact material guidelines create formulation adaptation costs for cross-border operators. The Île-de-France region concentrates demand for Snack Kits among younger urban demographics seeking trial flexibility.
Netherlands
Amsterdam and Rotterdam households show highest per-capita adoption of biodegradable packaging tiers. ECHA REACH compliance for packaging adhesives favors scaled operators with dedicated regulatory affairs teams. The Randstad logistics corridor enables last-mile delivery density that compresses unit economics for subscription models.
United Kingdom
London and Southeast England concentrate Health Conscious buyer segments prioritizing organic certification. EFSA novel food authorization pathways delay product pipeline expansion for emerging protein sources. The Midlands hosts cold-chain fulfillment infrastructure serving Northern European export routes.
Sweden
Stockholm and Gothenburg urban households demonstrate strong willingness-to-pay for certified compostable packaging materials. The country's environmental protection agency accelerates national transpositions of EU Green Deal carbon labeling requirements. Southern Sweden's food processing cluster invests in returnable packaging infrastructure ahead of mandatory reuse quotas.
Europe Plant-Based Meal Kit Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithmic personalization and sustainable packaging chemistry as differentiation vectors. The vendor base spans three maturity tiers: multinational food conglomerates with captive R&D pipelines, mid-cap specialists with regional logistics density, and venture-backed entrants targeting niche dietary segments. Two dominant competitive moves define current positioning: backward integration into proprietary plant protein formulations, and strategic partnerships with grocery retailers to offset direct-to-consumer subscription fatigue.
Within the multinational tier, Nestlé S.A. and Danone S.A. exemplify scale-driven operators leveraging sustained R&D spending for proprietary ingredient development. HelloFresh occupies a position representing logistics infrastructure dominance, with Northern European fulfillment density creating structural cost advantages. Among specialized entrants, Gousto exemplifies the algorithmic personalization archetype, while Beyond Meat Inc. anchors the alternative protein supplier category even as kit providers diversify sourcing. These three named entities represent distinct strategic postures without exhausting the competitive map.
| Leading Market Players |
|---|
| Gousto |
| Beyond Meat Inc. |
| Nestlé S.A. |
| Green Chef |
| Amy's Kitchen, Inc. |
| HelloFresh |
| Marley Spoon |
| Oatly Group AB |
| Danone S.A. |
| Others |
Supply & Pricing Matrix
Venture-backed specialists rolled up by private equity firms dominate mid-tier positioning, compressing margin discipline through scale-driven procurement while EU Green Deal compliance costs create tiered pricing separation between certified and conventional kit providers.
Pricing Analysis
Volume concentrates in Ready-to-Cook subscription tiers while Snack Kits capture premium margins. Three-tier pricing structure across premium organic certification, standard flexitarian, and economy trial-entry levels separates buyer segments. Price differentiation hinges on biodegradable packaging certification and algorithmic personalization depth. Cost compression in standard tiers intensifies because REACH compliance overhead disadvantages smaller operators lacking regulatory affairs teams. Flexitarian households in Germany show lowest price elasticity; trial-seeking younger demographics in France exhibit highest sensitivity.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Germany, and France anchor hub-and-spoke cold-chain patterns across Northern Europe. Plant protein isolates concentrate among Dutch and German suppliers. Specialized packaging adhesives and insulated liners draw from limited REACH-certified producers. Single-source vulnerability in novel protein authorization creates pipeline risk for emerging entrants. Distribution runs through dedicated fulfillment centers serving subscription density zones, with grocery retail partnerships expanding as secondary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon labeling mandates function as a cost-of-compliance moat, elevating capital requirements for supply chain traceability systems that scaled incumbents absorb more efficiently than emerging entrants.
For Market Incumbents: Deploy returnable packaging infrastructure ahead of mandatory reuse quotas to lock in structural cost advantages. Consolidate backward integration into proprietary plant protein formulations to reduce exposure to Dutch-German supplier concentration. Channel control through grocery retail partnerships offsets direct-to-consumer subscription fatigue in France and the Netherlands. For New Entrants and Emerging Players: Launch via Snack Kit white space in French urban markets where trial flexibility commands premium positioning without full logistics infrastructure. Target algorithmic recipe personalization as the most penetrable differentiation vector against established operators. Pursue specialty retail partnerships in the Netherlands to bypass cold-chain density requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with dedicated sustainability R&D teams in Germany and Sweden over capital-constrained venture-backed entrants. Long-term viability across the projection horizon rests on regulatory compliance capability rather than pure growth velocity. Watch EFSA novel food authorization timelines as the critical inflection signal for protein source diversification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Protein | Reduces dependency on Dutch-German isolate suppliers facing price volatility. |
| Returnable Packaging Infrastructure Buildout | Creates structural cost advantage ahead of EU Packaging and Packaging Waste Regulation reuse quotas. |
| Recipe Personalization Algorithm Investment | Reduces food waste per shipment while elevating subscription stickiness in competitive German urban markets. |
| Grocery Retail Channel Expansion | Transfers inventory risk to French and Dutch chains while capturing trial-flexible younger demographics. |
| Biodegradable Packaging Certification | Aligns with EU Green Deal mandates while capturing willingness-to-pay premiums in Amsterdam and Stockholm. |
Research Methodology
Multi-period observation of subscription cancellation rates, packaging compliance cost trajectories, and protein source authorization timelines anchored the trend analysis, supplemented by interviews with kit operations directors, cold-chain logistics managers, regulatory affairs specialists at EFSA, and grocery category buyers. Secondary validation drew from EU Packaging and Packaging Waste Regulation national transposition documents, EFSA novel food authorization databases, ECHA REACH compliance registries, and trade flow data for plant protein isolates. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices modeled volume and value across product type, customer dietary commitment level, distribution channel, and packaging sustainability tier throughout the forecast period. CAGRs derived from segment-level growth rate convergence analysis. Industry-specific forecast inputs included EMA food-contact material guideline adaptation costs and cold-chain labor scarcity indices.
EFSA authorization delays, national packaging regulation transposition timing, and flexitarian household churn spikes are the dominant revision risks warranting forecast sensitivity analysis. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Black Rice Protein Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market