
 Plant-Based Margarine Market | 2026-2036
Plant-Based Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Margarine Market Insights
The capital-intensity gap between multinational oil processors and artisanal plant-based specialists is collapsing as enzymatic interesterification equipment becomes more accessible at smaller scale. Unilever leverages its oleochemical infrastructure and global procurement networks to maintain cost parity across multiple geographies. Miyoko's Creamery differentiates through fermentation-derived cultured fats that command premium positioning in specialty retail channels. Upfield Holdings B.V. dominates European private-label supply through dedicated plant-based production facilities and long-term retail partnerships.
Plant-based margarine denotes a water-in-oil emulsion containing minimum 80% fat, formulated from refined vegetable oils through hydrogenation or enzymatic interesterification, with lecithin emulsifiers and citric acid preservatives ensuring oxidative stability during industrial baking cycles. Soybean oil-based formulations anchor commodity volume in North American food manufacturing due to established crushing infrastructure and price transparency, while nut-based variants occupy the fastest-expanding margin pool as almond and cashew butter blends penetrate premium bakery and patisserie channels. Olive oil-based spreads sustain Mediterranean market loyalty through cardiovascular health positioning, though coconut oil-based alternatives are displacing them in clean-label frozen dough applications where saturated fat functionality mimics butter more closely.
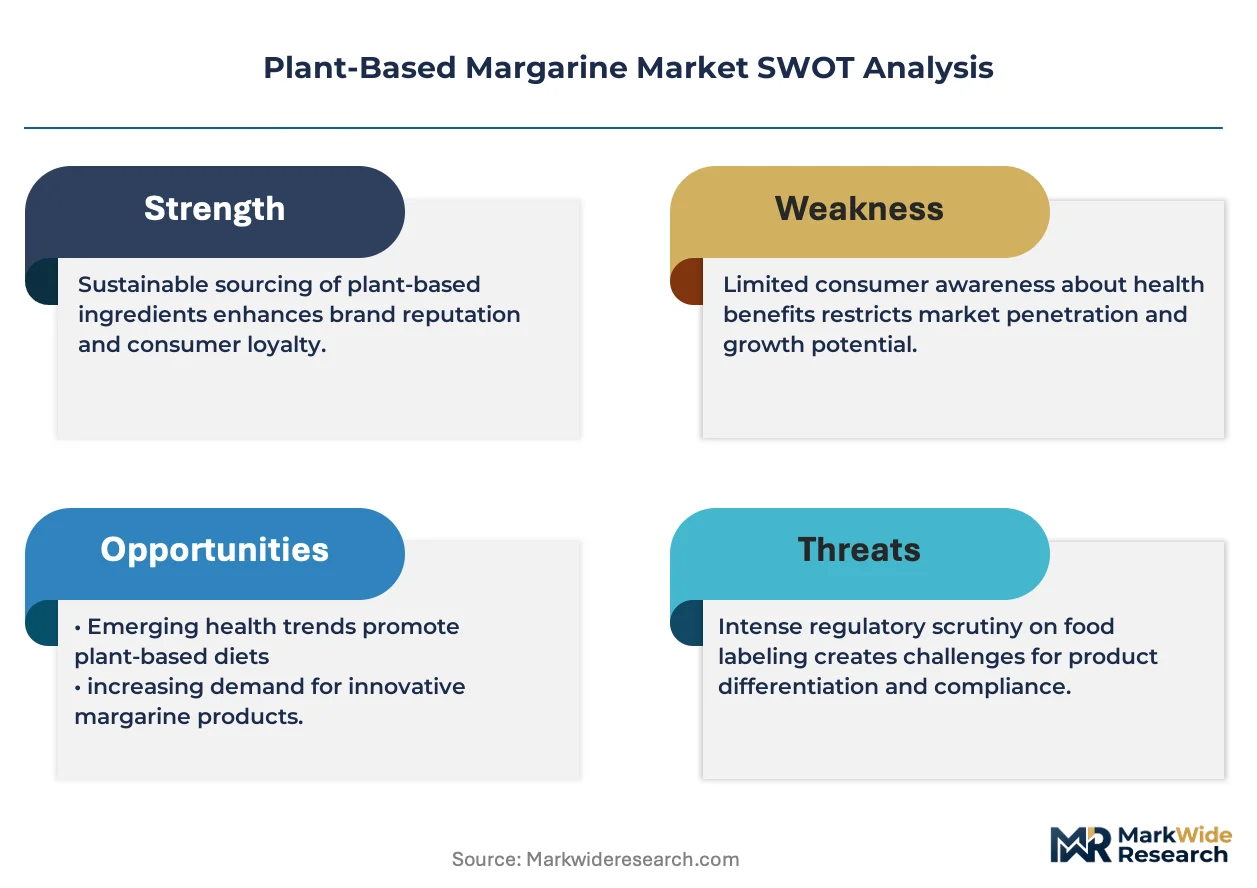
The FDA's updated definition of "healthy" nutrient content claims now encompasses plant-based spreads meeting specific unsaturated fat thresholds, directly expanding permissible marketing language for qualifying formulations. EFSA novel food assessments govern entry of emerging fermented fat technologies into European commerce, creating compliance timelines that favor established players with dedicated regulatory affairs capacity. REACH chemical safety registrations for emulsifier additives determine which suppliers can participate in EU-manufactured product lines. Stakeholders must monitor evolving front-of-pack labeling mandates across multiple jurisdictions, as interpretive warnings on ultra-processed foods could reclassify margarine regardless of plant origin.
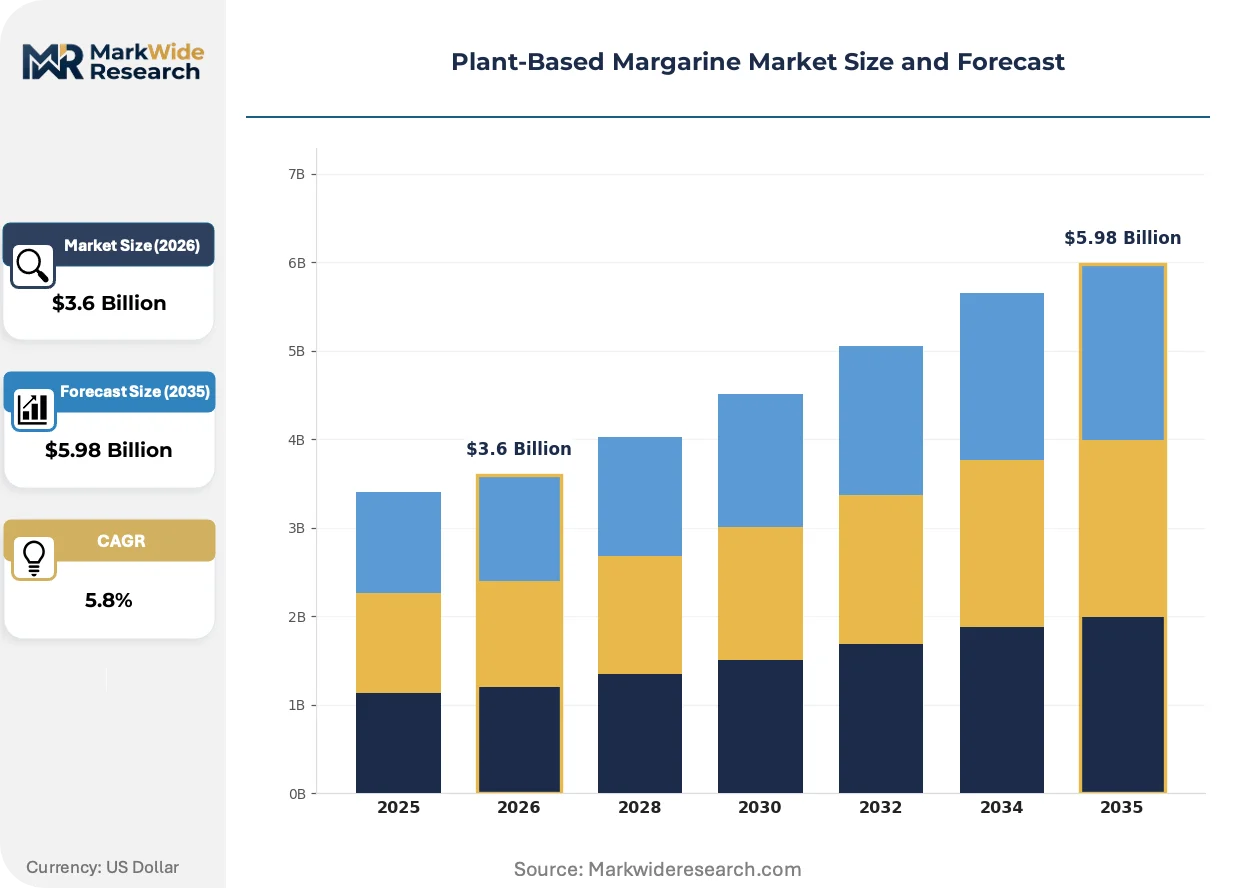
Market Dynamics
Enzymatic interesterification is collapsing the minimum efficient scale for fat modification, eroding the capital moat that historically separated multinational oil processors from artisanal entrants and redistributing competitive leverage toward formulation agility.
Growth Catalysts
- EU Green Deal deforestation-free mandates:Supply chain certification requirements are redirecting procurement toward certified palm-free oil blends, creating preferential market access for compliant suppliers.
- Bakery chain reformulation programs:Industrial baking operations are systematically replacing dairy fats with plant-based emulsions to meet vegan-menu mandates and reduce ingredient cost volatility.
- Germany retail private-label expansion:Discounter and supermarket chains are accelerating volume uptake through dedicated plant-based margarine SKUs and streamlined supplier qualification.
Market Restraints
- Soybean oil price transparency infrastructure:Commodity futures markets expose formulations to input cost volatility that premium-positioned alternatives cannot fully hedge.
- EFSA novel food assessment timelines:Fermented fat technologies face extended compliance windows that favor established players with dedicated regulatory affairs capacity.
- Butter functionality in laminated dough:Saturated fat crystallization properties in clean-label frozen applications resist full displacement by unsaturated plant-based alternatives.
Strategic Opportunities
- Almond and cashew butter premium channels:Nut-based variants are penetrating patisserie and specialty bakery segments where margin pools expand fastest.
- FDA "healthy" nutrient content claim expansion:Updated thresholds for unsaturated fat now permit expanded marketing language for qualifying formulations.
- Fermentation-derived cultured fat convergence:Precision fermentation and enzymatic modification are combining to replicate dairy mouthfeel without hydrogenation.
Industry Challenges
- REACH emulsifier registration gaps:Chemical safety documentation requirements for lecithin and citric acid derivatives are excluding smaller suppliers from EU-manufactured product lines.
- Front-of-pack labeling fragmentation:Interpretive warnings on ultra-processed foods are proliferating across jurisdictions with inconsistent criteria that could reclassify margarine regardless of plant origin.
- Oxidative stability formulation expertise:Industrial baking cycle requirements demand specialized knowledge in antioxidant synergies that outpaces available technical talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Margarine Market |
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil-Based, Coconut Oil-Based, Soybean Oil-Based, Nut-Based Application: Baking, Spreading, Cooking, Food Service Packaging Type: Tubs, Sticks, Pouches, Sachets Customer Type: Retail Consumers, Food Manufacturers, Restaurants, Bakeries |
| Companies Covered | Unilever, Upfield Holdings B.V., Conagra Brands, Bunge Limited, Wilmar International Ltd, Miyoko’s Creamery, Puratos, FUJI OIL HOLDINGS INC., Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Margarine Market Trends and Innovations
Formulation science is converging with bioprocessing to compress development cycles, while regulatory frameworks and procurement models are simultaneously rewriting competitive rules.
Precision fermentation platforms are generating lipid structures that replicate butter crystallization behavior without hydrogenation. Artisanal producers and contract manufacturers are adopting these systems within eighteen-month equipment payback periods. The technology is miniaturizing production footprints from industrial-scale refineries to regional bioreactor facilities.
EFSA novel food assessments now govern entry of all emerging fermented fat technologies into European commerce. Compliance documentation requirements are extending market entry timelines by twelve to twenty-four months relative to conventional oil blends. Specialty retail channels with established regulatory affairs teams are capturing first-mover positioning in cultured fat segments.
Clean-label frozen dough specifications are pivoting procurement criteria from cardiovascular health claims to saturated fat functionality. Coconut oil-based spreads are displacing olive oil variants in industrial formulations where crystallization speed determines production line throughput. Mediterranean retail markets remain loyal to olive oil positioning, creating geographic divergence in formulation preference.
Plant-Based Margarine Market Segmentation
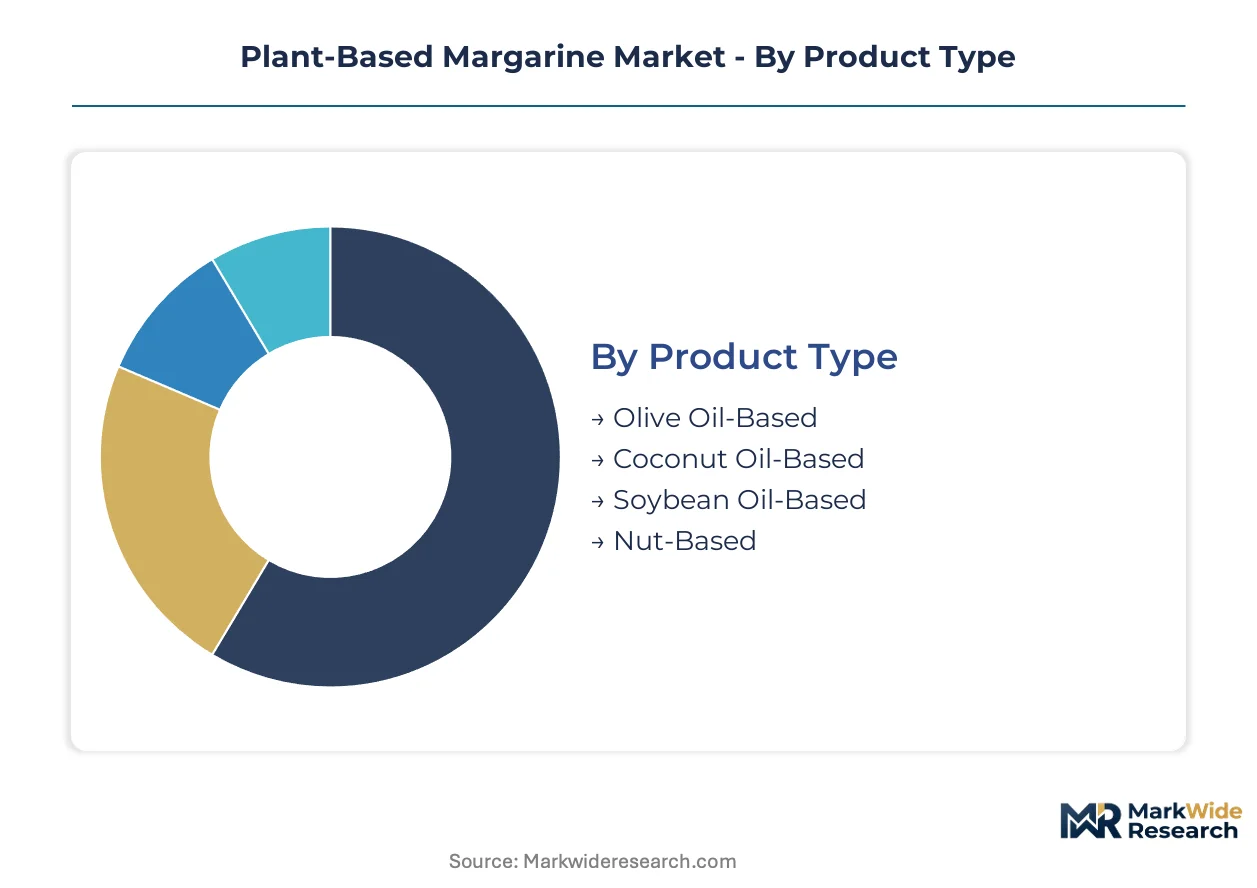
Plant-based margarine formulation and distribution fragment across four distinct dimensions, each carrying divergent margin structures and procurement logics. Product type determines raw material exposure and certification complexity, while application and customer type dictate packaging specifications and shelf-life requirements.
Product Type:
Premium positioning concentrates in nut-derived and specialty oil variants where supply scarcity and clean-label certification sustain price elevation.
- Soybean Oil-Based:These formulations anchor commodity volume through established crushing infrastructure and price transparency in futures markets. Industrial baking operations in Germany and the United States absorb the majority of volume, though margin compression from input cost volatility limits producer profitability.
- Nut-Based:Almond and cashew butter blends command the steepest price premiums through patisserie and specialty retail channels. Clean-label frozen dough manufacturers in France and artisanal bakeries across Northern Europe are driving fastest uptake as saturated fat functionality requirements intensify.
- Olive Oil-Based:Mediterranean retail markets sustain loyalty through cardiovascular health positioning, with EFSA health claim registrations supporting permissible marketing language.
- Coconut Oil-Based:Saturated fat crystallization properties are displacing olive variants in industrial applications where production line throughput depends on rapid solidification.
The dominant share belongs to Soybean Oil-Based, while Nut-Based is closing the gap fastest.
Application:
Volume concentration follows industrial procurement scale, though margin expansion tracks toward specialized end-uses with technical specification barriers.
- Baking:Laminated dough and frozen pastry applications require precise crystallization behavior that unsaturated plant fats struggle to replicate. Bakery chain reformulation programs across Germany and Austria are systematically replacing dairy fats, creating dedicated supplier qualification pipelines.
- Food Service:Vegan-menu mandates from contract caterers and institutional kitchens are generating bulk procurement contracts with eighteen-month volume commitments. The segment demands oxidative stability across extended holding temperatures, favoring suppliers with antioxidant formulation expertise.
- Spreading:Retail tabletop consumption competes directly with butter on taste and mouthfeel, pressuring producers toward fermentation-derived cultured fat investments.
- Cooking:High-heat stability requirements favor interesterified blends with elevated saturated fat content, creating formulation overlap with baking applications.
Baking captures the largest volume commitment, while Food Service is expanding most quickly.
Packaging Type:
Format selection directly determines distribution channel access and shelf-life extension capabilities across divergent retail environments.
- Tubs:Dominant format for retail spreading applications with resealability and portion control features. German discounters and supermarket chains are accelerating private-label expansion through dedicated tub SKUs with streamlined supplier qualification.
- Sticks:Butter-analogue format preferred by traditionalist consumers and precise measurement requirements in home baking. North American retail maintains stronger stick preference than European markets.
- Pouches:Food service bulk dispensing and industrial manufacturing inputs favor flexible packaging for cost efficiency and storage density.
- Sachets:Single-serve hospitality and airline catering applications command premium unit economics despite lower absolute volume.
Tubs hold the installed base advantage, though Pouches are climbing the fastest through food service channel consolidation.
Customer Type:
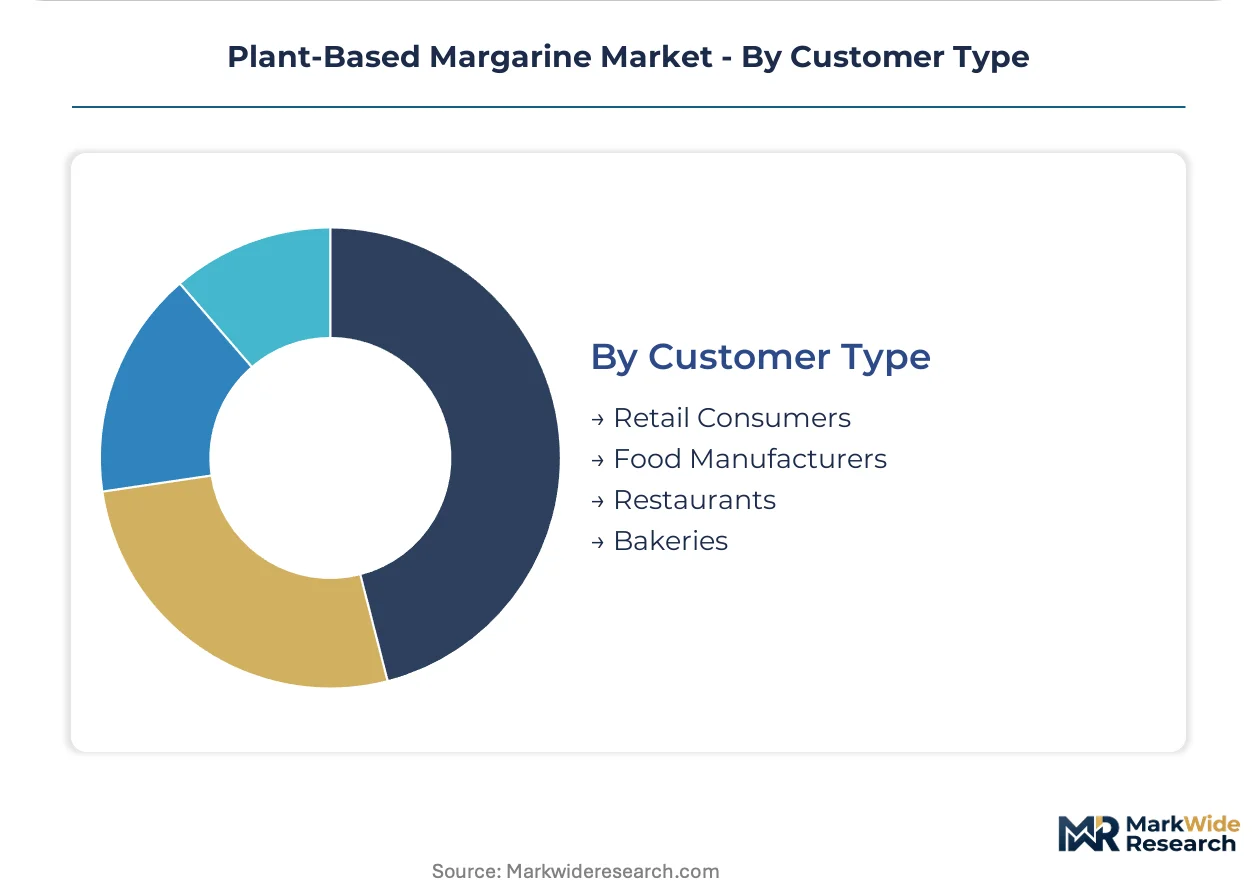
Procurement sophistication and specification stringency vary dramatically across customer categories, fragmenting supplier competitive requirements.
- Food Manufacturers:Industrial-scale buyers impose stringent oxidative stability and crystallization specifications with multi-year supply agreements. REACH emulsifier registration requirements are excluding smaller suppliers from EU-manufactured product lines serving this segment.
- Retail Consumers:Front-of-pack labeling sensitivity and ultra-processed food warnings are reclassifying purchase criteria regardless of plant origin. FDA "healthy" nutrient content claim thresholds now permit expanded marketing language for qualifying formulations.
- Restaurants:Menu cost pressures and vegan mandate compliance are driving spot purchasing with limited formulation loyalty.
- Bakeries:Artisanal and industrial sub-segments diverge sharply, with the former prioritizing fermentation-derived cultured fats and the latter optimizing for production line throughput.
Food Manufacturers command the deepest supplier relationships, while Retail Consumers are shifting purchase criteria most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands substantial premiums over commodity benchmarks in the United States, reflecting divergent regulatory stringency and private-label procurement sophistication across the Atlantic.
Germany
Retail private-label expansion and foodservice vegan-menu mandates concentrate volume uptake in discounter and supermarket chains. The EU Green Deal's deforestation-free supply chain requirements redirect sourcing toward certified palm-free oil blends. Industrial bakery clusters in Bavaria and North Rhine-Westphalia drive reformulation programs replacing dairy fats with plant-based emulsions.
United States
Soybean oil-based formulations anchor commodity volume through established crushing infrastructure and futures market price transparency. The FDA's updated "healthy" nutrient content claim definition expands permissible marketing language for qualifying unsaturated fat formulations. Chicago and Minneapolis-St. Paul processing corridors absorb the majority of industrial baking demand.
France
Patisserie and specialty bakery channels sustain premium positioning for nut-based almond and cashew butter blends. EFSA health claim registrations govern permissible cardiovascular positioning for olive oil-based spreads. Artisanal baking concentrations in Île-de-France and Auvergne-Rhône-Alpes prioritize fermentation-derived cultured fats for mouthfeel replication.
Netherlands
Private-label supply dominance leverages dedicated plant-based production facilities and long-term retail partnerships across the Randstad corridor. REACH chemical safety registrations for emulsifier additives determine supplier participation in EU-manufactured product lines. Rotterdam's oleochemical infrastructure supports cost parity maintenance across multiple geographies.
Japan
Clean-label frozen dough specifications pivot procurement toward coconut oil-based spreads where saturated fat functionality mimics butter crystallization. METI standards and novel food assessment frameworks extend compliance timelines for fermented fat technologies. Industrial baking concentrations in the Nagoya-Chubu corridor optimize production line throughput with rapid solidification requirements.
Plant-Based Margarine Market Competitive Landscape
Concentration sits with multinational oil processors leveraging global procurement networks and oleochemical infrastructure to maintain cost parity. The vendor base spans three tiers: diversified conglomerates with integrated crushing-to-retail capabilities, dedicated plant-based specialists exploiting enzymatic interesterification accessibility, and regional private-label suppliers anchored by retail partnerships. Dominant competitive moves include backward integration into certified palm-free oil sourcing and technology licensing agreements for precision fermentation platforms.
Within the diversified conglomerate tier, Unilever and Bunge Limited exemplify scale-driven positioning through established crushing infrastructure and futures market hedging capabilities. Upfield Holdings B.V. occupies a distinct private-label supply position, while Miyoko's Creamery represents the specialist archetype commanding premium positioning through fermentation-derived cultured fat differentiation.
| Leading Market Players |
|---|
| Unilever |
| Upfield Holdings B.V. |
| Conagra Brands |
| Bunge Limited |
| Wilmar International Ltd |
| Miyoko's Creamery |
| Puratos |
| FUJI OIL HOLDINGS INC. |
| Kerry Group plc |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day inventory cycles for enzymatic interesterification equipment compress capital barriers between multinational processors and artisanal entrants, redistributing pricing power toward formulation agility rather than scale economics. This lead-time compression tightens margins in commodity soybean oil tiers while expanding premium capture for certified palm-free and fermentation-derived cultured fat variants.
Pricing Analysis
The customization-premium spread between standard commodity formulations and configured-to-order cultured fat variants spans three distinct tiers: premium nut-based and fermentation-derived products, standard interesterified blends, and economy soybean oil anchors. Price differentiation hinges on clean-label certification grade and volume scale, with EFSA novel food registration status commanding substantial premia in European channels. Cost compression in the economy tier is intensifying as futures market transparency exposes formulations to input volatility. Food manufacturers exhibit the highest price sensitivity due to procurement scale, while patisserie and specialty retail channels absorb premium positioning with limited elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate industrial baking procurement, though strategic stockpiling of certified palm-free oil blends is emerging among EU Green Deal-compliant suppliers. Raw material sourcing concentrates in Indonesia and Malaysia for conventional palm derivatives, the United States and Brazil for soybean crushing infrastructure, and Southern Europe for olive oil inputs. The supply chain draws from single-source vulnerability in novel fermentation-derived lipid platforms, where precision fermentation capacity remains concentrated among limited contract manufacturers. Distribution runs through Rotterdam's oleochemical hub for European private-label supply, with regional bioreactor facilities displacing centralized refinery models for cultured fat segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across formulation technology, certification standards, and channel access creates multiple entry points for differentiated positioning. Bakery chain vegan-menu mandates and clean-label frozen dough specifications are splintering demand into specialty niches that reward agility over scale.
For Market Incumbents: Consolidate backward integration into certified palm-free oil sourcing to secure EU Green Deal compliance ahead of deforestation-free enforcement deadlines. Capture fermentation technology licensing agreements to neutralize Miyoko's Creamery and precision fermentation entrants threatening premium positioning. Channel control through dedicated plant-based production facilities remains the critical defensive lever against private-label erosion.
For New Entrants and Emerging Players: Lead with almond and cashew butter formulations targeting France's patisserie channels and Germany's artisanal bakery clusters, where saturated fat functionality requirements outpace incumbent R&D cycles. The most penetrable white space sits in clean-label frozen dough applications displacing coconut oil variants with improved crystallization behavior. A direct-to-specialty-retail go-to-market angle bypasses incumbent-dominated food manufacturer procurement pipelines.
For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because enzymatic interesterification accessibility is collapsing capital moats and redistributing returns toward formulation IP rather than asset ownership. Target acquisition profiles center on regional bioreactor operators with EFSA regulatory affairs capacity and established cultured fat compliance documentation. The signal to watch is front-of-pack labeling mandate proliferation across multiple jurisdictions, which could reclassify margarine regardless of plant origin and trigger portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Palm-Free Sourcing | EU Green Deal deforestation-free requirements redirect procurement toward compliant suppliers with preferential market access. |
| Precision Fermentation Platform Licensing | EFSA novel food assessment timelines favor established players with dedicated regulatory affairs capacity in cultured fat segments. |
| Private-Label Supply Partnership Expansion | German discounter and supermarket chains accelerate volume uptake through dedicated plant-based margarine SKU expansion. |
| Clean-Label Frozen Dough Formulation Development | Bakery chain reformulation programs in Bavaria and North Rhine-Westphalia systematically replace dairy fats with plant-based emulsions. |
| Regional Bioreactor Facility Deployment | Miniaturized production footprints from industrial-scale refineries to regional facilities compress equipment payback periods for artisanal entrants. |
Research Methodology
Cross-validation between executive interviews at enzymatic interesterification equipment manufacturers and secondary validation through EU customs trade data anchors the qualitative findings in observable procurement patterns. Primary fieldwork engaged plant managers at crushing facilities, procurement leads at German bakery chains, regulatory affairs directors navigating EFSA novel food pathways, and category buyers at Netherlands-based private-label suppliers. Secondary sources included FDA nutrient content claim filings, REACH chemical safety registration databases, EU Green Deal implementation guidance, and SEC disclosures from listed oil processors. Bottom-up volume builds from application-level consumption data triangulate against top-down macroeconomic elasticity assumptions.
Sensitivity analysis around input cost volatility and regulatory compliance timeline extensions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, packaging format, and customer procurement sophistication tier. CAGRs derive from elasticity-adjusted volume trajectories incorporating bakery chain reformulation program commitments and foodservice vegan-menu mandate adoption curves. Industry-specific forecast inputs encompass soybean futures market transparency effects and precision fermentation capacity buildout schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated FDA "healthy" claim threshold adoption would require recalibration. Forecasts reflect documented assumptions regarding enzymatic equipment cost curves and fermentation-derived fat technology maturation. Revision becomes warranted when front-of-pack labeling mandate proliferation crosses jurisdictional thresholds that reclassify margarine regardless of plant origin.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market