
 Plant Based Breads Market | 2026-2036
Plant Based Breads Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Breads Market Analytics
Ingredient sourcing margin is narrowing as commodity wheat costs compress value capture upstream. Dave's Killer Bread leverages organic supply chains to sustain premium positioning in North American retail. Silver Hills Bakery anchors its growth on sprouted grain technology leadership, while Food for Life Baking Company differentiates through Ezekiel Bread's biblical formula heritage and dense nutritional profile.
Plant based breads are bakery products formulated without animal-derived inputs, typically employing water, plant oils, leavening agents, and protein-enriched flours such as pea or almond to achieve structural integrity comparable to conventional loaves. Their primary commercial purpose centers on serving allergen-sensitive consumers, ethical dietary adherents, and institutional food programs requiring scalable vegan-compliant menus. Gluten-free formats now command the fastest expansion within product type segmentation as celiac diagnoses and self-directed wheat avoidance multiply across developed markets. Pea protein as an ingredient source is gaining traction for its functional binding properties and complete amino acid profile, while online retail distribution channels are capturing disproportionate growth velocity through subscription models and direct-to-consumer health branding.
FDA labeling standards for gluten-free claims and USDA organic certification requirements shape product development and market access thresholds for domestic manufacturers. EFSA allergen disclosure mandates and EU Green Deal agricultural transition targets are redirecting European sourcing toward regenerative grain programs and reduced-input cultivation. Stakeholders must monitor evolving protein fortification regulations and carbon accounting methodologies as these frameworks increasingly determine which formulations qualify for preferential retail placement and institutional procurement contracts.
Market Dynamics
Clean-label disclosure mandates from EFSA are compressing formulation flexibility across European supply chains, forcing manufacturers to rebuild recipes around shorter ingredient decks while maintaining structural integrity in high-moisture plant-based loaves.
Growth Catalysts
- EFSA Additive Disclosure Tightening:European manufacturers reformulating to preempt regulatory scrutiny are accelerating adoption of natural emulsifiers and fermented wheat proteins as clean-label alternatives to conventional dough conditioners.
- Specialty Food Service Procurement:Institutional buyers in healthcare and education sectors are mandating vegan-compliant bread SKUs for menu standardization, creating contracted volume pipelines that de-risk production planning for mid-scale bakeries.
- Pea Protein Functional Binding:The amino acid completeness and water-holding capacity of pea protein isolates are displacing soy and wheat gluten in premium formulations targeting athletic and aging consumer segments.
Market Restraints
- Commodity Wheat Cost Compression:Upstream margin capture is narrowing as global wheat futures volatility squeezes value-add differentiation for plant-based brands dependent on conventional flour bases.
- Regenerative Grain Supply Concentration:European sourcing for EU Green Deal compliance is concentrating among a limited cohort of regenerative-certified farms, creating bottleneck risk for clean-label procurement commitments.
- Gluten-Free Structural Limitations:The absence of wheat protein networks in celiac-targeted formulations requires expensive hydrocolloid and enzyme systems that degrade shelf stability and raise unit economics.
Strategic Opportunities
- Subscription Direct-to-Consumer Channels:Online retail platforms with recurring delivery models are capturing disproportionate growth velocity through health branding and personalized nutrition bundling.
- Functional Bakery Format Expansion:German consumer demand for protein-fortified and gut-health-positioned loaves is creating white space for fermented grain and sprouted wheat innovations.
- USDA Organic Certification Tailwinds:Premium retail placement algorithms increasingly weight organic certification, rewarding brands with captive organic supply chains and multi-year transition planning.
Industry Challenges
- Protein Fortification Regulatory Navigation:Evolving FDA thresholds for nutrient content claims require reformulation cycles that strain R&D bandwidth and delay product launches.
- Carbon Accounting Methodology Integration:Emerging institutional procurement standards for Scope 3 emissions tracking demand supply chain visibility that legacy bakery ERP systems cannot deliver without capital-intensive upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Breads Market |
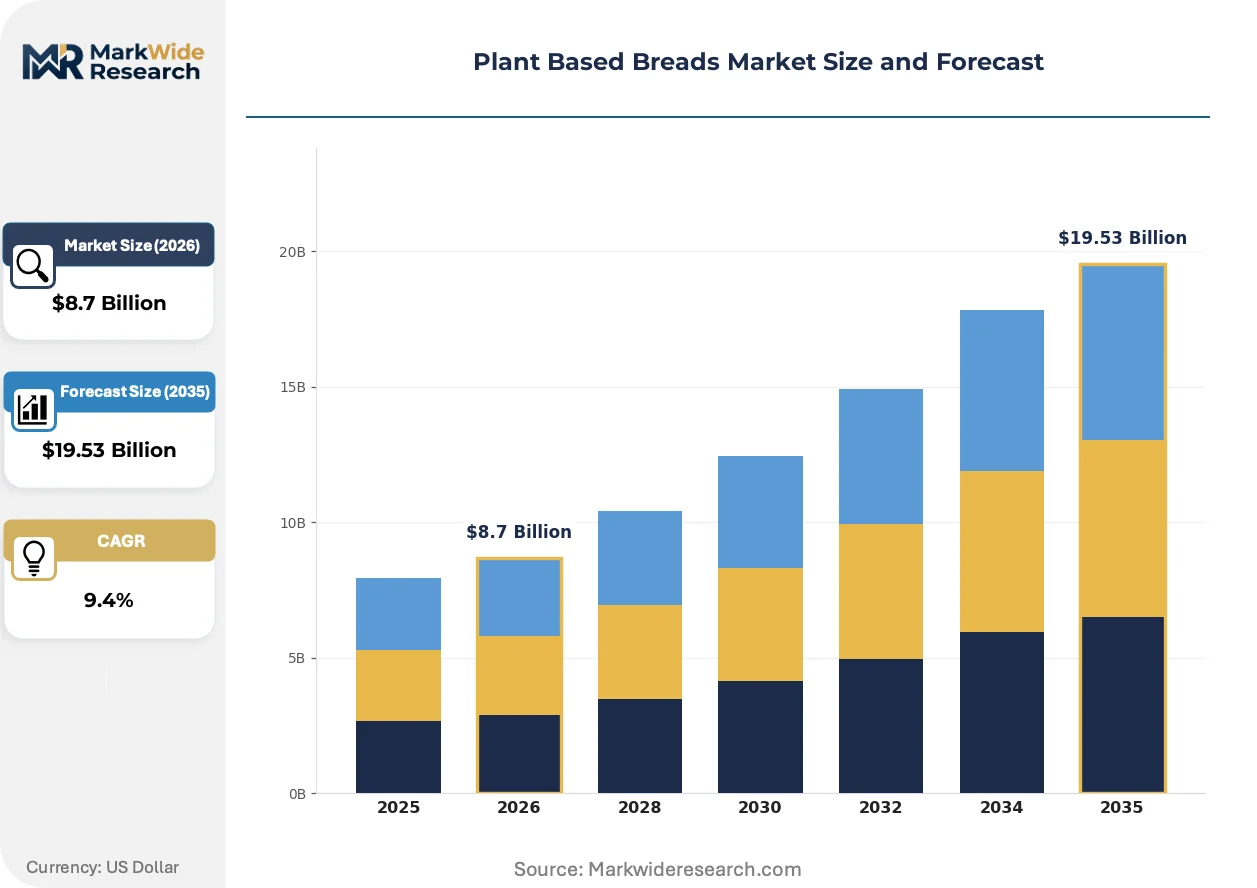
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Whole Grain, Sourdough, Multigrain Ingredient Source: Wheat, Almond Flour, Coconut Flour, Pea Protein Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Farmers Markets End User: Restaurants, Bakeries, Food Service, Households |
| Companies Covered | Dave's Killer Bread, Food for Life Baking Company, Silver Hills Bakery, Northern Bakehouse, Ezekiel Bread, Rudi's Organic Bakery, Alvarado Street Bakery, Engine 2, Three Bakers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Breads Market Evolving Landscape
Sprouted grain processing and precision fermentation are converging to redefine protein quality benchmarks, while regulatory pressure on additive transparency accelerates ingredient deck simplification across premium tiers.
Precision fermentation of functional proteins is digitizing the ingredient sourcing landscape for plant-based bread manufacturers. Specialty ingredient suppliers are deploying microbial production platforms to generate egg-replacement proteins and binding agents at scale. The technology is digitizing procurement risk assessment by enabling geographic decoupling from agricultural commodity cycles.
EU Green Deal agricultural transition targets are redirecting European grain sourcing toward reduced-input cultivation systems. EFSA clean-label guidelines are simultaneously tightening disclosure requirements for processing aids and preservatives. German and Dutch manufacturers are responding with vertically integrated regenerative supply partnerships that preempt compliance costs.
Health-conscious consumers are rotating toward self-directed wheat avoidance patterns independent of clinical celiac diagnosis. Retail buyers are compressing shelf-space allocation for conventional loaves in favor of gluten-free and ancient-grain alternatives. This behavioral shift is most visible in US coastal metropolitan markets and German organic retail channels where functional nutrition claims drive basket composition.
Plant Based Breads Market Segmentation
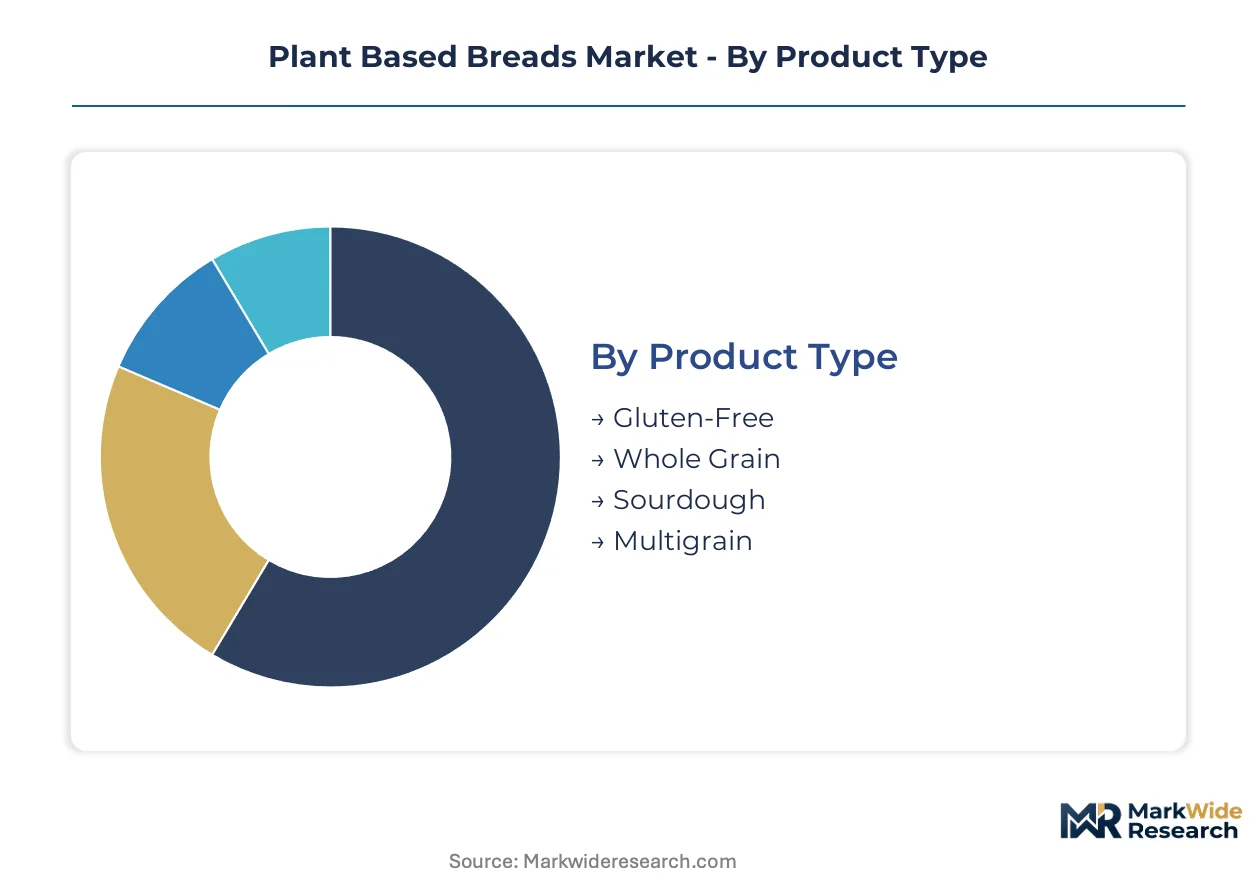
Plant-based bread segmentation reveals divergent margin profiles across formulation complexity and channel access. Manufacturers prioritize gluten-free and protein-fortified lines while navigating EFSA disclosure mandates and regenerative sourcing constraints.
Product Type:
Mature formats face margin compression from commodity wheat volatility, while emerging functional categories capture premium positioning through sprouted grain and precision-fermented protein integration.
- Gluten-Free:Formulations rely on hydrocolloid stabilizers and enzyme systems to replicate wheat protein networks. Demand concentrates in German organic retail and US coastal metros where self-directed wheat avoidance drives basket composition. EFSA additive disclosure mandates force continuous reformulation cycles.
- Sourdough:Extended fermentation protocols develop natural acidity and extended shelf stability without synthetic preservatives. French and Italian traditional bakeries anchor volume, while US craft producers scale through frozen dough intermediates. Clean-label positioning aligns with EU Green Deal agricultural transition targets.
- Whole Grain:Bran and germ retention delivers fiber density and mineral content for institutional nutrition programs. USDA organic certification unlocks premium retail placement algorithms.
- Multigrain:Composite flour systems blend ancient grains with functional seeds for texture differentiation and glycemic positioning.
Gluten-free handles the majority of throughput; sourdough is expanding most quickly on share as natural preservation reduces additive compliance burden.
Ingredient Source:
Cost tier stratification separates commodity grain dependence from specialty protein premiums, with mid-tier brands trapped between wheat futures volatility and regenerative supply scarcity.
- Wheat:Conventional milling bases dominate volume economics but face narrowing upstream margins from global futures volatility. German and Dutch manufacturers are vertically integrating into regenerative-certified farms to preempt EU Green Deal compliance costs.
- Pea Protein:Isolates deliver complete amino acid profiles and superior water-holding capacity for athletic and aging consumer segments. Functional binding properties displace soy and wheat gluten in premium formulations targeting protein fortification claims.
- Almond Flour:Low-carb positioning and fat content support keto-adjacent dietary protocols. California supply concentration creates price volatility risk.
- Coconut Flour:High fiber density and natural sweetness reduce added sugar requirements in clean-label formulations.
Wheat retains volume dominance; pea protein is gaining share fastest through functional bakery format expansion.
Distribution Channel:
Customer type fragmentation splits between institutional procurement standardization and direct-to-consumer personalization, with subscription models capturing disproportionate growth velocity.
- Supermarkets:Shelf-space compression favors gluten-free and ancient-grain SKUs over conventional loaves in health-conscious demographics. Placement algorithms increasingly weight USDA organic certification.
- Online Retail:Subscription models and personalized nutrition bundling enable recurring revenue pipelines. Direct-to-consumer health branding captures athletic and aging segments with protein-fortified positioning.
- Health Food Stores:Curated assortments prioritize sprouted grain and fermented wheat innovations for gut-health-positioned consumers.
- Farmers Markets:Local provenance and minimal processing appeal support premium pricing for small-batch sourdough and ancient-grain varieties.
Supermarkets handle the majority of throughput; online retail climbs the fastest on share through subscription infrastructure.
End User:
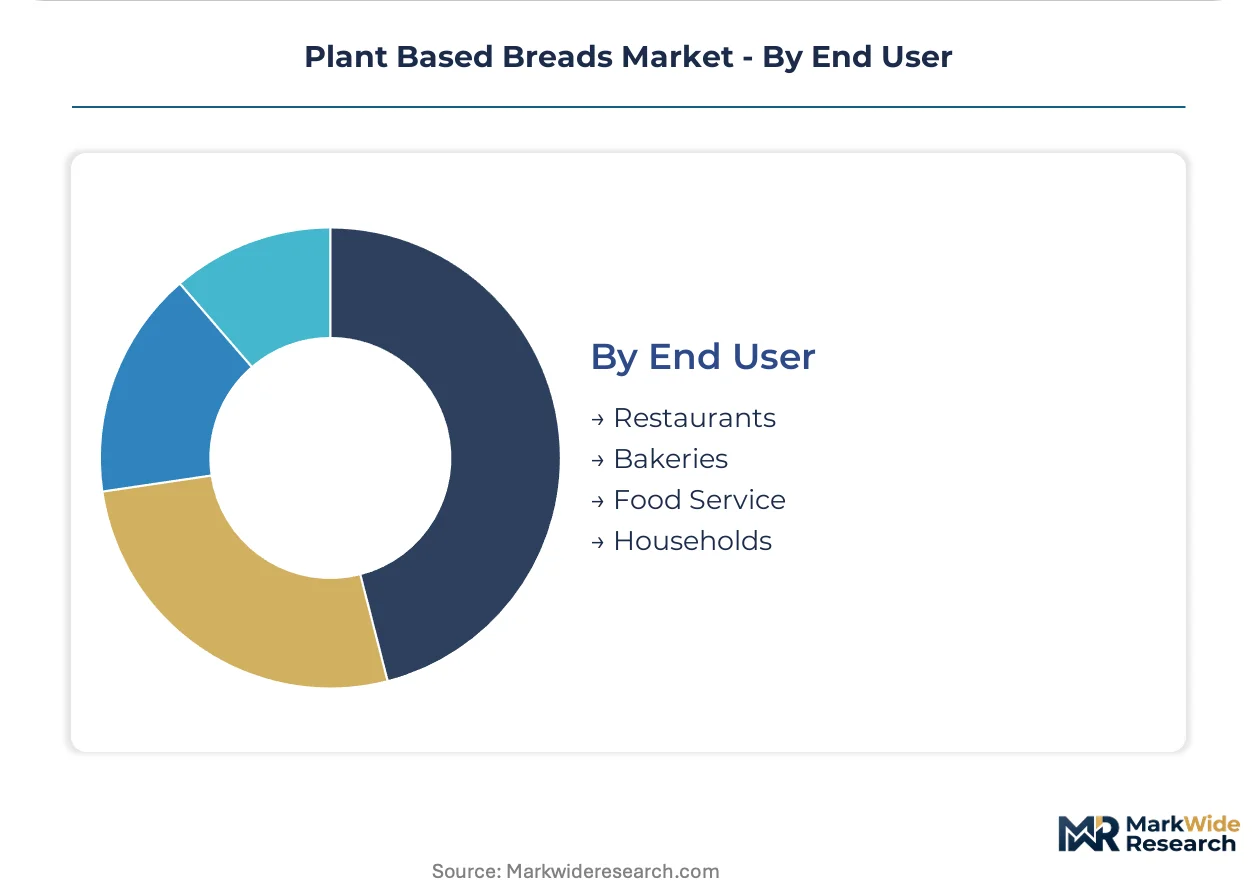
Application concentration varies between scalable institutional contracts and fragmented household purchasing, with food service procurement mandating vegan-compliant menu standardization.
- Food Service:Healthcare and education sector buyers mandate vegan-compliant bread SKUs for menu standardization, creating contracted volume pipelines that de-risk production planning. EFSA clean-label guidelines tighten additive disclosure requirements across European institutional procurement.
- Households:Self-directed dietary rotation toward functional nutrition claims drives trial of protein-fortified and gut-health-positioned formats. German consumers concentrate demand for fermented grain innovations.
- Restaurants:Premium positioning requires artisan credentialing and transparent supply chain narratives for menu differentiation.
- Bakeries:Intermediate processing of frozen dough and par-baked formats enables geographic expansion without capital-intensive production infrastructure.
Food service handles the majority of throughput; households are the fastest mover on share as functional bakery formats penetrate retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regenerative grain sourcing concentrates in Germany and the Netherlands, where vertically integrated supply partnerships preempt EU Green Deal compliance costs. EFSA disclosure mandates and USDA organic certification requirements shape formulation decisions across major production clusters. Consumer demand for functional bakery formats drives regional differentiation in product positioning and channel strategy.
Germany
Functional bakery formats and protein-fortified loaves anchor consumer demand in German organic retail channels. EFSA clean-label guidelines tighten additive disclosure requirements for processing aids and preservatives. Bavaria and North Rhine-Westphalia host vertically integrated regenerative supply partnerships that preempt compliance costs through captive grain programs.
United States
Self-directed wheat avoidance and protein-fortified positioning drive trial in coastal metropolitan markets. FDA labeling standards for gluten-free claims and USDA organic certification requirements shape product development thresholds. Pacific Northwest and Northeast Corridor clusters concentrate sprouted grain innovation and subscription direct-to-consumer infrastructure.
Netherlands
Reduced-input cultivation systems and regenerative grain sourcing redirect procurement under EU Green Deal agricultural transition targets. EFSA allergen disclosure mandates reshape institutional procurement standards for healthcare and education sector buyers. Randstad region anchors vertically integrated supply partnerships that integrate carbon accounting methodologies.
Canada
Pea protein functional binding applications gain traction among athletic and aging consumer segments. Health Canada regulations govern nutrient content claims and organic certification equivalency with USDA standards. Prairie Provinces concentrate regenerative grain production for clean-label procurement commitments.
United Kingdom
Sourdough and extended fermentation protocols align with natural preservation demand and clean-label positioning. EFSA-aligned disclosure expectations influence formulation decisions despite post-Brexit regulatory divergence. London and Southeast England concentrate specialty food service procurement and direct-to-consumer subscription infrastructure.
Plant Based Breads Market Competitive Landscape
Organic supply chain specialists and sprouted grain technology leaders split the market between premium retail placement and functional nutrition positioning. The competitive structure concentrates around three strategic archetypes: vertically integrated organic brands with captive supply chains, technology-forward innovators leveraging fermentation and sprouted grain processing, and heritage-positioned players emphasizing dense nutritional profiles and biblical formula narratives. Dominant competitive moves include backward integration into regenerative grain sourcing and portfolio diversification toward gluten-free and protein-fortified formats.
Within the heritage-positioned tier, Food for Life Baking Company and Ezekiel Bread exemplify dense nutritional profile positioning through biblical formula narratives. Dave's Killer Bread anchors the organic supply chain specialist archetype with North American retail concentration. Silver Hills Bakery occupies a position within the sprouted grain technology leadership segment. These three players collectively represent the strategic divergence between supply chain control, processing innovation, and brand heritage as competitive foundations.
| Leading Market Players |
|---|
| Dave's Killer Bread |
| Food for Life Baking Company |
| Silver Hills Bakery |
| Northern Bakehouse |
| Ezekiel Bread |
| Rudi's Organic Bakery |
| Alvarado Street Bakery |
| Engine 2 |
| Three Bakers |
| Others |
Value Network & Pricing Analysis
Regenerative grain supply concentration in Germany and the Netherlands anchors margin capture downstream, with vertically integrated bakeries commanding premium placement while commodity-dependent brands face narrowing value pools.
Pricing Analysis
EFSA clean-label disclosure mandates dictate the pricing tier structure across European plant-based bread markets. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified regenerative loaves from conventional gluten-free formats and commodity wheat-based economy lines. Price differentiation hinges on certification grade and captive supply chain control, with organic certification unlocking algorithmic retail placement. Pricing pressure stems from commodity wheat futures volatility compressing upstream margins for non-integrated brands. Institutional food service buyers exhibit lowest price sensitivity due to contractual volume commitments, while household consumers in coastal US metros and German organic channels show highest sensitivity to per-unit premiums.
Supply Chain Analysis
Extended payment terms from specialty ingredient suppliers now reach 90-120 days for pea protein isolates and precision-fermented binding agents, straining working capital for mid-scale bakeries. Geographic supply concentrates in Germany, the Netherlands, and the US Pacific Northwest for regenerative grain and sprouted wheat innovations. Raw material dependencies center on Canadian prairie pea protein, California almond flour, and EU-certified organic wheat. Supply chain risk concentrates in single-source vulnerability for regenerative-certified grain programs meeting EU Green Deal compliance. Distribution runs through supermarket shelf-space algorithms weighted toward organic certification, with online subscription platforms capturing fastest-growing downstream velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based bread markets are recovering from input cost cyclicality as regenerative grain supply expansion and precision fermentation scale ease commodity dependence.
For Market Incumbents: Insulate margin structure through backward integration into regenerative-certified grain programs in Germany and the Netherlands, preempting EFSA compliance cost escalation. Secure multi-year organic supply contracts before EU Green Deal agricultural transition targets tighten procurement bottlenecks. Channel control through direct-to-consumer subscription infrastructure defends against retail shelf-space compression favoring gluten-free and ancient-grain SKUs. For New Entrants and Emerging Players: Pursue white-space positioning in German functional bakery formats targeting protein-fortified and gut-health-positioned households, where demand concentrates fastest. Target online retail subscription models with personalized nutrition bundling for athletic and aging consumer segments, the most penetrable channel showing disproportionate growth velocity. Go-to-market angle should leverage precision-fermented protein ingredients to bypass regenerative grain supply scarcity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed organic supply chain specialists holding captive regenerative grain programs in North America and Europe. Long-term viability across the analysis window favors brands with vertically integrated sourcing and clean-label formulation R&D capabilities. Watch EFSA protein fortification threshold evolution as the inflection signal determining which formulations qualify for preferential institutional procurement contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Grain Supply Integration | Captive sourcing from Bavarian and Dutch farms preempts EU Green Deal compliance cost escalation. |
| Precision Fermentation Scale-Up | Microbial protein platforms reduce dependence on agricultural commodity cycles for binding agents. |
| Direct-to-Consumer Subscription Launch | Recurring revenue pipelines capture athletic and aging segments through personalized nutrition bundling. |
| USDA Organic Certification Investment | Premium retail placement algorithms increasingly weight organic certification for shelf-space allocation. |
| Gluten-Free Format Expansion | Hydrocolloid and enzyme system R&D addresses structural limitations degrading celiac-targeted shelf stability. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with bakery R&D directors, organic supply chain managers, retail category buyers, and institutional food service procurement officers informed formulation and channel dynamics. Secondary sources include EFSA additive disclosure guidelines, USDA organic certification databases, EU Green Deal agricultural transition documentation, and Nielsen retail audit data for gluten-free and ancient-grain SKU performance. Bottom-up volume modeling triangulates with top-down value projections across ingredient source and distribution channel dimensions.
Calibration against historical wheat futures volatility and pea protein isolate pricing informs elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type complexity, ingredient source tier, distribution channel structure, and end-user application concentration. CAGRs derive from regression analysis of premium format adoption curves and subscription channel penetration rates. Industry-specific forecast inputs incorporate EFSA regulatory timeline probability and regenerative grain supply expansion trajectories.
Sensitivities concentrate around EFSA protein fortification threshold revisions and EU Green Deal agricultural transition acceleration. Forecasts reflect documented assumptions on commodity input cost trajectories and clean-label disclosure mandate enforcement intensity. Macroeconomic wheat supply shocks, regulatory divergence from EFSA-aligned frameworks, or breakthrough precision fermentation cost reductions would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
China Rice Protein Market
Plant Based Food
North America Tofu Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Low Fat Plant-Based Diet Market