
 Global Textured Vegetable Protein Market | 2026-2036
Global Textured Vegetable Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textured Vegetable Protein Market Foresight
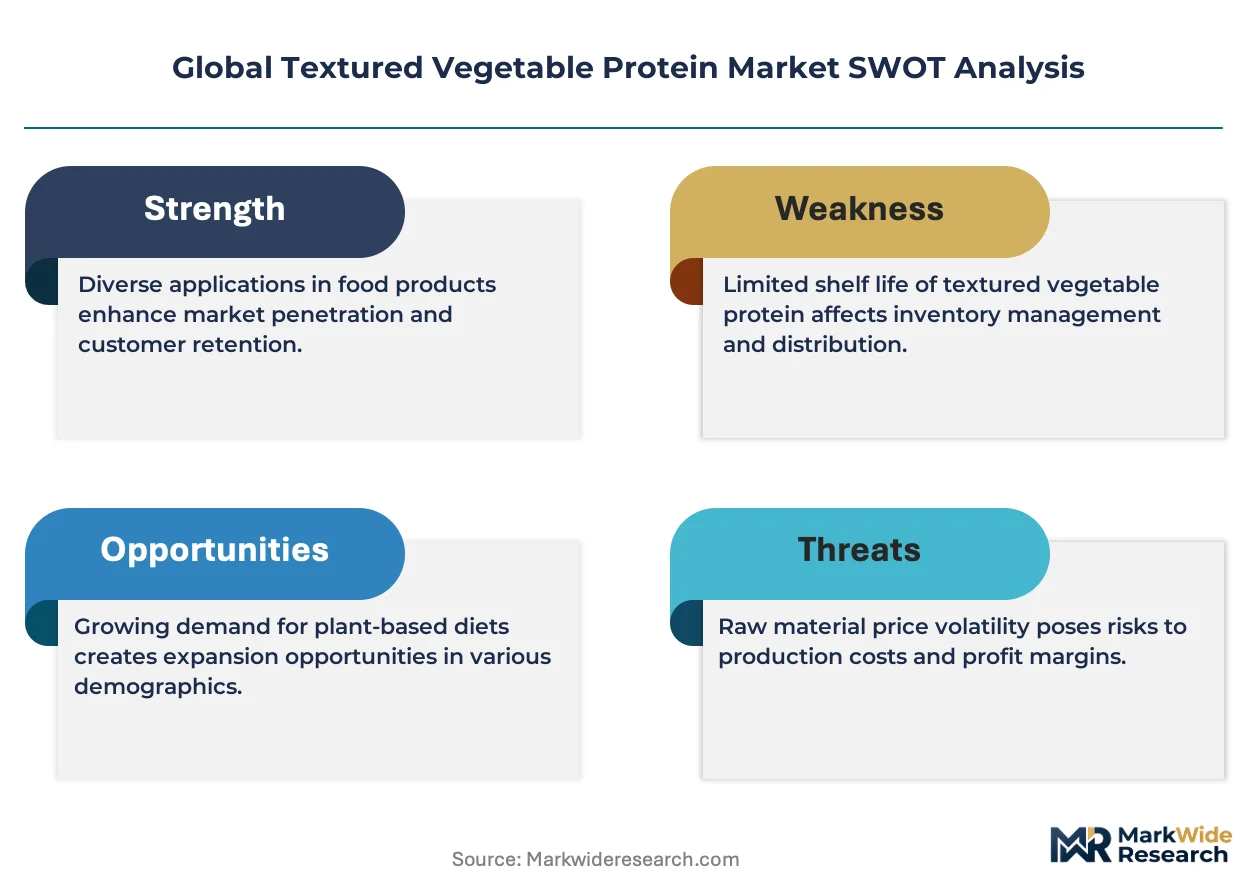
EU Green Deal carbon-border adjustments is repositioning ingredient sourcing economics for European food manufacturers. Archer Daniels Midland Company leverages its North American soy processing infrastructure to supply deforestation-certified raw material streams. Cargill, Incorporated sustains competitive positioning through backward integration into identity-preserved soybean origination. Roquette Frères anchors its European market presence with pea protein extraction capacity centered in France.
Textured vegetable protein denotes extruded plant matter, typically achieving protein contents between 50% and 70% on a dry-weight basis through thermoplastic processing of defatted flours or concentrates. The material functions primarily as a structural and nutritional analog to ground meat in formulated food systems. Soy-based variants occupy the dominant volume position given mature supply chains and cost-optimized extraction infrastructure. Pea protein extraction is accelerating as food manufacturers seek allergen-friendly alternatives with favorable emulsification profiles. Wheat gluten retains specialized placement in bakery applications where extensibility and viscoelastic recovery prove critical.
FDA GRAS determinations and USDA organic certification govern US market access pathways, while EFSA novel food assessments and EU organic regulations shape European commercialization timelines. China's NMPA and GB standards for plant-based foods are tightening protein content labeling requirements, altering export qualification protocols for international suppliers. Stakeholders must monitor evolving allergen threshold definitions and carbon intensity disclosure mandates across multiple jurisdictions to preserve formulation flexibility and market eligibility.
Market Dynamics
EU Green Deal carbon-border adjustments are restructuring ingredient sourcing economics for European food manufacturers, forcing rapid reformulation of meat-alternative and bakery portfolios toward deforestation-certified plant proteins.
Growth Catalysts
- Carbon Accounting Mandates:EU Green Deal disclosure rules for animal-derived ingredients are accelerating plant-protein substitution in German industrial bakery and meat-alternative production.
- Pea Protein Extraction Scale-Up:Food manufacturers seeking allergen-friendly alternatives with superior emulsification profiles are expanding French pea protein processing infrastructure.
- China:NMPA tightening of protein content labeling requirements for plant-based foods is upgrading export qualification standards, filtering out subscale international suppliers.
Market Restraints
- Soy Supply Concentration:North American soy processing infrastructure dominates deforestation-certified raw material streams, creating geographic dependency risk for European formulators.
- EFSA Novel Food Timelines:Extended safety assessment protocols for new protein sources delay European commercialization of emerging textured vegetable protein variants by 18-36 months.
- Wheat Gluten Substitution Limits:Viscoelastic recovery requirements in laminated bakery applications prevent full displacement of wheat gluten despite pea protein emulsification advantages.
Strategic Opportunities
- India:FSSAI plant-protein labeling guidelines are formalizing, creating first-mover advantage for suppliers establishing compliant supply chains ahead of enforcement.
- Hybrid Extrusion Convergence:Combining high-moisture extrusion with 3D food printing enables whole-muscle analog production previously unattainable with traditional thermoplastic processing.
- Direct-to-Manufacturer Platforms:B2B ingredient marketplaces are collapsing traditional distributor margins, allowing textured vegetable protein producers to capture value previously lost to intermediaries.
Industry Challenges
- Extrusion Technologist Scarcity:Food science programs produce insufficient specialists in thermoplastic processing of plant proteins, constraining R&D throughput at mid-scale manufacturers.
- Multi-Jurisdiction Allergen Threshold Harmonization:Divergent FDA, EFSA, and GB standards for soy and gluten labeling force costly SKU fragmentation and reformulation cycles.
- Legacy Equipment Retrofit Costs:Converting animal-protein processing lines to handle high-viscosity plant extrudates requires capital-intensive screw and die modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textured Vegetable Protein Market |
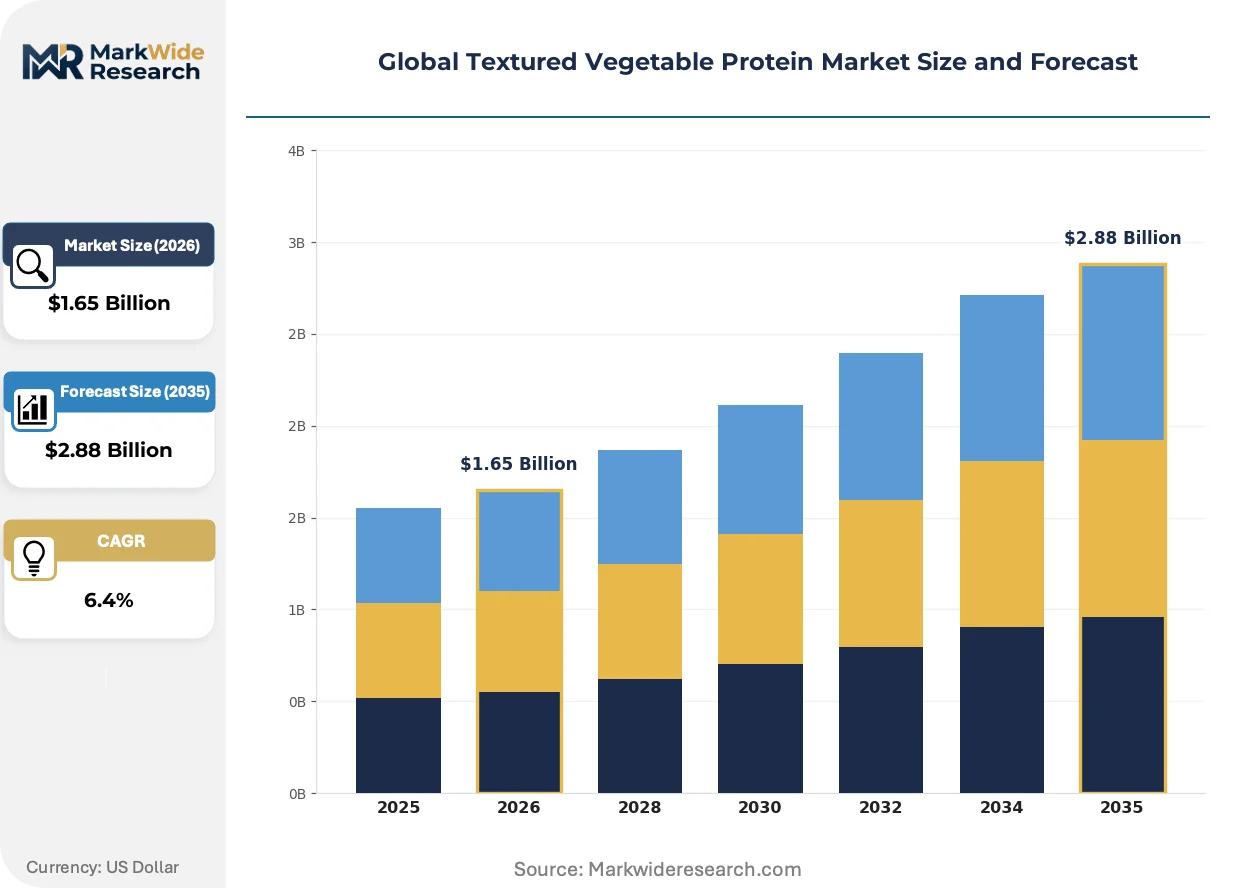
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy-Based, Pea Protein, Wheat Gluten, Rice Protein, Sunflower Protein Application: Meat Alternatives, Bakery, Snacks, Dairy-Free Products, Sports Nutrition Customer Type: Food Manufacturers, Food Service Providers, Nutritional Supplement Companies, Retailers, Private Label Brands Packaging Type: Bulk Bags, Sachets, Pouches, Vacuum Packs, Paper Bags |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Roquette Frères, Ingredion, International Flavors & Fragrances, The Scoular Company, MGP Ingredients, Shandong Yuxin Bio-Tech Co., Ltd., Axiom Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textured Vegetable Protein Market Shifts & Advancements
Active reformulation across meat-alternative and bakery segments is compressing development cycles and forcing convergence between extrusion technology and precision fermentation capabilities.
High-moisture extrusion is integrating twin-screw processing with post-extrusion texturization to create fibrous structures mimicking whole-muscle meat. European meat-alternative producers are adopting this at pilot scale within 18-month windows. The technology is integrating previously separate unit operations, reducing capital intensity for new market entrants.
EFSA novel food assessments are extending evaluation timelines for emerging protein sources, compressing competitive windows for first movers. This regulatory friction is favoring established soy and pea protein variants with existing safety dossiers. German and Dutch formulators are responding by locking in multi-year supply contracts with approved suppliers rather than awaiting novel determinations.
Buyer concentration among European retail private-label programs is compressing supplier negotiation leverage and accelerating specification standardization. Direct sourcing teams at German and UK supermarket chains are displacing traditional ingredient distributors. This shift is most visible in the Nordics, where sustainability scorecard requirements now dominate procurement decisions ahead of unit cost.
Global Textured Vegetable Protein Market Segmentation
Textured vegetable protein markets fragment across protein source, application intensity, and procurement scale. Buyers select segments based on emulsification requirements, allergen constraints, and carbon disclosure obligations.
Product Type:
Formulators differentiate by protein functionality, allergen profile, and supply chain certification status.
- Soy-Based:Thermoplastic extrusion of defatted soy flour yields protein concentrations between 50% and 70% on a dry-weight basis. German industrial bakery and meat-alternative producers dominate procurement volumes as EU Green Deal carbon accounting rules tighten disclosure requirements for deforestation-linked ingredients.
- Pea Protein:Roquette Frères anchors French extraction capacity supplying allergen-friendly alternatives with superior emulsification stability. Food manufacturers seeking clean-label positioning drive demand concentration in the Netherlands and Belgium where EFSA novel food assessments favor established safety dossiers.
- Wheat Gluten:Viscoelastic recovery properties retain specialized placement in laminated bakery applications where extensibility proves critical.
- Rice Protein:Hypoallergenic positioning serves nutritional supplement companies targeting sensitive consumer segments.
- Sunflower Protein:Emerging European cultivation networks support regional sourcing strategies for sustainability-scorecard compliance.
Volume sits with soy-based variants; growth tilts toward pea protein as allergen-friendly reformulation accelerates.
Application:
End-use intensity varies by structural requirements and regulatory scrutiny levels.
- Meat Alternatives:High-moisture extrusion creates fibrous whole-muscle analogs previously unattainable with traditional thermoplastic processing. European producers pilot this technology within compressed development cycles as retail private-label procurement teams displace traditional ingredient distributors.
- Bakery:Wheat gluten retains irreplaceable function in laminated dough systems despite pea protein emulsification advantages.
- Snacks:Extruded crisp textures drive adoption in seasoned protein-fortified formats.
- Dairy-Free Products:Emulsification stability requirements favor pea protein isolates in plant-based beverage systems.
- Sports Nutrition:Rice protein serves hypoallergenic positioning in powdered supplement formulations.
Meat alternatives capture procurement investment; bakery maintains volume stability through wheat gluten dependency.
Customer Type:
Scale and specification authority determine margin capture and contract structure.
- Food Manufacturers:Industrial bakery and meat-alternative producers in Germany reformulate portfolios to meet evolving EU Green Deal sustainability benchmarks.
- Food Service Providers:Central kitchen procurement teams specify textured vegetable protein for plant-based menu expansion.
- Nutritional Supplement Companies:Sports nutrition formulators prioritize rice and pea protein for allergen-sensitive positioning.
- Retailers:German and UK supermarket chains deploy direct sourcing teams displacing traditional ingredient distributors.
- Private Label Brands:Nordic sustainability scorecard requirements dominate procurement decisions ahead of unit cost.
Food manufacturers anchor contract volumes; private label brands are expanding most quickly through sustainability-linked specification.
Packaging Type:
Handling economics and shelf-life requirements segment procurement by operational scale.
- Bulk Bags:Industrial food manufacturers optimize per-kilogram logistics costs through tanker-truck and silo-receiving infrastructure.
- Sachets:Food service portion-control applications favor pre-measured single-use formats.
- Pouches:Retail-facing brands select resealable flexible packaging for consumer convenience.
- Vacuum Packs:Oxygen exclusion extends shelf stability for moisture-sensitive extrudates.
- Paper Bags:Sustainability-scorecard compliance drives adoption in Nordic retail private-label programs.
Bulk bags dominate tonnage movement; paper bags gain specification share fastest through carbon disclosure alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Netherlands and Belgium concentrate European textured vegetable protein import and processing infrastructure. These logistics hubs service German industrial food manufacturers facing EU Green Deal carbon-border compliance deadlines. Asia-Pacific demand clusters in Chinese coastal manufacturing provinces and Indian food-processing corridors.
Germany
Industrial bakery and meat-alternative producers drive procurement volumes as EU Green Deal disclosure rules tighten requirements for deforestation-linked ingredients. The country's national food safety regulator enforces strict allergen threshold definitions for soy and gluten labeling. North Rhine-Westphalia hosts concentrated extrusion technology clusters where manufacturers retrofit legacy animal-protein processing lines.
China
NMPA tightening of protein content labeling requirements for plant-based foods filters subscale international suppliers from export qualification protocols. GB standards for plant-based foods now mandate precise protein content declarations on packaging. Yangtze River Delta manufacturing provinces house the largest concentration of domestic textured vegetable protein extrusion capacity serving both food and feed applications.
United States
FDA GRAS determinations and USDA organic certification govern market access pathways for domestic and imported protein ingredients. The country's national agricultural department maintains deforestation-free sourcing requirements for federally procured food products. Midwest soy processing corridors in Illinois and Iowa anchor North American supply of thermoplastic extrusion feedstocks.
India
FSSAI plant-protein labeling guidelines are formalizing compliance standards ahead of enforcement timelines. The country's national food regulator mandates ingredient disclosure protocols for packaged foods containing textured vegetable protein. Maharashtra and Gujarat food-processing corridors attract first-mover suppliers establishing compliant supply chains for domestic and export markets.
France
Roquette Frères anchors national pea protein extraction capacity supplying allergen-friendly alternatives to Benelux and German formulators. EFSA novel food assessments favor established safety dossiers for soy and pea variants over emerging protein sources. Hauts-de-France agricultural processing zones concentrate deforestation-certified raw material intake infrastructure for European distribution.
Global Textured Vegetable Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the textured vegetable protein supply base. The market structure tilts toward consolidation at the raw material origination tier and fragmentation at specialized extrusion processing. Three archetypes dominate: agricultural commodity processors with backward integration into identity-preserved crops, European pea protein extraction specialists with regional supply chain anchoring, and Asian equipment-integrated manufacturers serving cost-sensitive export markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure deforestation-certified feedstock streams.
Among North American agricultural processors, Archer Daniels Midland Company exemplifies the diversified conglomerate archetype with extensive soy processing infrastructure. Cargill, Incorporated occupies a parallel position representing commodity traders with captive supply chain control over certified raw material streams. Roquette Frères anchors the European specialist tier, demonstrating how regional extraction capacity can dominate allergen-friendly protein segments. These three companies collectively illustrate the geographic and strategic segmentation shaping procurement decisions across German industrial bakery, Chinese export manufacturing, and Indian emerging market development.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Roquette Frères |
| Ingredion |
| International Flavors & Fragrances |
| The Scoular Company |
| MGP Ingredients |
| Shandong Yuxin Bio-Tech Co., Ltd. |
| Axiom Foods |
| Others |
Supply & Pricing Matrix
High-moisture extrusion adoption across European meat-alternative producers is simultaneously compressing unit production costs and concentrating procurement leverage among equipment-integrated manufacturers with captive extrusion technologist teams. This production-method transition forces mid-scale formulators to accept longer lead times or pay premiums for access to contracted extrusion capacity.
Pricing Analysis
Short-lead-time premiums for deforestation-certified soy protein concentrates run 15-25 percent above contract baselines, while spot inventory discounts attract buyers with flexible formulation calendars. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and carbon-disclosure documentation depth. Pricing pressure stems from buyer concentration among German and UK supermarket direct-sourcing teams. Private-label brands show highest price sensitivity; industrial bakery manufacturers with locked-in reformulation timelines show lowest.
Supply Chain Analysis
Reverse-logistics flows for textured vegetable protein remain minimal given food-grade handling requirements, though defective extrudate streams feed into animal feed channels in select jurisdictions. Raw material supply concentrates in the United States, Brazil, and France, with North American soy processing infrastructure and French pea protein extraction capacity anchoring global feedstock availability. The supply chain draws from deforestation-certified soybean origination, identity-preserved pea cultivation, and specialized high-protein wheat varietals. Single-source vulnerability sits with North American soy processing corridors. Distribution runs through Rotterdam and Antwerp logistics hubs serving German industrial manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textured vegetable protein market sits in a technology-transition phase as high-moisture extrusion displaces traditional thermoplastic processing for whole-muscle analog production.
For Market Incumbents: Cement multi-year supply contracts with EFSA-approved soy and pea protein suppliers before novel food assessment timelines extend competitive windows for emerging protein sources. Lock in extrusion technologist talent through specialized compensation structures, as food science program output lags R&D throughput requirements. Priority lever: backward integration into identity-preserved crop origination to secure deforestation-certified feedstock streams against carbon-border adjustment enforcement. For New Entrants and Emerging Players: Begin with hybrid extrusion-3D printing equipment configurations targeting the premium whole-muscle analog segment where incumbent capacity constraints create procurement gaps. White-space targets include Indian food-processing corridors ahead of FSSAI enforcement formalization and Nordic retail private-label programs with sustainability-scorecard procurement dominance. Go-to-market angle: direct-to-manufacturer B2B platforms collapsing traditional distributor margins. For Investors and Strategic Acquirers: Exit pathways concentrate in agricultural conglomerate acquisition of specialized extrusion technology firms, with strategic buyers seeking captive deforestation-certified supply chains. Five-to-ten-year viability favors equipment-integrated manufacturers with in-house extrusion technologist development programs. Signal to watch: EFSA novel food approval velocity for emerging protein sources as inflection indicator for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Origination | Cargill and Archer Daniels Midland leverage North American soy infrastructure to secure deforestation-certified streams ahead of EU Green Deal enforcement. |
| High-Moisture Extrusion Capacity Expansion | European meat-alternative producers pilot twin-screw processing with post-extrusion texturization to capture whole-muscle analog premiums. |
| Direct-to-Manufacturer Platform Launch | B2B ingredient marketplaces collapse distributor margins and allow textured vegetable protein producers to capture intermediary value. |
| EFSA Novel Food Dossier Investment | Roquette Frères anchors pea protein positioning through established safety dossiers that accelerate commercialization versus emerging protein variants. |
| Extrusion Technologist Talent Acquisition | Mid-scale manufacturers compete for scarce thermoplastic processing specialists through specialized compensation and training program development. |
Research Methodology
Trade databases, EFSA novel food submission records, and EU Green Deal regulatory filings formed the secondary backbone, supplemented by customs data tracking deforestation-certified soy and pea protein concentrate flows. Primary interviews with extrusion technology directors, procurement leads at German industrial bakery and meat-alternative manufacturers, sustainability officers at Nordic retail chains, and regulatory affairs specialists at French pea protein extraction facilities validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled production capacity estimates with end-use consumption patterns.
Bottom-up modeling anchored volume projections in named-country production capacity, extrusion equipment installation rates, and reformulation timelines at major food manufacturers, while top-down analysis cross-checked against EU Green Deal carbon accounting implementation schedules and retail private-label expansion commitments. Segmentation dimensions included protein source, application intensity, customer type scale, and procurement certification tier. CAGRs derived from elasticity-adjusted demand curves incorporating carbon-border adjustment cost pass-through assumptions and allergen-friendly reformulation substitution rates.
Underlying measurement precision varies by segment; soy-based and pea protein variants carry tighter precision than emerging sunflower and rice protein categories given established safety dossiers and production volume transparency. Forecasts reflect assumptions around EFSA novel food assessment timelines, EU Green Deal enforcement velocity, and extrusion technologist labor market expansion that could materially revise outcomes. Practitioners should monitor NMPA protein labeling enforcement in China, FSSAI guideline formalization in India, and buyer concentration trends among German supermarket direct-sourcing teams for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
India Pea Protein Market