
 Vegan Margarine Market | 2026-2036
Vegan Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Margarine Market Analytics
Premium clean-label certification is redrawing competitive boundaries in vegan margarine. Upfield leverages its European manufacturing footprint to sustain organic and palm-free supply lines. Miyoko's Creamery differentiates through cultured fermentation technology that anchors its artisan positioning. Unilever competes on brand recognition and retail shelf control across mass-market channels.
Vegan margarine denotes a water-in-fat emulsion containing no animal-derived ingredients, typically formulated with vegetable oils, lecithin, and water to achieve spreadability and baking performance comparable to dairy butter. Spreadable formats lead household penetration while block varieties command stronger margins in artisan bakery applications. Emulsified formulations dominate commercial foodservice demand, whereas organic positioning captures the fastest-growing premium tier in European retail. Tub packaging anchors consumer convenience expectations, though bulk formats sustain institutional bakery procurement economics.
EU Green Deal sustainability criteria and REACH chemical safety protocols shape ingredient sourcing obligations for manufacturers operating across Europe. EFSA nutritional labeling standards influence reformulation priorities as sodium reduction and clean-label claims intensify. Stakeholders must monitor evolving palm oil certification requirements and emerging fermentation-derived fat technologies that could disrupt conventional oil blending economics.
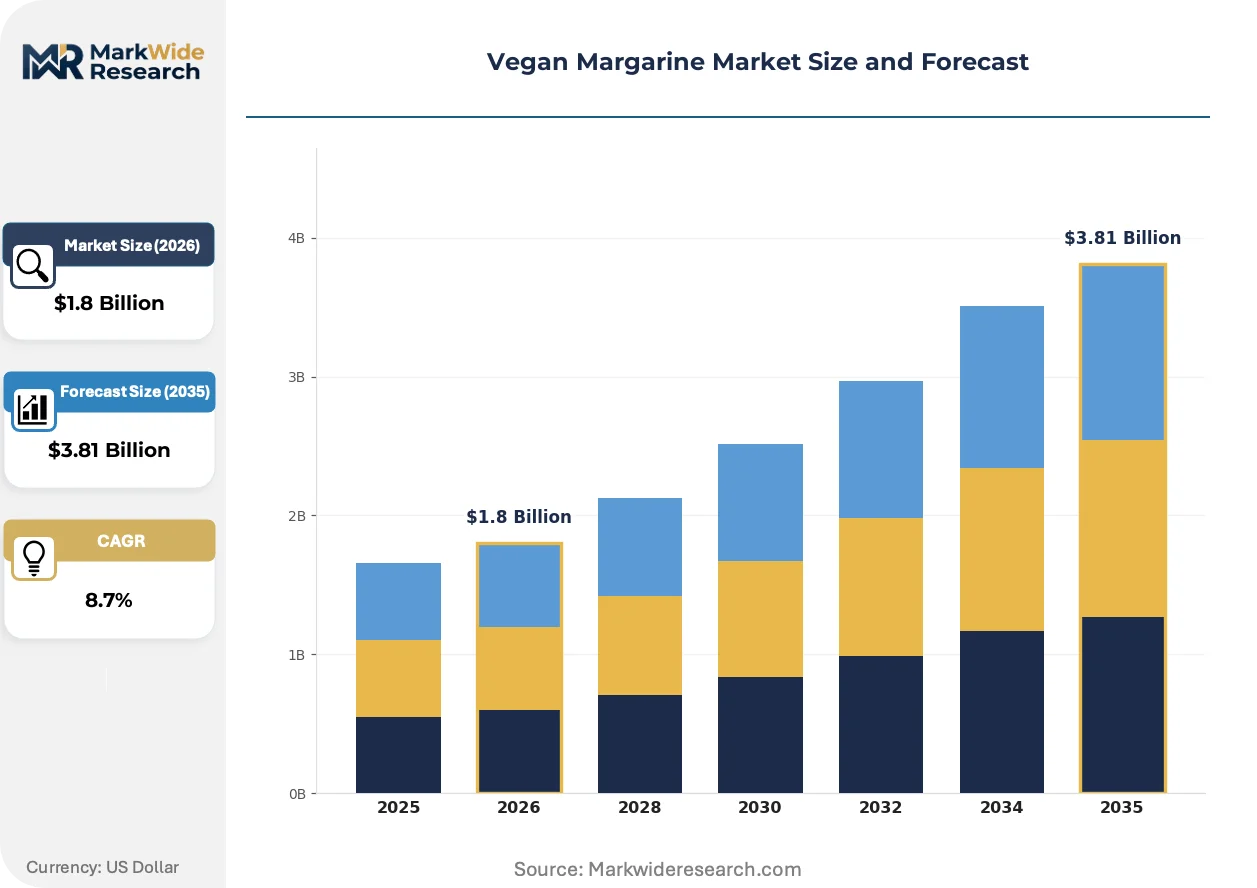
Market Dynamics
EU Green Deal sustainability mandates are compressing formulation timelines across the vegan margarine value chain, forcing manufacturers to requalify palm oil alternatives and fermentation-derived fat inputs ahead of 2027 compliance deadlines.
Growth Catalysts
- REACH chemical safety protocols:ECHA's tightening substance restrictions are accelerating clean-label reformulation investments among European manufacturers seeking preemptive regulatory alignment.
- Artisan bakery applications:Block-format vegan margarine commands premium positioning in France and Italy as craft bakeries replace dairy butter for plant-based menu certification.
- Cultured fermentation technology:Precision fermentation-derived fats are achieving functional parity with conventional oil blends while eliminating tropical deforestation linkages from supply chains.
Market Restraints
- Vegetable oil price volatility:Sunflower and rapeseed oil input costs fluctuate with Black Sea supply disruptions, compressing blender margins on fixed-price retail contracts.
- Southeast Asian palm oil concentration:RSPO-certified supply remains geographically concentrated in Indonesia and Malaysia, exposing buyers to single-origin sustainability audit risks.
- Technical emulsion stability limits:Water-in-fat formulations without lecithin alternatives struggle to maintain spreadability across freeze-thaw cycles required by frozen bakery channels.
Strategic Opportunities
- Underpenetrated Polish retail:Modern grocery expansion in Warsaw and Kraków creates shelf space for premium tub formats previously limited to Western European distribution.
- EU CSRD reporting requirements:Scope 3 emissions disclosure mandates are driving foodservice procurement teams toward certified palm-free suppliers with verifiable supply chain data.
- Direct-to-bakery e-procurement platforms:Digital ordering interfaces are disintermediating traditional foodservice distributors for mid-size bakery chains seeking just-in-time emulsified bulk deliveries.
Industry Challenges
- Fermentation scale-up talent scarcity:Bioprocess engineering expertise for industrial fat production concentrates in Denmark and Netherlands, constraining rapid capacity expansion elsewhere.
- Organic certification timeline compression:Three-year conversion periods for oilseed acreage lag behind retailer demand for certified organic positioning in German discount channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Margarine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block, Spreadable, Liquid, Baking Formulation: Emulsified, Flavored, Unsalted, Organic Packaging Type: Tub, Stick, Pouch, Bulk End User: Restaurants, Households, Bakeries, Foodservice |
| Companies Covered | Upfield, Conagra Brands, Unilever, Bunge Limited, Wilmar International, Miyoko's Creamery, Nutiva, EFKO Group, FUJI OIL HOLDINGS INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Margarine Market Evolving Landscape
Formulation science and procurement digitization are converging to reshape competitive advantage in vegan margarine, with sustainability verification now embedded as a baseline rather than premium differentiator.
Fermentation-derived fat technologies are supplanting conventional vegetable oil blending in premium product tiers. Danish and Dutch biotech suppliers are scaling precision fermentation capacity to meet bakery chain RFP specifications for deforestation-free emulsions. This shift is compressing the addressable market for commodity palm oil refiners lacking biotechnology partnerships.
EFSA nutritional labeling standards are mandating front-of-pack sodium disclosure across EU member states. Reformulation teams are accelerating potassium chloride substitution programs to maintain clean-label positioning under tightened salt reduction targets. Spreadable tub formats targeting German and Dutch households face the steepest compliance timelines given existing portfolio salt levels.
Foodservice procurement teams are consolidating supplier rosters around vertically integrated manufacturers with captive organic oilseed crushing and in-house fermentation capacity. Bakery chains in Belgium and Austria are awarding multi-year contracts to single-source vendors capable of delivering batch-level sustainability documentation. This concentration pattern favors established European manufacturers with backward integration into oilseed processing over import-dependent blenders.
Vegan Margarine Market Segmentation
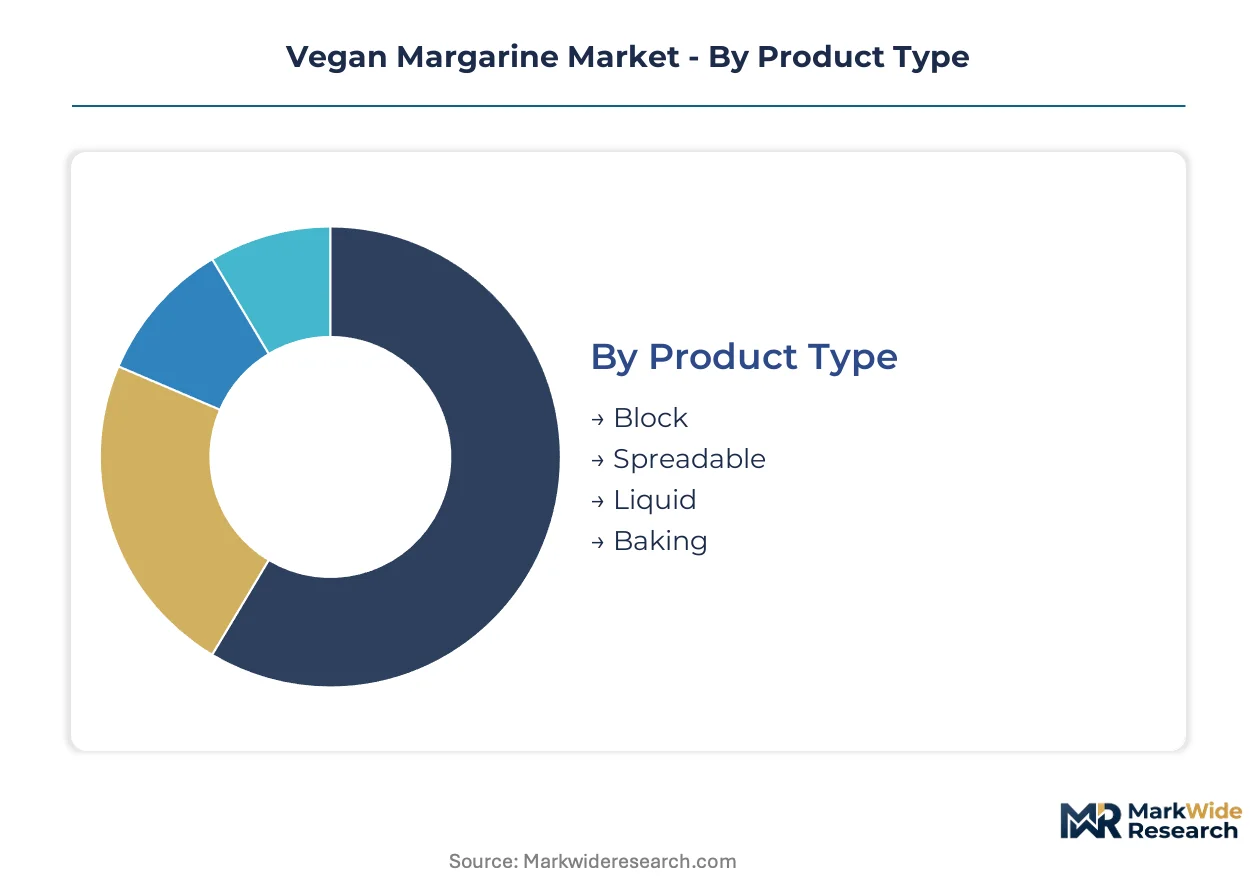
Vegan margarine segmentation reveals how formulation choices and packaging formats align with distinct use cases and purchasing channels. Understanding these splits helps manufacturers allocate R&D resources and optimize distribution investments across divergent customer requirements.
Product Type:
Spreadable formats face the strongest substitution pressure from dairy butter price volatility and olive oil spreads in Mediterranean markets, while block varieties defend position through bakery chain contract stickiness.
- Block:Solid fat structure with higher saturated fat content enables lamination performance in croissants and puff pastries. Artisan bakeries in France and Italy source block formats for clean-label menu certification, though frozen bakery channels demand modified formulations for freeze-thaw stability.
- Spreadable:Softer water-in-fat emulsion optimized for direct-from-refrigerator spreadability on bread. German and Dutch retail households concentrate demand here, pressured by EFSA sodium disclosure mandates accelerating reformulation timelines.
- Liquid:Pourable oil blend for cooking and sautéing applications where solid fat functionality is unnecessary.
- Baking:High-melting-point specialty formulation designed for cake batters and cookie doughs requiring creaming aeration.
Spreadable anchors the volume base while block gains share at the steepest rate.
Formulation:
Cost tier stratification separates premium-positioned organic and cultured variants from commodity emulsified products competing on unit economics.
- Emulsified:Standard water-in-fat system stabilized with lecithin or alternative emulsifiers for spreadability and shelf stability. Foodservice distributors and mid-size bakery chains in Belgium and Austria concentrate procurement here, consolidating around suppliers with batch-level sustainability documentation.
- Organic:Oilseeds from three-year certified organic acreage with restricted additive lists. German discount retailers are compressing certification timelines, creating supply shortages as conversion lags behind shelf placement demands.
- Flavored:Infused with herbs, garlic, or truffle for premium positioning in specialty retail.
- Unsalted:Zero-added-sodium variant targeting hypertension-conscious consumers and controlled-sodium baking applications.
Emulsified captures the largest revenue pool while organic climbs the fastest.
Packaging Type:
Customer type determines format selection, with institutional buyers prioritizing procurement economics and households valuing convenience and portion control.
- Tub:Wide-mouth plastic container dominating household retail across Western Europe. Convenience expectations in German and Dutch markets anchor this format's penetration, though lightweighting pressures intensify under EU packaging waste directives.
- Bulk:Intermediate bulk containers and tanker deliveries for bakery chain commissaries and foodservice distributors. Direct-to-bakery e-procurement platforms in Poland and Czechia are disintermediating traditional distributors for just-in-time bulk deliveries.
- Stick:Individually wrapped quarter-pound units mimicking butter portioning for recipe-measurement convenience.
- Pouch:Flexible film packaging for single-serve hospitality portions and airline catering applications.
Tub anchors household penetration while bulk expands most quickly through foodservice digitization.
End User:
Application requirements fragment demand across performance specifications, with bakeries demanding functional precision and restaurants prioritizing operational simplicity.
- Bakeries:Craft and industrial operations requiring precise melting profiles and emulsion stability for laminated doughs. France and Italy lead artisan adoption for plant-based menu certification, while frozen bakery channels impose freeze-thaw cycle requirements.
- Households:Retail consumers purchasing through supermarkets and discount channels. Clean-label preferences in Germany dominate purchasing decisions, with sodium reduction claims increasingly influential.
- Restaurants:Full-service and limited-service operations using margarine for cooking, grilling, and finishing.
- Foodservice:Institutional caterers, hotels, and centralized kitchen operations procuring through broadline distributors.
Households anchor the consumer volume base while bakeries drive premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in vegan margarine tilt toward net-exporting European manufacturers while import-dependent markets in Eastern Europe and Asia-Pacific absorb surplus capacity. Currency-adjusted margins favor producers with captive oilseed crushing near Rotterdam and Hamburg port complexes. Regulatory divergence between EU Green Deal compliance zones and non-aligned markets fragments pricing power across borders.
Germany
Clean-label retail preferences concentrate demand in discounter channels where sodium reduction claims determine shelf placement. EFSA front-of-pack labeling mandates accelerate reformulation timelines for spreadable tub formats. Bavaria-based bakery cooperatives are consolidating procurement around single-source suppliers with batch-level organic certification.
France
Artisan bakery chains drive block-format adoption for laminated dough applications requiring precise melting profiles. ANSM nutritional disclosure requirements align with EU-wide sodium targets while preserving traditional recipe exemptions. Paris basin industrial bakeries are retrofitting production lines for plant-based menu certification ahead of 2027 hospitality procurement deadlines.
Netherlands
Rotterdam port infrastructure anchors European oilseed import flows while biotech clusters near Delft scale precision fermentation capacity. REACH substance restrictions filter additive approvals for emulsifier alternatives. North Holland foodservice distributors are digitizing procurement interfaces to disintermediate traditional broadline channels for mid-size bakery chains.
Poland
Modern grocery expansion in Warsaw and Kraków creates first-mover shelf space for premium tub formats previously limited to Western European distribution. National food safety authority alignment with EFSA standards accelerates import qualification timelines. Silesian industrial baking clusters are testing direct-to-bakery e-procurement platforms for just-in-time bulk deliveries.
Italy
Craft bakery certification programs in Emilia-Romagna and Lombardy sustain block-format premiums for clean-label menu positioning. Ministry of Health transposes EU nutritional labeling standards with regional enforcement variation across northern production zones. Turin-based frozen bakery channels are demanding modified emulsion formulations for freeze-thaw stability in laminated applications.
Vegan Margarine Market Competitive Landscape
Listed leaders compete with private specialists across sustainability certification depth and fermentation technology access. Market structure tilts toward consolidated procurement power at the foodservice tier while retail fragmentation persists across private-label and branded positioning. Three archetypes dominate: multinational consumer goods conglomerates with retail shelf control, regional oilseed processors with backward integration into crushing, and biotech-anchored specialists scaling precision fermentation. Capacity expansion and strategic partnerships with fermentation technology licensors constitute the dominant competitive moves.
Within the biotech-specialist tier, Miyoko's Creamery and Upfield occupy positions representing alternative pathways to deforestation-free supply chains. Among diversified conglomerates, Unilever exemplifies mass-market channel leverage. Wilmar International and Bunge Limited anchor the oilseed-processor archetype with upstream control over tropical and temperate oil sourcing. EFKO Group and FUJI OIL HOLDINGS INC. sit within regional processing clusters serving adjacent food manufacturing verticals.
| Leading Market Players |
|---|
| Upfield |
| Conagra Brands |
| Unilever |
| Bunge Limited |
| Wilmar International |
| Miyoko's Creamery |
| Nutiva |
| EFKO Group |
| FUJI OIL HOLDINGS INC. |
| Others |
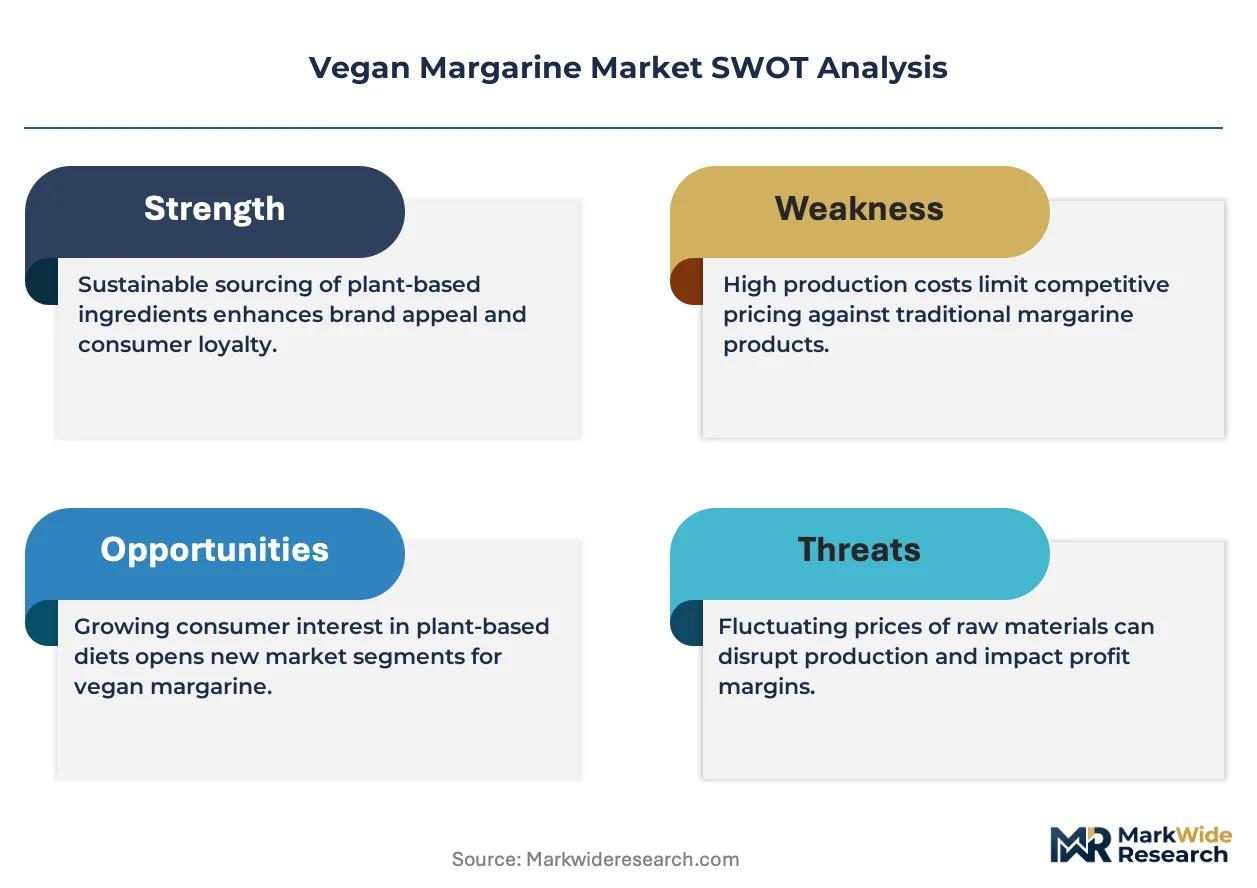
Value Network & Pricing Analysis
Rotterdam port capacity utilization above 85% anchors European oilseed processing economics, compressing unit costs for manufacturers with captive crushing while forcing import-dependent blenders toward price floors set by Black Sea sunflower oil volatility.
Pricing Analysis
Industrial bakery buyers anchor contract-based long-term offtake structures across the vegan margarine value chain. Three-tier pricing structure across organic certified, RSPO-segregated, and conventional emulsified grades separates premium fermentation-derived fats from commodity oil blends. Cost compression in standard-tier spreads is intensifying because German discount retailers are consolidating procurement around single-source suppliers. Artisan bakery chains exhibit lowest price sensitivity due to menu certification requirements, while frozen bakery channels face acute pressure from fixed-price retail contract exposure.
Supply Chain Analysis
Strategic stockpile preferences dominate among European manufacturers confronting Black Sea supply disruptions, whereas just-in-time bulk deliveries through direct-to-bakery e-procurement platforms are gaining traction in Poland and Czechia. Geographic supply concentrates in Germany, Netherlands, and Indonesia for RSPO-certified palm oil inputs, with rapeseed and sunflower oil drawing from Black Sea and North European temperate zones. Raw material dependencies rest on vegetable oil feedstocks, lecithin emulsifiers, and fermentation-derived fat precursors. Single-source vulnerability in Southeast Asian palm oil concentration exposes buyers to sustainability audit risks. Distribution runs through Rotterdam and Hamburg port complexes into foodservice distributor networks and modern grocery retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan margarine markets reward defensive positioning through regulatory entrenchment, where EU Green Deal compliance timelines and REACH substance restrictions create switching costs that lock in qualified suppliers ahead of 2027 deadlines.
For Market Incumbents: Secure backward integration into organic oilseed crushing and in-house fermentation capacity to defend against precision fermentation specialists displacing conventional blenders. Expand batch-level sustainability documentation capabilities to meet EU CSRD Scope 3 disclosure mandates driving foodservice procurement consolidation. Prioritize certification investment in palm-free supply chains as RSPO audit risks intensify buyer preference for verified alternatives. For New Entrants and Emerging Players: RSPO-IP fast-track certification unlocks shelf placement in German discount channels where incumbent supply shortages create white-space opportunities. Target Polish modern grocery expansion in Warsaw and Kraków for premium tub format penetration previously limited to Western European distribution. Emphasize direct-to-bakery digital procurement interfaces as the go-to-market angle to disintermediate traditional foodservice distributors for mid-size bakery chains. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with captive organic oilseed processing and multi-year bakery chain contracts. Long-term viability favors biotech-anchored specialists scaling precision fermentation capacity over commodity oil blenders facing margin compression from vegetable oil price volatility. Watch fermentation scale-up talent scarcity in Denmark and Netherlands as the inflection indicator for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Danish and Dutch biotech clusters are achieving functional parity with conventional oil blends while eliminating deforestation linkages. |
| Organic Oilseed Backward Integration | Captive crushing near Rotterdam and Hamburg port complexes secures supply chain control against Black Sea price volatility. |
| Direct-to-Bakery E-Procurement Launch | Digital ordering interfaces in Poland and Czechia disintermediate traditional distributors for just-in-time bulk deliveries. |
| RSPO-IP Certification Investment | Segregated palm oil certification meets EU Green Deal sustainability mandates ahead of 2027 compliance deadlines. |
| Sodium Reduction Reformulation Program | Potassium chloride substitution aligns spreadable tub formats with EFSA front-of-pack disclosure mandates in German retail. |
Research Methodology
Operator-level perspectives from bakery procurement directors, foodservice distribution executives, plant-based R&D formulators, and retail category buyers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with fermentation technology licensors and oilseed processing specialists, validated against secondary sources including EFSA regulatory filings, REACH substance restriction updates, EU CSRD disclosure guidance, and customs trade flow data for vegetable oil imports. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from production capacity and channel throughput analysis.
Sensitivity analysis across price elasticity assumptions and regulatory compliance timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, formulation grade, packaging format, end-use application, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume movements adjusted for structural shifts in procurement digitization and sustainability certification penetration. Industry-specific forecast inputs incorporated bakery chain contract renewal patterns and organic oilseed conversion timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and stable Black Sea oilseed supply; material deviation would warrant model refresh. Forecasts reflect assumptions of fermentation technology scale-up feasibility and retailer shelf placement continuity for certified organic positioning. Revision becomes warranted when vegetable oil price volatility crosses thresholds that trigger contract renegotiation cascades or when fermentation talent scarcity constrains capacity expansion below bakery chain RFP specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Soy Protein Market