
 United States Hemp Protein Market | 2026-2036
United States Hemp Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hemp Protein Market Analytics
Multi-source contracting across hemp seed suppliers is restructuring procurement economics for U.S. protein processors. Manitoba Harvest Hemp Foods anchors its position through backward integration into Canadian-U.S. cross-border cultivation partnerships. Victory Hemp Foods differentiates via specialized processing of hemp heart protein for beverage applications. Navitas LLC competes in the organic specialty channel with certified supply chains that command shelf-space premiums.
Hemp protein comprises the defatted meal remaining after oil extraction from Cannabis sativa seeds, typically yielding 50% protein by weight with a complete amino acid profile including edestin and albumin fractions. Its primary commercial purpose centers on fortifying plant-based foods, powders, and baked goods with digestible protein that avoids major allergens. Hemp seed protein leads volume due to established oil-crushing infrastructure, while isolate protein captures the fastest growth as beverage formulators seek neutral flavor and solubility. Full spectrum protein retains fiber and omega content, occupying the premium nutritional supplements tier where clean-label positioning sustains margin pools.
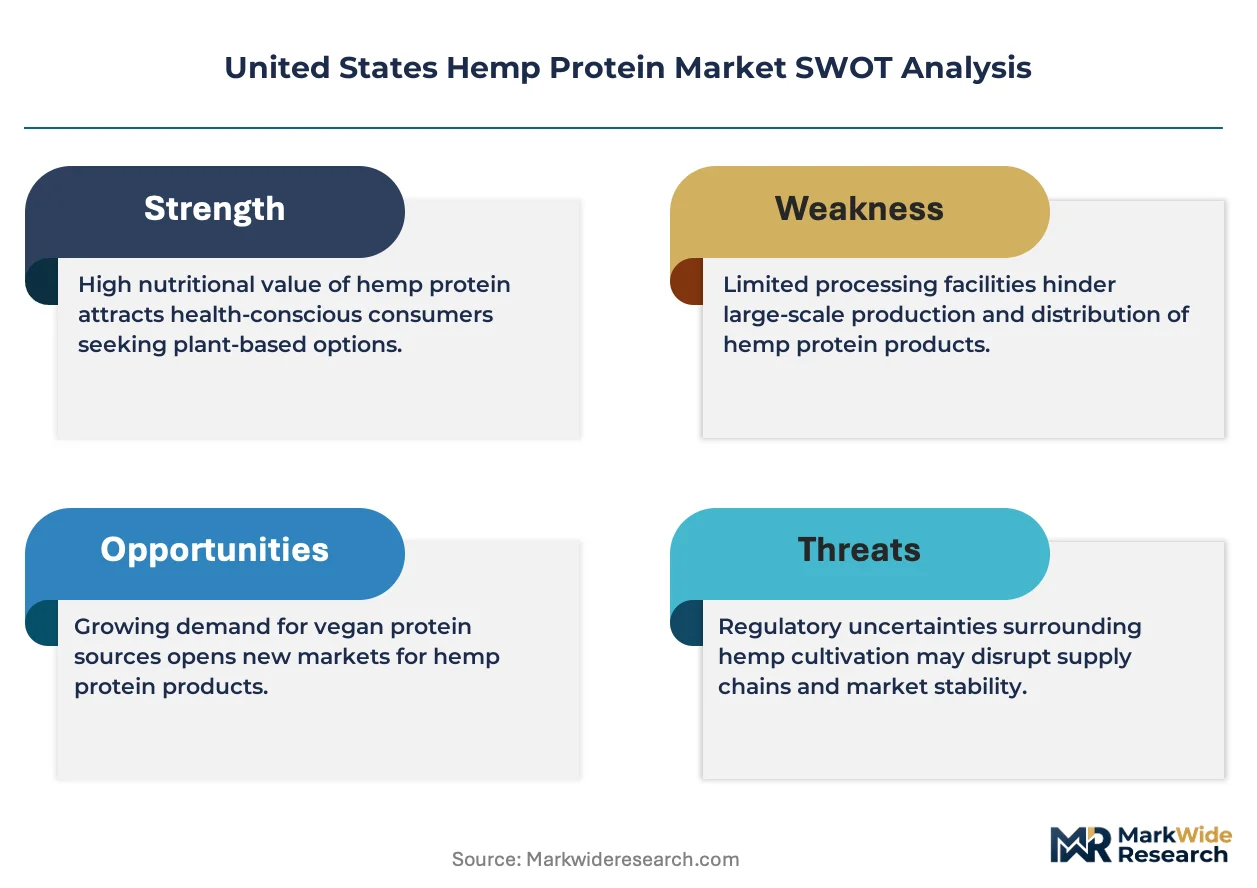
The USDA oversees hemp cultivation compliance through THC testing protocols that determine legal market access for raw material flows. FDA guidance on cannabinoid-containing foods creates uncertainty at the intersection of hemp protein and CBD-adjacent products, shaping reformulation decisions by food manufacturers. State agriculture departments in Colorado and Kentucky operate parallel certification programs that expedite processor licensing. Stakeholders must monitor pending FDA rulemaking on hemp-derived ingredients in conventional foods, as clarity will determine capital deployment into expanded milling and fractionation capacity.
Market Dynamics
The USDA's interim final rule on hemp production has streamlined interstate commerce, concentrating procurement power among processors in Colorado and Kentucky where state-level infrastructure has matured fastest.
Growth Catalysts
- Clean-label protein demand:Sports nutrition brands and plant-based food manufacturers are expanding procurement of hemp-derived ingredients to meet consumer preference for allergen-free, minimally processed protein sources.
- USDA compliance pathways:The federal THC testing protocol has reduced legal uncertainty for cultivators, enabling scaled raw material flows into protein processing facilities.
- Fiber-retaining formulations:Full spectrum protein products that retain omega content and dietary fiber are commanding premium shelf positioning in nutritional supplements.
Market Restraints
- Input cost volatility:Hemp seed prices fluctuate with Canadian-U.S. cross-border harvest yields and currency exchange rates, compressing processor margins.
- Supply concentration risk:Oil-crushing infrastructure for hemp seed protein concentrates in the Upper Midwest and Prairie provinces creates geographic dependency for domestic processors.
- Regulatory friction:FDA guidance ambiguity on cannabinoid-containing foods forces reformulation caution at the intersection of hemp protein and CBD-adjacent product lines.
Strategic Opportunities
- Isolate protein beverages:Neutral-flavor, high-solubility hemp protein isolate represents underexploited white space for beverage formulators seeking plant-based alternatives to soy and pea.
- State certification arbitrage:Kentucky and Colorado agriculture departments operate expedited processor licensing programs that reduce time-to-market for compliant operators.
- Baked goods fortification:Hemp heart protein's functional properties in moisture retention and texture modification open formulation partnerships with artisan and commercial bakeries.
Industry Challenges
- Fractionation capex requirements:Commercial-scale protein isolate production demands investment in specialized milling and solvent-free extraction equipment that mid-tier processors struggle to finance.
- Cross-contamination protocols:Facilities handling both hemp protein and CBD extracts must maintain segregated processing lines, extending compliance timelines and facility design costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hemp Protein Market |
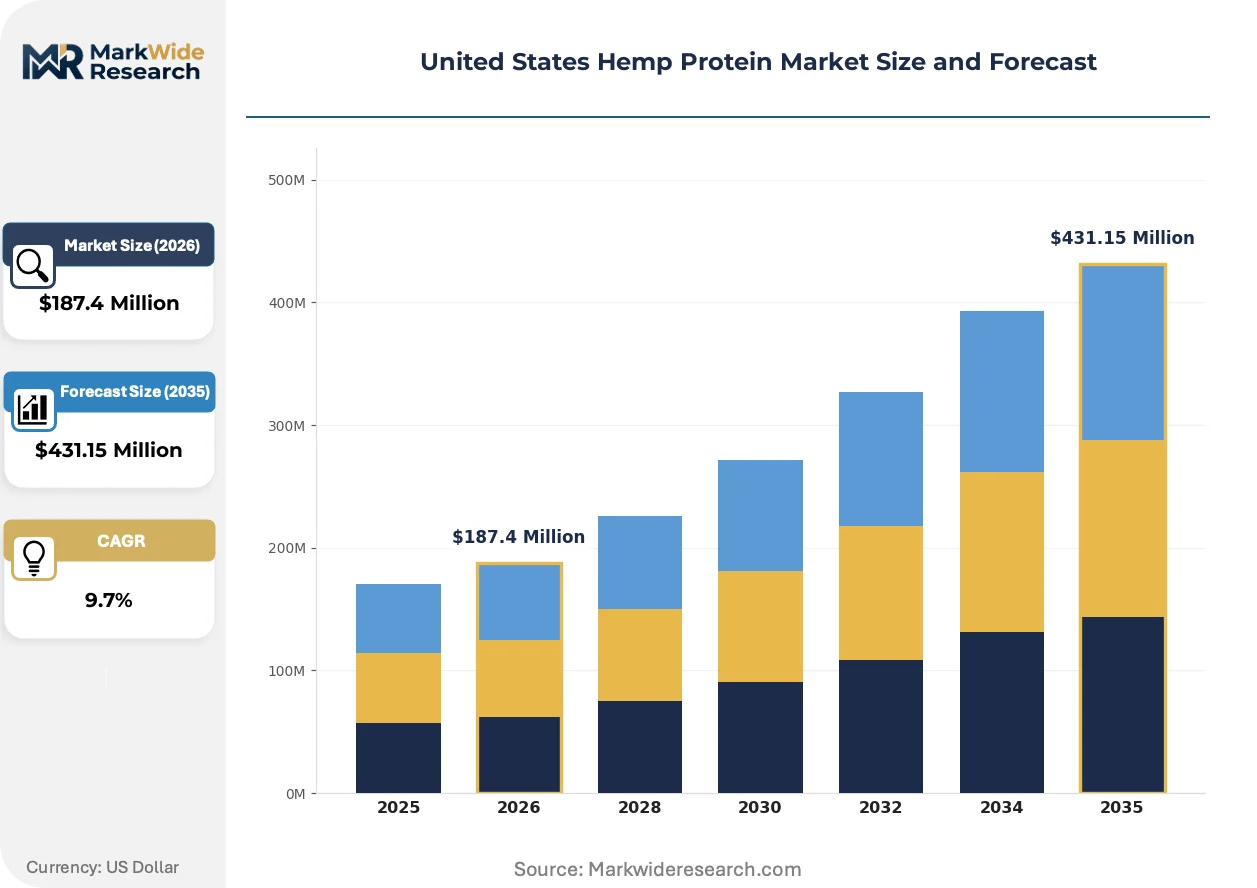
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp Seed Protein, Full Spectrum Protein, Isolate Protein, Concentrate Protein End User: Health Conscious Consumers, Fitness Enthusiasts, Vegan Dieters, Food Manufacturers Application: Food & Beverages, Nutritional Supplements, Cosmetic Products, Bakery Items Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Axiom Foods Inc., Manitoba Harvest Hemp Foods, ETChem Co., Tilray Brands Inc., North American Hemp & Grain Co. Ltd., Victory Hemp Foods, Navitas LLC, Nutiva, NOW Foods LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hemp Protein Market Evolving Landscape
Processing technology and regulatory clarity are converging to reshape competitive positioning across the hemp protein value chain, with implications for product form, procurement geography, and channel strategy.
Micro-milling and air-classification systems are integrating into hemp protein production lines to achieve particle sizes below 100 microns, improving mouthfeel and dispersibility. Beverage manufacturers in the plant-based dairy alternative segment are adopting these refined isolates at accelerating rates. The technology is integrating previously separate oil extraction and protein fractionation operations into continuous-flow configurations that reduce handling losses.
The FDA's pending rulemaking on hemp-derived ingredients in conventional foods is creating preparatory investment cycles among manufacturers. Food companies are restructuring supply agreements to include contingent sourcing clauses that activate upon regulatory clarity. Protein processors in Kentucky and Colorado are most affected, with state agriculture departments accelerating facility certifications to capture first-mover advantage when federal guidance finalizes.
Direct contracting between protein processors and regional bakery chains is displacing traditional ingredient distributor relationships for hemp-derived fortification. Smaller craft bakeries in the Mountain West and Pacific Northwest are establishing multi-year procurement commitments that bypass conventional foodservice distribution. This pattern is most visible in Colorado, where state-level hemp processing infrastructure supports localized supply chains with shorter lead times than national ingredient distributors can match.
United States Hemp Protein Market Segmentation
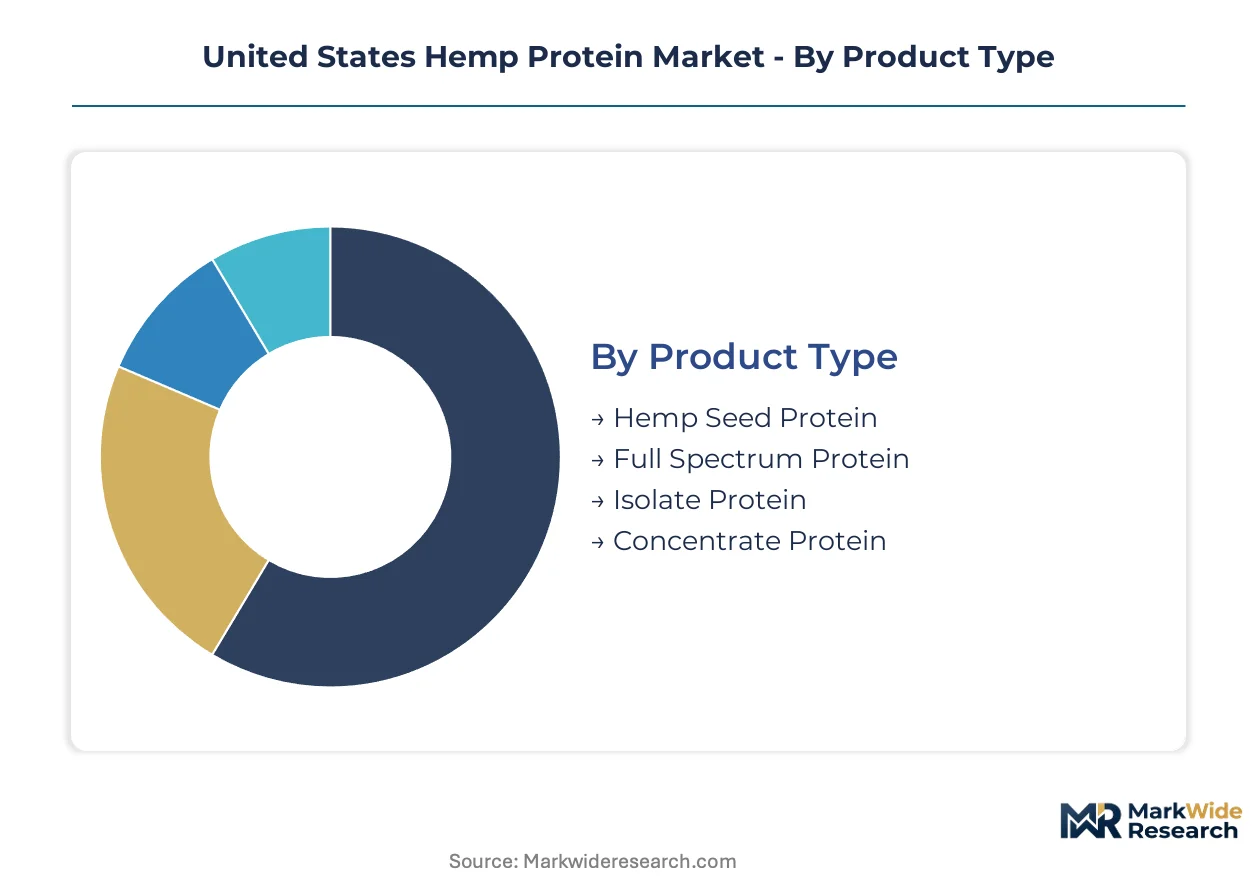
Hemp protein segmentation reflects divergent paths between commodity-scale oil-crushing byproducts and precision-fractionated isolates commanding formulation premiums. Product architecture, end-user priorities, and channel economics create distinct competitive arenas requiring specialized supply chain configurations.
Product Type:
Volume concentrates in established oil-extraction infrastructure, while premium capture shifts toward functional isolates with solubility and neutral-flavor specifications.
- Hemp Seed Protein:Defatted meal remaining after cold-press oil extraction, typically yielding 50% protein content with retained fiber fractions. Demand concentrates in Colorado and Kentucky bakery fortification applications where regional crushing facilities minimize transport costs. State-level processing maturation sustains cost-competitive positioning against imported Canadian supply.
- Isolate Protein:Micro-milled and air-classified fractions achieving 90%+ protein concentration with particle sizes below 100 microns for beverage dispersibility. Sports nutrition formulators in the plant-based dairy alternative segment are accelerating procurement as neutral-flavor specifications displace pea and soy alternatives. Fractionation capex requirements limit supplier base to vertically integrated processors.
- Full Spectrum Protein:Retains omega fatty acids, chlorophyll, and fiber content for premium nutritional supplements positioning.
- Concentrate Protein:Intermediate 60-70% protein grade serving cost-sensitive powder applications.
Today's leader: Hemp Seed Protein. Tomorrow's challenger: Isolate Protein.
End User:
Procurement authority fragments between direct-to-consumer wellness positioning and industrial-scale ingredient sourcing for reformulated product lines.
- Food Manufacturers:Industrial buyers integrating hemp protein into commercial bakery, snack, and alternative dairy formulations at scale. Procurement concentrates among Mountain West and Pacific Northwest regional bakery chains establishing multi-year direct contracts with Kentucky and Colorado processors. USDA compliance documentation requirements favor suppliers with state-level certification programs.
- Vegan Dieters:Consumers seeking complete amino acid profiles without major allergens, driving specialty channel premiums. Demand clusters in urban coastal markets where clean-label positioning commands shelf-space allocation in independent health food retail.
- Health Conscious Consumers:Broad wellness segment prioritizing minimally processed, fiber-retaining protein sources.
- Fitness Enthusiasts:Sports nutrition purchasers focused on post-workout recovery applications and macronutrient density.
Food Manufacturers consolidate procurement volume. Vegan Dieters expand the premium tier fastest.
Application:
Functional requirements differentiate between mouthfeel-critical beverage systems and texture-tolerant baked matrices.
- Food & Beverages:Plant-based dairy alternatives and functional beverages requiring solubility, emulsion stability, and neutral flavor profiles. Hemp heart protein from specialized processors is displacing soy in Colorado-based beverage manufacturing. FDA pending rulemaking on hemp-derived ingredients is restructuring supply agreements to include contingent sourcing clauses.
- Nutritional Supplements:Powder and capsule formats prioritizing complete amino acid profiles including edestin and albumin fractions. Full spectrum protein retains premium positioning through clean-label omega content retention.
- Bakery Items:Moisture retention and texture modification in artisan and commercial bread applications.
- Cosmetic Products:Topical formulations leveraging hemp protein amino acid content for skin barrier applications.
Beverage applications are climbing the fastest. Bakery fortification anchors volume throughput.
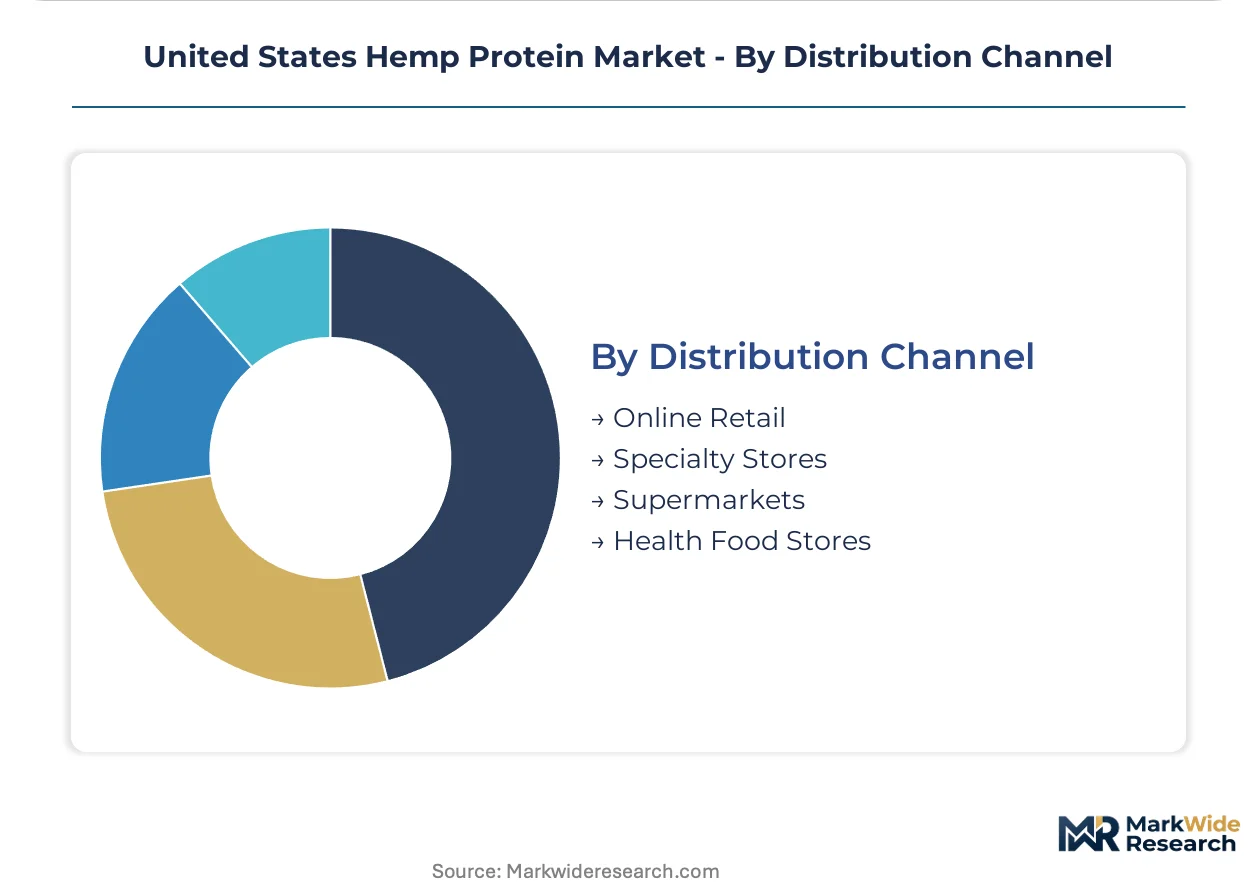
Distribution Channel:
Channel strategy bifurcates between national scale efficiency and localized supply chain compression.
- Online Retail:Direct-to-consumer platforms capturing specialty isolate and organic-certified product premiums. Subscription models concentrate among fitness enthusiasts seeking automated replenishment of flavored protein powders.
- Specialty Stores:Independent health food retailers in the Pacific Northwest and Mountain West curating regional hemp processor products with provenance storytelling.
- Supermarkets:Mass retail placement for hemp seed protein in conventional grocery baking and supplement aisles.
- Health Food Stores:Chain and franchise locations prioritizing certified organic and non-GMO verified SKUs.
Online Retail commands premium pricing power. Specialty Stores compress lead times through direct processor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mountain West processing corridor anchors domestic hemp protein capacity, with state-level infrastructure maturation compressing lead times for regional bakery and beverage manufacturers.
Colorado
Denver-Boulder corridor processors command procurement volume from regional craft bakeries and plant-based dairy startups. The Colorado Department of Agriculture operates an expedited hemp processor licensing program that reduces certification timelines versus federal baseline requirements. Fort Collins milling clusters integrate oil extraction and protein fractionation into continuous-flow configurations serving Mountain West distribution networks.
Kentucky
Bluegrass region crushing facilities supply defatted meal to commercial bakery chains across the Southeast and Mid-Atlantic. Kentucky's industrial hemp research program at the University of Kentucky provides cultivar development support that stabilizes seed oil content for protein yield optimization. Louisville-area processors leverage Ohio River logistics for bulk ingredient transport to food manufacturers in Ohio and Indiana.
California
Los Angeles and San Francisco Bay Area beverage formulators drive isolate protein demand for plant-based dairy alternatives. California Department of Public Health regulations on hemp-derived ingredients in conventional foods create contingent sourcing clauses in supply agreements pending federal clarity. Sacramento Valley oil-crushing infrastructure serves regional nut and seed processors expanding into hemp protein co-products.
Oregon
Willamette Valley cultivator networks supply raw seed to Portland-area protein processors specializing in organic certification. Oregon Department of Agriculture hemp rules align with USDA interim final protocols while maintaining state-level THC testing laboratories that accelerate compliance documentation. Eugene specialty millers focus on full spectrum protein retention for Pacific Northwest health food retail channels.
North Carolina
Research Triangle food science programs support hemp protein formulation partnerships with regional snack manufacturers. North Carolina State Extension's industrial hemp initiative provides technical assistance to processors scaling from pilot to commercial capacity. Charlotte-area distribution hubs connect Southeast bakery chains to Kentucky and Colorado processor supply.
United States Hemp Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue isolate protein specialization and organic certification premiums. The supplier base stratifies across three maturity levels: legacy oil-crushing operators with defatted meal byproducts, mid-tier fractionators investing in micro-milling capacity, and venture-backed isolates specialists targeting beverage applications. Strategic archetypes include backward-integrated cultivator-processors, toll-manufacturing specialists, and brand-house formulators. Competitive intensity concentrates on capacity expansion in Kentucky and Colorado plus contingent supply agreements hedging FDA regulatory uncertainty.
Among North American processor groups, Manitoba Harvest Hemp Foods and Victory Hemp Foods exemplify divergent specialization paths within the category. Manitoba Harvest anchors the integrated cultivator-processor archetype through cross-border supply chain control. Victory Hemp Foods occupies the application-specific tier focused on beverage-grade isolate production. Navitas LLC sits within the organic specialty channel where certified supply chains command retail shelf-space premiums. ETChem Co. and Tilray Brands Inc. represent adjacent-industry entrants leveraging extraction infrastructure and regulatory compliance capabilities from cannabinoid-adjacent operations.
| Leading Market Players |
|---|
| Axiom Foods Inc. |
| Manitoba Harvest Hemp Foods |
| ETChem Co. |
| Tilray Brands Inc. |
| North American Hemp & Grain Co. Ltd. |
| Victory Hemp Foods |
| Navitas LLC |
| Nutiva |
| NOW Foods LLC |
| Others |
Value Network & Pricing Analysis
Backward integration into Canadian-U.S. cross-border cultivation partnerships anchors both supply security and pricing power for dominant processors. This upstream control insulates margin pools from currency-driven input volatility while positioning integrated operators to capture premium-tier spreads in isolate protein formulations.
Pricing Analysis
Input-cost pass-through from hemp seed procurement to finished protein runs through Canadian harvest yields and exchange-rate fluctuations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with organic-certified isolates commanding shelf-space premiums. Cost compression in standard-grade concentrates is intensifying because oil-crushing infrastructure operates on thin byproduct economics. Food manufacturers exhibit highest price sensitivity due to reformulation volume requirements, while sports nutrition brands show lowest sensitivity for neutral-flavor isolate specifications.
Supply Chain Analysis
USDA THC testing certification and state-level processor licensing gate market access for raw material flows. Supply concentrates in Canada, Colorado, and Kentucky, with seed stock drawing from Prairie province cultivators and Bluegrass region research programs. The chain rests on cold-press oil extraction equipment, micro-milling systems, and air-classification technology. Single-source vulnerability concentrates in Upper Midwest oil-crushing infrastructure. Distribution runs through direct contracts between processors and regional bakery chains, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in U.S. hemp protein hinges on isolate protein premiumization and fractionation capex efficiency. FDA regulatory clarity will unlock capital deployment into expanded milling capacity.
For Market Incumbents: Extend backward integration into captive seed supply through multi-year cultivation contracts in Kentucky and Colorado. Add micro-milling capacity in Fort Collins and Louisville corridors before FDA rulemaking finalizes. Defend against beverage-formulator substitution to pea and soy by locking exclusive isolate supply agreements with plant-based dairy startups. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to entry for organic-certified full spectrum protein. Target Pacific Northwest specialty retail with provenance storytelling that bypasses national distributor markups. Pursue toll-manufacturing partnerships with underutilized oil-crushing facilities to avoid fractionation equipment capex. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier fractionators because state certification arbitrage creates geographic moats. Five-to-ten year viability favors processors with USDA-compliant documentation and beverage-grade isolate capabilities. Watch FDA pending rulemaking on hemp-derived ingredients in conventional foods as the signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Supply | Captive cultivation contracts in Kentucky and Colorado insulate margin pools from Canadian currency volatility. |
| Micro-Milling Capacity Expansion | Fort Collins and Louisville milling clusters integrate oil extraction and protein fractionation into continuous-flow configurations. |
| Direct-to-Consumer Channel Launch | Subscription models bypass national distributor markups and capture organic-certified premiums in fitness enthusiast segments. |
| State Certification Arbitrage | Kentucky and Colorado expedited licensing programs reduce time-to-market versus federal baseline requirements. |
| Beverage Formulator Partnership | Exclusive isolate supply agreements with plant-based dairy startups defend against pea and soy substitution. |
Research Methodology
Multiple input streams — executive interviews with protein processors, procurement leads at regional bakery chains, and regulatory affairs specialists — were reconciled against secondary validation. Primary fieldwork included plant managers at Colorado and Kentucky crushing facilities, category buyers at Mountain West specialty retailers, and compliance officers navigating USDA THC testing protocols. Secondary sources encompassed FDA guidance documents, USDA interim final rule filings, state agriculture department licensing records, and customs data on Canadian hemp seed imports. Bottom-up volume builds and top-down market sizing were cross-checked for triangulation.
Data-stream reconciliation across product type, end user, application, and distribution channel dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs included state-level processing infrastructure maturation curves, FDA rulemaking probability assessments, and beverage formulation substitution elasticities across the projection horizon.
Regulatory delay, input cost volatility, and fractionation technology adoption gaps are the dominant revision risks. Deviation in FDA rulemaking timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market