
 China Plant-Based Food and Beverages Market | 2026-2036
China Plant-Based Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
China Plant-Based Food and Beverages Market Outlook
Ingredient sourcing and formulation partnerships between dairy incumbents and protein technology startups is rewriting profit allocation across the China plant-based value chain. Yili Group leverages its refrigerated distribution network to secure shelf dominance in northern provinces. Vitasoy International Holdings Ltd. anchors its position through decades of soy milk brand equity in Greater China retail. Oatly Group AB competes by positioning oat milk as a coffee-shop standard rather than a grocery alternative.
China plant-based food and beverages encompass formulated products derived from extracted, fermented, or texturized plant proteins designed to replicate the sensory and nutritional profiles of animal-derived foods, typically requiring protein content above 2.5% and fat emulsion stability for mouthfeel replication. Their primary commercial purpose is to serve as direct substitutes in mainstream consumption occasions ranging from daily nutrition to foodservice ingredient applications. Plant-based milk retains the largest volume footprint yet faces margin compression from private-label entrants, while meat alternatives command premium pricing due to extrusion technology barriers and limited domestic equipment suppliers. Online retail channels are expanding fastest among distribution pathways, though supermarkets still capture the majority of consumer trial purchases through end-cap placement and chilled cabinet access.
SAMR food labeling requirements and GB standards for plant protein beverages establish compositional thresholds that filter out subscale producers, while the NHC dietary guidelines create institutional endorsement for reduced-animal-protein consumption patterns. CSRD-aligned sustainability disclosures from European-headquartered parent companies of China operating units are additionally reshaping procurement specifications for ingredient traceability. Stakeholders must monitor whether domestic extrusion equipment manufacturers can close technology gaps with European suppliers before capacity expansion timelines accelerate.
Market Dynamics
Dual carbon goals are compressing investment timelines across the China plant-based value chain, forcing processors to retrofit facilities for energy-intensive extrusion and fermentation before 2030 compliance deadlines lock in.
Growth Catalysts
- NHC Dietary Guidelines:The National Health Commission's reduced meat consumption recommendations create institutional legitimacy for plant-based alternatives in institutional catering and school nutrition programs.
- Quick-service restaurant expansion:Tier-one city chains are integrating oat milk and plant-based meat into standard menus, normalizing trial among urban flexitarian consumers.
- Extrusion technology maturation:Domestic equipment manufacturers are closing gaps with European suppliers, enabling localized production of textured vegetable proteins at scale.
Market Restraints
- Protein isolate import dependency:Pea and fava bean protein concentrates rely on North American and European supply, exposing formulators to freight volatility and currency risk.
- GB standards compliance costs:SAMR labeling requirements and compositional thresholds for plant protein beverages filter out subscale producers, consolidating shelf access around capitalized incumbents.
- Sensory replication gaps:Fat emulsion stability in high-heat applications remains technically constrained, limiting meat alternative penetration in traditional Chinese cooking methods.
Strategic Opportunities
- Lower-tier city penetration:Shanghai, Beijing, and Shenzhen saturation creates expansion corridors into Chengdu, Hangzhou, and Wuhan where chilled distribution infrastructure is maturing.
- Foodservice ingredient positioning:Oat milk is migrating from coffee-shop standard to bakery and dessert manufacturing applications, opening B2B volume contracts.
- CSRD-aligned procurement:European-headquartered parent companies of China operating units are mandating ingredient traceability disclosures, creating premium positioning for certified sustainable suppliers.
Industry Challenges
- Extrusion engineering talent scarcity:Domestic universities produce limited specialists in high-moisture extrusion process control, forcing reliance on foreign technical consultants.
- Chilled distribution capex intensity:Plant-based milk requires refrigerated cabinet placement and cold-chain integrity, demanding substantial working capital for slotting fees and fleet expansion.
- Cross-labeling compliance complexity:Dual positioning as both dairy alternative and functional beverage triggers overlapping GB standards, extending product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plant-Based Food and Beverages Market |
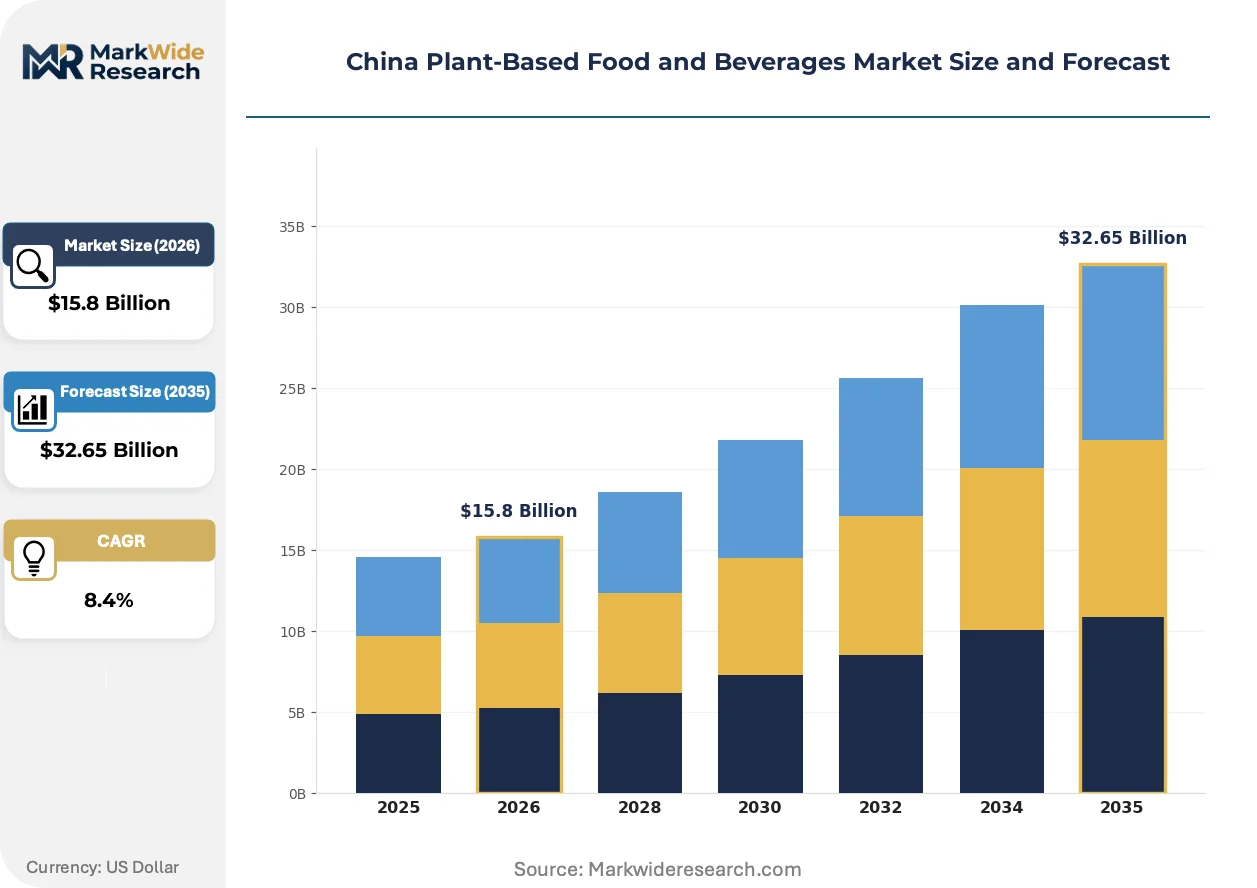
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $32.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Milk, Meat Alternatives, Vegan Snacks, Plant-Based Yogurt Ingredients: Pea Protein, Soy Protein, Almond, Oat Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Consumer Type: Health Conscious Consumers, Vegans, Vegetarians, Flexitarians |
| Companies Covered | Yili Group, The Livekindly Company Inc., Green Monday Group, Whole Perfect Foods, Vitasoy International Holdings Ltd., Qishan Foods, Oatly Group AB, Unilever PLC (The Vegetarian Butcher), Zhenmeat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plant-Based Food and Beverages Market Strategic Shifts
Formulation science and regulatory architecture are converging to redefine competitive moats in China's plant-based sector, with sensory fidelity and carbon accounting replacing price as primary purchase determinants.
Fermentation-derived proteins are migrating from niche ingredient to mainstream formulation backbone. Precision fermentation startups are supplying dairy-identical proteins to ice cream and yogurt manufacturers. This shift is compressing the functional gap between plant-based and animal-derived nutrition labels, enabling clean-ingredient claims without sensory compromise.
GB standards for plant protein beverages are tightening compositional thresholds under SAMR oversight. The revised frameworks mandate minimum protein content and restrict additive portfolios. Beverage categories face reformulation cycles, with soy milk incumbents accelerating R&D spending to maintain shelf positioning against oat and pea entrants.
Flexitarian consumption patterns are rotating demand toward hybrid formulations rather than pure substitutes. Food manufacturers are blending animal and plant proteins in processed meats and bakery applications. Shanghai and Beijing quick-service operators report stronger repeat purchase rates for blended SKUs than for 100% plant-based equivalents, suggesting a permanent category architecture shift.
China Plant-Based Food and Beverages Market Segmentation
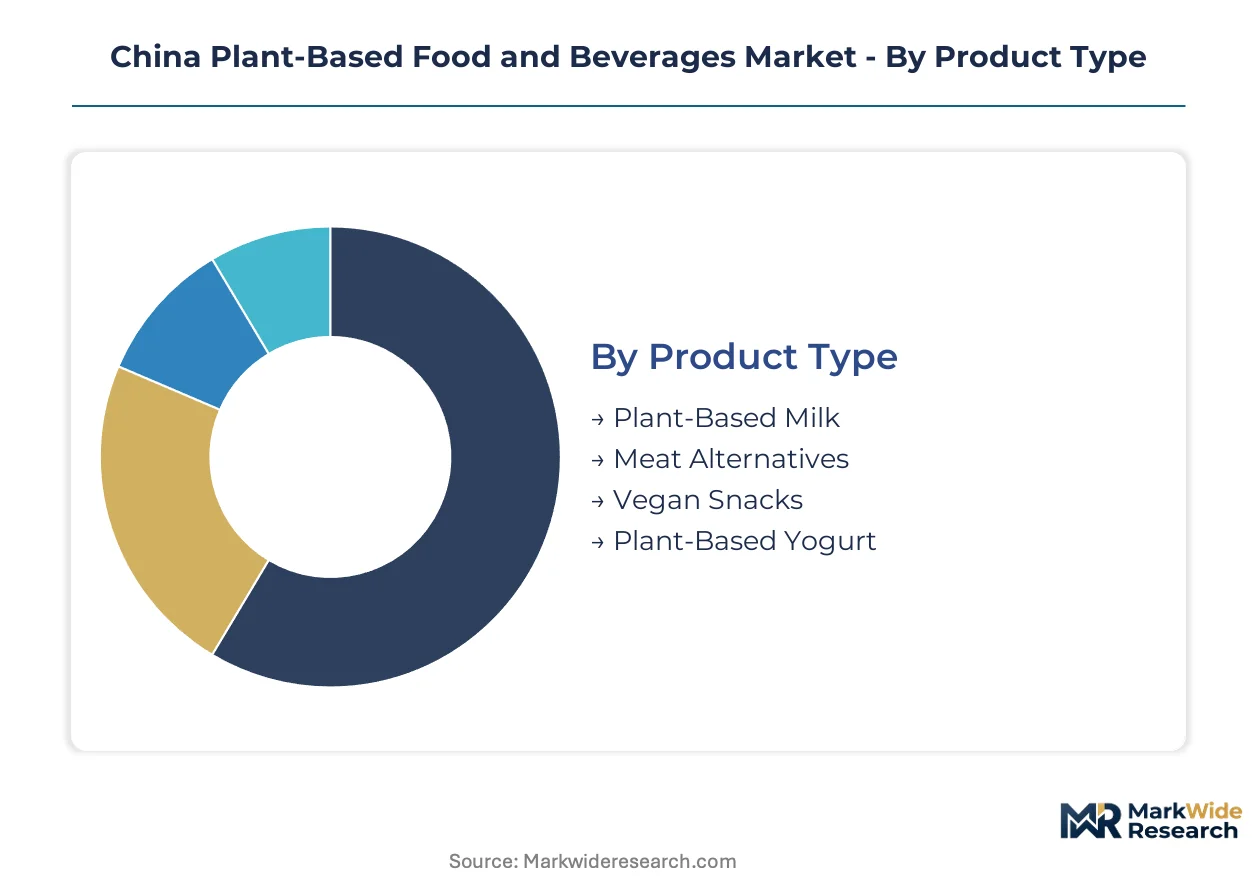
Product differentiation in China's plant-based sector follows distinct velocity patterns. Formulation complexity and cold-chain requirements create divergent replenishment cycles across categories.
Product Type:
Plant-based milk turns inventory fastest due to daily consumption frequency, while meat alternatives move slowest given higher price points and trial hesitation.
- Plant-Based Milk:Formulated beverages with protein content above 2.5% and fat emulsion stability for mouthfeel replication. Shanghai and Beijing quick-service coffee chains drive volume through oat milk standardization, though private-label entrants compress margins in northern provinces.
- Meat Alternatives:Extruded or texturized proteins replicating animal muscle structure and sensory profiles. Tier-one city restaurant chains normalize trial among flexitarian segments, yet high-heat cooking applications expose fat emulsion stability gaps.
- Vegan Snacks:Shelf-stable formulated products targeting on-the-go consumption occasions.
- Plant-Based Yogurt:Fermented analogs requiring chilled distribution and live culture maintenance.
Plant-based milk anchors the volume base while meat alternatives gain share at the steepest rate.
Ingredients:
Input costs stratify sharply — commodity soy concentrates trade at substantial discounts to imported pea isolates.
- Pea Protein:North American and European-sourced isolates with complete amino acid profiles. Formulators face freight volatility and currency exposure, though extrusion technology maturation enables localized textured vegetable protein production.
- Soy Protein:Domestic supply chains with decades of processing infrastructure. Vitasoy International Holdings Ltd. leverages brand equity across Greater China retail, while GB standards compliance filters subscale producers.
- Almond:Water-intensive cultivation concentrated in California supply regions.
- Oat:Scandinavian processing technology dominates functional beta-glucan extraction.
Soy protein commands the installed production base while oat climbs fastest among emerging formulations.
Distribution Channel:
Cold-chain intensity separates capital requirements — online retail avoids slotting fees but demands last-mile refrigeration investment.
- Online Retail:Direct-to-consumer platforms with subscription mechanics and temperature-controlled logistics. Tier-one city penetration enables trial among digitally native flexitarians, though fulfillment economics strain outside Beijing-Shanghai-Shenzhen corridors.
- Supermarkets:End-cap placement and chilled cabinet access capture majority consumer trial purchases. Yili Group exploits refrigerated distribution networks to secure shelf dominance in northern provinces.
- Health Food Stores:Specialty retail with premium positioning and educated staff.
- Convenience Stores:Impulse-oriented formats with limited chilled space allocation.
Supermarkets anchor the volume base while online retail expands most quickly among pathways.
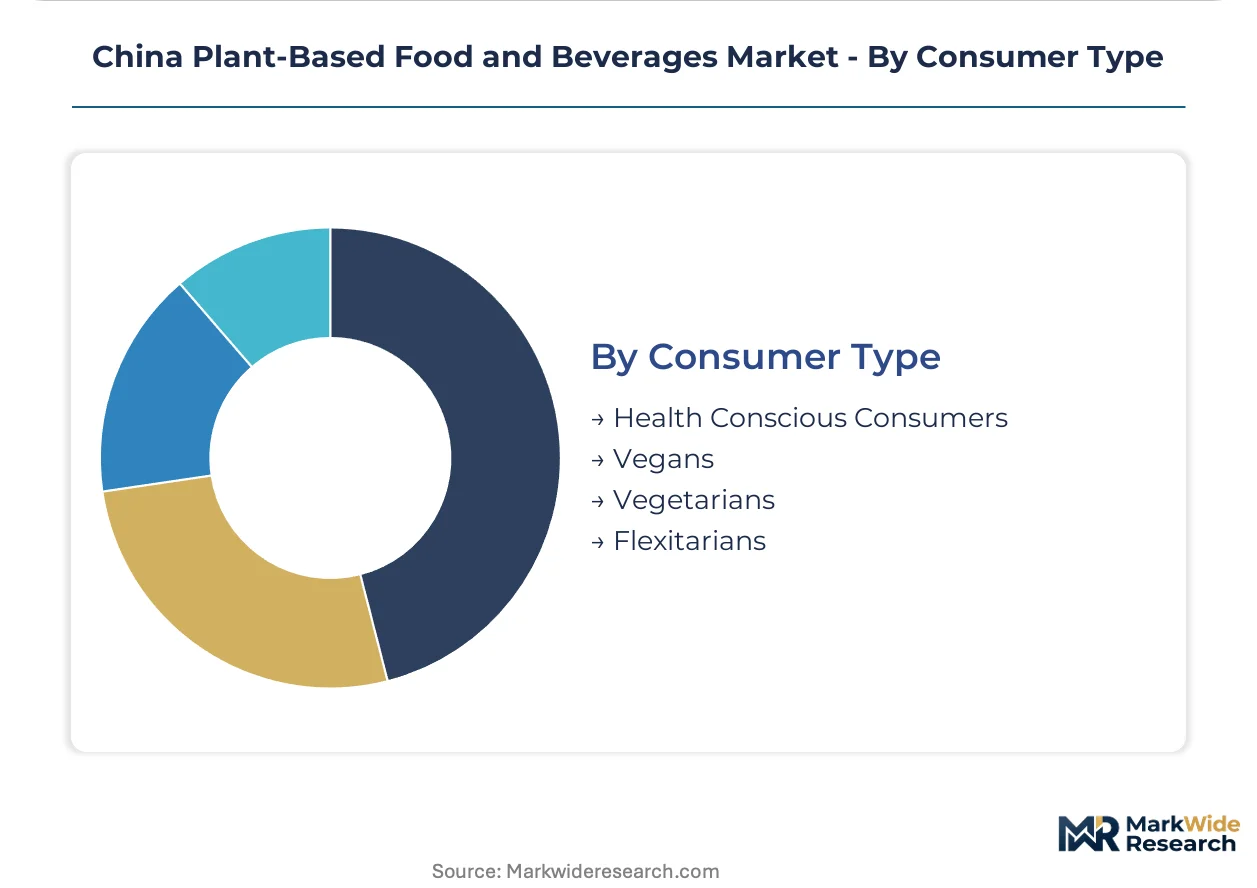
Consumer Type:
Adoption velocity correlates with dietary restriction strictness — health-motivated buyers experiment faster than ethical absolutists.
- Health Conscious Consumers:Flexibility-seekers prioritizing nutritional density and reduced saturated fat intake. NHC dietary guideline revisions create institutional endorsement for reduced-animal-protein consumption patterns in school nutrition programs.
- Flexitarians:Occasional meat reducers driving category mainstreaming. Shanghai and Beijing quick-service operators report stronger repeat purchase rates for hybrid animal-plant formulations than for 100% plant-based equivalents.
- Vegans:Ethical absolutists with zero-tolerance ingredient verification requirements.
- Vegetarians:Dairy-inclusive dietary pattern with established supply chain familiarity.
Health conscious consumers anchor the volume base while flexitarians gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Chinese sub-regions, with eastern coastal cities treating plant-based products as daily staples while inland provinces retain them as occasional novelties. This usage-mix differential shapes everything from cold-chain investment to formulation priorities.
Yangtze River Delta
Shanghai and Hangzhou quick-service operators drive oat milk standardization in coffee applications, with flexitarian consumers normalizing daily consumption. SAMR labeling requirements enforce compositional thresholds that filter subscale local producers. The Shanghai cluster concentrates extrusion technology partnerships between food manufacturers and European equipment suppliers.
Pearl River Delta
Shenzhen and Guangzhou consumers show highest trial rates for hybrid animal-plant protein formulations in quick-service menus. Dual carbon goals compress facility retrofit timelines for processors serving this export-oriented manufacturing hub. The Guangzhou-Shenzhen corridor anchors chilled distribution infrastructure expansion into southern provinces.
Beijing-Tianjin-Hebei
Institutional catering procurement in Beijing schools and government canteens responds directly to NHC dietary guideline revisions emphasizing reduced meat consumption. GB standards compliance costs consolidate shelf access around capitalized national players. The Beijing cluster concentrates R&D facilities for fermentation-derived protein startups.
Sichuan-Chongqing
High-heat cooking applications in traditional Sichuan cuisine expose fat emulsion stability gaps that constrain meat alternative penetration. Provincial agricultural policies promote domestic soy processing infrastructure to reduce protein isolate import dependency. The Chengdu metro area emerges as a test market for localized textured vegetable protein formulations.
Shandong Peninsula
Dairy incumbent processing capacity in Jinan and Qingdao retrofits for plant-based milk production to leverage existing refrigerated distribution networks. SAMR food safety inspections prioritize this northern manufacturing zone given its supply chain centrality. The Qingdao port facilitates pea protein concentrate imports from North American suppliers.
China Plant-Based Food and Beverages Market Competitive Environment
Capability concentration sits with protein technology specialists and fermentation startups; scale advantage sits with dairy incumbents leveraging refrigerated infrastructure. The market structures around three tiers: national dairy conglomerates with cold-chain dominance, regional soy processors with decades of brand equity, and international entrants positioning through foodservice channels. Strategic moves center on formulation partnerships between incumbents and technology suppliers, plus chilled distribution slotting fee competition in tier-one retail.
Among dairy-derived diversifiers, Yili Group exemplifies scale-driven shelf dominance through refrigerated network exploitation. Vitasoy International Holdings Ltd. anchors the soy heritage tier with decades of Greater China retail presence. Oatly Group AB occupies the foodservice-first positioning archetype, having established oat milk as coffee-shop standard before grocery expansion.
| Leading Market Players |
|---|
| Yili Group |
| The Livekindly Company Inc. |
| Green Monday Group |
| Whole Perfect Foods |
| Vitasoy International Holdings Ltd. |
| Qishan Foods |
| Oatly Group AB |
| Unilever PLC (The Vegetarian Butcher) |
| Zhenmeat |
| Others |
Value Chain & Pricing Dynamics
Pea protein isolate import dependency from North American and European suppliers compresses pricing power across formulation tiers while simultaneously forcing extrusion equipment localization timelines. This single-source vulnerability widens spreads between premium oat-based formulations and economy soy alternatives, and reshapes procurement toward domestic textured vegetable protein partnerships.
Pricing Analysis
Long-term offtake contracts dominate procurement for imported pea and fava bean protein concentrates, insulating large formulators from spot market freight volatility that exposes smaller competitors. Pricing stratifies across premium, standard, and economy tiers based on protein isolate purity grades and SAMR GB standards certification levels. Cost compression in plant-based milk intensifies as private-label entrants exploit Yili Group's refrigerated distribution slotting fee model. Quick-service restaurant chains show lowest price sensitivity due to menu positioning requirements, while supermarket private-label buyers drive the steepest discount negotiations.
Supply Chain Analysis
Export-control regimes on high-moisture extrusion process technology from European suppliers constrain domestic equipment manufacturing scale-up. Protein isolate supply concentrates in Canada, France, and the Netherlands, while oat beta-glucan extraction technology remains anchored in Scandinavian processing facilities. Raw material dependencies span North American pea concentrates, European fermentation-derived dairy proteins, and domestic soy processing infrastructure. Single-source vulnerability in extrusion engineering talent forces reliance on foreign technical consultants. Distribution runs through tier-one city chilled networks with Yili Group and Vitasoy International Holdings Ltd. controlling northern and Greater China cabinet access respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent dairy processors face substitution pressure from precision fermentation startups supplying dairy-identical proteins to ice cream and yogurt manufacturers without sensory compromise. This threat demands defensive repositioning before clean-label claims erode traditional plant-based differentiation.
For Market Incumbents: Harden refrigerated distribution network control through exclusive slotting fee arrangements in northern provinces before fermentation-derived proteins achieve cost parity. Accelerate backward integration into domestic soy processing infrastructure to reduce pea protein isolate import exposure. Prioritize R&D investment in fat emulsion stability for high-heat applications to defend against hybrid animal-plant formulation encroachment.
For New Entrants and Emerging Players: Chengdu and Wuhan metro areas present the most penetrable expansion corridors as chilled infrastructure matures beyond Beijing-Shanghai-Shenzhen saturation. Target foodservice ingredient positioning for bakery and dessert manufacturing applications where oat milk migrates from coffee-shop standard to B2B volume contracts. Pursue CSRD-aligned procurement mandates from European-headquartered parent companies requiring certified sustainable supplier traceability disclosures.
For Investors and Strategic Acquirers: NHC dietary guideline revisions reshaping school nutrition procurement reshape the acquisition landscape toward fermentation technology specialists and precision protein platforms. Long-term viability over a multi-year horizon favors targets with extrusion equipment partnerships and SAMR registration expertise rather than pure brand plays. Monitor domestic equipment manufacturer technology gap closure with European suppliers as the critical inflection signal for localized production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Chilled Distribution Network Expansion | Yili Group's slotting fee dominance in northern provinces blocks competitor trial access. |
| Precision Fermentation Partnership | Dairy-identical protein supply enables clean-label claims without sensory compromise gaps. |
| Domestic Extrusion Equipment Localization | Technology transfer from European suppliers reduces capital intensity for textured vegetable protein scale-up. |
| CSRD-Aligned Procurement Certification | European parent company mandates create premium positioning for traceable sustainable ingredient suppliers. |
| Hybrid Formulation Development | Shanghai quick-service operators report stronger repeat purchase rates for blended animal-plant SKUs. |
Study Parameters
Operator-level perspectives from plant-based formulation scientists, quick-service restaurant procurement directors, chilled distribution network managers, and SAMR regulatory affairs specialists anchored the qualitative base. Primary interview findings combined with secondary validation from customs protein concentrate import records, GB standards revision documentation, NHC dietary guideline publications, and CSRD sustainability disclosure filings. Bottom-up volume modeling across product type, ingredient source, distribution channel, and consumer type segments triangulated with top-down market sizing from dairy incumbent revenue disclosures.
Scenario-bracketing around extrusion technology localization timelines and NHC guideline implementation pace framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product formulation complexity, cold-chain intensity, protein source origin, and regional consumption occasion patterns. CAGRs derived from historical velocity differentials between plant-based milk inventory turns and meat alternative trial-to-repeat conversion rates, incorporating fermentation technology cost curve assumptions and private-label margin compression trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive refrigerated network expansion by dairy conglomerates or rapid precision fermentation cost breakthroughs would shift outcomes. Material shifts in SAMR labeling enforcement intensity or dual carbon goals facility retrofit deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Bacon Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Canada Plant-Based Food and Beverages Market