
 Low Fat Plant-Based Diet Market | 2026-2036
Low Fat Plant-Based Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Plant-Based Diet Market Analytics
Market Context
European pea protein processors is realigning supply chains toward reduced-fat extrusion capabilities. Beyond Meat leverages its European production footprint to serve reformulated product lines with lower saturated fat profiles. Amy's Kitchen sustains competitive positioning through organic-certified, low-fat frozen entrees that anchor shelf space in North American natural channel retailers. Impossible Foods Inc. differentiates via heme technology that delivers meat-like sensory profiles without the fat content of conventional alternatives.
Technical Definition and Segment Structure
A low fat plant-based diet comprises nutritional regimens and packaged food products deriving protein, fat, and carbohydrate macronutrients predominantly from vegetable sources while restricting total fat intake, typically below thirty percent of caloric consumption, to achieve cardiovascular risk reduction and weight control objectives. Dairy Alternatives leads product type revenue due to oat and almond milk scale economies, while Meal Kits represents the fastest-expanding category as subscription services bundle portion-controlled, recipe-specified low-fat plant proteins. Health-Conscious Consumers dominates end user spending, though Fitness Enthusiasts commands premium pricing for performance-positioned, high-protein low-fat formulations distributed through specialty channels.
Regulatory Environment and Outlook
The FDA governs nutrition fact panel declarations and health claims for plant-based foods in the United States, while the EU Green Deal and Farm to Fork Strategy mandate front-of-pack labeling schemes that disadvantage high-fat formulations across European markets. EFSA novel food authorizations create market access barriers for emerging protein sources such as precision-fermented ingredients seeking low-fat positioning. Stakeholders must monitor evolving protein quality scoring methodologies and fat-replacement additive approvals that will determine which reformulation pathways secure regulatory clearance and retail distribution.
Market Dynamics
EU Green Deal nutritional labeling mandates are compressing formulation timelines as processors race to reformulate high-fat plant-based lines before front-of-pack restrictions take full effect.
Growth Catalysts
- Farm to Fork Strategy:The EU's sustainability criteria tighten nutritional thresholds, creating compliant product premiums for reformulated low-fat entries across German and French retail chains.
- Precision fermentation:Emerging protein production methods enable fat-mimetic texture without lipid content, attracting performance-positioned meal kit subscribers seeking macronutrient control.
- German retail concentration:Dedicated plant-based sections in Rewe and Edeka chains normalize premium pricing for reduced-fat alternatives, pulling adjacent European markets toward similar shelf architectures.
Market Restraints
- Pea protein supply concentration:European extrusion capacity clusters in Netherlands and Denmark, creating input bottlenecks when reformulation waves spike demand for reduced-fat ingredient streams.
- EFSA novel food timelines:Emerging protein sources face 18-24 month authorization windows, freezing pipeline innovation for startups seeking low-fat positioning claims.
- Sensory substitution ceiling:Current fat-replacement additives fail to replicate mouthfeel in ambient-stable formats, limiting shelf-stable meal expansion.
Strategic Opportunities
- Nordic meal kit penetration:Sweden and Norway show subscription service underpenetration relative to per-capita plant-based consumption, offering white space for portion-controlled low-fat bundles.
- Organic-low-fat convergence:Dual certification commands 40-60% shelf price premiums in natural channel retail, rewarding processors who secure both EU organic and reduced-fat positioning.
- Food service direct distribution:Contract manufacturers are bypassing retail brokerage to supply reformulated low-fat SKUs directly to contract catering operators in hospital and corporate segments.
Industry Challenges
- Extrusion engineering talent scarcity:Reduced-fat texturizing requires specialized protein chemistry expertise that food science programs have not scaled to match reformulation demand.
- Dual certification complexity:Simultaneous organic and low-fat claim validation creates documentation burdens that extend product development cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Plant-Based Diet Market |
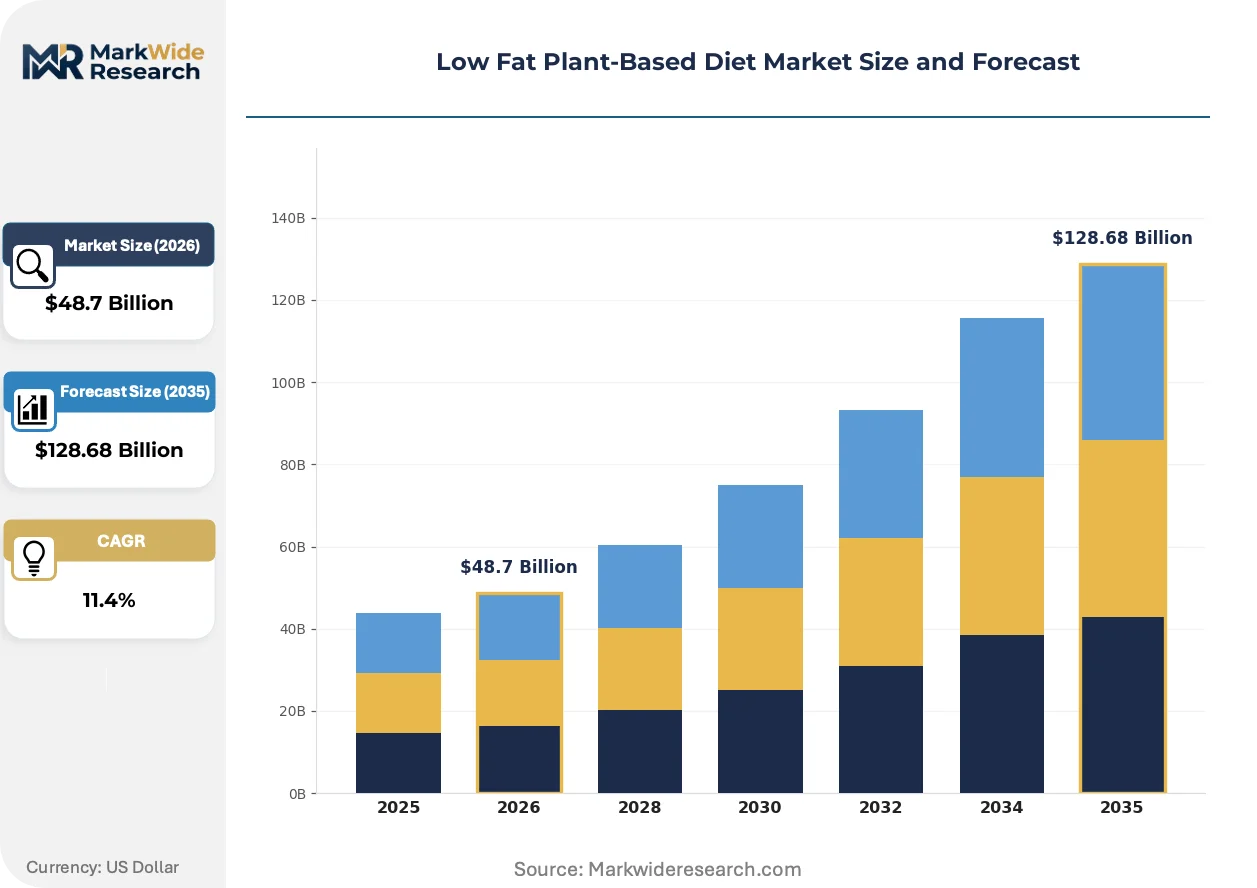
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Sauces, Meal Kits, Dairy Alternatives End User: Health-Conscious Consumers, Fitness Enthusiasts, Vegetarians, Vegans Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Application: Weight Management, Heart Health, Meal Replacement, Nutritional Supplements |
| Companies Covered | Beyond Meat, Impossible Foods Inc., Amy's Kitchen Inc., Maple Leaf Foods, Conagra Inc., Vegetarian Butcher, Tofurky, The Hain-Celestial, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Plant-Based Diet Market Evolving Landscape
Reformulation science is compressing the gap between sensory fidelity and nutritional compliance, enabling plant-based products to meet tightening fat thresholds without sacrificing purchase intent.
High-pressure processing is unifying microbial safety and clean-label positioning in refrigerated low-fat alternatives. Retail buyers in the natural channel are adopting HPP-treated SKUs at twice the rate of thermally stabilized equivalents. This technology is unifying shelf-life extension with front-of-pack simplicity, eliminating preservative declarations that trigger health-conscious consumer rejection.
EU Green Deal front-of-pack labeling mandates are recalibrating R&D priorities toward fat-reduction targets. Processors must now reformulate before Nutri-Score algorithms penalize lipid content in algorithmic shelf placement decisions. Dairy alternative categories face the steepest compliance curves, with oat milk formulations already shifting below 1.5% fat to secure A-grade ratings.
Subscription meal kit procurement is consolidating buyer power around specified macronutrient profiles. HelloFresh and Marley Spoon are replacing spot-market ingredient purchasing with annual contracts for guaranteed low-fat protein volumes. This concentration is most visible in German-speaking markets, where kit penetration exceeds 15% of household protein occasions and suppliers must commit to batch-level nutritional certification.
Low Fat Plant-Based Diet Market Segmentation
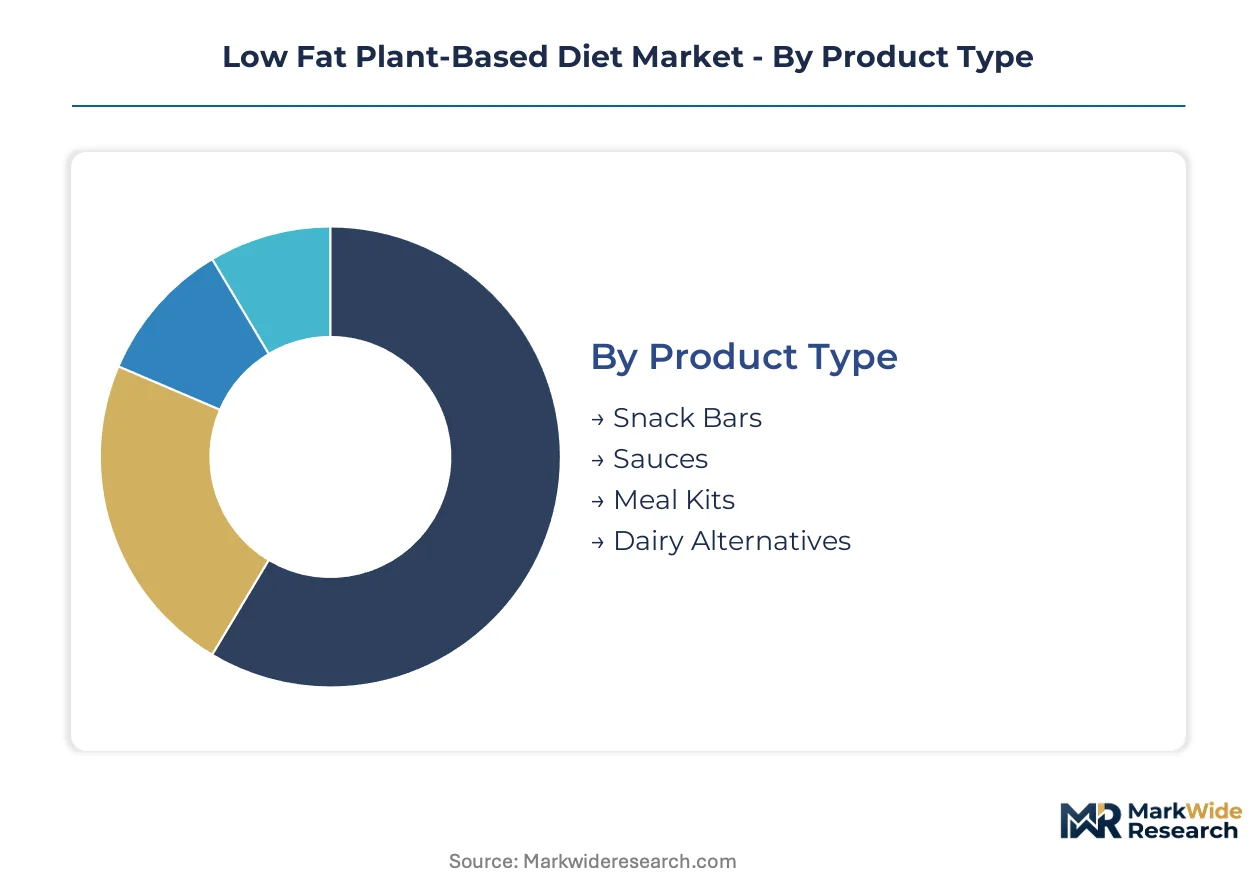
Segmentation in the low-fat plant-based diet market reveals divergent purchasing logic across consumption occasions and buyer wellness objectives. Category boundaries blur as reformulation advances enable single products to span multiple nutritional claims simultaneously.
Product Type:
Buyers in this category separate by consumption occasion urgency versus preparation tolerance.
- Dairy Alternatives:Oat and almond milk formulations dominate refrigerated shelf space with sub-1.5% fat profiles engineered for Nutri-Score A-grade positioning. German retail chains Rewe and Edeka dedicate aisle sections to these SKUs, pulling volume through breakfast occasion substitution.
- Meal Kits:Subscription services specify macronutrient-controlled protein bundles with batch-level certification. HelloFresh and Marley Spoon lock suppliers into annual low-fat volume contracts, concentrating procurement power in German-speaking markets where kit penetration exceeds 15% of household protein occasions.
- Snack Bars:Ambient-stable formats face sensory ceiling constraints from fat-replacement additive limitations.
- Sauces:Reformulated emulsions target food service operators seeking compliant menu items under tightening EU nutritional labeling.
Volume sits with Dairy Alternatives; growth tilts toward Meal Kits.
End User:
Purchasing intensity correlates with dietary restriction strictness and performance tracking behavior.
- Health-Conscious Consumers:Flexible dietary adopters prioritize front-of-pack simplicity and clean-label positioning over absolute fat elimination. This cohort drives mainstream retail velocity through trial and brand switching.
- Fitness Enthusiasts:Macro-tracking behavior commands premium pricing for high-protein low-fat formulations distributed through specialty channels and direct-to-subscription models.
- Vegetarians:Lacto-ovo dietary frameworks create demand for dairy-adjacent low-fat innovations rather than complete meat analogues.
- Vegans:Ethical commitment sustains price tolerance for dual-certified organic and reduced-fat products despite formulation cost premiums.
Revenue concentrates with Health-Conscious Consumers; Fitness Enthusiasts generate the steepest margin expansion.
Distribution Channel:
Channel selection reflects buyer trade-offs between assortment breadth, nutritional verification, and immediate availability.
- Supermarkets:Rewe, Edeka, and Carrefour anchor volume through dedicated plant-based sections that normalize premium pricing for reduced-fat alternatives. Front-of-pack labeling mandates accelerate SKU turnover as processors race to reformulate before algorithmic shelf placement penalties.
- Online Retail:Subscription consolidation enables direct macronutrient specification and batch-level traceability unavailable in physical retail.
- Health Food Stores:Natural channel buyers adopt HPP-treated refrigerated alternatives at twice the rate of thermally stabilized equivalents.
- Specialty Stores:Performance-positioned formulations targeting Fitness Enthusiasts concentrate in limited-assortment environments with educated staff.
Transaction volume flows through Supermarkets; Online Retail captures the fastest share gain.
Application:
Functional outcome expectations determine reformulation priorities and regulatory claim pathways.
- Weight Management:Caloric restriction frameworks prioritize volume-eating satisfaction through fiber-enhanced, fat-reduced texture systems. Meal replacement positioning requires complete micronutrient profiles that extend development cycles.
- Heart Health:Cardiovascular risk reduction claims fall under FDA and EFSA health claim regulations, demanding clinical substantiation that smaller processors cannot resource.
- Meal Replacement:Complete nutrition obligations create formulation complexity as fat reduction must not compromise essential fatty acid delivery.
- Nutritional Supplements:Precision dosing formats target Fitness Enthusiasts with isolated protein streams and minimal lipid carryover.
Weight Management anchors current volume; Heart Health applications face the steepest regulatory compliance curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pea protein cultivation concentrates in the northern European plains, anchoring reformulation capacity near Rotterdam and Copenhagen processing clusters. Supply chain proximity to German retail demand shapes regional investment flows.
Germany
Rewe and Edeka chains dedicate aisle sections to reduced-fat plant-based alternatives, normalizing premium pricing for reformulated SKUs. The EU Green Deal's Farm to Fork Strategy tightens nutritional thresholds through Nutri-Score algorithms. Berlin-Brandenburg hosts extrusion engineering firms serving dairy alternative processors racing to secure A-grade fat profiles.
Netherlands
Rotterdam port logistics enable pea protein import consolidation for European extrusion networks. EFSA novel food authorizations create 18-24 month regulatory windows that freeze pipeline innovation timelines. Wageningen University clusters feed reduced-fat texturizing R&D into adjacent food science incubators.
United States
FDA nutrition fact panel declarations govern health claim pathways for cardiovascular risk reduction positioning. California's natural channel retailers adopt HPP-treated refrigerated alternatives at twice the rate of thermally stabilized equivalents. Los Angeles and San Francisco metro areas anchor meal kit subscription density for portion-controlled protein bundles.
United Kingdom
HelloFresh UK procurement contracts specify batch-level macronutrient certification for low-fat protein volumes. Post-Brexit regulatory divergence from EU labeling schemes creates dual compliance burdens for cross-channel suppliers. London's contract catering operators source reformulated SKUs directly from manufacturers bypassing retail brokerage.
Sweden
Subscription meal kit penetration trails per-capita plant-based consumption, exposing white space for portion-controlled bundles. The country's national food agency enforces front-of-pack labeling that disadvantages high-fat formulations in algorithmic shelf placement. Stockholm's food tech incubators pilot precision-fermented protein streams targeting fat-mimetic texture without lipid content.
Low Fat Plant-Based Diet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision-fermented ingredients and direct-to-food-service distribution. The vendor base stratifies across three tiers: multinational packaged food conglomerates with frozen entree scale, specialized plant-based meat analog specialists, and organic-certified natural channel anchors. Two dominant competitive moves define current positioning: backward integration into extrusion capacity and dual organic-low-fat certification pursuit.
Within the specialized analog tier, Beyond Meat and Impossible Foods Inc. exemplify technology-differentiated positioning, while Amy's Kitchen Inc. occupies the organic-natural channel intersection. These three entities represent divergent pathways to reduced-fat market capture—heme-based sensory replication, extrusion engineering scale, and dual-certification shelf premiums respectively.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods Inc. |
| Amy's Kitchen Inc. |
| Maple Leaf Foods |
| Conagra Inc. |
| Vegetarian Butcher |
| Tofurky |
| The Hain-Celestial |
| General Mills |
| Others |
Value Network & Pricing Analysis
Precision fermentation scale-up is compressing cost curves for fat-mimetic proteins while concentrating upstream capacity in Dutch and Danish extrusion clusters. This dual shift simultaneously erodes legacy soy isolate economics and tightens procurement leverage for reformulated low-fat SKUs across German retail networks.
Pricing Analysis
Annual macronutrient certification bundled into supplier contracts commands unbundled spot-market premiums for batch-verified low-fat protein volumes. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified organic-low-fat SKUs from single-claim alternatives and commodity plant proteins. Cost compression in standard-tier extruded ingredients is intensifying because Rotterdam port logistics enable import competition from North American pea processors. Health-Conscious Consumers in mainstream supermarkets exhibit highest price sensitivity, while Fitness Enthusiasts accepting subscription lock-in show lowest elasticity for performance-positioned formulations.
Supply Chain Analysis
Dual-sourcing requirements from HelloFresh and Marley Spoon procurement teams mandate multi-supplier qualification for annual low-fat volume contracts, fragmenting order concentration across Netherlands, Denmark, and Germany extrusion networks. European supply draws from Canadian and Ukrainian pea cultivation, Dutch enzyme processing for precision-fermented streams, and German organic certification facilities. Single-source vulnerability concentrates in Rotterdam port logistics for North American protein imports. Distribution runs through Rewe and Edeka direct store delivery for refrigerated alternatives, bypassing traditional wholesale brokerage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-fat plant-based diet market sits in a technology-transition phase where precision fermentation displaces legacy extrusion-dependent texture systems. Heme-based and enzyme-catalyzed production methods are rewriting formulation economics while EFSA authorization timelines freeze competitive entry.
For Market Incumbents: Deploy backward integration into captive extrusion capacity in Netherlands and Denmark clusters to secure input priority during reformulation waves. Consolidate shelf positioning through dual organic-low-fat certification investment before EU Green Deal algorithmic penalties accelerate SKU turnover. Precision-fermented entrants threaten sensory parity without lipid content, demanding accelerated heme technology licensing to defend premium positioning. For New Entrants and Emerging Players: Capture white space in Swedish and Norwegian meal kit subscription markets where per-capita plant-based consumption exceeds service penetration. Target hospital and corporate contract catering channels with direct-manufacturer distribution models that bypass retail brokerage margin extraction. Lead with batch-level macronutrient certification as the go-to-market anchor for procurement specifications at HelloFresh and Marley Spoon. For Investors and Strategic Acquirers: Exit pathways concentrate in precision-fermented ingredient platforms awaiting EFSA novel food clearance, positioning for acquisition by multinational packaged food conglomerates seeking reformulation capabilities. Long-term viability favors processors with secured organic certification infrastructure and locked extrusion capacity contracts across the analysis window. Watch EFSA authorization velocity for precision-fermented proteins as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extrusion Capacity | Captive supply of reduced-fat texturizing capability secures priority allocation during reformulation demand spikes in Netherlands and Denmark clusters. |
| Dual Certification Investment | Simultaneous EU organic and low-fat claim validation unlocks 40-60% shelf price premiums in Rewe and Edeka natural channel sections. |
| Direct Food Service Distribution | Bypassing retail brokerage enables margin capture from hospital and corporate catering operators sourcing reformulated SKUs under EU nutritional labeling mandates. |
| Precision Fermentation Scale-Up | EFSA novel food authorization for fat-mimetic protein streams displaces legacy extrusion economics in performance-positioned meal kit formulations. |
| Subscription Procurement Lock-In | Annual volume contracts with HelloFresh and Marley Spoon specify batch-level macronutrient certification unavailable in spot-market ingredient purchasing. |
Research Methodology
EU Farm to Fork Strategy documentation, EFSA novel food authorization registers, and German retail audit data from Rewe and Edeka formed the secondary backbone for supply-side calibration. Primary interviews with extrusion engineering directors, procurement leads at meal kit operators, regulatory affairs specialists navigating EFSA timelines, and category buyers at natural channel retailers combined with secondary validation. Bottom-up and top-down triangulation cross-checked volume assumptions against pea protein import flows through Rotterdam and Copenhagen processing utilization rates.
Bottom-up modeling anchored projections to segment-level pricing and volume interactions across product type, end user, distribution channel, and application dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to base-year market sizing, with sensitivity testing around EFSA authorization delays and German retail shelf architecture evolution. Industry-specific inputs included Nutri-Score algorithm weightings for fat content and subscription service penetration rates in German-speaking markets.
The model holds under stable EU Green Deal implementation timelines and sustained German retail chain commitment to dedicated plant-based sections; deviation in EFSA novel food authorization velocity or precision fermentation cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
India Plant Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Vegan Food Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Targeting Pod Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Vegan Alternatives Market