
 Vegan Pastry Market | 2026-2036
Vegan Pastry Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Pastry Market Analytics
The gap between premium artisan vegan pastries and mass-market commodity offerings is broadening as ingredient sourcing and production methods diverge sharply. Green Common leverages its vertically integrated supply chain to control ingredient provenance across Asia-Pacific markets. Loving Hut sustains competitive pressure through its global network of branded cafés that double as retail distribution nodes. Simple Life differentiates by specializing in clean-label formulations that exclude ultra-processed stabilizers.
Vegan pastries are baked goods formulated without animal-derived ingredients such as butter, eggs, or dairy, typically relying on plant-based fats, aquafaba, or cultured alternatives to achieve comparable texture and shelf stability; their primary commercial purpose is to serve consumers with ethical, environmental, or allergen-related dietary restrictions. Cakes currently occupy the largest margin pool within product type segmentation due to celebration-driven purchasing and premium pricing tolerance. Eco-friendly packaging is accelerating fastest among packaging categories as retailers face mounting compliance obligations under extended producer responsibility frameworks.
The EU Green Deal and EFSA labeling standards shape formulation transparency requirements across European markets, while FDA allergen disclosure rules in the United States govern how vegan claims intersect with cross-contamination warnings. India's FSSAI plant-based food categorization guidelines are creating new compliance thresholds for manufacturers targeting export channels. Stakeholders must monitor how divergent national standards for vegan claim verification reshape cross-border product development budgets and certification costs.
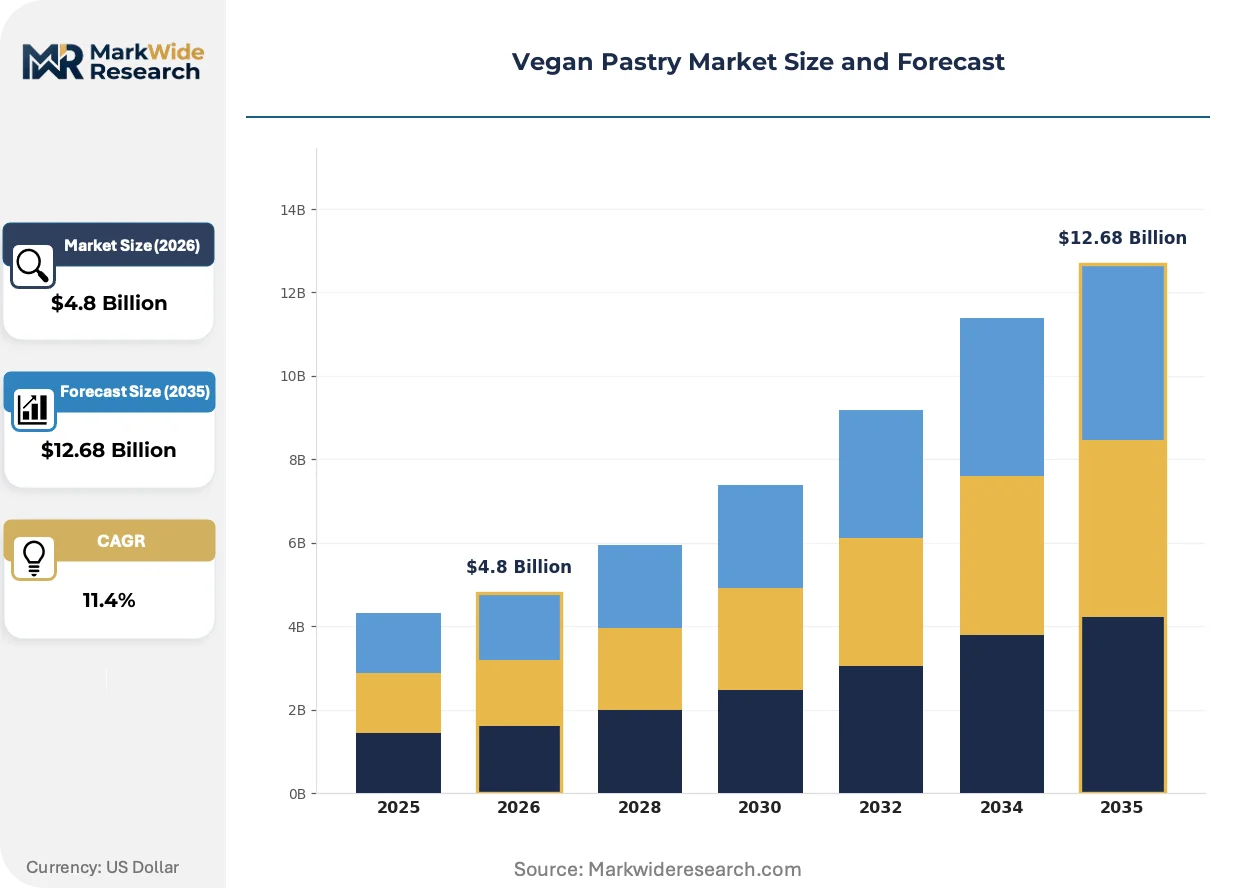
Market Dynamics
The EU Green Deal's sustainable food system targets are forcing wholesale reformulation across bakery supply chains, as extended producer responsibility frameworks and carbon labeling mandates compress development timelines for plant-based fat alternatives and clean-label stabilizers.
Growth Catalysts
- EFSA labeling standards:These transparency requirements across European markets accelerate consumer trust in vegan claim verification, pulling reformulated products through retail channels faster than conventional equivalents.
- Specialty café networks:Boutique bakeries in Berlin and Munich now function as category educators, converting trial into repeat purchase through visible production and ingredient storytelling.
- Cultured fat technology:Precision fermentation-derived butter alternatives achieve mouthfeel parity with dairy, removing the final sensory barrier for mainstream dessert consumers.
Market Restraints
- Oilseed price volatility:Coconut and shea butter supply concentrates in Southeast Asian and West African export corridors, exposing margins to weather-driven harvest shocks.
- Cross-contamination liability:FDA allergen disclosure rules in the United States create legal friction where shared bakery equipment handles both vegan and dairy-containing products.
- Functional ingredient scarcity:Clean-label emulsifiers excluding mono- and diglycerides remain limited to two qualified suppliers, constraining scale-up for mid-tier brands.
Strategic Opportunities
- India's FSSAI plant-based categorization:New export-channel compliance thresholds favor early movers who pre-certify formulations for this manufacturing hub.
- Eco-friendly packaging acceleration:Extended producer responsibility frameworks in Germany and France mandate recyclable or compostable materials, creating first-mover advantage for compliant suppliers.
- Aquafaba stabilization:This chickpea-processing byproduct converges with carbon-footprint reduction goals to unlock cost advantages in high-volume cake production.
Industry Challenges
- Reformulation talent scarcity:Food scientists with simultaneous expertise in plant lipid chemistry and clean-label preservation remain concentrated in Netherlands and Denmark research clusters.
- Certification timeline compression:Vegan Society and V-Label approval processes now lag product development cycles, delaying market entry by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Pastry Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Cakes, Tarts, Muffins Ingredient Type: Whole Grains, Nuts, Fruits, Sweeteners Packaging Type: Eco-Friendly, Resealable Bags, Boxes, Plastic Containers Distribution Channel: Retail Stores, Online Platforms, Farmers Markets, Cafés |
| Companies Covered | Green Common, Greenr, Simple Life, Vegan Nation, 24 Carrot, Sattviko, The Real Green Café, Swees Plant Based Foods, Loving Hut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Pastry Market Evolving Landscape
Active reformulation is compressing the texture gap between plant-based and conventional pastries, while regulatory pressure on packaging and labeling forces simultaneous innovation across multiple product attributes.
Cultured dairy alternatives produced via precision fermentation are converging with traditional bakery production lines as equipment manufacturers retrofit churning and lamination systems for higher-moisture fat substrates. Artisan bakeries in Copenhagen and Stockholm pilot these integrations first, drawn by consumer willingness to pay parity prices. The structural result is collapsing the premium price wedge that previously separated plant-based from conventional viennoiserie.
REACH chemical safety registrations now govern emulsifier substitutions in EU-bound products, forcing suppliers to retire legacy polysorbate formulations ahead of 2026 renewal deadlines. Industrial bakeries respond by accelerating clean-label certification timelines, often bypassing intermediate reformulation stages entirely. Cake segments face the steepest compliance costs due to their complex stabilization requirements.
Celebration-driven purchasing now dominates category margin capture, as consumers accept premium pricing for event-specific vegan cakes that signal dietary values to social networks. Specialty retailers in Munich and Hamburg displace supermarket pastry counters for these high-occasion transactions. Germany's dense vegan-friendly retail infrastructure makes this behavioral shift most visible, though Paris and Amsterdam clusters follow closely.
Vegan Pastry Market Segmentation
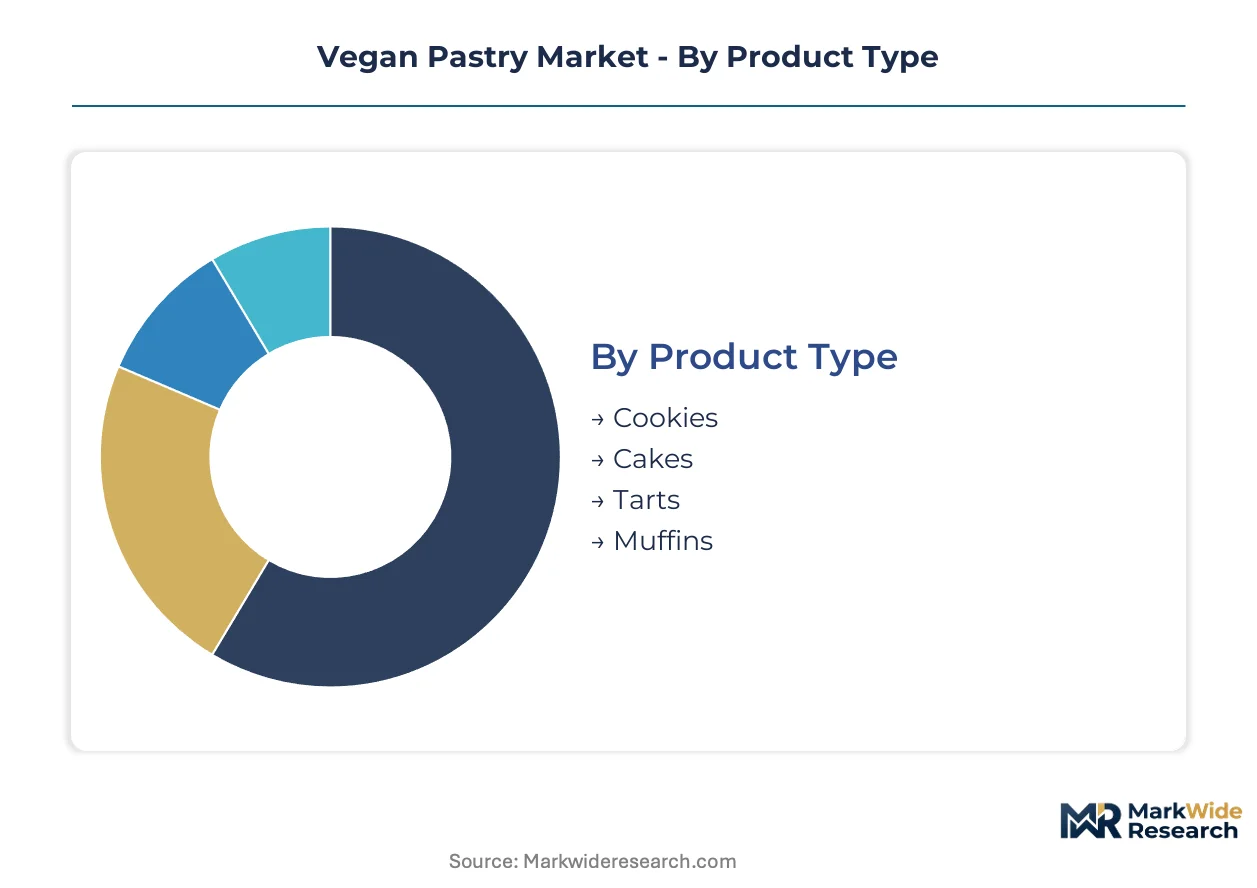
Vegan pastry segmentation reveals how reformulation priorities, packaging compliance, and channel specialization fragment commercial opportunity. Each dimension carries distinct margin structures and regulatory exposure that reshape where manufacturers allocate R&D and certification budgets.
Product Type:
End-use occasion and price tolerance separate buyers across formats, with celebration-driven purchases commanding premium positioning.
- Cakes:Multi-layer formulations requiring stabilized plant-based creams and cultured butter alternatives dominate revenue pools. Specialty retailers in Munich and Hamburg capture the highest-margin transactions through visible ingredient storytelling and custom decoration services.
- Cookies:Shelf-stable formulations with lower moisture sensitivity suit mass retail distribution and export logistics. German supermarket chains now dedicate permanent aisle space to clean-label cookie assortments, compressing development timelines for mid-tier brands seeking placement.
- Tarts:Laminated dough applications demand precise fat crystallization control achievable through shea-coconut blends or precision-fermented alternatives.
- Muffins:Single-serve formats align with grab-and-go café consumption and breakfast substitution occasions.
Cakes lead volumes today; cookies are gaining share fastest through retail channel expansion.
Ingredient Type:
Raw material provenance and processing intensity determine clean-label credibility and export eligibility under divergent national standards.
- Nuts:Almond, cashew, and hazelnut bases provide structural fat and protein in premium formulations but carry elevated allergen disclosure obligations under FDA and EFSA frameworks. India's FSSAI plant-based categorization creates new compliance thresholds for nut-forward products targeting export manufacturing partnerships.
- Whole Grains:Oat, spelt, and buckwheat flours supply fiber positioning and lower glycemic index claims for health-focused segments. German artisan bakeries in Berlin cluster source heritage grain varieties through regional mill cooperatives, building traceability narratives that justify price premiums.
- Fruits:Date paste, apple puree, and berry concentrates replace refined sugars in reduced-sugar positioning.
- Sweeteners:Coconut sugar, maple syrup, and monk fruit extracts serve keto-adjacent and low-glycemic subsegments.
Nuts dominate premium tier placement; whole grains are climbing the fastest as clean-label bakery demand broadens.
Packaging Type:
Extended producer responsibility mandates and shelf-life requirements force simultaneous innovation in material science and barrier properties.
- Eco-Friendly:Compostable cellulose films and molded fiber trays respond to Germany's and France's recyclable-packaging mandates under EU Green Deal implementation. First-mover suppliers capture preferred supplier status with specialty café networks seeking compliance-ready solutions.
- Resealable Bags:Zip-lock laminates with moisture barriers extend ambient shelf stability for cookie and muffin formats distributed through retail and online channels.
- Boxes:Rigid paperboard structures protect decorated cakes during celebration-driven pickup transactions.
- Plastic Containers:PET and PP clamshells retain share in foodservice and deli counter applications where visibility and stackability outweigh sustainability claims.
Plastic containers still handle the highest unit volumes; eco-friendly formats are expanding most quickly as regulatory deadlines approach.
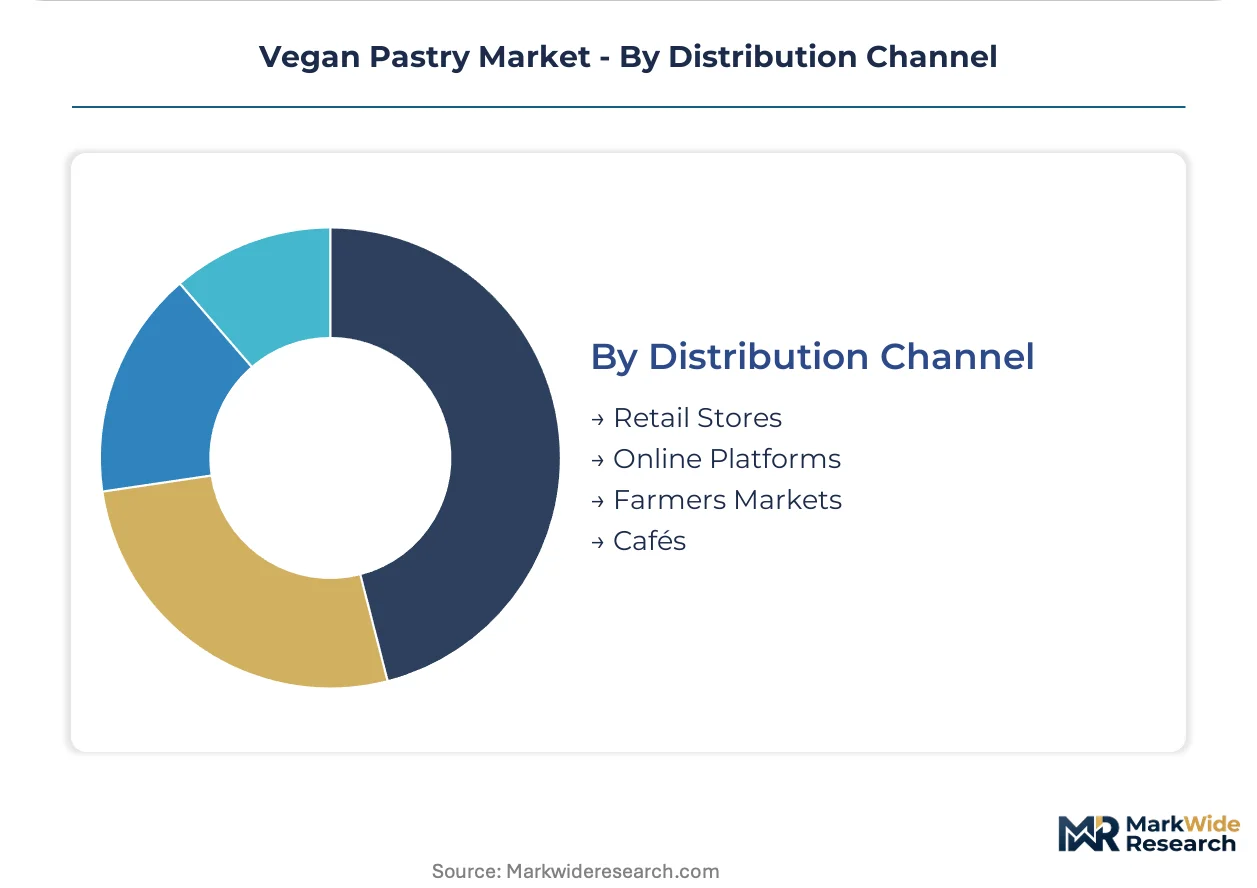
Distribution Channel:
Customer education intensity and purchase frequency diverge sharply across touchpoints, reshaping where new entrants concentrate launch resources.
- Cafés:Branded boutique locations in Berlin and Munich function as category educators, converting trial through visible production and staff expertise. These outlets capture the highest per-transaction values and generate social media visibility that drives regional demand formation.
- Online Platforms:Direct-to-consumer and marketplace channels enable subscription models and national reach for frozen or ambient-stable formats. Cold-chain logistics investments separate viable operators from margin-compromised entrants in this segment.
- Retail Stores:Supermarket and specialty grocery placement requires slotting fees and promotional support that favor scaled manufacturers with certification breadth.
- Farmers Markets:Hyperlocal producer-direct sales support artisan positioning and ingredient provenance storytelling with minimal packaging overhead.
Retail stores maintain the widest volume base; cafés are capturing share fastest as experience-driven purchasing intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists with simultaneous expertise in plant lipid chemistry and clean-label preservation concentrate in Netherlands and Denmark research clusters, anchoring Europe's formulation leadership while Asia-Pacific manufacturing hubs scale production capacity.
Germany
Specialty café networks in Berlin and Munich convert trial into repeat purchase through visible production and ingredient storytelling. The EU Green Deal's extended producer responsibility frameworks mandate recyclable or compostable packaging materials by 2026. Bavaria's dense vegan-friendly retail infrastructure captures the highest-margin celebration-driven cake transactions.
United States
FDA allergen disclosure rules create legal friction where shared bakery equipment handles both vegan and dairy-containing products. Precision fermentation-derived butter alternatives achieve mouthfeel parity with dairy, removing sensory barriers for mainstream consumers. Brooklyn and Los Angeles clusters pilot cultured fat technology integrations with traditional lamination systems.
India
FSSAI plant-based food categorization guidelines create new compliance thresholds for manufacturers targeting export channels. Nut-forward formulations carry elevated allergen disclosure obligations under divergent national standards. Maharashtra and Karnataka manufacturing hubs pre-certify formulations for European and North American export markets.
France
REACH chemical safety registrations govern emulsifier substitutions ahead of 2026 renewal deadlines, forcing retirement of legacy polysorbate formulations. Parisian artisan bakeries displace supermarket pastry counters for high-occasion vegan cake transactions. Île-de-France retail clusters follow German celebration-driven purchasing patterns with premium pricing tolerance.
United Kingdom
Clean-label emulsifiers excluding mono- and diglycerides remain limited to qualified suppliers, constraining scale-up for mid-tier brands. V-Label and Vegan Society certification processes lag product development cycles, delaying market entry. London's specialty retailers capture experience-driven purchasing through staff expertise and visible production.
Vegan Pastry Market Competitive Landscape
Top-tier vendors anchor premium artisan positioning through vertically integrated supply chains and branded café networks, while mid-tier players compete on clean-label formulations and mass retail placement. The vendor base stratifies across three archetypes: vertically integrated supply chain controllers, café-retail hybrid operators, and clean-label specialists. Consolidation pressure intensifies as certification timelines compress and reformulation talent scarcity widens capability gaps between tiers. Dominant competitive moves include strategic partnerships with precision fermentation suppliers and geographic expansion through pre-certified export manufacturing.
Within the vertically integrated tier, Green Common exemplifies supply chain control across Asia-Pacific markets. Among café-retail hybrid operators, Loving Hut occupies a position as a global network of branded locations that double as distribution nodes. Clean-label specialists include Simple Life, which represents formulation expertise excluding ultra-processed stabilizers. These three archetypes illustrate how competitive positioning diverges based on whether players prioritize upstream control, downstream touchpoint density, or ingredient transparency credentials.
| Leading Market Players |
|---|
| Green Common |
| Greenr |
| Simple Life |
| Vegan Nation |
| 24 Carrot |
| Sattviko |
| The Real Green Café |
| Swees Plant Based Foods |
| Loving Hut |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's extended producer responsibility frameworks gate qualified supply of compostable packaging materials and premium-tier pricing access for compliant manufacturers serving German and French retail channels.
Pricing Analysis
Bundled ingredient-provenance services command substantial premiums over unbundled commodity formulations across the vegan pastry market. Three-tier pricing structure across premium, standard, and economy levels separates artisan café-direct sales from supermarket private-label placement. Price differentiation stems from certification grade and geographic delivery cost, with V-Label and Vegan Society tiers extracting margin premiums. Cost compression in the economy tier is intensifying because oilseed price volatility erodes contract bakery margins. Supermarket chains exhibit the highest price sensitivity, while specialty café networks in Berlin and Munich tolerate parity pricing with conventional equivalents.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian coconut butter and West African shea butter suppliers, exposing margins to weather-driven harvest shocks. Raw material procurement draws from Indonesia, Philippines, and Ghana for structural fats, with precision fermentation alternatives emerging from Netherlands and Denmark research clusters. Supply chain risk centers on commodity price volatility in oilseed corridors. Distribution runs through vertically integrated café-retail hybrid networks in Germany, direct-to-consumer cold-chain platforms, and mass retail slotting arrangements across EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan pastry market reads as a geographic-arbitrage play: India's FSSAI pre-certification costs undercut European compliance timelines by four to six months, enabling export-manufacturing cost advantages for early movers.
For Market Incumbents: Extend backward integration into shea and coconut sourcing corridors to defend against oilseed price volatility. Lock long-term supply agreements with precision fermentation suppliers before capacity constraints tighten. Prioritize certification breadth across EU, US, and Indian regulatory frameworks to maintain cross-border placement flexibility against emerging clean-label specialists.
For New Entrants and Emerging Players: Specialty café networks in secondary German cities present the most penetrable white-space target, as Berlin and Munich incumbents concentrate capacity. India's export-oriented manufacturing hubs offer geographic arbitrage for pre-certified formulations targeting European channels. Lead with aquafaba-based cake formulations to exploit cost advantages and carbon-footprint positioning in celebration-driven segments.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier clean-label specialists lacking café-retail hybrid infrastructure but holding formulation IP. Long-term viability hinges on consolidation into vertically integrated supply chain controllers or café-network operators. Watch certification timeline compression as the inflection signal: approval process delays beyond six months indicate regulatory capacity constraints favoring scaled incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Cultured butter alternatives from Netherlands suppliers remove sensory barriers for mainstream dessert consumers. |
| Extended Producer Responsibility Compliance | Compostable packaging certification secures preferred supplier status with German specialty café networks. |
| FSSAI Pre-Certification Investment | Early compliance with India's plant-based categorization unlocks export-manufacturing cost advantages for European channels. |
| Café-Retail Hybrid Expansion | Visible production locations in Berlin and Munich convert trial into repeat purchase through ingredient storytelling. |
| Clean-Label Emulsifier Sourcing | Exclusive supplier relationships for polysorbate-free stabilizers constrain mid-tier competitor scale-up capacity. |
Research Methodology
Direct dialogue with plant lipid chemists, specialty café operators, clean-label procurement leads, and EFSA regulatory consultants anchored qualitative grounding for this analysis. Secondary validation drew from EU Green Deal implementation documents, FSSAI categorization guidelines, REACH chemical safety registrations, and extended producer responsibility framework filings. Bottom-up and top-down triangulation cross-checked ingredient cost trajectories against channel-level pricing observations.
Bottom-up modeling tracked volume and value outputs across product type, ingredient provenance, packaging compliance tier, and distribution channel density throughout the forecast period. CAGRs were derived from segment-level growth rate assumptions calibrated to reformulation adoption curves and regulatory deadline impacts. Forecast inputs incorporated precision fermentation capacity buildout timelines and clean-label emulsifier supplier qualification rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to oilseed harvest volatility, certification authority backlog expansion, and cultured fat technology cost curves. Forecasts reflect documented assumptions about regulatory implementation pacing and consumer willingness-to-pay parity thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Vegan Food Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
China Rice Protein Market