
 United States Plant Growth Chambers Market | 2026-2036
United States Plant Growth Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Plant Growth Chambers Market Intelligence
The gap between precision-controlled walk-in systems and basic reach-in units is repositioning procurement patterns across American research institutions. Thermo Fisher Scientific leverages its life sciences distribution network to dominate high-throughput phenotyping installations. Percival Scientific sustains its position in seed germination chambers through specialized LED spectrum engineering. Darwin Chambers Company anchors the Midwest market with region-specific service density and rapid calibration turnaround.
Plant growth chambers are enclosed environmental systems that regulate temperature, humidity, light intensity, and photoperiod to simulate precise growing conditions for scientific reproducibility, with specifications typically spanning negative ten to sixty degrees Celsius and relative humidity control from ten to ninety percent. These systems serve primarily to accelerate breeding cycles, validate genetic modifications, and standardize crop stress-response studies under repeatable laboratory conditions. Walk-in chambers capture the largest share of capital expenditure as agricultural research institutes pursue multi-crop parallel testing capacity, while LED lighting technology represents the fastest-advancing segment as institutions replace fluorescent systems to reduce heat load and extend spectral programmability. Automated monitoring systems are maturing rapidly, though margin pools remain concentrated in climate controls where proprietary algorithm development creates differentiation barriers.
USDA research grants through the National Institute of Food and Agriculture shape demand by requiring documented environmental compliance for funded crop science projects, while EPA ENERGY STAR specifications for laboratory-grade equipment constrain product design and filter market access for imported systems. FDA oversight of plant-made pharmaceutical applications indirectly expands chamber requirements for containment-grade tissue culture protocols. Stakeholders must weigh capital allocation between retrofitting existing fluorescent installations against full LED conversion timelines as utility rebate programs and federal procurement standards continue tightening efficiency benchmarks.
Market Dynamics
LED spectral engineering is compressing replacement cycles across American research institutions as utility rebate programs and federal procurement standards tighten efficiency benchmarks faster than capital planning horizons.
Growth Catalysts
- USDA NIFA Grant Requirements:Documented environmental compliance for funded crop science projects mandates certified chamber installations at land-grant universities.
- Biotechnology R&D Expansion:Controlled-environment agriculture investments by seed companies cluster around Illinois and Iowa research corridors.
- EPA ENERGY STAR Specifications:Laboratory-grade equipment standards filter market access and accelerate LED conversion timelines.
Market Restraints
- Capital Equipment Intensity:Walk-in chamber installations require specialized HVAC infrastructure and electrical upgrades.
- Import System Exclusion:EPA compliance certification barriers block European and Asian manufacturers from federal procurement channels.
- Technical Talent Scarcity:Calibration technicians with photobiology expertise concentrate in Midwest metropolitan clusters.
Strategic Opportunities
- Plant-Made Pharmaceuticals:FDA oversight of containment-grade tissue culture protocols expands specialized chamber requirements.
- Automated Monitoring Convergence:Climate control algorithms integrate with phenotyping software platforms.
- Southeast Research Corridor:Underpenetrated university stations in Georgia and North Carolina lack region-specific service density.
Industry Challenges
- Retrofit Integration Complexity:Legacy fluorescent installations require complete HVAC rebalancing for LED heat load reduction.
- Calibration Turnaround Pressures:Research reproducibility standards demand 24-hour service response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Plant Growth Chambers Market |
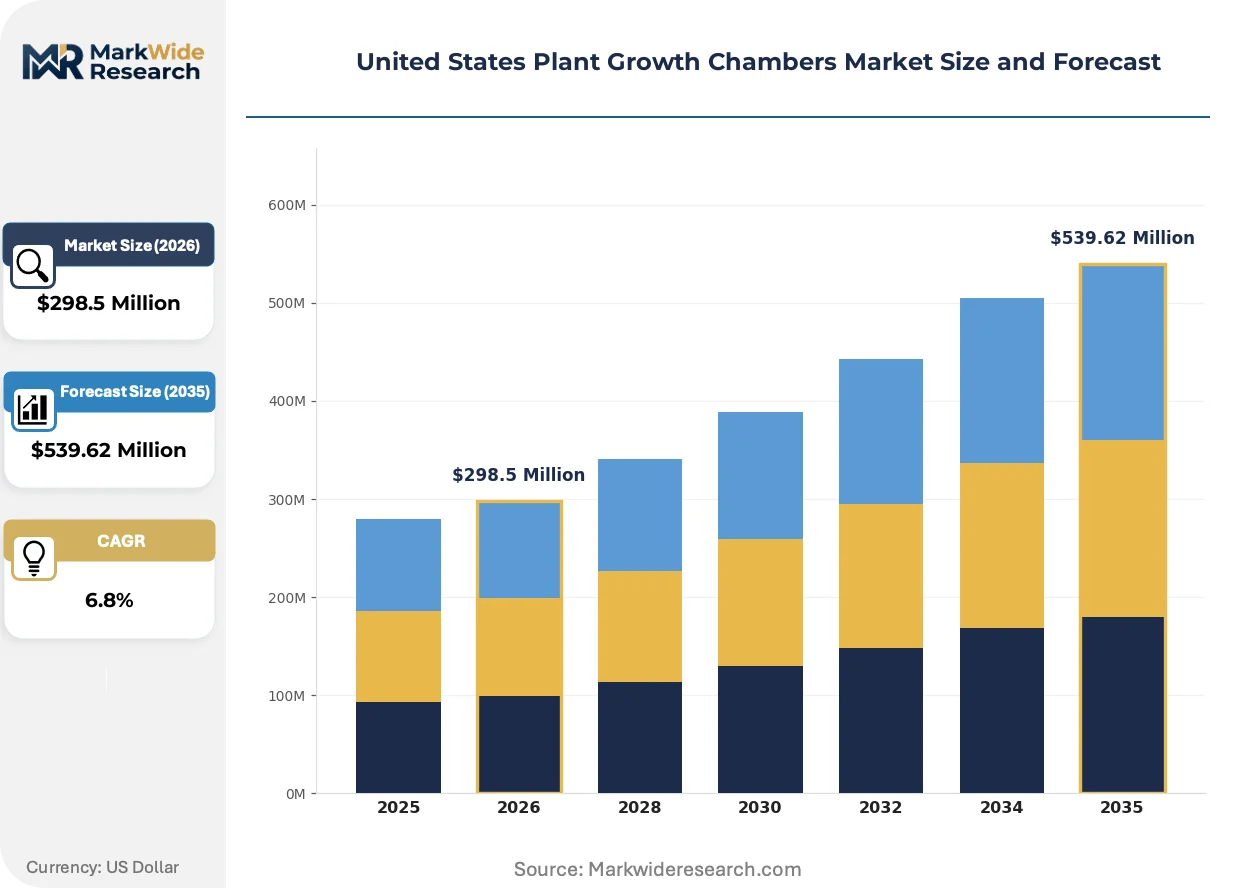
| Market Size in 2026 | $298.5 Million |
| Market Size in 2035 | $539.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-In Chambers, Reach-In Chambers, Seed Germination Chambers, Growth Racks Application: Agronomy Research, Plant Breeding, Tissue Culture, Education End User: Agricultural Research Institutes, Universities, Commercial Growers, Biotechnology Firms Technology: LED Lighting, Climate Controls, Hydroponics Systems, Automated Monitoring |
| Companies Covered | Thermo Fisher Scientific, Percival Scientific, CARON Scientific & Services, Conviron, Darwin Chambers Company, BINDER GmbH, Weiss Technik, PHC Corporation of North America, Control Environments Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Plant Growth Chambers Market Strategic Shifts & Innovations
Spectral programmability and automated environmental logging are compressing the gap between precision research requirements and operational cost constraints.
Dynamic LED arrays with tunable far-red and blue wavelength ratios are unifying photomorphogenesis research with energy efficiency mandates. Agricultural institutes in the Corn Belt adopt these systems within accelerated replacement cycles. This unification enables multi-crop parallel testing protocols previously requiring separate chamber banks.
EPA ENERGY STAR specifications for laboratory-grade equipment constrain product design and filter market access for imported systems. Domestic manufacturers redesign thermal management systems to meet tightening efficiency benchmarks. Seed company R&D facilities in Iowa and Illinois face procurement delays as certification timelines extend.
Service unbundling from equipment sales disrupts traditional distributor relationships in the Midwest. Research stations now contract calibration and preventive maintenance separately from capital purchases. This pattern concentrates in Illinois university clusters where multi-vendor standardization reduces vendor lock-in.
United States Plant Growth Chambers Market Segmentation
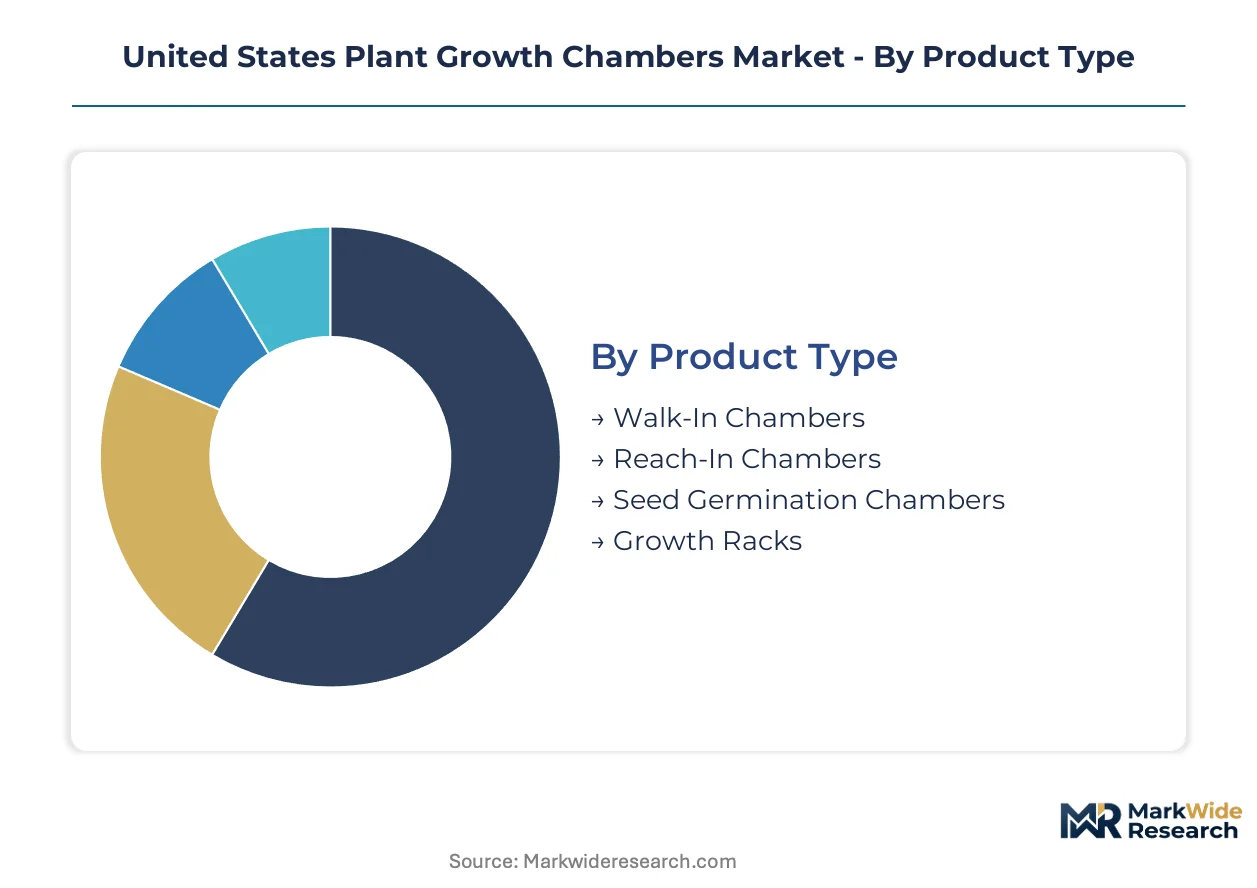
Segmentation in the United States plant growth chambers market reveals how procurement priorities diverge across research missions and facility scales. Capital allocation patterns differ sharply between multi-crop walk-in installations at federal research stations and compact reach-in units deployed for undergraduate laboratory instruction.
Product Type:
Supply concentration in walk-in systems anchors manufacturing capacity around Midwest fabrication facilities serving the Corn Belt research corridor.
- Walk-In Chambers:These large-scale enclosed environments accommodate multi-crop parallel testing with precise climate zoning across separate compartments. Demand concentrates at USDA Agricultural Research Service facilities in Iowa and Illinois where federal breeding programs require simultaneous evaluation of hundreds of genetic lines under controlled conditions.
- Reach-In Chambers:Compact benchtop and floor-standing units serve individual researchers with limited space and budget constraints. University biology departments in Georgia and North Carolina procurement channels favor these systems for their reduced HVAC infrastructure requirements and faster installation timelines.
- Seed Germination Chambers:Specialized units with enhanced humidity control and uniform airflow patterns optimize germination uniformity for viability testing protocols.
- Growth Racks:Modular vertical systems maximize space efficiency in greenhouse transition zones and tissue culture laboratories with limited footprint.
Today's leader: Walk-In Chambers. Tomorrow's challenger: Growth Racks.
Application:
Cost tier differentiation separates capital-intensive breeding programs from budget-constrained educational deployments.
- Plant Breeding:Accelerated generation cycling and precise environmental replication enable seed companies to compress variety development timelines. Biotechnology firms in the Illinois-Iowa corridor invest heavily in these capabilities to maintain competitive positioning in commodity crop markets.
- Agronomy Research:Multi-factor stress studies require programmable environmental sequences simulating drought, heat, and nutrient limitation scenarios. Land-grant universities leverage USDA NIFA grant compliance requirements to justify chamber acquisitions for funded crop science investigations.
- Tissue Culture:Containment-grade protocols for plant-made pharmaceutical applications demand HEPA filtration and positive pressure maintenance.
- Education:Undergraduate laboratory instruction relies on simplified controls and reduced specification ranges to accommodate high student throughput and limited technical support.
Plant Breeding commands premium pricing. Education segments expand volume through standardization.
End User:
Volume concentration among agricultural research institutes shapes service network density and calibration response capabilities.
- Agricultural Research Institutes:Federal and state-funded facilities operate the largest installed base of walk-in chambers with intensive utilization schedules requiring 24-hour maintenance response windows.
- Biotechnology Firms:Controlled-environment agriculture investments by seed companies cluster around Midwest research corridors with specialized requirements for high-throughput phenotyping integration.
- Universities:Diverse procurement patterns span basic instructional equipment through advanced research installations depending on departmental funding levels.
- Commercial Growers:Emerging adoption for cultivar trialing and propagation optimization remains limited by capital intensity relative to greenhouse alternatives.
Agricultural Research Institutes dominate service contract value. Biotechnology Firms drive specification advancement fastest.
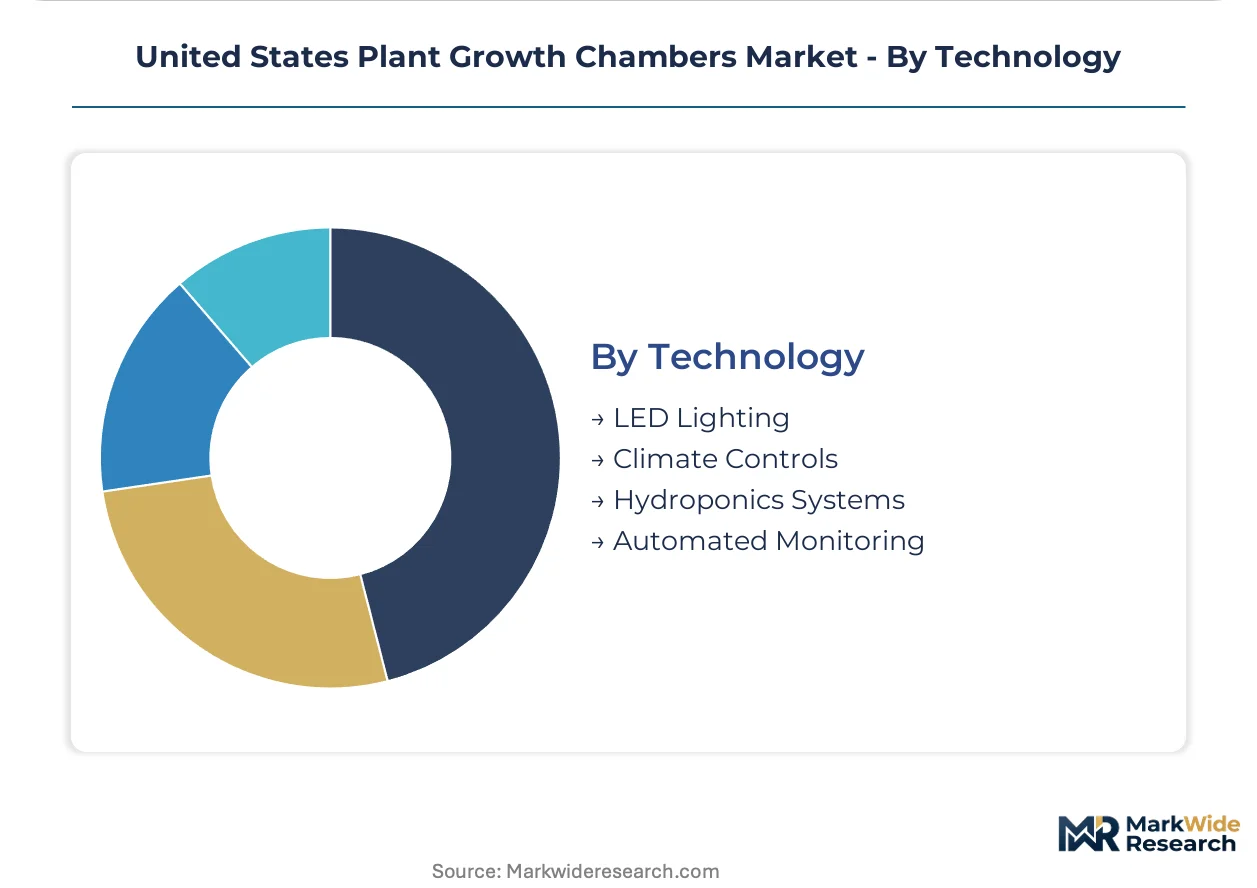
Technology:
Margin concentration in climate control algorithms creates differentiation barriers against commoditized hardware components.
- Climate Controls:Proprietary environmental management systems integrating temperature, humidity, and CO2 regulation represent the highest-value component category with significant aftermarket software licensing revenue.
- LED Lighting:Dynamic spectral programmability with tunable far-red and blue wavelength ratios unifies photomorphogenesis research with EPA ENERGY STAR compliance mandates. Utility rebate programs accelerate replacement of legacy fluorescent installations.
- Automated Monitoring:Sensor networks and data logging systems mature rapidly though margin pools remain thinner than climate control software.
- Hydroponics Systems:Integrated nutrient delivery and root zone temperature management serve specialized tissue culture and controlled-environment agriculture applications.
Climate Controls capture margin concentration. LED Lighting expands fastest under efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technicians with photobiology expertise concentrate in Midwest metropolitan clusters, anchoring service network density around federal research stations and seed company R&D corridors.
Midwest Corn Belt
USDA Agricultural Research Service facilities in Iowa and Illinois drive walk-in chamber demand for multi-crop parallel testing of hundreds of genetic lines. EPA ENERGY STAR certification timelines extend procurement cycles for federal breeding programs. Seed company R&D facilities cluster around Des Moines and Champaign-Urbana with specialized high-throughput phenotyping requirements.
Southeast Research Corridor
University stations in Georgia and North Carolina lack region-specific service density, creating underpenetrated demand for reach-in systems with reduced HVAC infrastructure. USDA NIFA grant compliance mandates chamber acquisitions at land-grant universities expanding crop science investigations. Atlanta and Raleigh-Durham research parks attract controlled-environment agriculture investments with faster installation timelines than Midwest counterparts.
Pacific Northwest
Specialized tissue culture protocols for plant-made pharmaceutical applications expand containment-grade chamber requirements at biotechnology incubators. FDA oversight of pharmaceutical-grade tissue culture drives HEPA filtration specifications. Seattle and Portland metropolitan areas host emerging agricultural technology startups with modular growth rack deployments.
Great Plains
Drought stress research programs at Kansas and Nebraska agricultural experiment stations accelerate climate control algorithm procurement. Utility rebate programs from regional power cooperatives compress LED conversion timelines. Manhattan and Lincoln university clusters standardize on multi-vendor service contracts to reduce vendor lock-in.
Northeast Corridor
Undergraduate laboratory instruction at Massachusetts and New York universities favors compact reach-in units with simplified controls for high student throughput. NSF research infrastructure grants supplement USDA funding for environmental compliance documentation. Boston and Ithaca research institutions prioritize rapid calibration turnaround over capital cost minimization.
United States Plant Growth Chambers Market Key Industry Players
Top-tier vendors anchor the premium specification segment, while mid-tier fabricators compete on regional service density and faster installation timelines. The vendor base stratifies across three tiers: multinational life sciences conglomerates with distribution network advantages, specialized climate control engineering firms with proprietary algorithm development, and regional fabrication shops with Midwest service proximity. Two dominant competitive moves are reshaping positioning: LED spectral engineering partnerships with utility rebate programs, and service unbundling from equipment sales to capture recurring calibration revenue.
Within the specialized engineering tier, Percival Scientific and Darwin Chambers Company exemplify contrasting geographic anchoring strategies. Percival Scientific represents the spectrum-engineering archetype with concentrated seed germination chamber expertise. Darwin Chambers Company occupies a position defined by Midwest service density and rapid calibration response capabilities. Thermo Fisher Scientific anchors the multinational conglomerate tier, leveraging life sciences distribution infrastructure for high-throughput phenotyping installations. These three vendors illustrate how procurement patterns diverge between federal research stations prioritizing service proximity and biotechnology firms seeking phenotyping integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Percival Scientific |
| CARON Scientific & Services |
| Conviron |
| Darwin Chambers Company |
| BINDER GmbH |
| Weiss Technik |
| PHC Corporation of North America |
| Control Environments Ltd |
| Others |
Cost & Logistics Intelligence
EPA ENERGY STAR specifications gate qualified supply and premium-tier pricing access by mandating certified thermal management systems that only domestic manufacturers with Midwest fabrication facilities can deliver within federal procurement timelines. Utility rebate programs compress LED conversion cycles, forcing buyers to choose between expedited premium installations and extended lead times for standard-tier equipment.
Pricing Analysis
The bundled-vs-unbundled service split now dominates procurement negotiations across federal research stations. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified walk-in systems with 24-hour calibration response from basic reach-in units with deferred maintenance schedules. Price differentiation stems from certification tier and geographic service density, with Midwest corridor buyers paying premiums for same-day technician dispatch. Cost compression in standard-tier reach-in chambers intensifies because university biology departments prioritize capital cost minimization over operational uptime guarantees. Education segments exhibit highest price sensitivity; agricultural research institutes demonstrate lowest sensitivity due to grant-funded compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with specialized LED driver manufacturers concentrated in Taiwan and South Korea, where component lead times now extend procurement cycles for spectral-programmable systems. Domestic chamber fabrication draws from Midwest steel fabrication, German precision HVAC components, and Japanese sensor networks. Tariff exposure on imported climate control modules amplifies cost volatility for manufacturers lacking NAFTA-qualifying supply chains. Distribution runs through life sciences equipment distributors with regional service technicians, though direct manufacturer relationships are displacing traditional channel partners for large walk-in installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA ENERGY STAR certification milestones and USDA NIFA grant compliance documentation drive replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anchor Midwest service density through exclusive calibration technician certification programs that lock federal research stations into multi-year maintenance contracts. Deepen backward integration into LED spectral engineering to capture utility rebate program margins currently flowing to third-party lighting vendors. Defend against emerging modular growth rack entrants by embedding climate control algorithms into phenotyping software platforms.
For New Entrants and Emerging Players: University equipment distributors represent the most accessible channel partner type for penetrating the underpenetrated Southeast Research Corridor. Target Georgia and North Carolina land-grant universities with reach-in systems featuring simplified HVAC infrastructure requirements and grant-compliant documentation packages. White-space opportunities concentrate in tissue culture containment protocols for plant-made pharmaceutical applications, where FDA oversight has outpaced incumbent specialization.
For Investors and Strategic Acquirers: Roll-up economics work for regional service-centric chamber fabricators because calibration response capabilities concentrate in discrete metropolitan clusters with limited technician mobility. The 5-10 year viability window favors acquisition of Midwest-based firms with USDA contract relationships and EPA certification expertise. Watch for inflection when EPA proposes tightened efficiency benchmarks that would obsolete legacy fluorescent installations and trigger accelerated replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Spectral Engineering Partnership | Utility rebate program alignment captures efficiency mandate margins ahead of regulatory deadlines. |
| Service Unbundling from Equipment Sales | Recurring calibration revenue stabilizes cash flows amid cyclical federal procurement budgets. |
| Climate Control Algorithm Integration | Phenotyping software platform embedding creates switching costs for biotechnology firm customers. |
| Southeast Corridor Service Expansion | Atlanta and Raleigh-Durham technician placement addresses 48-hour response gaps versus Midwest benchmarks. |
| Containment-Grade Tissue Culture Certification | FDA pharmaceutical-grade protocols open specialized margin pools beyond agricultural research applications. |
Research Approach
Multiple input streams — primary interviews with chamber procurement officers, secondary validation through USDA grant databases and EPA certification records, and trade data reconciliation — were synthesized to construct market estimates. Conversations with agricultural research institute facility managers, university biology department heads, seed company R&D directors, and calibration service technicians informed demand-side dynamics. Secondary sources included federal procurement databases, utility rebate program filings, land-grant university capital expenditure disclosures, and life sciences equipment distributor financial statements. Bottom-up unit economics triangulated against top-down addressable market sizing.
Historical shipment data cross-referenced against expert panel inputs established baseline penetration rates across walk-in, reach-in, and specialized germination chamber categories. The analytical framework modeled demand across product type, application mission, end-user institution class, and technology component with regional granularity through the projection horizon. CAGRs derived from weighted scenario analysis incorporating regulatory compliance deadlines, utility incentive program timelines, and federal research funding trajectories. Industry-specific forecast inputs included USDA NIFA grant award cycles and EPA ENERGY STAR specification revision schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal research funding appropriations, EPA efficiency benchmark tightening schedules, and biotechnology firm consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
LED Farming Market