
 Digital Agriculture Infrastructure Market | 2026-2036
Digital Agriculture Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Agriculture Infrastructure Market Insights
Consolidation among North American commodity crop operators is repositioning procurement power toward fewer buyers with larger digital infrastructure budgets. Deere & Company leverages its embedded base of precision planting hardware to extend software subscription attach rates. Trimble Inc. competes through channel control over GNSS correction networks that anchor high-accuracy field operations. AGCO Corporation differentiates via open-platform architecture that accommodates mixed-fleet environments across fragmented grower cooperatives.
Digital agriculture infrastructure encompasses the networked hardware, software, and data systems that capture, transmit, and act upon agronomic information at sub-field resolution, typically integrating sensor arrays sampling soil moisture at 10-centimeter depth intervals with edge-computing gateways processing telemetry within 50 milliseconds. Its primary purpose is to optimize input application timing, reduce operational waste, and generate auditable yield traceability for downstream food processors. IoT Solutions currently dominates installed connectivity volume across irrigated acreage, while AI Algorithms represent the fastest-expanding margin pool as insurers and grain traders pay premiums for predictive crop models. Cloud Computing sustains the central data layer where multi-season field histories accumulate, though Robotics remains a nascent segment concentrated in high-value specialty crop harvesting.
The EPA regulates pesticide application rates that precision spraying systems must document, while the USDA administers conservation program incentives contingent upon verified digital stewardship records. Compliance with these frameworks shapes platform design requirements and creates barriers for vendors lacking federal certification pathways. Stakeholders must monitor how emerging carbon credit verification standards will restructure data ownership terms between growers and their technology providers.
Market Dynamics
Consolidation among commodity crop operators concentrates procurement power toward fewer buyers with larger digital infrastructure budgets, reshaping vendor pricing power and platform design priorities.
Growth Catalysts
- EPA Data Interoperability Mandates:The EPA and USDA are tightening requirements for farm management platforms, forcing legacy system upgrades and creating replacement demand for certified digital infrastructure.
- Brazilian Soy Belt Digitization:Commercial operators in Mato Grosso are digitizing irrigation and harvest logistics, generating concentrated demand for IoT-enabled soil monitoring arrays and edge-computing gateways.
- Carbon Credit Verification Standards:Emerging protocols for agricultural carbon sequestration are restructuring data ownership terms and requiring auditable yield traceability systems.
Market Restraints
- Semiconductor Supply Concentration:Edge-computing gateway production depends on concentrated Asian foundry capacity, exposing lead time volatility for telemetry processing hardware.
- Legacy Equipment Interoperability:Mixed-fleet environments at fragmented grower cooperatives create technical friction for unified platform deployment.
- Input Cost Volatility:Sensor array manufacturing faces lithium and rare earth price swings that compress hardware margins.
Strategic Opportunities
- AI Algorithm Premium Monetization:Insurers and grain traders are paying premiums for predictive crop models, opening margin expansion beyond hardware sales.
- Open-Platform Architecture Adoption:Mixed-fleet accommodation capabilities create wedge opportunities against closed-ecosystem competitors in cooperative-dominated markets.
- Robotics Integration in Specialty Crops:Nascent harvesting automation in high-value crops offers first-mover positioning before commodity crop saturation.
Industry Challenges
- Agronomic Data Science Talent Scarcity:Platform vendors face acute shortages of specialists capable of integrating sub-field sensor telemetry with machine learning pipelines.
- Federal Certification Timeline Compression:USDA conservation program incentive eligibility requires verified digital stewardship records that demand lengthy compliance documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Agriculture Infrastructure Market |
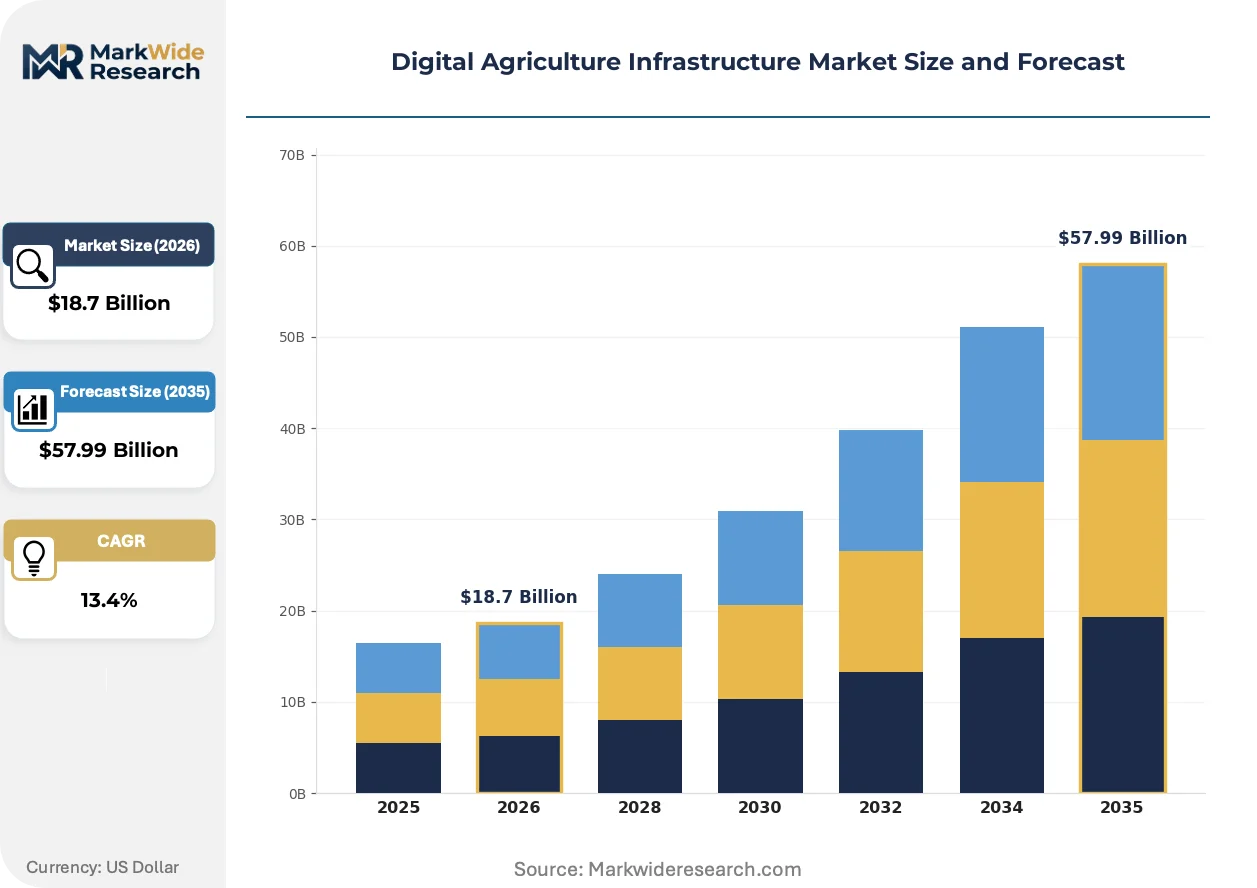
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Software, Automation Systems, Data Analytics Technology: IoT Solutions, Cloud Computing, AI Algorithms, Robotics End Use: Crop Production, Livestock Management, Soil Monitoring, Precision Farming Distribution Channel: Direct Sales, Online Retail, Distributor Partnerships, Resellers |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Bayer AG, Syngenta Group, IBM Corporation, Microsoft Corporation, Topcon Positioning Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Agriculture Infrastructure Market Trends and Innovations
Edge-computing architectures are redistributing data processing from centralized cloud layers to field-level gateways, compressing telemetry-to-action latency and enabling real-time input adjustments.
Edge-computing gateways processing telemetry within 50 milliseconds are decentralizing agronomic decision authority from cloud-based farm management platforms to in-field automation nodes. Large-scale crop production enterprises are expanding procurement of these distributed processing arrays to enable sub-minute irrigation adjustments. This shift is compressing vendor differentiation around latency performance rather than storage capacity.
The EPA's tightening data interoperability requirements for farm management platforms are mandating standardized API architectures and auditable data lineage. Platform vendors must now embed federal certification pathways into product development cycles. Precision spraying system manufacturers face the steepest compliance burden as pesticide application documentation rules harden.
Grain traders and food processors are unbundling after-sales service from hardware procurement, preferring subscription-based predictive analytics over perpetual license models. This shift pressures traditional equipment vendors to restructure revenue recognition. Brazil's commercial operators are most advanced in demanding outcome-based platform performance guarantees tied to yield optimization metrics.
Digital Agriculture Infrastructure Market Segmentation
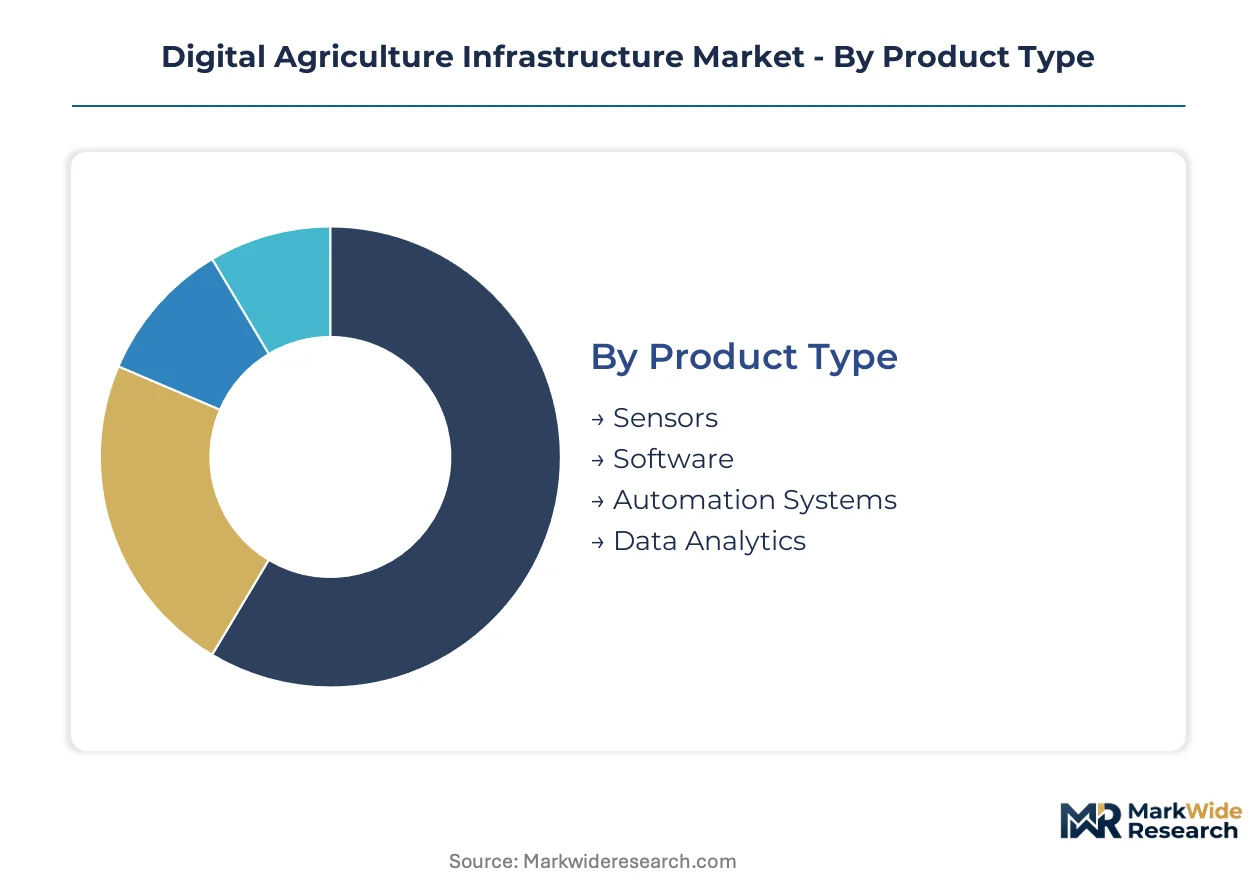
Segmentation in digital agriculture infrastructure reveals how procurement priorities diverge between hardware-intensive operators and software-centric service providers. Understanding these splits exposes where upgrade cycles concentrate and which technology layers command premium pricing.
Product Type:
Replacement cycles for field hardware are shortening as sensor durability improves and firmware updates extend functional lifespans, while software subscriptions face annual renewal pressure.
- Sensors:Soil moisture probes, weather stations, and multispectral imaging arrays capture sub-field agronomic data at 10-centimeter depth intervals. Brazilian Mato Grosso soy operators are expanding procurement of these IoT-enabled arrays as digitization of irrigation systems accelerates.
- Software:Farm management platforms integrate telemetry streams into unified dashboards for input timing optimization. EPA and USDA tightening of data interoperability requirements is forcing legacy system upgrades toward certified platforms.
- Automation Systems:Precision spraying controllers and variable-rate applicators execute field-level commands with sub-meter accuracy.
- Data Analytics:Predictive yield models and risk scoring tools serve insurers and grain traders seeking crop outcome visibility.
Volume placements concentrate in Sensors; the faster expansion belongs to Software.
Technology:
Margin structures vary sharply across technology layers, with connectivity hardware facing commoditization while algorithmic services capture expanding value pools.
- IoT Solutions:Edge-computing gateways and telemetry networks process field data within 50 milliseconds for real-time irrigation adjustments. This segment currently dominates installed connectivity volume across irrigated acreage globally.
- AI Algorithms:Machine learning pipelines transform multi-season field histories into predictive crop models. Insurers and grain traders pay premiums for these capabilities, opening margin expansion beyond hardware sales.
- Cloud Computing:Centralized data layers accumulate multi-season field histories and enable cross-farm benchmarking.
- Robotics:Autonomous harvesting systems and mechanical weeders operate in high-value specialty crops with limited commodity penetration.
IoT Solutions anchor current infrastructure deployment; AI Algorithms are climbing the fastest as predictive services displace reactive management.
End Use:
Application intensity correlates with farm scale and crop value, creating divergent customer profiles across commodity and specialty production systems.
- Crop Production:Large-scale commodity operators deploy comprehensive sensor arrays and automation systems across extensive acreage. Consolidation among North American operators is concentrating procurement power toward fewer buyers with larger digital infrastructure budgets.
- Precision Farming:Sub-field management techniques optimize input application timing and reduce operational waste. Carbon credit verification standards are restructuring data ownership terms and requiring auditable yield traceability in this application.
- Livestock Management:Animal health monitoring and feed optimization systems serve concentrated feeding operations.
- Soil Monitoring:Dedicated moisture and nutrient sensing supports conservation program compliance and irrigation scheduling.
Crop Production absorbs the largest absolute investment; Precision Farming is gaining share fastest as outcome-based performance guarantees take hold.
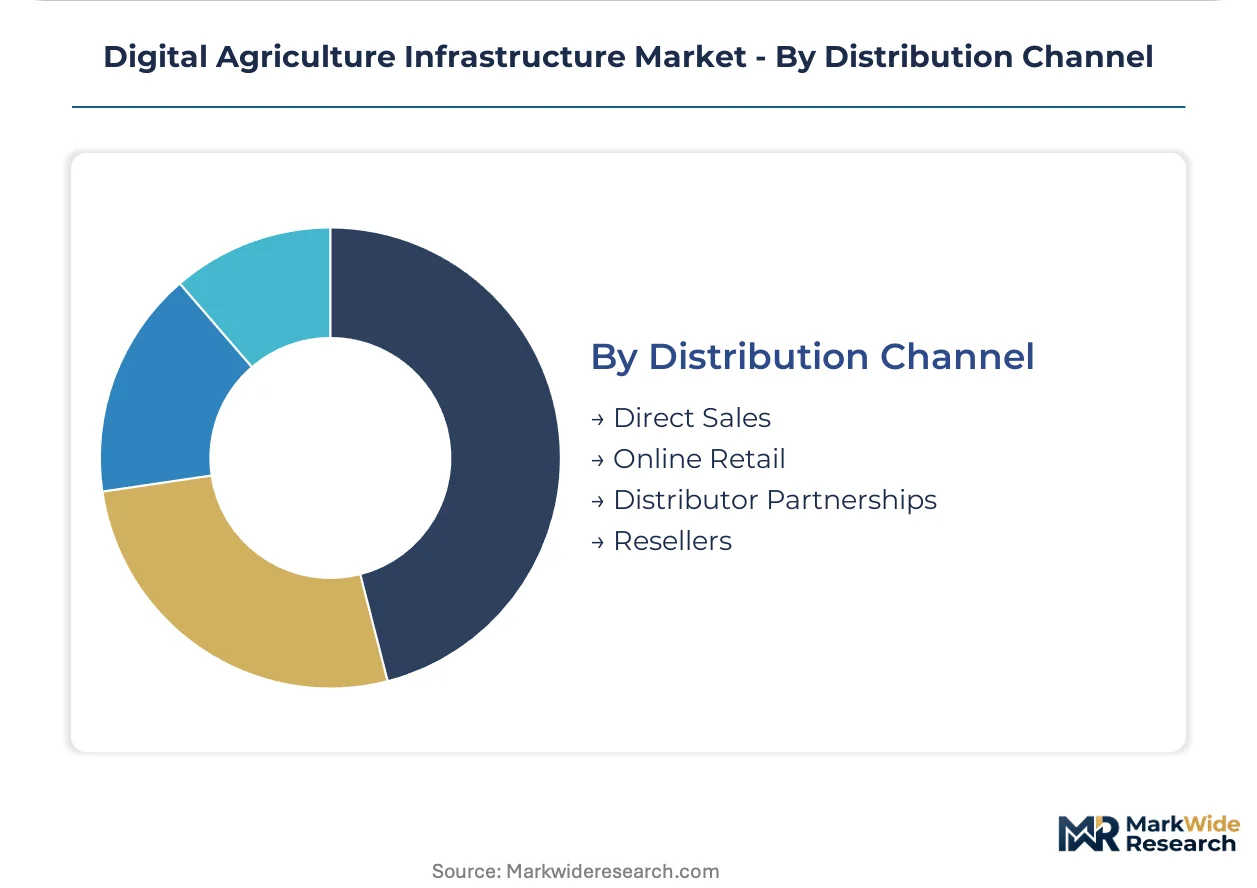
Distribution Channel:
Channel economics reflect the technical complexity of implementation and the ongoing service intensity required for platform optimization.
- Direct Sales:Vendor field teams handle complex multi-year deployments with integrated hardware-software bundles. Deere & Company leverages its embedded precision planting base to extend software subscription attach rates through this channel.
- Distributor Partnerships:Regional agricultural equipment dealers provide local installation support and maintenance coverage. Trimble Inc. competes through channel control over GNSS correction networks that anchor high-accuracy field operations.
- Online Retail:Standardized sensor kits and software licenses reach smaller operators with limited implementation support.
- Resellers:Independent systems integrators assemble mixed-vendor solutions for fragmented grower cooperatives.
Direct Sales capture the highest-value enterprise contracts; Distributor Partnerships are expanding most quickly as vendors pursue cooperative-dominated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean cultivation in Brazil's Mato Grosso state anchors procurement intensity for IoT-enabled soil monitoring arrays. Corn belt operators in the United States drive replacement cycles for precision planting hardware. European Union conservation compliance requirements reshape data platform architectures across member states.
United States
Consolidated commodity crop operators in Iowa and Illinois concentrate procurement power for comprehensive sensor deployments. The EPA mandates standardized API architectures for pesticide application documentation, forcing legacy platform upgrades. California's Central Valley specialty crop producers pioneer subscription-based predictive analytics adoption.
Brazil
Commercial soy and corn operators in Mato Grosso digitize irrigation systems and harvest logistics at scale. ANVISA coordinates with agricultural regulators on data interoperability standards for input traceability. São Paulo state's agribusiness clusters anchor Latin America's largest precision farming equipment distribution networks.
Germany
Baden-Württemberg's machinery manufacturers integrate edge-computing gateways into precision spraying controllers for EU market compliance. The EU Green Deal's carbon credit verification protocols restructure data ownership terms between growers and technology providers. Bavarian dairy cooperatives deploy livestock monitoring systems with conservation program eligibility documentation.
China
Shandong Province's wheat belt accelerates procurement of soil moisture probe arrays for water conservation compliance. MIIT standards for agricultural IoT device interoperability shape domestic platform development priorities. Yangtze River Delta technology clusters concentrate AI algorithm development for crop yield prediction services.
Australia
Murray-Darling Basin irrigators deploy telemetry networks for real-time water allocation compliance and deficit irrigation scheduling. The country's national agricultural regulator enforces data lineage standards for drought resilience program participation. Queensland's sugar cane regions adopt edge-computing architectures for sub-minute irrigation adjustments during critical growth windows.
Digital Agriculture Infrastructure Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithmic services and carbon verification platforms. Three tiers structure competitive positioning: integrated equipment manufacturers with embedded hardware bases, specialized precision technology vendors with channel-controlled accuracy networks, and open-platform architects serving fragmented cooperative environments. Consolidation among commodity crop operators concentrates procurement power toward fewer buyers with larger digital infrastructure budgets. Dominant competitive moves include M&A to acquire agronomic data science capabilities and strategic partnerships to embed federal certification pathways into product development cycles.
Within the integrated equipment tier, Deere & Company and AGCO Corporation represent contrasting architectural philosophies. Trimble Inc. anchors the specialized precision technology segment with channel control over GNSS correction networks. IBM Corporation and Microsoft Corporation exemplify cloud and AI service providers penetrating agricultural verticals through platform partnerships rather than field hardware deployment.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Bayer AG |
| Syngenta Group |
| IBM Corporation |
| Microsoft Corporation |
| Topcon Positioning Systems |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between EPA-compliant platforms and uncertified legacy systems splits both pricing power and sourcing strategies across the vendor base. Premium-tier vendors embed federal validation pathways into development cycles, commanding subscription premiums while locking in multi-year procurement contracts from consolidated commodity operators.
Pricing Analysis
Warranty and predictive maintenance bundling separates enterprise-tier platform vendors from hardware-only suppliers in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service intensity. Price differentiation hinges on EPA validation status and GNSS correction network access. Margins are tightening in sensor hardware due to lithium and rare earth cost volatility. Smallest fragmented grower cooperatives exhibit highest price sensitivity; large-scale Mato Grosso soy operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Freight cost exposure from Asian semiconductor foundries to North American assembly plants compresses margin buffers for edge-computing gateway manufacturers. Production concentrates in Taiwan, South Korea, and China for telemetry processing chips. Component sourcing draws from Chilean lithium deposits, Chinese rare earth processors, and German precision sensor foundries. Single-source vulnerability in 7-nanometer fab capacity threatens lead time stability. Distribution runs through regional agricultural equipment dealer networks with localized installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPA's tightening data interoperability mandates erect a cost-of-compliance barrier that favors incumbent platform vendors with established federal certification pathways. This regulatory moat protects validated players while forcing legacy system obsolescence.
For Market Incumbents: To counter open-platform challengers in cooperative-dominated markets, Deere and AGCO should deepen channel control through exclusive GNSS correction network partnerships and accelerate agronomic data science hiring to close talent gaps. Backward integration into edge-computing gateway assembly reduces exposure to Asian foundry concentration. For New Entrants and Emerging Players: AI-first algorithmic services offer the most penetrable wedge against hardware-anchored incumbents, particularly in Brazilian Mato Grosso where outcome-based performance guarantees are displacing perpetual licenses. Target carbon credit verification platforms as the fastest-expanding margin pool. Pursue strategic partnerships with grain traders and insurers seeking predictive crop models rather than direct field hardware deployment. For Investors and Strategic Acquirers: Re-rating potential sits with specialized precision technology vendors given carbon credit verification standardization as a catalyst for data ownership restructuring. Long-term viability favors players with embedded accuracy network infrastructure and federal certification pipelines. Watch EPA enforcement intensity on pesticide application documentation as the signal for replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified telemetry dashboards satisfy EPA data interoperability mandates for pesticide documentation. |
| Strategic Partnership | GNSS correction network alliances anchor high-accuracy field operations for consolidated buyers. |
| Acquisition of Specialist Firm | Agronomic data science talent scarcity drives M&A for machine learning pipeline capabilities. |
| Geographic Expansion | Brazilian Mato Grosso soy belt digitization concentrates demand for irrigation monitoring arrays. |
| Product Launch | Carbon credit verification platforms restructure data ownership terms between growers and providers. |
Research Methodology
Trade databases, EPA regulatory filings, and USDA conservation program records formed the secondary backbone, supplemented by primary interviews with farm management platform executives, precision agriculture equipment dealers, and agronomic data scientists. Triangulation across bottom-up sensor shipment tracking and top-down platform revenue aggregation validated market sizing. Stakeholder consultations included IoT gateway manufacturers, grain trader risk management officers, and Brazilian agribusiness procurement leads.
Bottom-up modeling anchored volume estimates in irrigated acreage penetration rates and hardware replacement cycles, while top-down analysis cross-checked against vendor-reported subscription revenues and federal conservation program enrollment data. Segmentation dimensions spanned product type, technology layer, end-use application, and distribution channel. CAGRs derived from regression analysis of multi-season field history accumulation patterns and predictive analytics adoption curves across commodity and specialty crop operators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated carbon credit verification standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
US Smart Agriculture Market