
 United States Grow Light Market | 2026-2036
United States Grow Light Market Size, Share, and Industry Trends Forecast 2026-2036
United States Grow Light Market Intelligence
LED chip-on-board arrays are repositioning high-pressure sodium fixtures out of premium indoor installations. Signify Holding leverages its horticultural lighting division to sustain R&D pipelines across controlled-environment portfolios. California LightWorks anchors its position through domestic manufacturing scale in the western states. Mars Hydro competes aggressively on direct-to-cultivator channel control, while VIVOSUN extends its reach through bundled grow-system offerings.
United States grow lights are electrically powered luminaires engineered to emit photosynthetically active radiation in the 400–700 nanometer range, typically incorporating aluminum heat sinks, diode drivers, and spectral tuning for chlorophyll absorption peaks. Their primary commercial purpose is to substitute or supplement solar irradiance in environments where natural light duration or intensity falls below crop photoperiod requirements. LED product types now dominate margin pools due to tunable spectrum capability and thermal efficiency, while HPS installations retain share in legacy greenhouse retrofits where capital constraints slow replacement cycles. Application demand clusters around vegetable cultivation and flowering plants, with vertical farming installations representing the fastest-growing installation type as real estate costs in urban corridors push production upward.
The Department of Energy sets minimum efficacy standards that filter inefficient legacy technologies from federally subsidized agricultural projects, while OSHA workplace safety rules govern electrical installation and thermal exposure in commercial grow facilities. The EPA's Energy Star certification program creates product differentiation for LED manufacturers that meet strict photon efficacy thresholds. State-level cannabis regulatory boards in California, Colorado, and Michigan impose traceability and security requirements that indirectly mandate reliable lighting infrastructure for compliance documentation. Stakeholders must monitor how evolving federal agricultural energy incentives and state cannabis licensing trajectories reshape capital deployment timelines for indoor cultivation infrastructure.
Market Dynamics
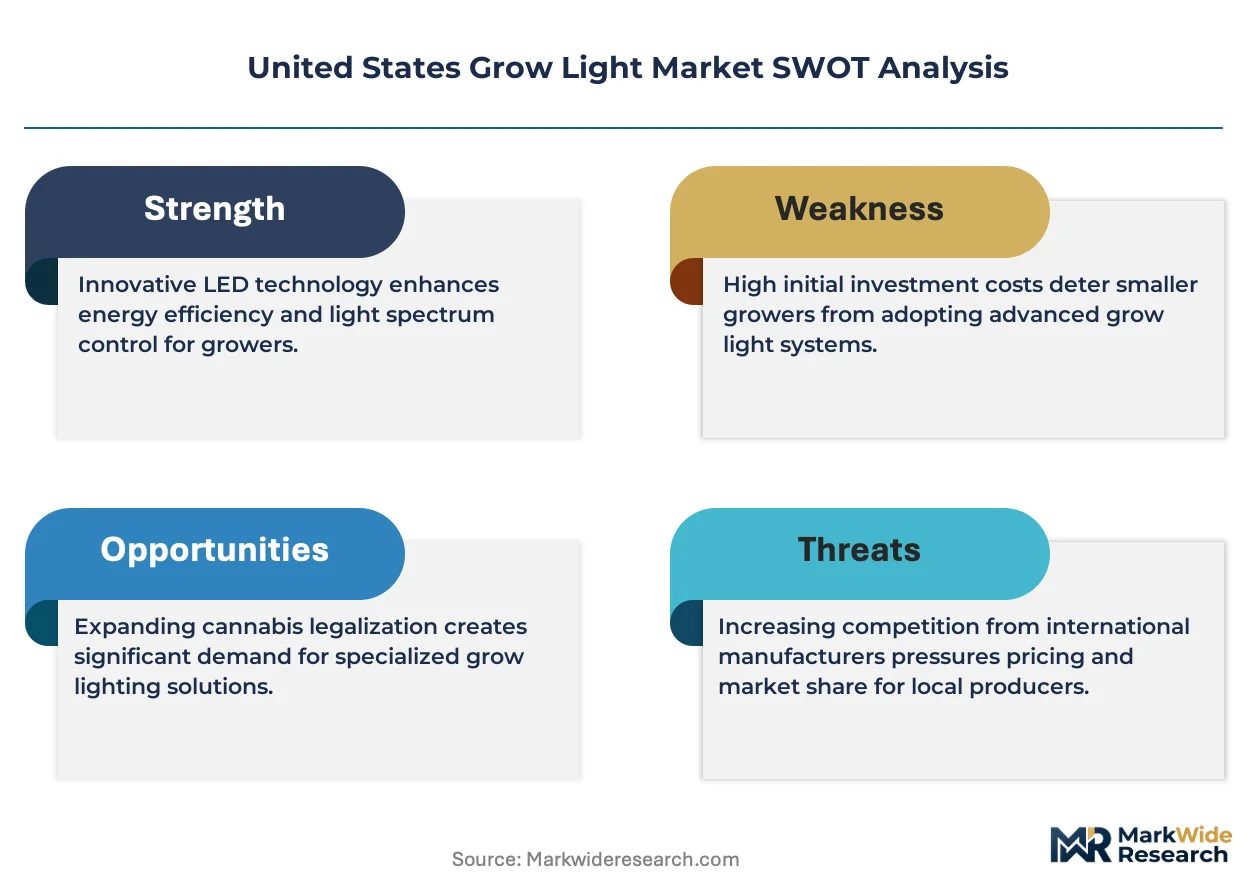
The Department of Energy's appliance efficiency standards are compressing legacy HPS fixture margins while redirecting capital toward LED architectures in commercial cannabis and controlled-environment vegetable operations across California, Colorado, and Michigan.
Growth Catalysts
- IRA Clean Energy Tax Credits:Federal investment tax credits for energy-efficient agricultural equipment accelerate LED retrofit timelines in indoor cultivation facilities.
- Controlled-Environment Agriculture:Vertical farming installations in urban corridors from New York to Seattle drive demand for tunable-spectrum fixtures that optimize photoperiod control.
- State Cannabis Legalization:Regulatory boards in Michigan and Illinois mandate traceability infrastructure that requires reliable lighting systems for compliance documentation and security protocols.
Market Restraints
- Aluminum Price Volatility:Heat sink manufacturing costs fluctuate with commodity metal markets, squeezing fixture margins for domestic producers.
- LED Driver Supply Concentration:Asian semiconductor foundries control critical diode driver components, exposing assemblers to shipping disruptions and tariff exposure.
- Legacy Greenhouse Capital Constraints:HPS installations persist where retrofit financing is unavailable, delaying technology turnover in mature protected-culture operations.
Strategic Opportunities
- Southwest Urban Corridors:Phoenix and Las Vegas metropolitan areas present underpenetrated demand for vertical farming infrastructure amid water scarcity pressures.
- Utility Rebate Programs:Pacific Coast electric cooperatives offer demand-side management incentives that subsidize high-efficacy LED adoption in commercial grow operations.
- Spectral-Tuning Software:Integration of IoT sensors with diode arrays enables real-time chlorophyll absorption optimization, creating service revenue streams beyond hardware sales.
Industry Challenges
- Horticultural Lighting Engineering Talent:The intersection of photobiology and electrical systems design requires specialized expertise that remains scarce in domestic labor markets.
- OSHA Thermal Compliance:Commercial facilities must manage heat dissipation from high-density diode arrays to meet workplace safety exposure limits.
- Energy Star Certification Timelines:EPA photon efficacy verification processes create product launch delays for manufacturers pursuing premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Grow Light Market |
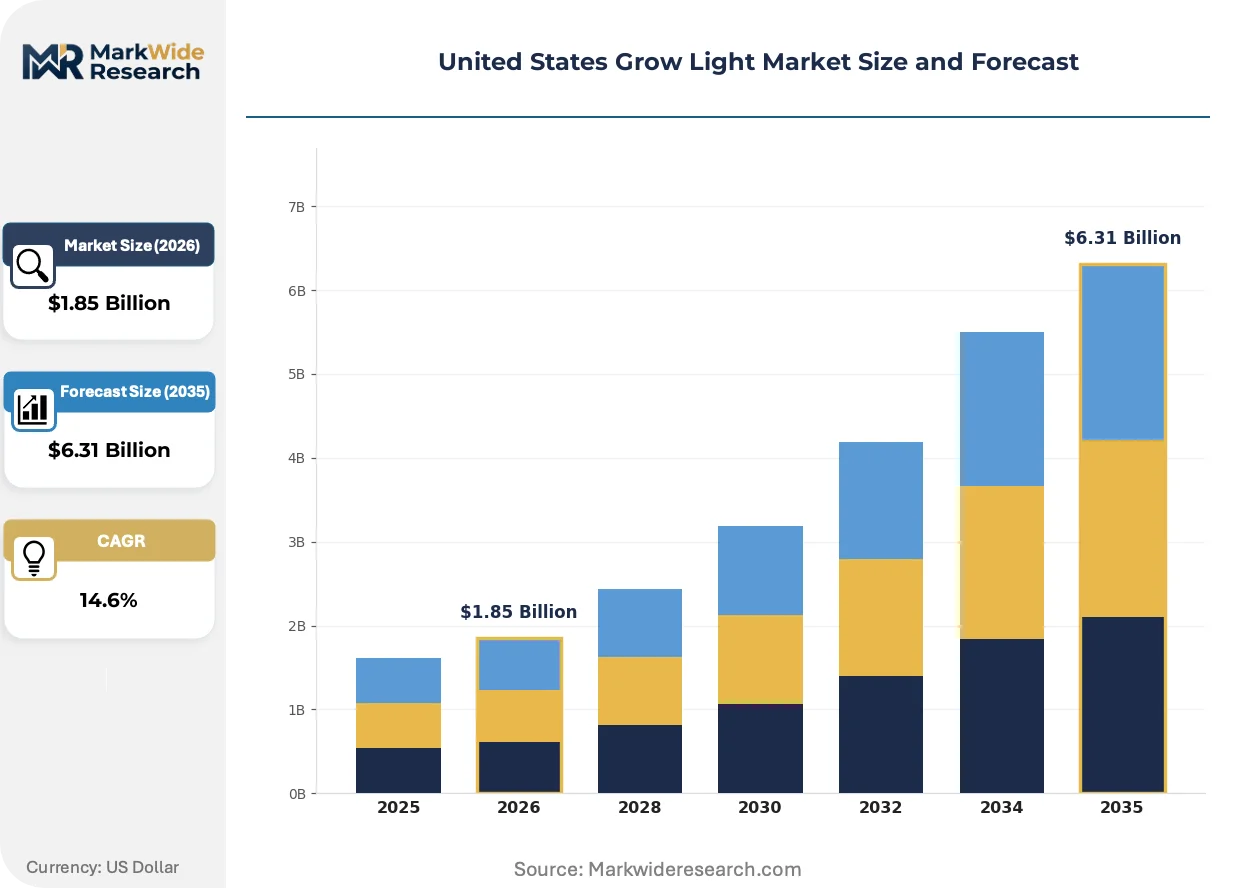
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HPS, Fluorescent, CMH Application: Vegetable Cultivation, Fruit Production, Flowering Plants, Seed Germination Installation Type: Indoor, Outdoor, Hydroponic, Vertical Farming Control Mechanism: Manual, Digital, Smart, Automated |
| Companies Covered | Signify Holding, California LightWorks, Heliospectra, Valoya, Kind LED Grow Lights, VIVOSUN, Mars Hydro, ViparSpectra, Biological Innovation and Optimization Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Grow Light Market Strategic Shifts & Innovations
Spectral control architectures and connected fixture management are compressing the performance gap between artificial and solar irradiance. Three developments dominate capital allocation and product roadmaps.
Chip-on-board LED arrays are integrating phosphor-converted white diodes with discrete red and blue emitters to match chlorophyll A and B absorption peaks precisely. Large-scale vegetable cultivators in Arizona and Texas greenhouses are adopting these systems at accelerated replacement cycles. The technology is integrating photobiological research directly into fixture firmware, enabling cultivators to program growth-stage-specific spectra without hardware swaps.
OSHA workplace safety rules governing electrical installation and thermal exposure in commercial grow facilities are tightening enforcement protocols. Inspectors now mandate documented heat-mapping for facilities exceeding 50,000 square feet of illuminated canopy. Cannabis operations in Colorado and California are responding by specifying fixtures with integrated thermal monitoring and automatic dimming safeguards.
Cultivator procurement teams are consolidating vendor relationships around full-system providers rather than component sourcing. Direct-to-facility distribution channels are displacing traditional electrical supply houses for orders above 500 fixtures. This concentration is most visible in Michigan's emerging cannabis market, where multi-license operators negotiate enterprise pricing for bundled lighting, climate control, and monitoring platforms.
United States Grow Light Market Segmentation
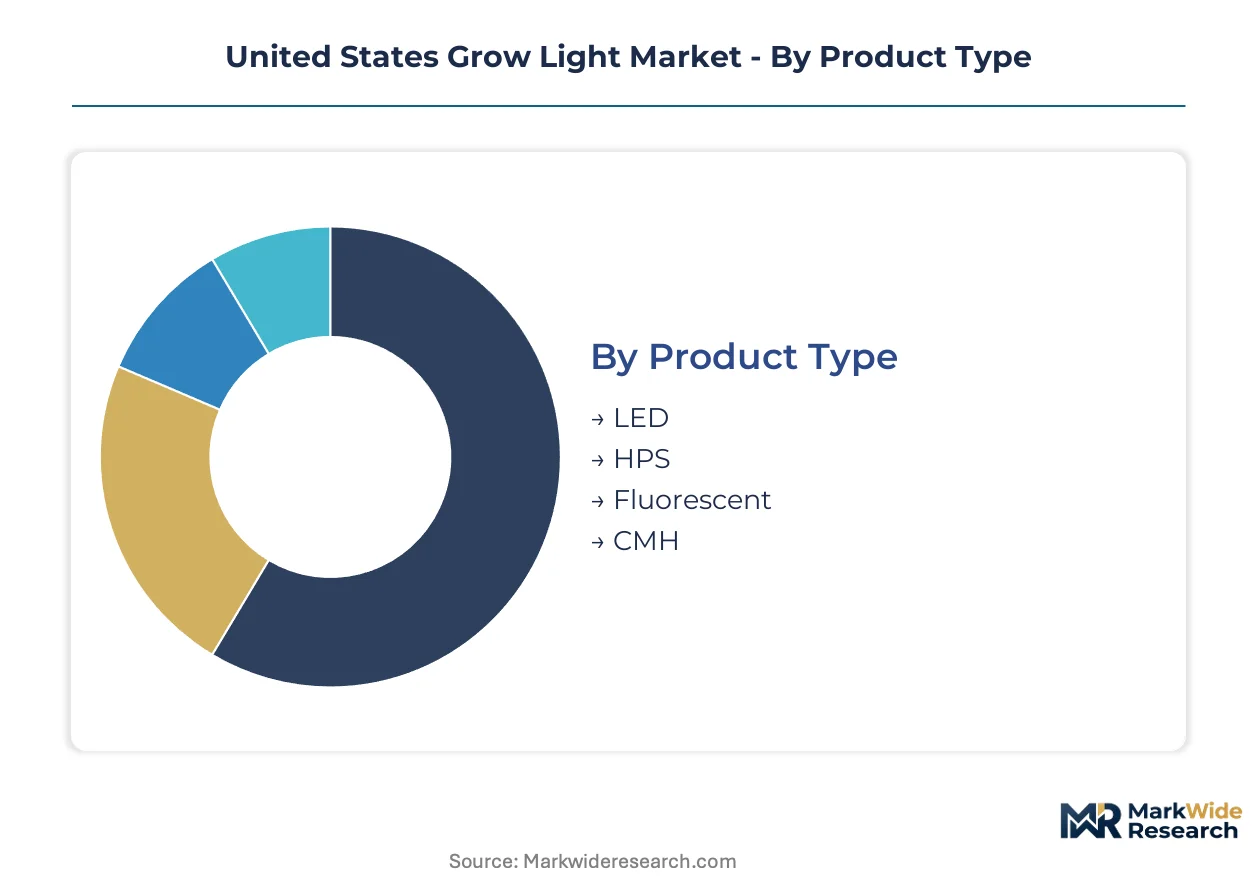
Segmentation in the United States grow light market reveals how technology choices cascade through installation economics, regulatory compliance, and cultivator operational models. Product architecture decisions determine thermal management requirements, while application specificity drives spectral tuning investments.
Product Type:
LED fixtures command premium positioning through efficacy advantages, while HPS retains volume share in capital-constrained retrofits. The volume-premium split reflects divergent payback period tolerances across cultivator segments.
- LED:Chip-on-board arrays with aluminum heat sinks and tunable 400–700 nanometer output dominate new installations in California and Colorado cannabis facilities. Pacific Coast utility rebate programs accelerate replacement of legacy fixtures in vegetable operations.
- HPS:High-pressure sodium arc tubes deliver photosynthetic photon flux density at lower capital cost, sustaining share in Michigan greenhouse retrofits where financing constraints delay LED transitions. Thermal output complicates OSHA compliance in dense canopy configurations.
- Fluorescent:T5 and compact tube formats serve seedling propagation racks with lower intensity requirements in Southwest vertical farming startups.
- CMH:Ceramic metal halide systems offer broad-spectrum output for research institutions and specialty crop breeders prioritizing color rendering accuracy over energy efficiency.
Mature deployment sits with HPS in legacy protected-culture operations. Newer deployment is concentrated in LED architectures across controlled-environment cannabis and vegetable facilities.
Application:
Cultivation purpose dictates photoperiod complexity and fixture density, with flowering crops requiring precise spectrum manipulation across growth stages.
- Vegetable Cultivation:Leafy greens and herbs in Arizona and Texas greenhouse clusters demand consistent daily light integral with minimal spectral variation. LED fixtures with fixed white-phosphor output satisfy these requirements at declining cost per micromole.
- Flowering Plants:Cannabis and ornamental crops require red-spectrum enrichment during reproductive phases, driving demand for tunable diode arrays in Colorado and Michigan licensed facilities. State traceability mandates reinforce investment in reliable, documentable lighting infrastructure.
- Fruit Production:Tomato and pepper operations in Southwest hydroponic greenhouses utilize high-intensity discharge supplemental lighting during winter photoperiod deficits.
- Seed Germination:Propagation chambers in urban vertical farms employ low-wattage fluorescent or early-stage LED arrays with minimal heat generation for delicate seedling establishment.
Commercial scale concentrates in vegetable and flowering applications. Seed germination represents the most fragmented, facility-specific deployment pattern.
Installation Type:
Real estate costs and water scarcity pressures are redistributing cultivation architecture across the continental United States.
- Vertical Farming:Stacked rack systems in New York and Seattle metropolitan corridors maximize production per square foot, demanding compact, low-profile LED fixtures with integrated thermal management. This segment gains share fastest as urban agriculture capital flows intensify.
- Indoor:Warehouse conversions in California and Colorado cannabis markets require complete solar substitution through high-density diode arrays, with OSHA thermal exposure rules governing fixture spacing and aisle width.
- Hydroponic:Nutrient film technique and deep-water culture operations in Southwest states combine grow lights with recirculating systems, prioritizing moisture-resistant fixture housings.
- Outdoor:Supplemental lighting in Texas and Florida field operations extends photoperiods for off-season production, utilizing weather-rated HPS or LED flood configurations.
Outdoor supplemental deployment remains mature and price-sensitive. Indoor and vertical configurations represent the steepest expansion trajectory for premium fixture sales.
Control Mechanism:
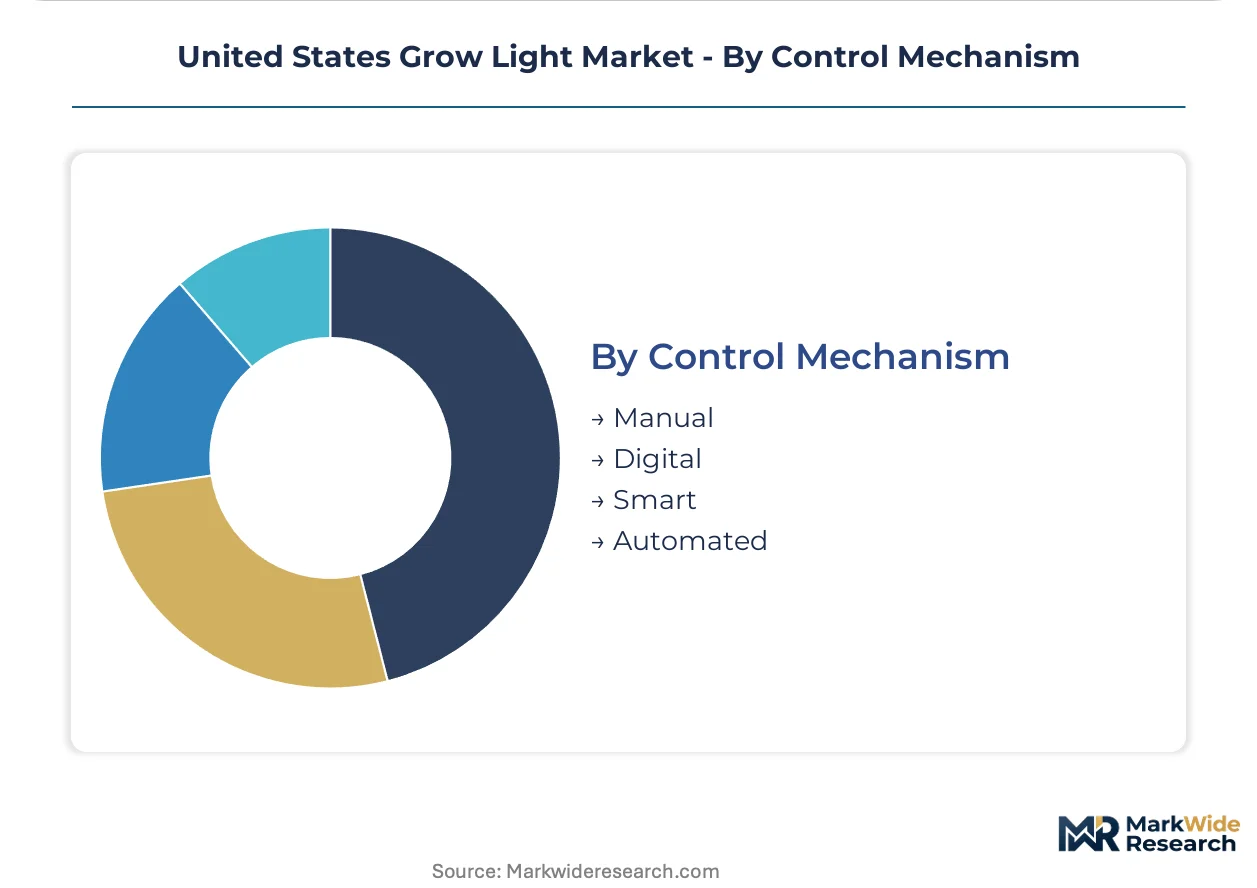
Automation depth separates commodity hardware from value-added system sales, with integration complexity rising alongside facility scale.
- Smart:IoT-enabled fixtures with spectral-tuning firmware and cloud-connected monitoring command pricing premiums in Michigan multi-license cannabis operations seeking enterprise-scale climate platform integration.
- Automated:Programmable logic controllers manage photoperiod, intensity, and spectrum sequencing without human intervention, prevalent in Arizona commercial vegetable facilities with standardized crop cycles.
- Digital:Timer-based dimming and switching systems offer intermediate automation for mid-scale cultivators in Colorado transitioning from manual operations.
- Manual:Basic on-off switching persists in small-scale and research installations where operational labor costs remain negligible.
Manual control dominates legacy and research installations. Smart and automated systems are concentrating in new commercial facilities seeking labor efficiency and compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level cannabis tax frameworks are concentrating capital deployment in Southwest and Pacific Coast corridors where water scarcity and energy costs reshape cultivation economics.
California
Cannabis license caps in Humboldt and Santa Barbara counties drive facility consolidation toward enterprise-scale LED retrofits. The state's cannabis regulatory board mandates seed-to-sale tracking that requires documented environmental controls. Los Angeles and Oakland warehouse conversions dominate indoor installation demand as urban agriculture capital flows intensify.
Colorado
Denver Metro's mature cannabis market prioritizes operational efficiency over expansion, favoring spectral-tuning upgrades in existing facilities. OSHA thermal compliance enforcement tightened following 2023 workplace safety audits in Pueblo County grow operations. Boulder and Fort Collins research institutions anchor demand for ceramic metal halide systems in plant science applications.
Michigan
Detroit and Grand Rapids multi-license operators negotiate bundled procurement for lighting and climate platforms at scale. State cannabis regulators impose security and traceability infrastructure requirements that indirectly mandate reliable fixture performance. The Great Lakes region's variable solar availability sustains year-round supplemental lighting demand in vegetable greenhouses.
Arizona
Phoenix metropolitan vertical farming startups exploit water scarcity premiums to justify capital-intensive LED installations. Utility rebate programs from Arizona Public Service subsidize high-efficacy fixture adoption in commercial grow operations. Tucson greenhouse clusters adopt chip-on-board arrays for tomato and pepper winter production cycles.
Pacific Northwest
Seattle and Portland urban agriculture ventures maximize production per square foot through stacked rack configurations demanding compact thermal management. Washington State's cannabis regulatory framework emphasizes energy efficiency in licensing criteria. The region's cloudy winter photoperiod deficits sustain consistent demand for supplemental vegetable cultivation lighting.
United States Grow Light Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium fixture sales concentrating around horticultural lighting divisions of diversified electronics groups while volume tiers fragment among direct-to-cultivator channels. The vendor base organizes around three archetypes: legacy lighting conglomerates with horticultural divisions, domestic manufacturing specialists with regional distribution control, and direct-channel brands competing on price-accessibility. Consolidation pressures intensify as multi-license operators demand enterprise-scale procurement relationships. Technology licensing agreements between semiconductor foundries and fixture assemblers reshape upstream supply control.
Within the diversified electronics tier, Signify Holding anchors positioning through horticultural lighting R&D pipelines. California LightWorks exemplifies domestic manufacturing scale concentration in western states. Mars Hydro occupies the direct-to-cultivator channel control position through aggressive e-commerce and bundled system offerings. These three archetypes represent the competitive vectors—conglomerate R&D leverage, regional manufacturing proximity, and channel price disruption—that structure capital deployment and margin capture across installation types.
| Leading Market Players |
|---|
| Signify Holding |
| California LightWorks |
| Heliospectra |
| Valoya |
| Kind LED Grow Lights |
| VIVOSUN |
| Mars Hydro |
| ViparSpectra |
| Biological Innovation and Optimization Systems |
| Others |
Cost & Logistics Intelligence
EPA Energy Star certification gates qualified supply and premium-tier pricing access for LED fixture manufacturers, compressing margins for uncertified competitors while concentrating pricing power among verified producers serving federally subsidized agricultural projects.
Pricing Analysis
Lead-time-driven pricing stratifies across three tiers: premium fixtures with sub-30-day domestic fulfillment command 15-25% markups over standard inventory, while spot-market Asian imports trade at discounts with extended delivery windows. Pricing stratifies across premium, standard, and economy tiers based on photon efficacy certification and spectral-tuning capability. Cost compression in economy-tier chip-on-board arrays is intensifying because Pacific Coast utility rebate programs subsidize high-efficacy alternatives. Small-scale cultivators and research installations exhibit highest price sensitivity; multi-license cannabis operators in Michigan and California demonstrate lowest sensitivity due to enterprise procurement scale.
Supply Chain Analysis
Warehouse-distribution layer consolidation concentrates inventory in Phoenix, Los Angeles, and Denver regional distribution centers serving Southwest and Pacific Coast cultivation corridors. Semiconductor foundries in Taiwan, South Korea, and China control critical LED driver components, exposing domestic assemblers to shipping disruptions and tariff exposure. Aluminum heat sink fabrication draws from domestic extrusion capacity in Ohio and Pennsylvania, with commodity metal price volatility squeezing fixture margins. Distribution runs through direct-to-facility channels for orders above 500 fixtures, displacing traditional electrical supply houses in Michigan and Colorado cannabis markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic LED driver fabrication capacity constraints prop pricing power for qualified suppliers, creating durable margin pools for certified manufacturers serving federally subsidized controlled-environment agriculture projects.
For Market Incumbents: Extend spectral-tuning software capabilities to capture recurring service revenue beyond hardware sales, while consolidating vendor relationships with multi-license operators in Michigan and Colorado seeking bundled climate platform procurement. Backward integration into aluminum heat sink fabrication mitigates commodity price volatility exposure threatening fixture margins. Prioritize OSHA thermal compliance documentation to defend positioning against low-cost Asian imports lacking certified safeguards. For New Entrants and Emerging Players: The price-point gap between premium Energy Star-certified fixtures and uncertified economy imports creates white-space opportunity for mid-tier players offering efficacy-verified products at standard-tier pricing. Arizona and Nevada vertical farming startups represent the most penetrable geography, with water scarcity pressures justifying capital-intensive LED installations. Target utility rebate program eligibility as the primary go-to-market angle, positioning fixtures to capture Pacific Coast demand-side management incentives. For Investors and Strategic Acquirers: Michigan state cannabis regulatory board mandates for traceability infrastructure is the leading indicator that lighting-system reliability will concentrate procurement among enterprise-scale suppliers with compliance documentation capabilities. Acquisition targets should feature IoT-enabled fixture platforms with cloud-connected monitoring serving multi-license operators. Long-term viability across the projection horizon hinges on spectral-tuning firmware differentiation and thermal management engineering talent retention.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic LED Driver Manufacturing Scale-Up | Reduces tariff exposure and shipping disruption risk for fixture assemblers serving federal agricultural projects. |
| Spectral-Tuning Software Licensing | Creates recurring revenue streams beyond hardware sales through chlorophyll absorption optimization subscriptions. |
| OSHA Thermal Compliance Certification Investment | Accelerates facility approval timelines for commercial cannabis operations in Colorado and California. |
| Utility Rebate Program Partnership Development | Unlocks Pacific Coast demand-side management incentives subsidizing high-efficacy LED adoption. |
| Vertical Farming System Bundling | Captures urban agriculture capital flows in Phoenix and Las Vegas through integrated lighting-climate platforms. |
Research Approach
Multi-period observation of fixture shipment volumes, utility rebate program disbursements, and state cannabis licensing trajectories anchored the trend analysis, supplemented by interviews with controlled-environment agriculture facility operators, horticultural lighting procurement managers, semiconductor supply chain specialists, and EPA Energy Star certification coordinators. Secondary validation drew from Department of Energy appliance efficiency standard filings, OSHA workplace safety enforcement records, state regulatory board traceability mandates, and Pacific Coast electric cooperative demand-side management reports. Bottom-up cultivation facility demand modeling triangulated against top-down manufacturer revenue aggregation across the analysis window.
Segment-weighting approaches distributed value and volume estimates across product architecture tiers, application categories, installation types, and control mechanism sophistication levels. CAGRs were derived from fitted growth curves calibrated to historical fixture replacement cycles and projected controlled-environment agriculture capital deployment. Forecast inputs incorporated aluminum commodity price volatility bands, LED driver lead time assumptions, and state-level cannabis licensing trajectory scenarios without year-specific anchoring.
Inputs from manufacturer shipment disclosures, utility program administrators, and state regulatory filings were available through the study window; gaps in private-label import volume data introduce uncertainty bands around economy-tier market share estimates. Forecasts reflect documented assumptions regarding federal agricultural energy incentive continuity and state cannabis policy evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Vertical Farming Produce Market