
 Plant Phenotyping Market | 2026-2036
Plant Phenotyping Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Phenotyping Market Intelligence
The basis of competition in plant phenotyping is shifting from standardized, high-throughput screening platforms toward custom-engineered systems integrating proprietary imaging and sensor technologies. Large-scale providers like LemnaTec GmbH specialize in automated, controlled-environment solutions for research institutes. In contrast, Phenospex differentiates with field-deployable sensor systems for real-world data collection. Integrated players such as BASF SE leverage extensive in-house phenotyping capabilities to support their own crop science research and development pipelines.
Plant phenotyping is the quantitative assessment of a plant's structural and functional traits, which result from genetic and environmental interactions. The process utilizes technologies like 3D LiDAR to map canopy architecture or hyperspectral imaging to analyze biochemical composition. Its primary purpose is to accelerate plant breeding and crop improvement by connecting a plant's genetic code to its observable performance characteristics. Imaging technologies, including thermal and multispectral sensors, command the largest share, especially for high-throughput screening deployments. Within applications, stress tolerance analysis and yield prediction represent the fastest-growing areas for seed producers.
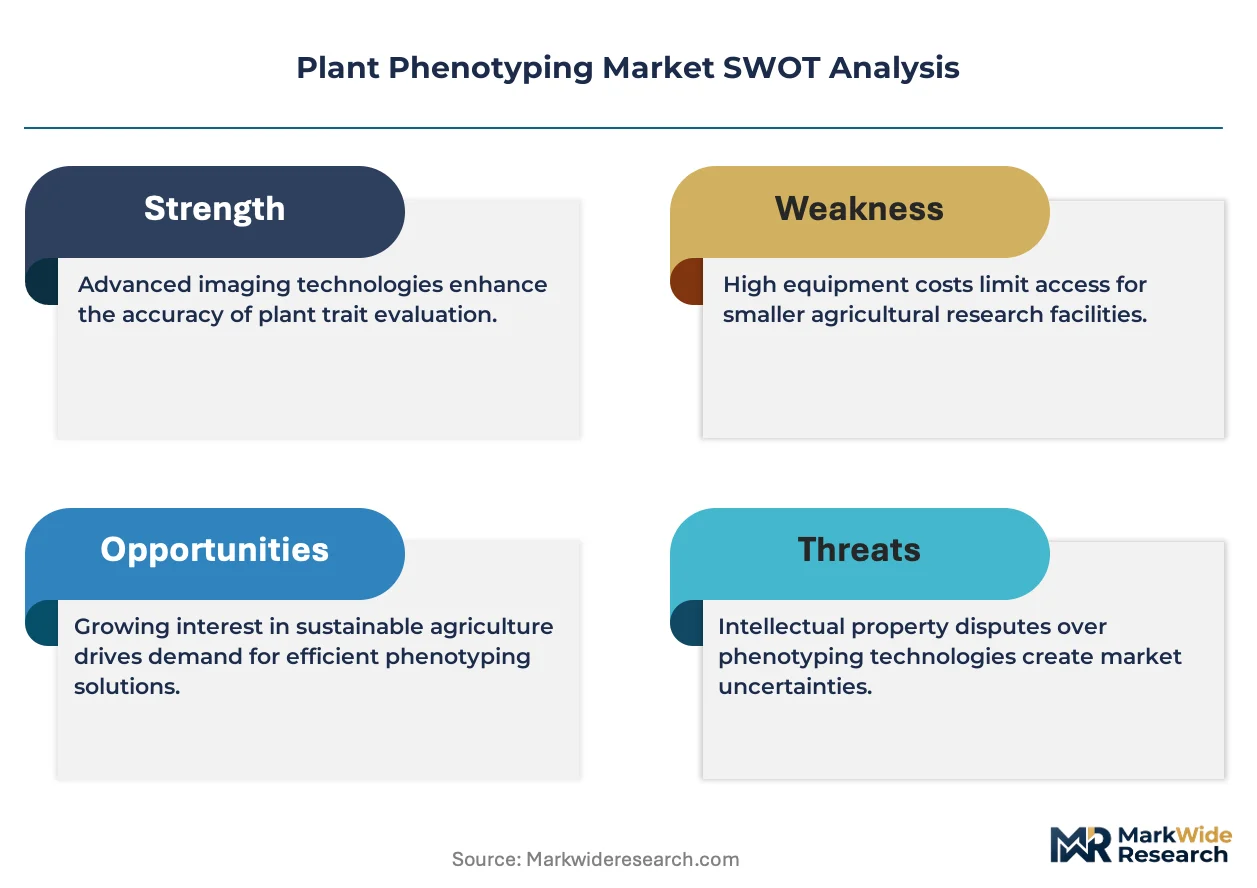
Regulatory frameworks influencing the market include intellectual property protections for plant varieties under the UPOV Convention and data governance rules like the EU's GDPR for cloud-based analytics platforms. Government funding from agencies such as the USDA in the United States and national research programs in China directly supports technology development and adoption in public institutions. The critical decision for stakeholders now centers on balancing investment in capital-intensive, centralized screening facilities against the adoption of more distributed, field-based sensor networks.
Market Dynamics
The convergence of artificial intelligence, advanced sensor technologies, and big data analytics is the central force redefining the plant phenotyping market. This shift moves the competitive basis from hardware throughput to the predictive power of integrated, data-driven analytical systems.
Growth Catalysts
- Intellectual Property Frameworks:The UPOV Convention provides robust legal protection for new plant varieties, creating a direct financial incentive for agricultural firms to invest in advanced phenotyping to accelerate breeding cycles and secure patents.
- Advanced Imaging Technologies:The deployment of hyperspectral and thermal imaging allows for non-destructive, high-throughput analysis of plant stress responses, a critical need for seed producers developing climate-resilient crop varieties.
- Biotechnology R&D Investment:Agricultural biotechnology companies are expanding their use of phenotyping to shorten the timeline for trait discovery and validation, linking genomic data directly to observable plant performance under specific environmental conditions.
Market Restraints
- High Capital Investment:The substantial upfront cost required to establish automated, controlled-environment phenotyping platforms creates a significant barrier to entry for smaller research institutions and companies.
- Data Interoperability Standards:A lack of universal standards for data formats and communication protocols between different sensor systems and software platforms hinders the integration and comparative analysis of datasets.
- Data Governance Complexity:Regulations like the EU's GDPR impose strict requirements on the management and transfer of data collected by cloud-based analytics platforms, adding compliance costs and operational friction.
Strategic Opportunities
- Predictive Analytics Integration:Integrating machine learning algorithms with 3D LiDAR data offers an opportunity to create highly accurate, predictive models of plant growth and canopy architecture for optimizing resource use.
- Field-Based Diagnostic Services:Developing mobile, sensor-based systems for real-time nutrient deficiency and disease detection in the field opens a new service-based market targeting precision agriculture applications.
- Geographic Expansion:Major agricultural economies such as Brazil and Australia represent underpenetrated markets for high-throughput phenotyping technologies, supported by their large-scale crop research and production sectors.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage exists for professionals possessing the interdisciplinary skills in plant science, data analytics, and sensor engineering needed to operate and interpret results from advanced phenotyping systems.
- Legacy System Integration:Researchers face significant operational hurdles when attempting to integrate modern, high-volume phenotyping data streams with pre-existing laboratory information management systems and databases.
- Methodological Standardization:The absence of standardized measurement protocols across different platforms and environments makes it difficult to validate and compare phenotyping data generated by different research groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Phenotyping Market |
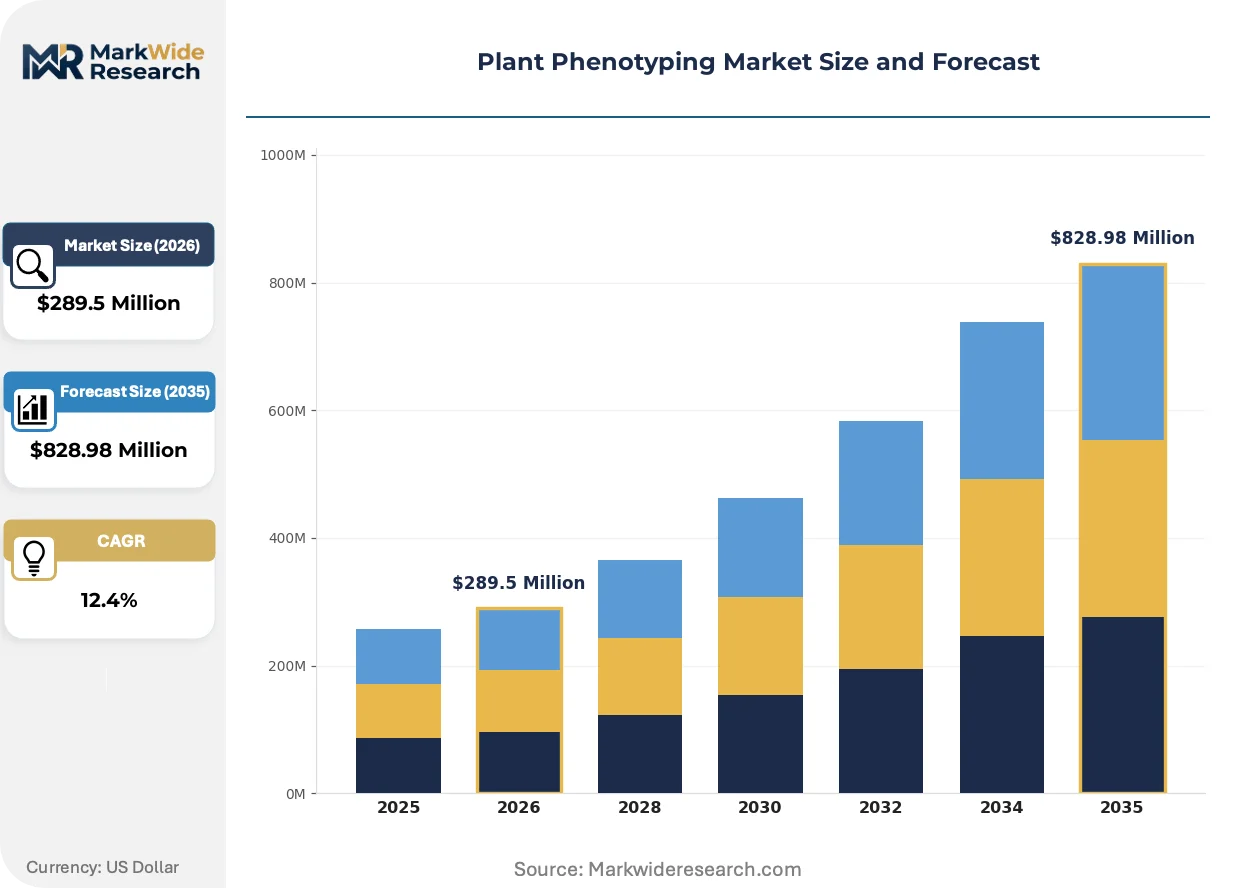
| Market Size in 2026 | $289.5 Million |
| Market Size in 2035 | $828.98 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
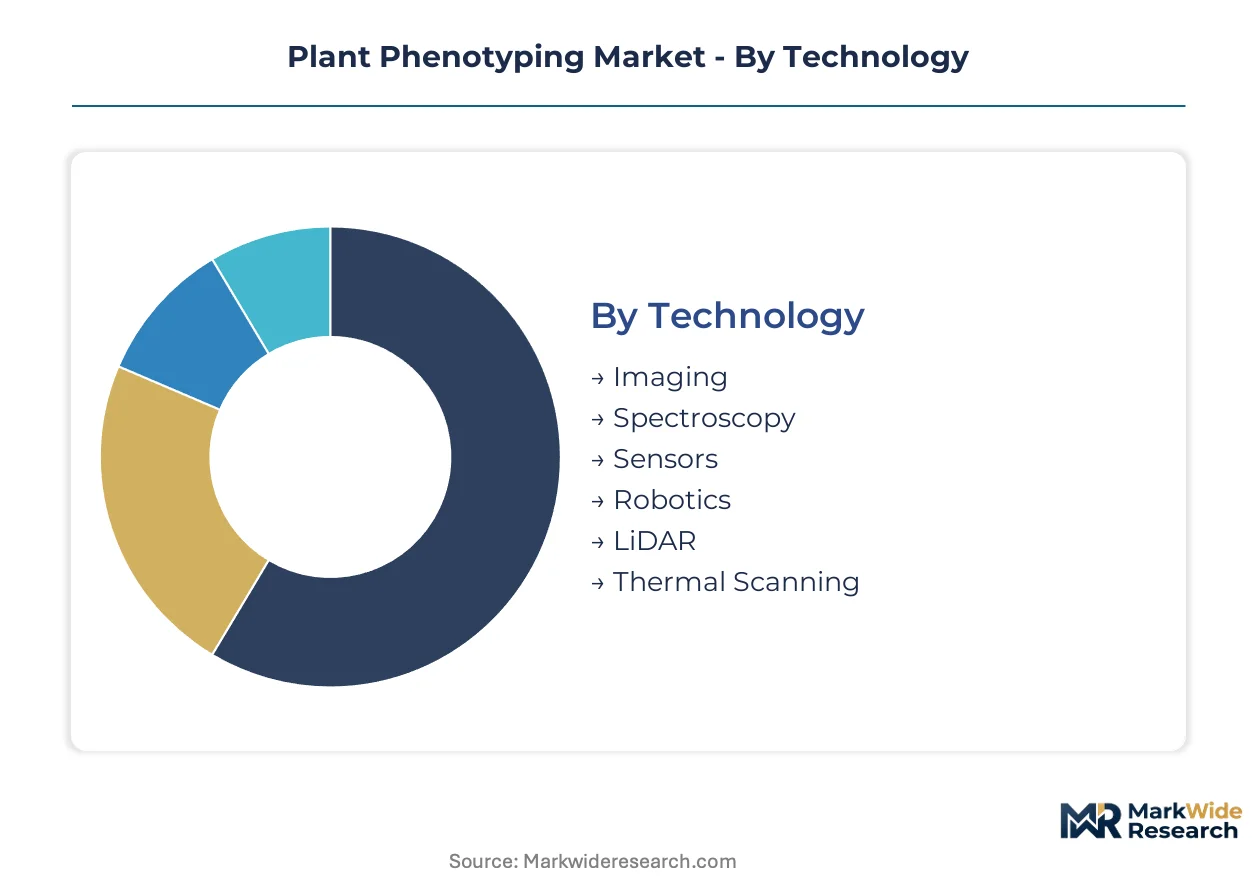
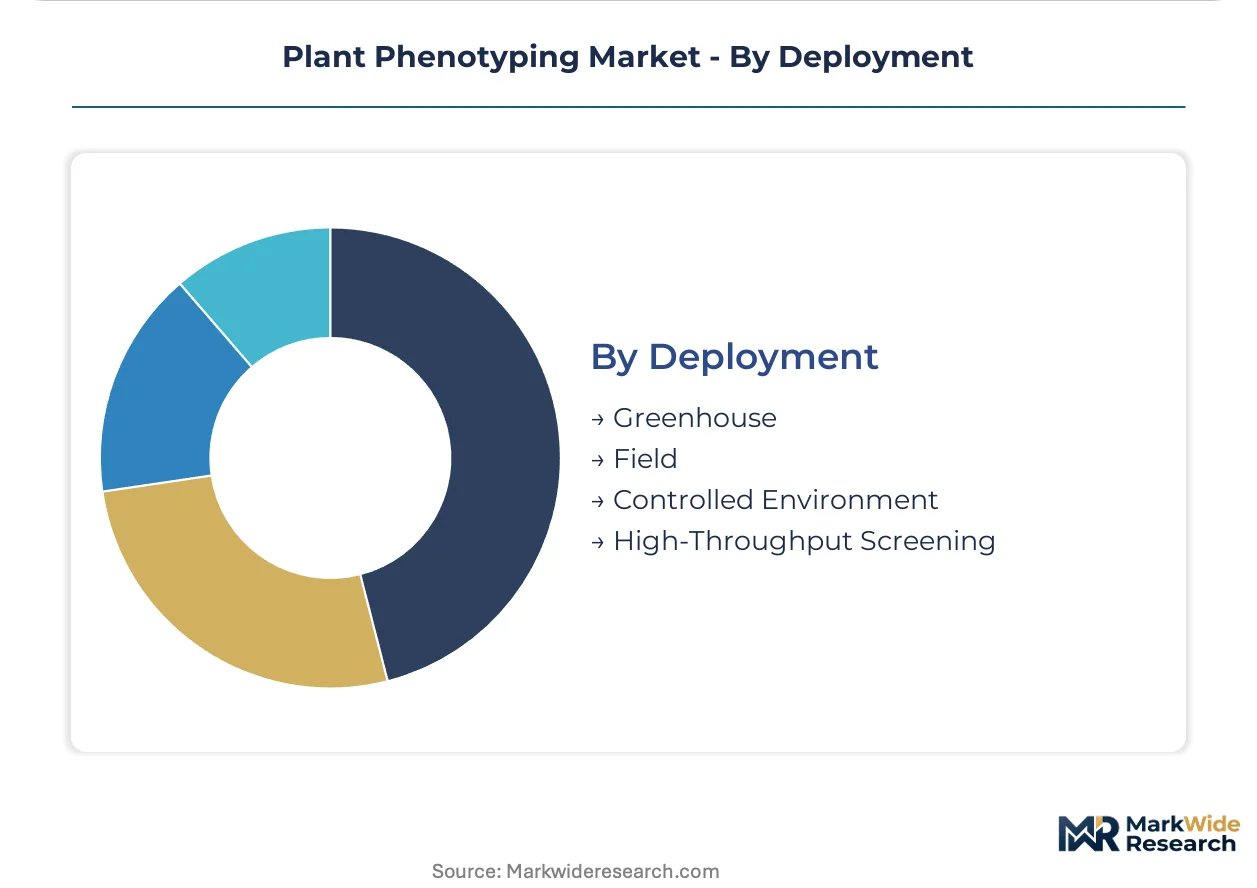
| Segmentation | Technology: Imaging, Spectroscopy, Sensors, Robotics, LiDAR, Thermal Scanning Application: Crop Improvement, Stress Tolerance Analysis, Yield Prediction, Disease Detection, Phenomic Trait Analysis End User: Research Institutes, Seed Producers, Agricultural Biotechnology Firms, Crop Consulting Agencies Deployment: Greenhouse, Field, Controlled Environment, High-Throughput Screening |
| Companies Covered | Heinz Walz GmbH, Delta-T Devices, LemnaTec GmbH, Qubit Systems, Photon Systems Instruments, BASF SE, Keygene, WIWAM, Phenospex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Phenotyping Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental transition from static, lab-centric measurements toward dynamic, field-deployable sensor networks that generate continuous data streams. This enables a more holistic and predictive understanding of plant performance in real-world agricultural environments.
Edge computing integrated with field sensors provides on-site processing of complex imaging and environmental data. Agricultural research consortia and large seed companies are adopting this technology to overcome data transmission latency from remote trial locations. This on-site analytical capability is consolidating the value of sensor networks by turning them from simple data loggers into instruments for immediate, actionable insight.
National research funding mandates, particularly from agencies like the USDA in the United States, increasingly require open access for data from publicly supported projects. This policy is pressuring institutions to adopt platforms that support FAIR data principles. University research programs are therefore prioritizing investments in systems with standardized data outputs and metadata to facilitate collaboration and data sharing across the scientific community.
A significant behavioral change is the move from capital-intensive hardware acquisitions toward subscription-based Phenotyping-as-a-Service (PaaS) models. This model disrupts traditional equipment sales by offering access to data acquisition and analytics without the burden of infrastructure ownership. The trend is most visible among small and mid-sized biotechnology firms that need access to advanced screening capabilities but lack large capital budgets.
Plant Phenotyping Market Segmentation
Plant phenotyping market segmentation provides a granular view of the diverse technologies, applications, and end-user requirements driving innovation. Understanding these distinct segments helps stakeholders identify specific growth pockets and tailor solutions for optimized crop development.
Technology:
The technology segment delineates the balance between high-volume, standardized data capture and specialized, premium solutions for advanced analyses.
- Imaging:This technology captures visual data, including thermal and multispectral sensors, providing non-destructive analysis of plant traits. Imaging technologies command the largest share, especially for high-throughput screening deployments in research institutes.
- Sensors:These devices measure various environmental and plant physiological parameters, supporting real-time data collection in diverse settings. Phenospex differentiates with field-deployable sensor systems for real-world data collection, meeting growing demand for distributed networks.
- Spectroscopy:This method analyzes light interaction with plant tissues to determine biochemical composition and physiological states. Agricultural biotechnology firms use spectroscopy for detailed analysis of stress markers and nutrient content.
- Robotics:Automated robotic platforms integrate various sensors and imaging systems for high-throughput, repetitive phenotyping tasks. Research institutions deploy robotics to reduce manual labor and increase data collection efficiency in controlled environments.
- LiDAR:3D LiDAR technology precisely maps plant canopy architecture and biomass, offering structural insights into plant growth. Machine learning algorithms integrate with LiDAR data to create predictive models of plant development.
- Thermal Scanning:This technique measures plant surface temperature to detect water stress and disease symptoms early. Seed producers utilize thermal scanning to screen for drought-tolerant crop varieties.
Today's leader: Imaging. Tomorrow's challenger: Sensors.
Application:
Application segmentation highlights the diverse functional objectives driving plant phenotyping adoption across the agricultural value chain.
- Stress Tolerance Analysis:This application identifies plant resilience to environmental stressors like drought, salinity, and heat. Stress tolerance analysis represents a rapidly expanding area for seed producers developing climate-resilient crop varieties.
- Yield Prediction:Phenotyping data informs models that forecast crop productivity under various conditions, optimizing resource allocation. Yield prediction represents a rapidly expanding area for seed producers, seeking to improve agricultural output.
- Crop Improvement:This broad application encompasses accelerating plant breeding cycles and enhancing desirable genetic traits. Agricultural biotechnology firms leverage phenotyping to shorten the timeline for trait discovery and validation.
- Disease Detection:Phenotyping systems identify early signs of plant diseases, enabling timely intervention and reduced crop losses. Field-based diagnostic services utilizing mobile sensor systems offer real-time disease detection capabilities.
- Phenomic Trait Analysis:This involves comprehensive characterization of a plant's observable traits, linking genetic code to performance. Research institutes use phenomic trait analysis to understand complex gene-environment interactions.
The segment expanding most quickly is Stress Tolerance Analysis, driven by the urgent need for climate-resilient crops.
End User:
End user classification reveals distinct procurement behaviors and research priorities among key stakeholders in the plant science ecosystem.
- Seed Producers:These companies utilize phenotyping to develop new crop varieties with enhanced traits, securing intellectual property rights. Seed producers invest in advanced phenotyping to accelerate breeding cycles and validate genetic performance.
- Agricultural Biotechnology Firms:These organizations integrate phenotyping into their R&D pipelines for trait discovery, gene editing, and product development. BASF SE leverages extensive in-house phenotyping capabilities to support its crop science research.
- Research Institutes:Academic and government research bodies employ phenotyping for fundamental plant science studies and collaborative projects. Public institutions receive government funding from agencies like the USDA to support technology development.
- Crop Consulting Agencies:These firms offer specialized advice to growers, increasingly incorporating phenotyping data for precision agriculture recommendations. Crop consulting agencies represent an emerging market for field-based diagnostic services.
Demand from Seed Producers is increasing, while Crop Consulting Agencies represent a developing market.
Deployment:
Deployment segmentation differentiates plant phenotyping based on the operational environment, ranging from highly controlled indoor facilities to dynamic field conditions.
- Field:This deployment involves sensor networks and mobile systems for data collection directly in agricultural fields. Field deployments enable a more holistic understanding of plant performance in real-world agricultural environments.
- High-Throughput Screening:These automated platforms rapidly assess large populations of plants in controlled settings. High-throughput screening systems are central to accelerating plant breeding and crop improvement programs.
- Greenhouse:Phenotyping systems in greenhouses allow for controlled environmental studies and early-stage plant development assessments. LemnaTec GmbH specializes in automated, controlled-environment solutions for greenhouse research.
- Controlled Environment:This category includes growth chambers and phytotrons, offering precise control over environmental variables for specific experiments. Researchers use controlled environments to isolate specific genetic and environmental interactions.
The shift towards Field deployments is redefining data collection strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly specialized talent concentrations in agricultural science and data analytics drive regional demand for plant phenotyping. These clusters foster innovation and facilitate the adoption of advanced systems. They also attract significant public and private investment into crop improvement technologies.
United States
Demand for plant phenotyping in the United States stems from the need to develop climate-resilient crops and improve yield prediction. The USDA provides significant funding, directly supporting technology development and adoption in public institutions. Research clusters in California and the Midwest actively integrate AI with imaging analytics for advanced crop science.
Germany
Germany's plant phenotyping market is propelled by strong agricultural biotechnology firms and academic research, focusing on high-throughput screening and stress tolerance analysis. National research programs in Germany fund technology development, promoting innovation in controlled-environment solutions. Specialized agricultural research clusters around Bonn and Jülich drive advanced phenotyping system deployment.
Netherlands
The Netherlands exhibits robust demand for advanced phenotyping, driven by its intensive agricultural research and greenhouse horticulture sectors. European Union regulations, such as GDPR, influence data governance for cloud-based analytics platforms used in Dutch research. Wageningen University & Research acts as a central hub, fostering collaboration in plant science and sensor technology.
Brazil
Brazil represents an underpenetrated market for high-throughput phenotyping, with demand stemming from its large-scale crop production and research sectors. The country's agricultural policies increasingly support innovation in sustainable agriculture and crop improvement. Agricultural research centers in states like São Paulo and Paraná are expanding their phenotyping capabilities.
Australia
Australia's market for plant phenotyping is driven by the necessity to develop drought-tolerant crop varieties and optimize yield in challenging environments. Government funding supports research into climate-resilient agriculture, encouraging technology adoption. Research institutions in Adelaide and Canberra are key to integrating advanced sensor networks for field-based data collection.
Plant Phenotyping Market Key Industry Players
Top-tier vendors anchor the integrated solutions segment, while specialized providers target niche applications with advanced sensor technologies. The market structure exhibits a blend of consolidation among established players and fragmentation among innovative startups offering specialized analytics. Strategic archetypes include high-throughput screening specialists, field-deployable sensor system developers, and integrated crop science firms. Dominant competitive moves involve strategic partnerships for technology integration and portfolio diversification to cover a broader range of phenotyping applications, alongside targeted geographic expansion.
On the premium-tier vector, LemnaTec GmbH exemplifies providers specializing in automated, controlled-environment solutions for research institutes, offering sophisticated high-throughput screening platforms. In contrast, Phenospex represents companies focused on field-deployable sensor systems for real-world data collection, catering to the market's shift towards distributed networks and precision agriculture. BASF SE, an integrated player, leverages extensive in-house phenotyping capabilities to support its own crop science research and development pipelines, highlighting the importance of captive supply for large agricultural biotechnology firms seeking to accelerate trait discovery and validation.
| Leading Market Players |
|---|
| Heinz Walz GmbH |
| Delta-T Devices |
| LemnaTec GmbH |
| Qubit Systems |
| Photon Systems Instruments |
| BASF SE |
| Keygene |
| WIWAM |
| Phenospex |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private equity-backed specialists drive innovation in plant phenotyping, influencing both system supply and service pricing through their specialized technology offerings and operational efficiencies.
Pricing Analysis
Bundled hardware and software solutions command premium pricing, while subscription-based Phenotyping-as-a-Service (PaaS) models offer more flexible access. Pricing stratifies across premium, standard, and economy tiers based on customization level and the depth of integrated data analytics. Pricing softness reflects the increasing availability of standardized field-deployable sensor systems. Smaller biotechnology firms and academic researchers exhibit higher price sensitivity compared to large seed producers and integrated agricultural biotechnology firms.
Supply Chain Analysis
Reverse logistics for sensor calibration and equipment refurbishment are becoming critical for maintaining system accuracy and extending asset life. The supply chain for advanced phenotyping components concentrates in Germany, the Netherlands, and the United States. It relies on specialized imaging sensors, high-performance computing components, and AI-enabled software modules. Single-source vulnerability for proprietary sensor technology poses a structural risk to system manufacturers. Distribution channels primarily involve direct sales from manufacturers to research institutions and agricultural enterprises, alongside specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant phenotyping market presents a geographic-arbitrage opportunity, given the varied regulatory landscapes for data governance and the regional disparities in specialized talent availability.
For Market Incumbents: Deploy strategic partnerships with AI analytics firms to integrate predictive modeling into existing high-throughput platforms. Expand offerings for field-deployable sensor networks to counter the threat from specialized startups. Invest in data interoperability standards development to secure a dominant position in the evolving data ecosystem. Focus on developing climate-resilient crop varieties through advanced stress tolerance analysis.
For New Entrants and Emerging Players: Small and mid-sized biotechnology firms represent an underserved buyer archetype for accessible phenotyping solutions. Target field-based diagnostic services for real-time nutrient deficiency detection in precision agriculture. Offer subscription-based Phenotyping-as-a-Service (PaaS) models to lower capital investment barriers for these segments. Develop niche solutions for specific crop types or environmental stressors to gain market entry.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized sensor developers and data analytics platforms with proprietary algorithms. Consider long-term viability tied to the increasing demand for climate-resilient crops and precision agriculture. Acquire firms offering integrated AI and LiDAR capabilities for predictive plant growth modeling. A key signal to watch is the increasing adoption of open-access data platforms by public research institutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI with Imaging Analytics | Enhances predictive power for crop performance, accelerating breeding cycles for seed producers. |
| Expand Field-Deployable Sensor Solutions | Captures real-world plant performance data, critical for climate-resilient crop development. |
| Develop Phenotyping-as-a-Service (PaaS) Models | Lowers entry barriers for smaller firms, democratizing access to advanced screening capabilities. |
| Invest in Data Interoperability Standards | Facilitates data sharing and comparative analysis across diverse research groups and platforms. |
| Target Underpenetrated Agricultural Economies | Unlocks new revenue streams by addressing the demand for high-throughput phenotyping in Brazil. |
Research Approach
Bottom-up seed producers and research institutes modeling reconciled against top-down sensor manufacturers and software developers tracking forms the analytical core of this study. This approach combines primary interviews with industry stakeholders and secondary validation from diverse sources.
The forecast framework utilizes an input-output matrix to project market dynamics across the analysis window. This model segments the market by technology, application, end-user, deployment, and geographic region. Compound Annual Growth Rates were derived from historical trends and projected adoption rates of advanced phenotyping technologies. Key forecast inputs include agricultural biotechnology R&D investment and global climate change adaptation strategies.
Underlying measurement precision varies by segment; high-throughput screening and controlled environment deployments carry tighter precision than others. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Data interoperability challenges and the scarcity of specialized talent represent risk factors that could revise projections. Practitioners should monitor government funding changes and major agricultural biotechnology investments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Farming As a Service Market