
 Smart Egg Incubators Market | 2026-2036
Smart Egg Incubators Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Egg Incubators Market Insights
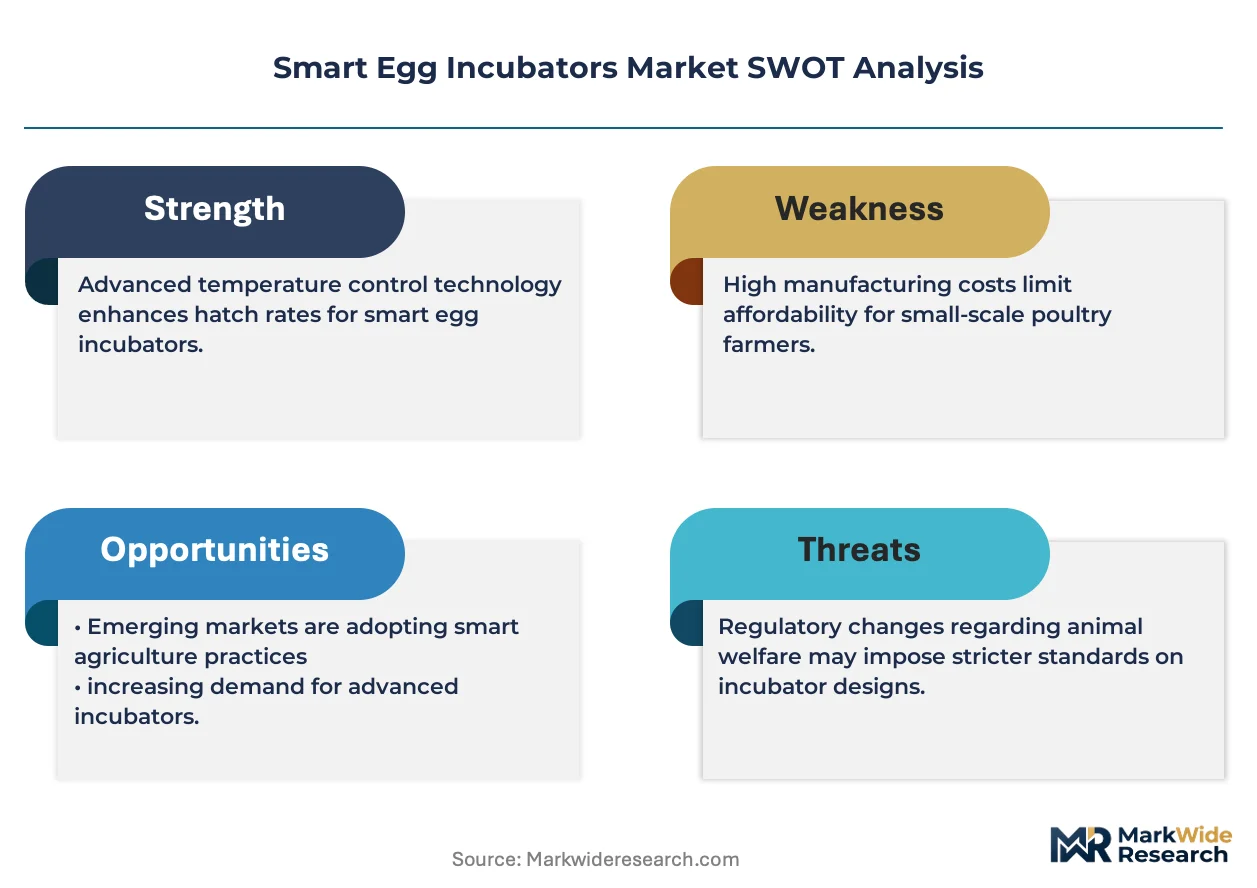
The gap between premium precision systems and basic commodity units is realigning purchasing patterns across the poultry value chain. Petersime NV leverages captive sensor calibration networks to sustain premium positioning in European hatchery upgrades. HatchTech anchors its competitive stance through proprietary laminar airflow engineering that dominates large-scale commercial deployments. Pas Reform Hatchery Technologies differentiates via modular cabinet architectures that let mid-size operators scale capacity in phased increments.
Smart egg incubators are climate-controlled enclosures that regulate temperature, humidity, and ventilation within precise tolerances—typically maintaining 37.5°C and 50-65% relative humidity—to optimize embryonic development and hatch rates. Their primary commercial purpose is to maximize viable chick output while minimizing labor input and energy consumption in both industrial hatcheries and smaller poultry operations. Digital control systems command the fastest expansion trajectory as operators replace analog units with IoT-enabled platforms that enable remote monitoring and automated alarm response. Automatic incubators occupy the dominant volume position across commercial hatcheries, where labor scarcity and throughput requirements make manual intervention economically untenable. Solar-powered units represent an emerging niche with concentrated uptake in off-grid poultry clusters across sub-Saharan Africa and South Asia.
The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant choices and material specifications for climate modules sold into European markets, elevating engineering costs for non-compliant suppliers. In the United States, USDA biosecurity protocols and NHTSA-adjacent equipment safety standards shape product certification requirements for interstate hatchery equipment commerce. China's GB standards and SAMR equipment safety rules govern import access and domestic manufacturing compliance for both foreign and local incubator producers. Stakeholders must weigh regulatory compliance investments against the margin compression risk from low-cost digital entrants in price-sensitive geographies.
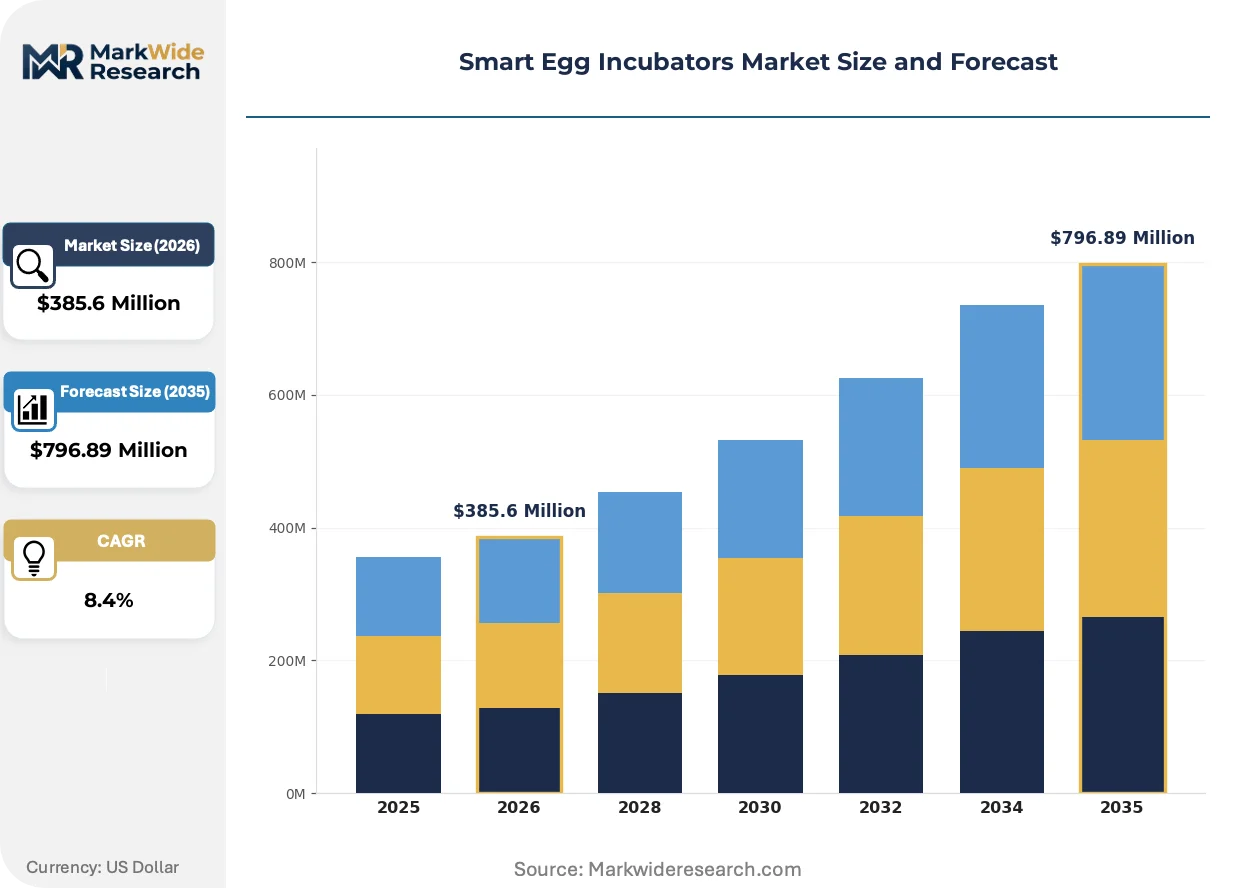
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant transitions across climate control modules while Brazilian commercial hatcheries scale automated capacity to meet export-grade poultry standards, compressing margins for analog equipment suppliers.
Growth Catalysts
- EU F-Gas Regulation:The mandate for low-global-warming-potential refrigerants is accelerating equipment replacement cycles across European hatchery infrastructure.
- Vertically integrated poultry groups in China:Modernization of legacy hatchery infrastructure is pulling demand toward IoT-enabled platforms with remote monitoring capabilities.
- Automated incubation systems:Labor scarcity in commercial hatcheries is rendering manual intervention economically untenable across high-throughput operations.
Market Restraints
- Refrigerant compliance costs:REACH and F-Gas frameworks elevate engineering costs for climate module suppliers serving European markets.
- Supply concentration in precision sensor manufacturing:Captive calibration networks limit vendor options for premium positioning strategies.
- Energy input volatility:Thermal regulation demands create exposure to electricity price fluctuations in grid-dependent installations.
Strategic Opportunities
- Off-grid poultry clusters in sub-Saharan Africa:Solar-powered incubation units address energy access gaps in rural production zones.
- GB standards alignment:SAMR equipment safety compliance creates import access pathways for foreign manufacturers targeting Chinese modernization programs.
- Modular cabinet architectures:Phased capacity scaling enables mid-size operators to expand without full system replacement.
Industry Challenges
- Biosecurity protocol integration:USDA standards for interstate commerce require recalibration of alarm response systems and data logging protocols.
- Sensor calibration expertise:Precision tolerance maintenance demands specialized technical labor scarce in emerging hatchery markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Egg Incubators Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Incubators, Manual Incubators, Digital Incubators, Batch Incubators Power Source: Electric, Solar, Battery-operated, Hybrid Control Method: Analog Control, Digital Control, Smart Control, Mechanical Control End User: Commercial Hatcheries, Poultry Farms, Research Institutions, Home Users |
| Companies Covered | Petersime NV, HatchTech, Pas Reform Hatchery Technologies, Jamesway Incubator Company, Brinsea Products Ltd., Rcom Incubators, GQF Manufacturing Company Inc., Surehatch Egg Incubators, Chore-Time (CTB, Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Egg Incubators Market Trends and Innovations
Digital control architectures are displacing analog systems while regulatory pressure on refrigerants and laminar airflow engineering reshape equipment specifications across commercial deployments.
Climate control modules with variable-speed compressors and predictive humidity algorithms are modularizing hatchery infrastructure design. Large-scale commercial operators in Brazil and China are adopting these platforms to enable phased facility expansion without full system overhaul. The technology is modularizing vendor relationships, allowing operators to mix sensor, airflow, and cabinet suppliers rather than accepting single-source bundles.
The EU F-Gas Regulation bans hydrofluorocarbon refrigerants with high global warming potential from new climate equipment sales. Hatchery equipment manufacturers serving European markets must redesign thermal systems around propane or CO2 alternatives. Premium segment suppliers are absorbing compliance costs while economy-tier competitors face exit pressure from certified procurement channels.
Service contract unbundling is separating equipment sales from maintenance and calibration obligations. Mid-size hatchery operators in Southeast Asia are purchasing incubators through distributor channels while sourcing sensor recalibration and spare parts through independent technical service networks. This pattern is most visible in Vietnam and Indonesia where poultry group consolidation has outpaced captive technical workforce development.
Smart Egg Incubators Market Segmentation
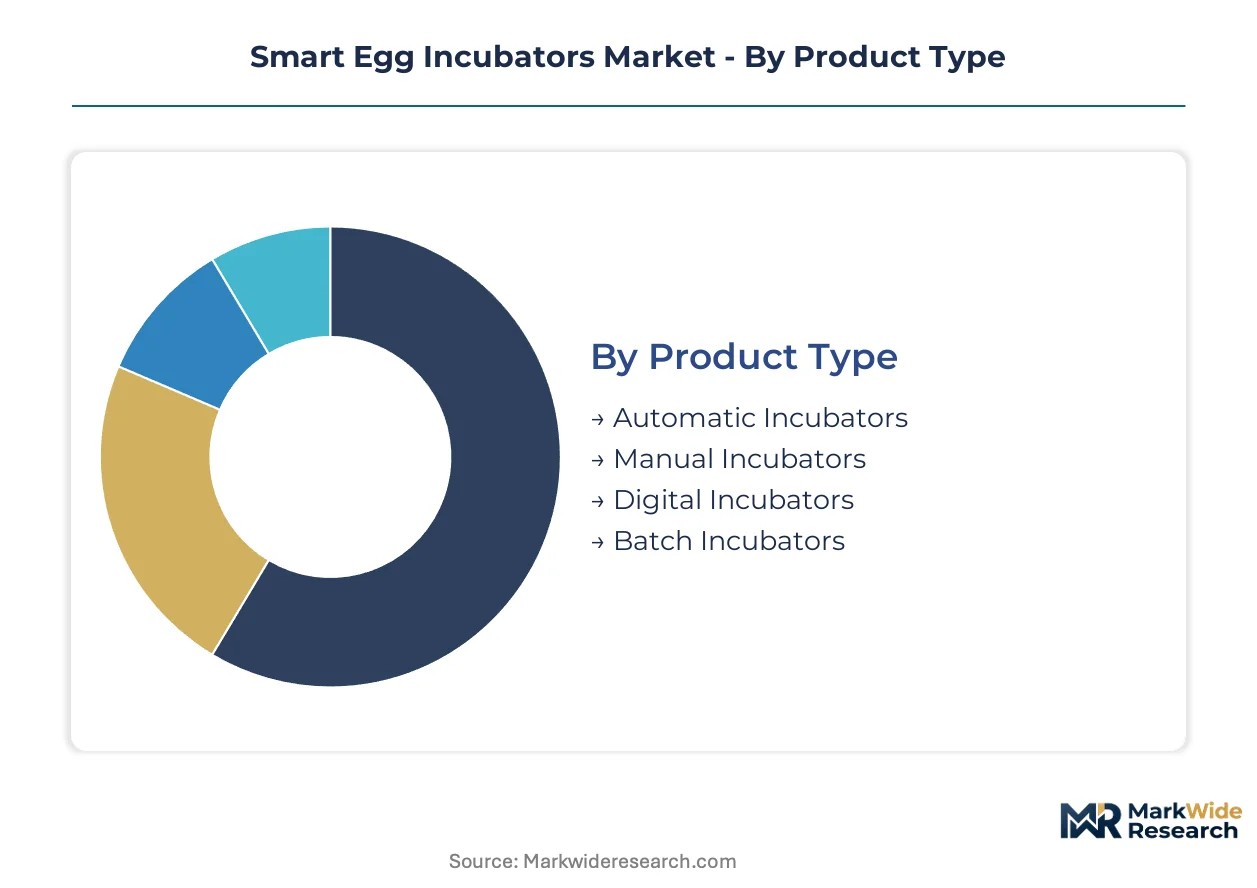
Segmentation in the Smart Egg Incubators Market reveals how automation depth and energy access shape procurement decisions across disparate operational scales. Understanding these divides exposes where technology premiums command pricing power versus where cost minimization dominates purchasing criteria.
Product Type:
Standalone cabinet systems serve discrete operational needs while integrated hatchery lines embed incubation within fully automated production workflows.
- Automatic Incubators:These units deploy motorized turning mechanisms and programmable climate cycles to eliminate manual egg rotation. Demand concentrates in Brazilian commercial hatcheries scaling for export-grade poultry standards, where labor scarcity makes manual intervention economically untenable.
- Digital Incubators:IoT-enabled platforms with remote monitoring capabilities and automated alarm response systems. Vertically integrated poultry groups in China are modernizing legacy infrastructure with these systems to enable centralized oversight across distributed hatchery networks.
- Manual Incubators:Hand-operated turning trays with basic thermostat regulation serve entry-level poultry operations and educational settings where capital constraints outweigh labor availability.
- Batch Incubators:Single-cycle cabinets designed for synchronized hatching schedules support seasonal poultry producers and specialty breed operations with non-continuous production needs.
Automatic Incubators lead volumes today; Digital Incubators are gaining share fastest.
Power Source:
Grid dependency versus energy autonomy creates divergent total-cost-of-ownership profiles across installation geographies.
- Electric:Grid-connected units with resistive heating and compressor-based cooling dominate commercial hatcheries in Brazil and China where infrastructure reliability supports continuous operation.
- Solar:Photovoltaic-powered systems with battery storage address energy access gaps in off-grid poultry clusters across sub-Saharan Africa and rural South Asia.
- Battery-operated:DC-powered portable units serve mobile veterinary services and emergency backup applications where grid independence is intermittent rather than permanent.
- Hybrid:Dual-mode systems switching between grid and solar input mitigate electricity price volatility in grid-dependent installations while maintaining operational continuity during outages.
Electric systems anchor commercial deployments; Solar configurations are expanding most quickly in frontier markets.
Control Method:
Interface sophistication separates precision agriculture adopters from price-sensitive operators maintaining legacy equipment.
- Digital Control:Microprocessor-based platforms with touchscreen interfaces and data logging capabilities satisfy USDA biosecurity protocols for interstate commerce through automated record-keeping.
- Smart Control:AI-driven predictive algorithms adjusting temperature and humidity based on embryo development stage. These systems absorb EU F-Gas Regulation compliance costs while economy-tier competitors face exit pressure from certified procurement channels.
- Analog Control:Dial-based thermostat and hygrometer systems persist in replacement markets for legacy cabinet maintenance and budget-constrained smallholder operations.
- Mechanical Control:Bimetallic strip thermostats and passive ventilation without electronic components serve extreme environments where humidity and dust compromise electronic reliability.
Digital Control holds the installed base; Smart Control is climbing the fastest as IoT platforms displace analog units.
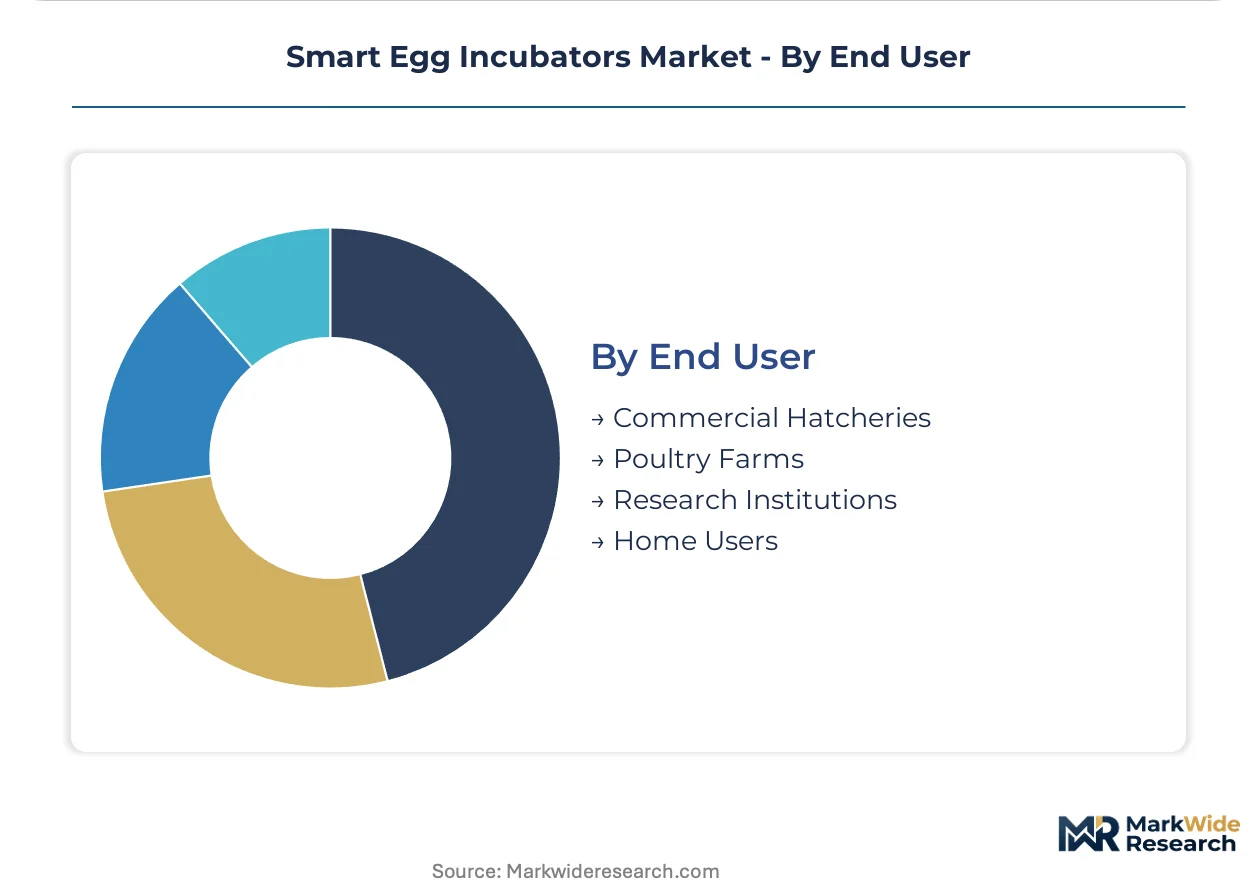
End User:
Throughput requirements and biosecurity mandates fragment demand across facility scales with incompatible procurement criteria.
- Commercial Hatcheries:High-throughput operations with laminar airflow engineering and modular cabinet architectures enabling phased capacity expansion. Brazilian operators scaling automated capacity drive specification intensity for export-grade compliance.
- Poultry Farms:Mid-size integrated operations requiring scalable platforms with remote monitoring to manage distributed breeder flocks without captive technical workforces.
- Research Institutions:Precision-tolerance systems with calibrated sensor networks and data integrity protocols supporting experimental reproducibility and regulatory documentation.
- Home Users:Small-capacity cabinets for hobby breeding and specialty poultry enthusiasts where purchase decisions prioritize footprint and noise levels over throughput metrics.
Commercial Hatcheries dominate revenue concentration; Poultry Farms are expanding most quickly as consolidation outpaces captive workforce development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hatchery technicians and poultry engineering talent concentrate in Brazil, Germany, China, and the United States, anchoring regional innovation clusters that shape equipment specification and procurement patterns across their respective markets.
Brazil
Commercial hatcheries in São Paulo and Paraná states are scaling automated capacity to meet export-grade poultry standards for EU and Middle East buyers. ANVISA biosecurity protocols and MAPA sanitary certification requirements govern equipment import and installation timelines. The Cascavel-São José do Rio Preto corridor hosts the densest concentration of modernized hatchery infrastructure, where operators are replacing analog climate systems with IoT-enabled platforms.
Germany
Precision engineering expertise in Bavaria and North Rhine-Westphalia sustains premium-tier incubator manufacturing for European hatchery upgrades. The EU F-Gas Regulation mandates low-global-warming-potential refrigerants in climate control modules, accelerating replacement cycles across legacy installations. The Münsterland region anchors laminar airflow engineering development, with technical universities supplying specialized workforce talent to equipment manufacturers.
China
Vertically integrated poultry groups in Shandong and Guangdong provinces are modernizing legacy hatchery infrastructure with centralized monitoring capabilities. SAMR equipment safety rules and GB standards compliance govern import access for foreign manufacturers while domestic producers scale output. The Yangtze River Delta cluster around Nantong and Yangzhou concentrates mid-size operator demand for modular cabinet architectures enabling phased capacity expansion.
United States
USDA-inspected commercial hatcheries in the Southeast and Midwest are deploying digital control systems to satisfy interstate commerce biosecurity protocols. The department's HPAI response frameworks and NPIP certification requirements shape alarm response and data logging specifications. Georgia's poultry belt and Arkansas River Valley host the most intensive hatchery automation deployments, with operators prioritizing remote monitoring to manage distributed breeder flocks.
Smart Egg Incubators Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure where captive sensor calibration networks and proprietary airflow engineering separate premium positioning from commodity competition. The vendor base clusters around three strategic archetypes: integrated hatchery solution providers with full-system capabilities, specialized climate control module fabricators, and regional assemblers serving price-sensitive geographies. Consolidation pressure concentrates among mid-tier analog suppliers facing margin compression from digital entrants and regulatory compliance costs. Dominant competitive moves include technology licensing partnerships for IoT platform integration and geographic expansion through distributor channel development in Southeast Asia and sub-Saharan Africa.
Within the integrated solution provider tier, Petersime NV and HatchTech exemplify divergent technical anchoring strategies, while Pas Reform Hatchery Technologies occupies a modular architecture position enabling phased customer scaling. Jamesway Incubator Company and Brinsea Products Ltd. represent North American and European specialist heritage respectively, with GQF Manufacturing Company Inc. sitting within the mid-market equipment fabricator archetype. These named entities illustrate how competitive positioning fragments across precision engineering credentials, regional manufacturing footprint, and service network density rather than converging on uniform product specifications.
| Leading Market Players |
|---|
| Petersime NV |
| HatchTech |
| Pas Reform Hatchery Technologies |
| Jamesway Incubator Company |
| Brinsea Products Ltd. |
| Rcom Incubators |
| GQF Manufacturing Company Inc. |
| Surehatch Egg Incubators |
| Chore-Time (CTB, Inc.) |
| Others |
Pricing and Supply Chain Analysis
Premium-captive calibration networks versus commodity sensor sourcing bifurcates procurement economics across European hatchery upgrades and price-sensitive emerging markets, with EU F-Gas compliance costs embedding into premium tier quotations while Brazilian distributors absorb margin compression through unbundled service models.
Pricing Analysis
Equipment-plus-service bundling versus unbundled component sales splits procurement patterns across customer tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and sensor calibration precision, with EU REACH and F-Gas compliance elevating engineering costs for climate module suppliers. Pricing pressure stems from low-cost digital entrants penetrating Southeast Asian distributor channels. Smallholder operations in rural South Asia exhibit highest price sensitivity, while research institutions with reproducibility mandates show lowest.
Supply Chain Analysis
Freight cost differentials between European precision component hubs and Asian assembly centers shape landed cost structures for modular cabinet architectures. Manufacturing concentrates in Germany, China, and the Netherlands, with sensor calibration expertise anchored in Bavaria and North Rhine-Westphalia. Supply chains draw from precision thermistor suppliers, variable-speed compressor fabricators, and laminar airflow engineering specialists. Single-source vulnerability concentrates in captive calibration networks. Distribution runs through distributor channels in Southeast Asia and direct sales for large-scale commercial hatcheries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas compliance costs in European manufacturing create margin headroom for certified-plant capacity additions in China serving domestic modernization programs.
For Market Incumbents: Deploy proprietary laminar airflow engineering licensing to defend against modular cabinet competitors. Absorb EU refrigerant transition costs through premium-tier pricing while accelerating sensor calibration network density in Brazil to block digital entrant channel access. Capacity consolidation in Southeast Asian distributor relationships counters unbundled service competition from independent technical networks. For New Entrants and Emerging Players: Enter via solar-powered incubation units targeting off-grid poultry clusters in sub-Saharan Africa where energy access gaps exceed technical workforce scarcity. White-space concentrates in battery-integrated hybrid systems for grid-intermittent zones. Phased capacity scaling architectures for mid-size Vietnamese and Indonesian operators offer lowest competitive density. Go-to-market through independent technical service networks bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with modular cabinet specialists enabling phased customer scaling without full system replacement commitment. Long-term viability favors platforms with IoT-enabled remote monitoring capabilities as labor scarcity intensifies across commercial hatchery operations. Acquisition targets should demonstrate SAMR compliance pathways for Chinese market access. Signal to watch: distributor channel consolidation velocity in Southeast Asia indicating incumbent defensive positioning intensity.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Enables centralized oversight across distributed hatchery networks for vertically integrated poultry groups. |
| EU F-Gas Compliance Certification | Unlocks procurement access for European hatchery infrastructure replacement cycles. |
| Solar-Battery Hybrid Development | Addresses energy access gaps in off-grid poultry clusters across sub-Saharan Africa. |
| Modular Cabinet Architecture Licensing | Allows mid-size operators to scale capacity without full system replacement. |
| Southeast Asian Distributor Expansion | Captures service contract unbundling demand in Vietnam and Indonesia consolidation zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hatchery operations directors, climate control module procurement leads, sensor calibration technicians, and distributor channel managers with secondary validation through customs trade data, SEC equipment manufacturer filings, ANVISA certification registries, and SAMR equipment safety documentation. Bottom-up installation tracking and top-down revenue triangulation anchored market sizing across the analysis window.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns in European and Brazilian hatchery infrastructure. Segmentation modeling spanned automation depth, power source configuration, control interface sophistication, and end-user facility scale. CAGRs derived from equipment shipment trajectories and average selling price evolution across certified versus non-certified procurement channels. Forecast inputs incorporated EU F-Gas regulatory phase-out schedules and Chinese poultry group consolidation velocity.
The model holds under stable refrigerant compliance timelines and continued labor scarcity in commercial hatcheries; deviation in energy price volatility or biosecurity protocol stringency would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Global Drip Emitters Market