
 Quantum Board Grow Light Market | 2026-2036
Quantum Board Grow Light Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Board Grow Light Market Insights
EU Ecodesign regulations is rebalancing the cost-of-entry calculus for quantum board manufacturers serving European commercial growers. Horticulture Lighting Group leverages its Samsung LM301H diode partnerships to sustain component cost advantages across mid-wattage fixtures. Mars Hydro competes aggressively on direct-to-consumer pricing, while Gavita International anchors professional channel relationships through dedicated horticultural distribution networks.
A quantum board grow light is a flat-panel solid-state luminaire comprising surface-mounted LED arrays on aluminum substrate boards, typically delivering photosynthetic photon flux density above 2.7 micromoles per joule for controlled-environment agriculture. The technology dimension shows LED configurations commanding the installed base while OLED research prototypes target spectral tunability for research institutions. Full spectrum product types dominate commercial grower procurement, though UV LED variants attract premium pricing from cultivators pursuing secondary metabolite enhancement in high-value crops.
EPA Energy Star certification and FCC electromagnetic compliance shape product qualification timelines for US market entry, while CE marking and EU F-Gas Regulation phase-outs accelerate LED substitution in European greenhouse retrofits. The USDA National Organic Program creates preferential procurement pathways for fixtures meeting specific spectral efficiency thresholds in certified operations. Stakeholders must monitor evolving DLC qualified products list requirements, as utility rebate eligibility increasingly filters competitive viability in North American commercial segments.
Market Dynamics
Samsung's diode supply concentration is restructuring component economics for quantum board manufacturers, forcing fixture makers to secure multi-source LED partnerships or accept captive pricing terms from dominant semiconductor suppliers.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Dutch commercial indoor farms face binding retrofit deadlines that accelerate HPS-to-LED substitution, creating guaranteed demand visibility through 2030.
- Spectral tunability R&D:Research institutions in Japan and Germany are piloting OLED quantum board prototypes for precision photobiology applications requiring real-time wavelength adjustment.
- Cannabis facility modernization:Licensed North American cultivators are replacing legacy high-pressure sodium installations with solid-state horticultural lighting to reduce HVAC loads and electricity tariffs.
Market Restraints
- Aluminum substrate cost volatility:Metal commodity price swings directly compress gross margins for board fabricators without long-term smelter contracts.
- Single-source diode dependency:Korean and Taiwanese LED foundries control premium horticultural chip supply, exposing fixture assemblers to allocation risk during semiconductor cycle peaks.
- Legacy HPS infrastructure lock-in:Existing greenhouse ballast and reflector investments create switching cost barriers for mid-scale European vegetable growers.
Strategic Opportunities
- USDA National Organic Program spectral thresholds:Certified organic operations gain procurement preference for fixtures meeting defined photosynthetic efficiency benchmarks, creating a compliance-driven premium tier.
- UV LED secondary metabolite enhancement:Specialty crop cultivators in California and Oregon are experimenting with supplemental ultraviolet arrays to increase terpene and cannabinoid concentrations in high-margin strains.
- Direct-to-installer channel expansion:E-commerce platforms are disintermediating traditional horticultural distributors for sub-1000W residential and small-commercial segments.
Industry Challenges
- DLC qualified products list compliance:Utility rebate eligibility in North American commercial segments requires extensive third-party testing timelines that delay revenue recognition for new fixture introductions.
- Electromagnetic compatibility certification:FCC Part 15 and CE marking electromagnetic interference testing adds six-to-nine month qualification delays for multi-array board designs.
- Legacy climate control integration:Solid-state lighting's reduced heat output disrupts existing greenhouse heating and ventilation control algorithms, requiring building management system reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Board Grow Light Market |
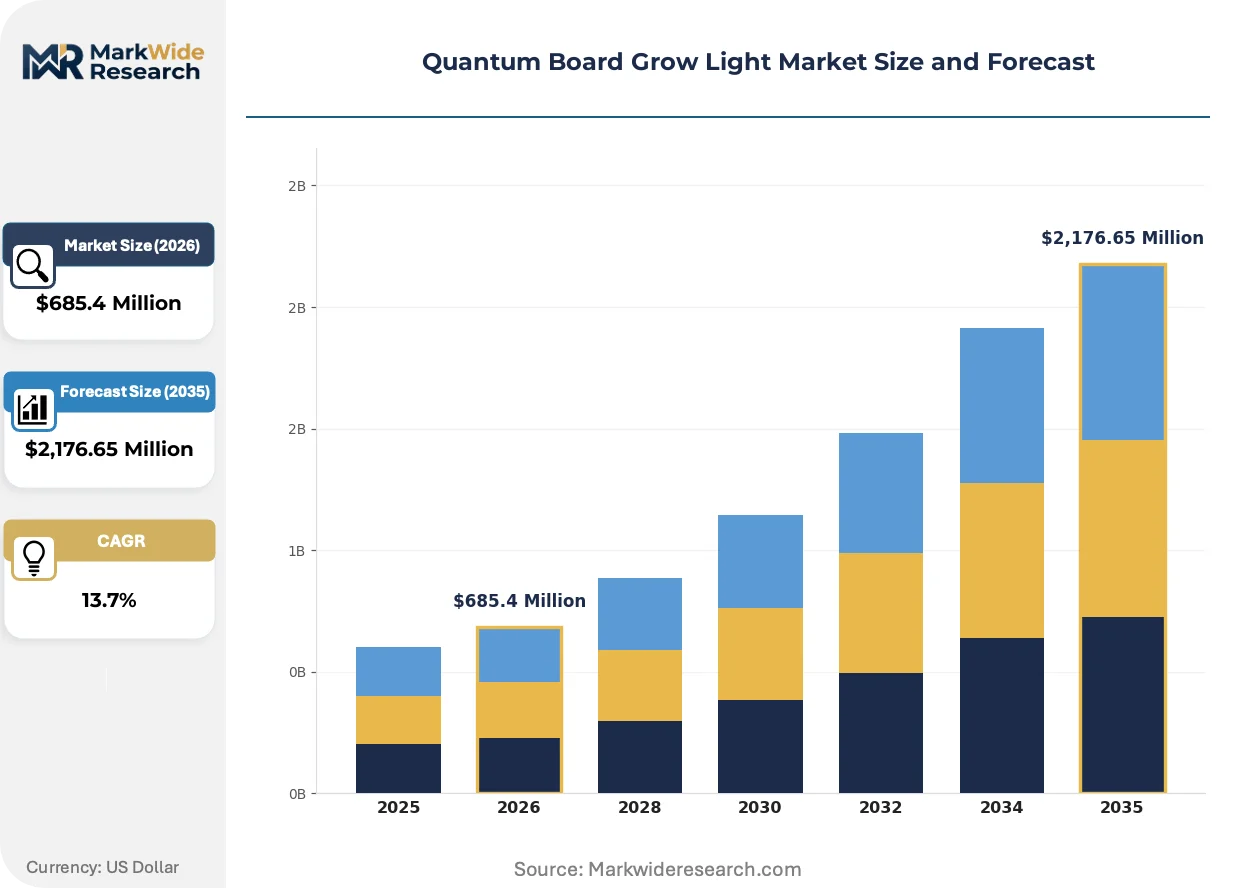
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, UV LED, COB, Quantum Board Technology: LED, OLED, Induction, HPS End User: Commercial Growers, Indoor Farms, Research Institutions, Home Gardens Power Rating: 100W, 200W, 300W, 400W |
| Companies Covered | Horticulture Lighting Group, California LightWorks, Black Dog LED, Mars Hydro, ILUMINAR Lighting, Kind LED Grow Lights, ViparSpectra, Signify Holding, Gavita International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Board Grow Light Market Trends and Innovations
Spectral engineering and connectivity integration are transforming quantum boards from passive illumination hardware into data-rich crop management platforms, compressing the traditional fixture replacement cycle and expanding addressable value per installation.
Multi-channel tunable white LED engines are electrifying fixture architecture by enabling dynamic photosynthetic photon flux density adjustment across vegetative and flowering growth stages. Large-scale Canadian cannabis producers are deploying these systems at commercial scale. The technology is electrifying competitive differentiation away from raw efficacy metrics toward software-defined cultivation protocols.
EPA Energy Star horticultural lighting certification is tightening efficacy thresholds for federal procurement eligibility, forcing mid-tier manufacturers to redesign thermal management systems or exit the rebate-dependent commercial channel. California investor-owned utilities are incorporating these standards into their agricultural efficiency incentive programs. The policy shift is compressing product development timelines for fixture makers serving the North American commercial greenhouse segment.
Subscription-based lighting-as-a-service models are emerging in the controlled-environment agriculture sector, displacing capital expenditure purchases for venture-backed vertical farming operators. These arrangements bundle hardware, spectral optimization consulting, and predictive maintenance into per-square-meter monthly fees. The financing innovation is most visible among indoor leafy green producers in Singapore and the Netherlands seeking to preserve balance sheet capacity for facility expansion.
Quantum Board Grow Light Market Segmentation
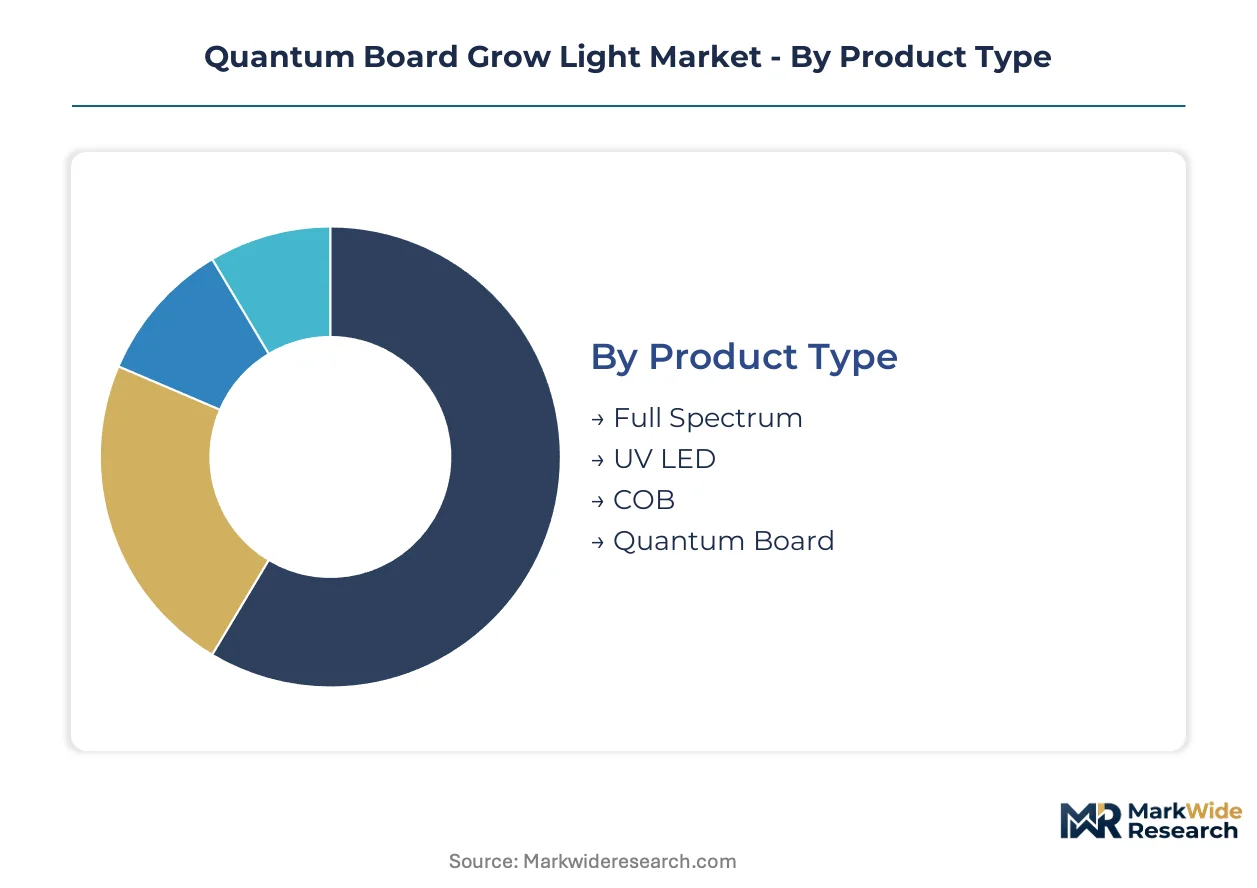
Quantum board grow light segmentation reveals distinct procurement patterns across spectral engineering sophistication and controlled-environment scale. Fixture manufacturers must align thermal management architectures and diode configurations to the specific photosynthetic photon flux density requirements of each buyer category.
Product Type:
Volume concentrates in full spectrum installations, while UV LED variants command substantial price premiums for specialized metabolite enhancement applications.
- Full Spectrum:Broad wavelength arrays spanning 400-700 nanometers dominate commercial greenhouse retrofits in the Netherlands under EU Green Deal mandates. Dutch vegetable cooperatives favor these configurations for predictable crop scheduling across lettuce and tomato production cycles.
- UV LED:Narrow-band ultraviolet supplementation targets terpene concentration in Oregon and California cannabis operations. Premium pricing reflects secondary metabolite research partnerships with university agricultural extension programs.
- COB:Chip-on-board configurations integrate multiple diodes under single optical lenses for simplified thermal management in mid-scale indoor farms.
- Quantum Board:Surface-mounted LED arrays on aluminum substrates deliver the highest photosynthetic photon flux density efficiency for professional cultivators replacing legacy HPS infrastructure.
Today's leader: Full Spectrum. Tomorrow's challenger: UV LED.
Technology:
Application maturity separates established solid-state platforms from experimental photobiology research tools.
- LED:Samsung LM301H diode platforms anchor current commercial deployments with proven efficacy above 2.7 micromoles per joule. North American cannabis facilities transitioning from HPS infrastructure represent concentrated demand.
- OLED:Organic electroluminescent prototypes enable real-time spectral tunability for Japanese and German precision agriculture research institutions. Development timelines extend five-to-seven years behind commercial LED maturation.
- Induction:Electrodeless fluorescent systems persist in legacy European greenhouse installations with lower retrofit urgency.
- HPS:High-pressure sodium retains residual share among cost-constrained vegetable growers in southern Spain and Italy.
LED dominates installed capacity. OLED climbs the fastest among emerging technology investments.
End User:
Scale economics divide procurement between institutional volume buyers and dispersed residential installations.
- Commercial Growers:Licensed cannabis operators in Canada and select US states drive 1000W+ fixture demand with dedicated HVAC integration requirements.
- Indoor Farms:Vertical leafy green producers in Singapore and the Netherlands deploy subscription-based lighting-as-a-service models to preserve capital for facility expansion.
- Research Institutions:University photobiology laboratories in Germany and Japan pilot multi-channel tunable white engines for vegetative-to-flowering stage transitions.
- Home Gardens:Sub-300W direct-to-consumer sales through e-commerce platforms disintermediate traditional horticultural distribution.
Commercial Growers anchor revenue concentration. Indoor Farms expand most quickly through operational expenditure financing structures.
Power Rating:
Wattage tiers correlate directly with facility scale and thermal management complexity.
- 100W:Compact configurations serve residential hobbyists and small-scale herb cultivation with minimal ventilation requirements.
- 200W:Mid-range fixtures balance coverage area against circuit load constraints for boutique commercial operations.
- 300W:Standardized units dominate Canadian cannabis flowering rooms with uniform canopy coverage specifications.
- 400W:High-output arrays target professional greenhouse bay replacements with dedicated driver compartments and active cooling systems.
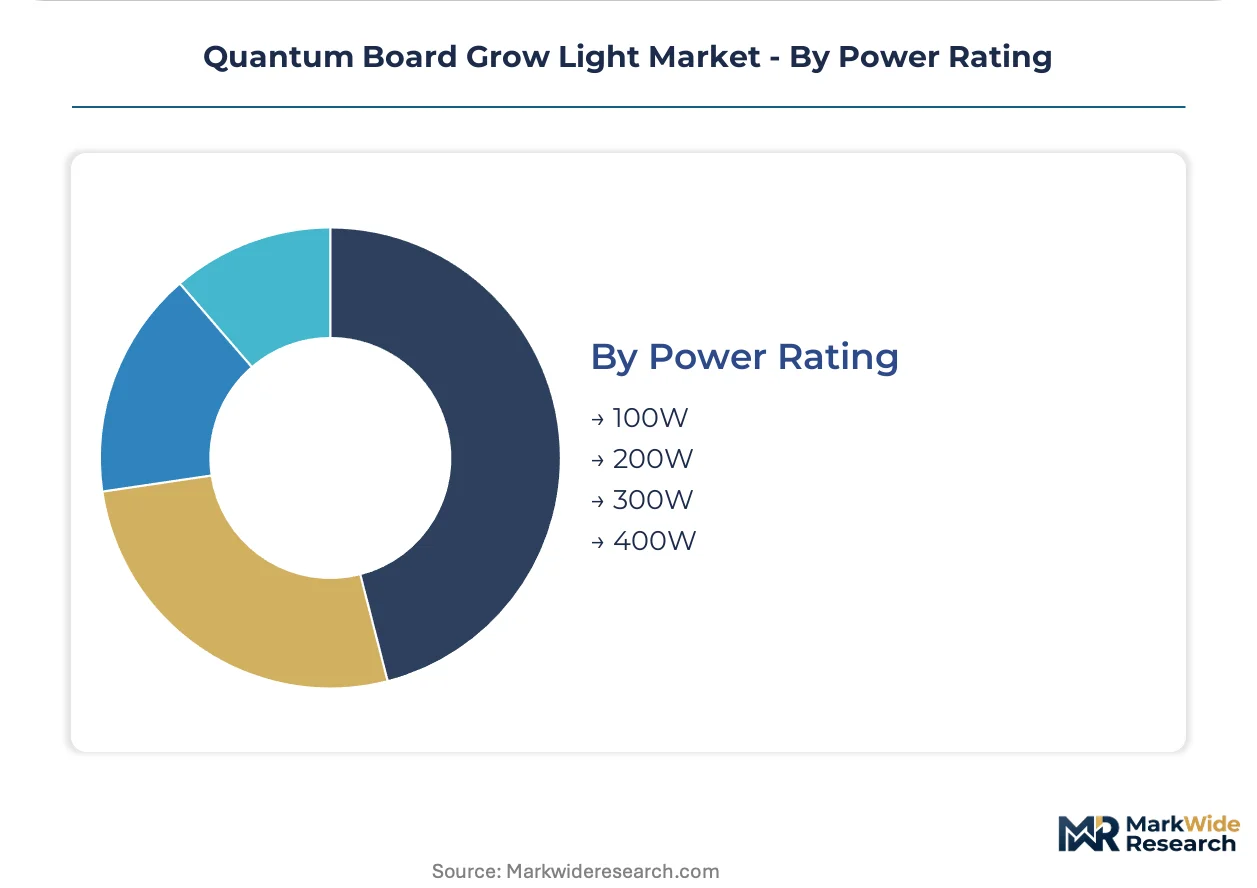
300W fixtures lead commercial procurement volumes. 400W systems gain share fastest among professional channel upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled horticultural engineers cluster around Eindhoven and Shenzhen, anchoring fixture design and diode integration capabilities. These talent pools concentrate near Samsung's LED foundry partnerships and Dutch greenhouse automation clusters.
United States
Licensed cannabis cultivators in California and Oregon drive 300W+ fixture demand for HPS-to-LED retrofits. EPA Energy Star horticultural certification tightens efficacy thresholds for federal procurement eligibility. Denver and Sacramento host concentrated installer networks serving commercial greenhouse operators.
Netherlands
Vegetable cooperatives in Westland face binding EU Green Deal retrofit deadlines through 2030. CE marking and EU F-Gas Regulation phase-outs accelerate LED substitution in greenhouse infrastructure. Wageningen University anchors precision agriculture research partnerships with fixture manufacturers.
Germany
Research institutions in Munich and Berlin pilot multi-channel tunable white engines for photobiology applications. Ecodesign regulations under the EU Green Deal restructure cost-of-entry for commercial growers. Bavarian greenhouse operators invest in spectral optimization for tomato and cucumber production cycles.
Canada
Licensed producers in British Columbia and Ontario deploy 1000W+ fixtures with dedicated HVAC integration requirements. Health Canada cannabis regulations mandate standardized lighting documentation for facility licensing. Toronto-area vertical farming startups experiment with subscription-based lighting-as-a-service financing.
Japan
METI-funded research consortia in Osaka and Tsukuba develop OLED quantum board prototypes for real-time spectral tunability. Precision agriculture initiatives target plant factory export competitiveness. Chiba Prefecture hosts concentrated vertical farming demonstration facilities testing next-generation photobiology tools.
Quantum Board Grow Light Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels. The vendor base separates into three tiers: premium professional-channel fixtures, mid-range direct-to-consumer units, and economy residential configurations. Two strategic archetypes dominate: diode-integrated manufacturers with captive Samsung partnerships, and assembler-distributors sourcing components from Taiwanese foundries. M&A activity concentrates on thermal management technology acquisitions, while capacity expansion targets aluminum substrate fabrication in Shenzhen and Eindhoven.
Within the professional-channel tier, Horticulture Lighting Group and Gavita International exemplify diode-integrated positioning through Samsung LM301H supply relationships. Mars Hydro occupies a scale-driven position in direct-to-consumer distribution. These three anchors represent divergent channel strategies: dedicated horticultural distribution networks versus e-commerce platform disintermediation versus hybrid professional-residential portfolios.
| Leading Market Players |
|---|
| Horticulture Lighting Group |
| California LightWorks |
| Black Dog LED |
| Mars Hydro |
| ILUMINAR Lighting |
| Kind LED Grow Lights |
| ViparSpectra |
| Signify Holding |
| Gavita International |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal energy-efficiency mandates gate qualified supply access and premium-tier pricing power for fixture manufacturers serving Dutch commercial greenhouse operators. The regulation creates a bifurcated procurement landscape where CE-marked, DLC-qualified products command substantial price premiums over uncertified alternatives.
Pricing Analysis
Subscription-based lighting-as-a-service offerings versus per-unit transactional sales split the pricing landscape across commercial grower segments. Three-tier pricing structure across premium professional-channel fixtures, mid-range direct-to-consumer units, and economy residential configurations reflects certification grade and thermal management sophistication. Cost compression in the mid-wattage tier intensifies as Samsung diode supply partnerships concentrate component sourcing leverage among diode-integrated manufacturers. Boutique cannabis cultivators in California and Oregon exhibit highest price sensitivity, while Dutch vegetable cooperatives under binding retrofit deadlines demonstrate lowest sensitivity due to guaranteed demand visibility.
Supply Chain Analysis
Direct-to-installer e-commerce channels handle residential and small-commercial demand below 1000W, while dedicated horticultural distribution networks serve professional greenhouse operators. Component sourcing concentrates in South Korea for Samsung LED foundry output, China for aluminum substrate fabrication in Shenzhen, and Taiwan for secondary semiconductor supply. Raw material dependencies span aluminum metal pricing, high-efficacy horticultural diodes, and thermal interface materials. Single-source diode vulnerability from Korean and Taiwanese LED foundries exposes fixture assemblers to allocation risk during semiconductor cycle peaks. Distribution runs through hybrid models combining Amazon and direct-to-consumer platforms with traditional agricultural supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage between Dutch regulatory-mandated demand certainty and North American cannabis facility capital expenditure cyclicality defines geographic positioning strategy. The Netherlands offers guaranteed procurement volume through 2030 under binding EU retrofit deadlines, while US markets present higher margin volatility with substantial upside during licensing waves.
For Market Incumbents: Acquire thermal management technology assets to defend against emerging Asian competitors with integrated aluminum substrate capabilities. Secure multi-source diode partnerships beyond Samsung to reduce captive pricing exposure during semiconductor allocation constraints. Expand capacity in Eindhoven engineering clusters to anchor professional-channel relationships against direct-to-consumer disintermediation. For New Entrants and Emerging Players: E-commerce platform routes offer lowest barrier-to-entry for sub-300W residential segments underserved by traditional horticultural distributors. Target California and Oregon home cultivation markets where regulatory fragmentation prevents incumbent scale advantages. Deploy spectral optimization software as differentiated service layer to escape commodity hardware pricing. For Investors and Strategic Acquirers: Roll-up economics work for thermal management specialists because fixture differentiation increasingly centers on heat dissipation engineering rather than raw diode efficacy. Mid-cap manufacturers with captive Samsung partnerships and established DLC qualification track records represent optimal acquisition profiles. Monitor DLC qualified products list expansion velocity as inflection indicator for utility rebate program generosity and commercial segment addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| Samsung Diode Supply Partnership | Secures component cost advantages for mid-wattage fixture manufacturers against Taiwanese foundry alternatives. |
| DLC Qualified Products List Certification | Unlocks utility rebate eligibility in North American commercial segments with extensive third-party testing investment. |
| Thermal Management Technology Acquisition | Addresses aluminum substrate cost volatility through captive fabrication capabilities in Shenzhen or Eindhoven clusters. |
| Lighting-as-a-Service Model Launch | Preserves balance sheet capacity for Singapore and Netherlands vertical farming operators seeking facility expansion capital. |
| UV LED Secondary Metabolite Array Development | Captures premium pricing from California and Oregon cannabis cultivators pursuing terpene concentration enhancement. |
Research Methodology
Bottom-up commercial grower and indoor farm demand modeling reconciled against top-down diode supply and fixture production tracking forms the analytical core. Primary interviews with greenhouse operations managers, horticultural lighting procurement officers, LED component sourcing directors, and utility rebate program administrators combined with secondary validation from EPA Energy Star certification databases, DLC qualified products list filings, EU Ecodesign regulatory documentation, and Samsung LED supply partnership disclosures. Triangulation between installation volume estimates from Dutch vegetable cooperatives, North American cannabis facility licensing records, and aluminum substrate import data ensures methodological robustness.
Input-output matrices map photosynthetic photon flux density requirements by crop type against available fixture configurations across the analysis window. Segmentation dimensions span spectral engineering sophistication, controlled-environment scale, power rating tier, and regional regulatory framework. CAGRs derive from curve-fitting historical substitution patterns from HPS to LED infrastructure against policy-mandated retrofit timelines. Industry-specific forecast inputs include EU Green Deal binding deadline schedules and Health Canada cannabis facility licensing velocity.
The model assumes a particular technology adoption path; alternative pathways for OLED spectral tunability would alter the outlook if commercial maturation accelerates beyond current five-to-seven year development timelines. Forecasts reflect assumptions regarding aluminum price stability, semiconductor allocation continuity, and rebate program persistence that specific risk factors including trade policy shifts or commodity supercycles could revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
North America Vertical Farming Market