
 Canada Indoor Farming Market | 2026-2036
Canada Indoor Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Indoor Farming Market Insights
Direct-to-restaurant supply chains is rewriting procurement patterns for fresh produce in Canadian urban corridors. GoodLeaf Farms leverages controlled-environment expertise to sustain year-round output from its Guelph facility. Elevate Farms anchors premium herb distribution through dedicated partnerships with Toronto's fine-dining sector. DeepBlue Greens differentiates via deep-water culture systems optimized for high-density lettuce production.
Canada indoor farming denotes soilless cultivation within enclosed structures using artificial lighting, climate control, and nutrient delivery systems to achieve yield rates per square meter exceeding open-field agriculture by an order of magnitude. These facilities primarily serve commercial buyers seeking traceable, pesticide-minimal produce with compressed harvest-to-plate timelines. Hydroponics dominates installed capacity due to lower capital thresholds and operational familiarity among Canadian growers. Vertical farming represents the fastest-expanding technology segment as developers stack production layers to maximize land productivity in expensive urban real estate. The retailer end-user channel commands the largest revenue share while restaurant direct sales yield superior per-unit margins.
Health Canada's Safe Food for Canadians Regulations impose preventive control plans and traceability requirements that elevate compliance costs for smaller operators. Provincial energy regulators including Ontario's IESO and BC Hydro shape facility economics through demand-response programs and clean electricity rate structures for agricultural loads. Stakeholders must monitor evolving municipal zoning bylaws that alternately restrict or incentivize vertical farm construction in Canadian core urban districts.
Market Dynamics
Restaurant procurement of hyperlocal greens is compressing harvest-to-plate timelines and forcing Ontario and British Columbia facilities to reconfigure distribution networks around same-day delivery commitments.
Growth Catalysts
- Health Canada Safe Food for Canadians Regulations:Traceability mandates favor large controlled-environment operators with integrated monitoring systems over fragmented field growers.
- IESO demand-response programs:Ontario's clean electricity rate structures for agricultural loads reduce operational costs for facilities participating in grid-balancing schemes.
- Vertical farming technology:Stacked production layers maximize yield per square meter in expensive Greater Toronto Area real estate, attracting developer capital.
Market Restraints
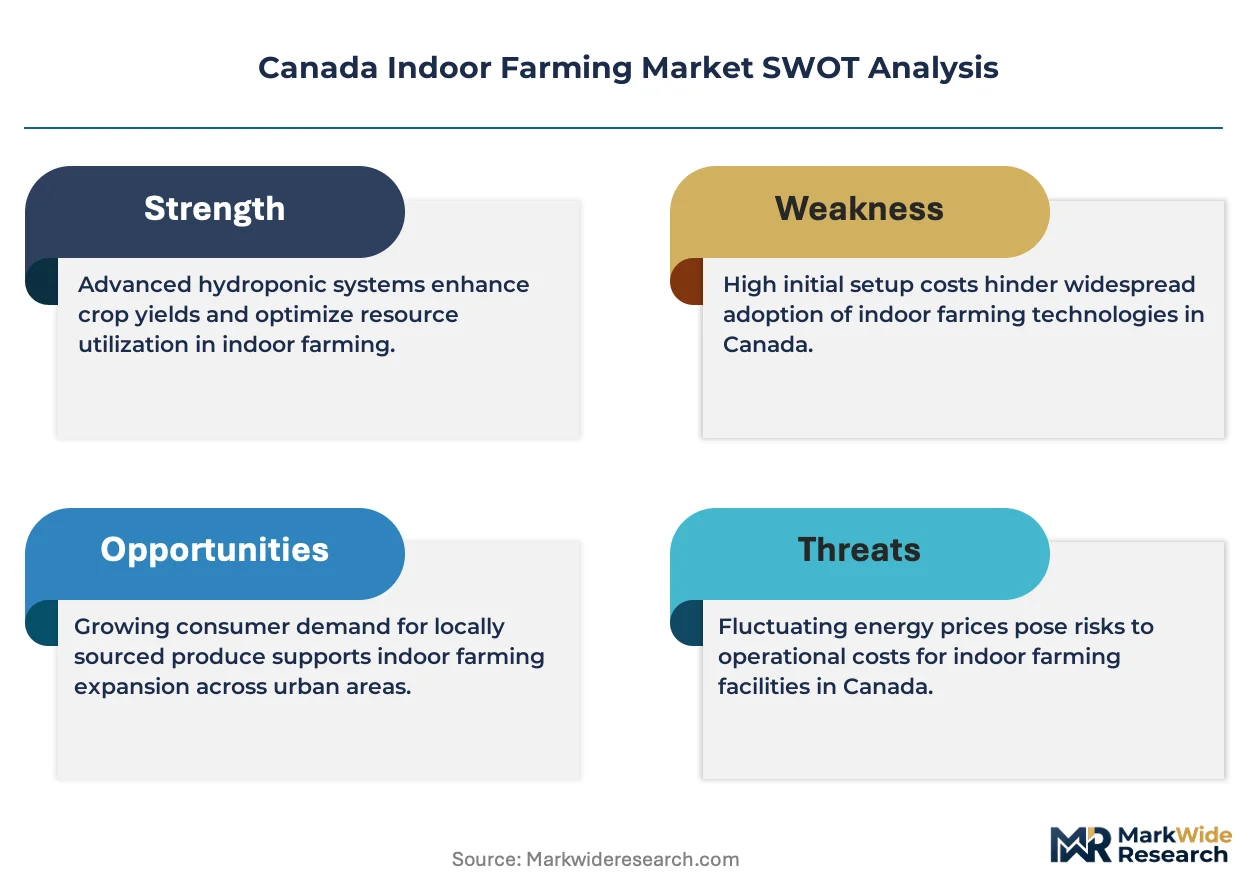
- Energy cost volatility:Ontario and BC electricity rate fluctuations compress margins for artificial lighting and climate control systems.
- Input supply concentration:Specialized LED grow light and nutrient solution suppliers concentrate in Asia-Pacific, exposing Canadian operators to currency and shipping risks.
- Technical limitation:Current controlled-environment systems struggle with energy-intensive fruiting crops beyond leafy greens and herbs.
Strategic Opportunities
- Underpenetrated Atlantic Canada:Halifax and Moncton lack vertical farming infrastructure despite restaurant demand for traceable produce.
- Provincial energy efficiency mandates:BC Hydro and Ontario IESO incentive programs subsidize retrofitting existing warehouse structures for controlled-environment agriculture.
- Direct-to-restaurant channels:Bypassing distributors captures margin premiums from Toronto fine-dining establishments seeking provenance documentation.
Industry Challenges
- Controlled-environment agronomy expertise:Canadian universities produce limited graduates with combined horticulture and engineering skills for facility management.
- Safe Food for Canadians certification timelines:Preventive control plan documentation delays market entry for new entrants by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Indoor Farming Market |
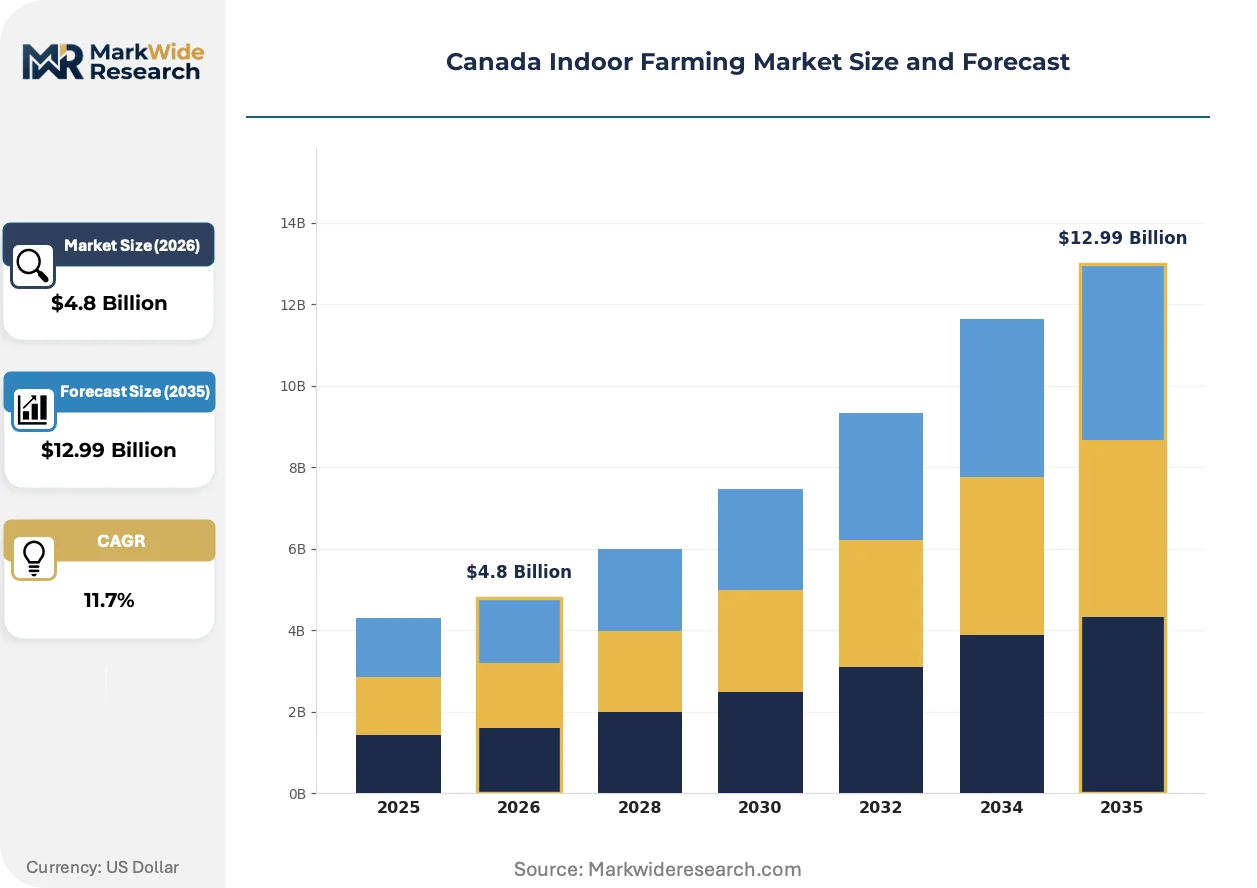
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Herbs, Flowers Technology: Hydroponics, Aeroponics, Aquaponics, Vertical Farming End User: Retailers, Restaurants, Wholesalers, Home Consumers Distribution Channel: Online, Direct Sales, Supermarkets, Farmers' Markets |
| Companies Covered | Elevate Farms, DeepBlue Greens, Mantra Farms, orun.ai, Jardin Indoor Inc., Metropolis Farms, Sky Greens Canada, GoodLeaf Farms, Avery Farms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Indoor Farming Market Trends and Innovations
Automation and data analytics are compressing operational decision cycles and enabling predictive harvest scheduling that aligns production with restaurant order patterns.
Spectral tuning LED systems adjust light wavelength combinations to manipulate plant morphology and phytochemical profiles. Large-scale Ontario facilities deploy these systems to customize herb flavor intensity for specific chef contracts. This precision is rendering obsolete the uniform-output model of first-generation vertical farms.
Health Canada's preventive control plan requirements under the Safe Food for Canadians Regulations mandate hazard analysis and traceability documentation. Smaller operators face compliance cost burdens that favor consolidation around integrated software platforms. British Columbia facilities respond fastest due to prior experience with provincial organic certification rigor.
Chef-driven specification of harvest maturity and post-harvest handling protocols now governs contract terms. Toronto fine-dining establishments source microgreens with defined cotyledon stage and custom packaging, displacing distributor-assorted commodity offerings. This specification intensity concentrates in the Greater Toronto Area where restaurant density supports dedicated supply relationships.
Canada Indoor Farming Market Segmentation
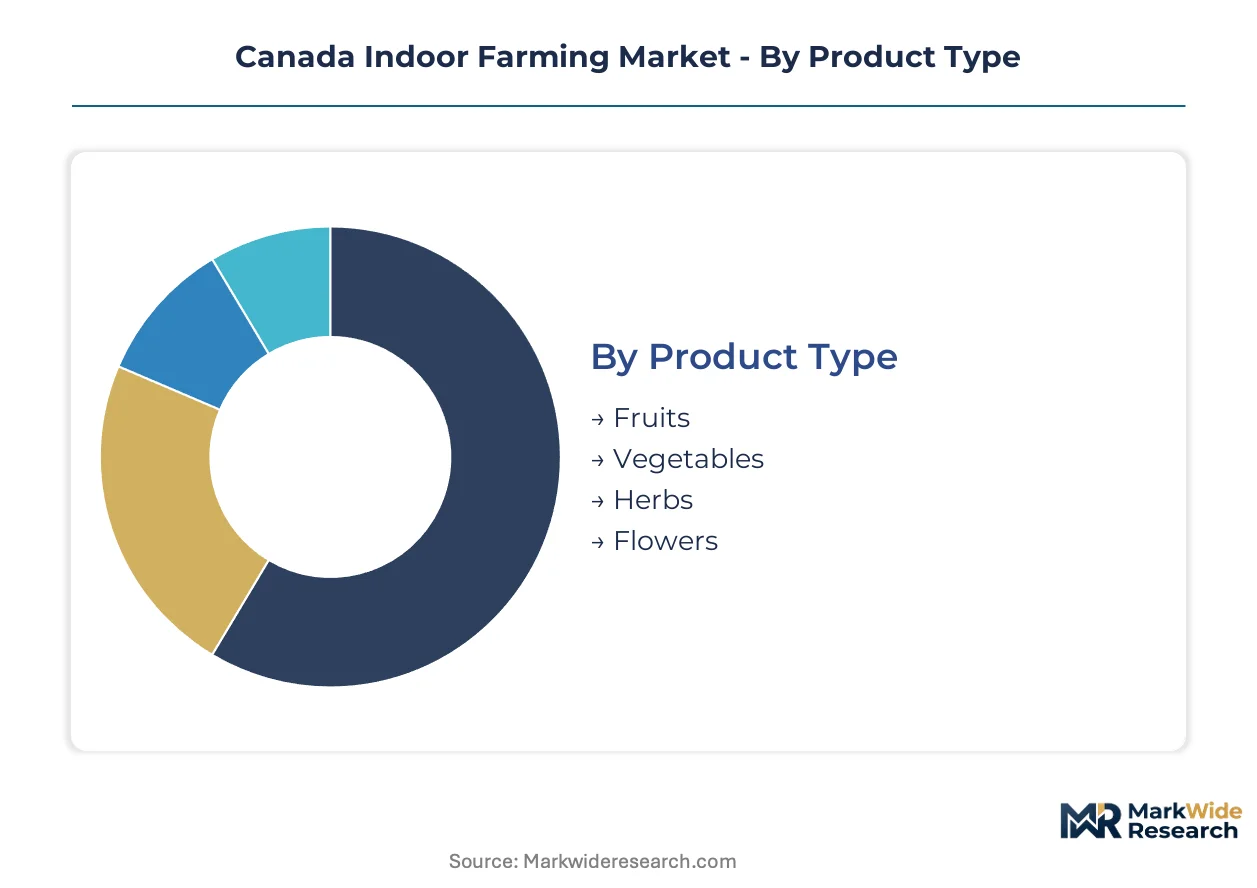
Segmentation reveals how Canadian indoor farming operators configure production and distribution around distinct buyer requirements. Each dimension carries implications for facility design, regulatory compliance, and margin structure.
Product Type:
After-sales service intensity varies sharply across crop categories, with perishable leafy products demanding rapid response logistics while woody herbs require extended technical support for pruning protocols.
- Vegetables:Leafy greens and microgreens dominate Ontario and British Columbia facility output, with lettuce varieties optimized for deep-water culture systems achieving harvest cycles under 35 days. Toronto restaurant procurement concentrates demand for same-day delivery of living product with intact root systems.
- Herbs:Culinary basil, cilantro, and specialty varieties command premium pricing through direct chef relationships in Vancouver and Montreal fine-dining establishments. Health Canada traceability requirements favor large operators with integrated batch documentation systems.
- Fruits:Strawberry production in controlled environments remains limited due to energy-intensive fruiting stage requirements; British Columbia operators piloting tiered vertical systems for berry cultivation face technical constraints on yield consistency.
- Flowers:Ornamental and edible flower categories serve niche event catering and floral retail segments in Calgary and Ottawa metropolitan areas.
Vegetables hold the largest share; momentum sits with herbs as chef-driven specification intensity deepens.
Technology:
Capital deployment patterns divide Canadian operators between lower-threshold hydroponic systems and premium vertical farming installations targeting urban real estate constraints.
- Hydroponics:Nutrient film technique and deep-water culture systems constitute the majority of installed Canadian capacity, with Guelph-area facilities leveraging established agronomic expertise and lower technical staffing requirements. Ontario IESO demand-response programs favor these energy-profiled operations.
- Vertical Farming:Stacked-layer production maximizes yield per square meter in expensive Greater Toronto Area warehouse conversions, attracting developer capital seeking land productivity arbitrage. Spectral tuning LED systems enable customization of plant morphology for specific buyer contracts.
- Aeroponics:Mist-based nutrient delivery reduces water consumption but requires precise engineering control; limited Canadian adoption due to technical staffing scarcity and higher maintenance protocols.
- Aquaponics:Integrated fish-plant systems operate at small scale in educational and research facilities; commercial viability constrained by dual-species regulatory compliance under Health Canada and provincial fisheries regulations.
Hydroponics retains the dominant installed base; vertical farming climbs fastest as urban land costs reshape facility economics.
End User:
Customer type determines pricing power, with direct restaurant relationships capturing margin premiums unavailable through distributor-mediated channels.
- Restaurants:Toronto and Vancouver fine-dining establishments source hyperlocal produce with defined harvest maturity, custom packaging, and provenance documentation. Same-day delivery commitments compress distribution network design.
- Retailers:Grocery chains in Ontario and British Columbia represent the largest revenue channel by volume, though per-unit margins trail direct sales; Loblaw and Sobeys procurement emphasizes consistent supply and competitive pricing.
- Wholesalers:Traditional produce distributors aggregate output from multiple Canadian controlled-environment facilities for redistribution to institutional foodservice; this channel faces margin pressure from direct-to-restaurant disintermediation.
- Home Consumers:Compact countertop systems and subscription seedling services serve urban hobbyist segments in Montreal and Calgary; limited scale relative to commercial channels.
Retailers command the largest revenue share; restaurant direct sales yield superior per-unit margins and fastest growth trajectory.
Distribution Channel:
Channel selection reflects trade-offs between margin capture and operational complexity, with direct sales requiring dedicated logistics infrastructure.
- Direct Sales:Dedicated delivery fleets serving Toronto restaurant clusters enable harvest-to-plate timelines under 12 hours and documentation of provenance for chef specifications. Elevated operational overhead concentrates viability in dense urban corridors.
- Supermarkets:Loblaws, Sobeys, and Metro chains provide volume absorption for Ontario vertical farming facilities, though slotting fees and price competition compress returns compared to direct channels.
- Online:E-commerce platforms aggregate home consumer demand for living herb products and compact growing systems; Vancouver and Toronto metropolitan areas show highest penetration.
- Farmers' Markets:Seasonal direct retail in Ottawa, Halifax, and Victoria offers brand-building opportunities for smaller operators; limited scale and weather dependency constrain year-round relevance.
Supermarkets absorb the largest volume; direct sales channels expand most quickly as restaurant procurement patterns shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The St. Lawrence Seaway and CN Rail freight corridors enable Ontario's vertical farming clusters to reach Toronto restaurant markets within hours of harvest, anchoring Canada's controlled-environment agriculture infrastructure.
Ontario
Toronto's fine-dining density drives demand for same-day microgreen delivery with documented provenance. Ontario's IESO demand-response programs subsidize clean electricity rates for agricultural loads participating in grid-balancing schemes. Guelph hosts GoodLeaf Farms' flagship facility leveraging controlled-environment expertise for year-round output.
British Columbia
Vancouver's restaurant procurement of hyperlocal greens compresses harvest-to-plate timelines to under twelve hours. BC Hydro shapes facility economics through demand-response programs and clean electricity rate structures for controlled-environment loads. Metro Vancouver vertical farming clusters scale production of culinary herbs for chef-driven specifications.
Quebec
Montreal's institutional foodservice and emerging fine-dining segments absorb controlled-environment lettuce and herb output. Provincial energy efficiency mandates for agricultural operations incentivize LED retrofitting in existing warehouse structures. Laval and Longueuil warehouse conversions attract developer capital seeking land productivity arbitrage near dense urban corridors.
Alberta
Calgary's corporate catering and event segments create demand for traceable ornamental and edible flower categories. The province's electricity market deregulation exposes operators to rate volatility affecting artificial lighting economics. Edmonton metropolitan area facilities pilot deep-water culture systems for high-density lettuce production serving regional grocery chains.
Atlantic Canada
Halifax and Moncton restaurant demand for pesticide-minimal produce outpaces local controlled-environment supply capacity. Federal Safe Food for Canadians Regulations impose preventive control plan requirements that delay new entrant market entry. Saint John warehouse availability and port access position the region for future vertical farming development serving Maritime urban markets.
Canada Indoor Farming Market Competitive Landscape
On the supply side, the industry is consolidating around integrated operators with captive distribution networks and regulatory compliance infrastructure. Tiered competitive dynamics separate large-scale vertical farming developers from specialized hydroponic herb producers and technology-anchored newcomers. Strategic archetypes include controlled-environment scale players, chef-direct relationship specialists, and automation-integrated system developers. Dominant competitive moves center on direct-to-restaurant channel capture and provincial energy program participation for operational cost reduction.
Among Ontario-based operators, Elevate Farms and GoodLeaf Farms exemplify the scale-driven archetype with integrated production and distribution infrastructure, while DeepBlue Greens occupies a position within the technology-differentiated tier emphasizing system-level optimization. These three entities anchor distinct competitive vectors: chef-direct premium positioning, year-round volume supply, and technical system efficiency respectively.
| Leading Market Players |
|---|
| Elevate Farms |
| DeepBlue Greens |
| Mantra Farms |
| orun.ai |
| Jardin Indoor Inc. |
| Metropolis Farms |
| Sky Greens Canada |
| GoodLeaf Farms |
| Avery Farms |
| Others |
Pricing and Supply Chain Analysis
The Greater Toronto Area's vertical farming cluster concentrates national production capacity for hyperlocal leafy greens, translating geographic scarcity into premium pricing power for same-day restaurant delivery contracts. Ontario IESO demand-response participation subsidizes electricity rates for compliant facilities, compressing operational cost differentials against smaller non-participating competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Canadian indoor farming transactions. Premium tiers attach to chef-direct microgreen contracts with defined cotyledon stage and custom packaging; standard tiers serve grocery chains emphasizing consistent supply; economy tiers capture institutional foodservice through wholesaler aggregation. Pricing pressure stems from Ontario and British Columbia electricity rate volatility affecting artificial lighting economics. Restaurant direct buyers exhibit lowest price sensitivity due to provenance documentation requirements, while institutional foodservice channels negotiate aggressively on volume.
Supply Chain Analysis
Export-control regimes on advanced LED grow light technology from China and South Korea constrain Canadian facility expansion timelines and capital deployment. Specialized semiconductor components for spectral tuning systems and precision nutrient dosing equipment concentrate in Taiwan, Japan, and Germany. Supply chain risk centers on single-source vulnerability for high-efficiency LED modules subject to Asia-Pacific shipping disruptions. Distribution runs through dedicated delivery fleets for Toronto restaurant clusters and supermarket consolidation points for grocery chain absorption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's indoor farming sector represents a high-growth disruption anchored by Health Canada Safe Food for Canadians Regulations that favor integrated operators with preventive control infrastructure over fragmented field growers.
For Market Incumbents: Build regulatory compliance moats through integrated traceability software platforms that automate Health Canada preventive control documentation. Deepen backward integration into captive seed genetics programs to reduce input dependency on external suppliers. Consolidation around multi-facility networks defends against emerging automation-anchored entrants targeting same-day delivery density. For New Entrants and Emerging Players: Atlantic Canada restaurant demand in Halifax and Moncton represents the most penetrable entry point given supply scarcity and lower incumbent saturation. Warehouse conversion opportunities in Saint John leverage port access for future Maritime urban market expansion. Go-to-market positioning should emphasize direct chef relationships with provenance documentation rather than competing on grocery chain volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical farming operators with multi-year restaurant supply contracts and IESO demand-response program lock-in. Long-term viability across the projection horizon favors facilities with spectral tuning LED capabilities and automated harvest scheduling alignment with buyer order patterns. Watch for inflection signals in provincial energy efficiency mandate expansion beyond Ontario and British Columbia.| Strategic Initiative | Industry Significance |
|---|---|
| IESO Demand-Response Program Enrollment | Clean electricity rate subsidies from Ontario's grid operator compress operational cost structures for artificial lighting loads. |
| Spectral Tuning LED System Deployment | Wavelength manipulation capabilities enable customization of herb morphology for specific Toronto chef contract specifications. |
| Direct-to-Restaurant Channel Expansion | Same-day delivery infrastructure captures margin premiums unavailable through Loblaw and Sobeys supermarket consolidation. |
| Preventive Control Plan Automation | Integrated software platforms reduce Health Canada Safe Food for Canadians certification timelines from twelve months toward six. |
| Atlantic Canada Warehouse Conversion | Saint John facility development addresses supply scarcity in Halifax and Moncton restaurant markets with underpenetrated infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from vertical farming facility operators, restaurant procurement managers, provincial energy regulatory officials, and controlled-environment agronomists and refined through secondary validation. Primary fieldwork combined structured interviews with GoodLeaf Farms and Elevate Farms executives alongside facility tours in Guelph and Toronto. Secondary sources included Health Canada Safe Food for Canadians Regulations documentation, Ontario IESO demand-response program filings, BC Hydro agricultural rate schedules, and municipal zoning bylaws for controlled-environment agriculture. Bottom-up facility capacity modeling and top-down restaurant demand aggregation were triangulated against trade data for LED grow light and nutrient solution imports.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed product type, technology platform, end-user channel, and distribution configuration alongside regional regulatory cluster differentiation. CAGRs were derived from facility-level output projections weighted by electricity rate scenario sensitivity. Industry-specific forecast inputs incorporated Ontario IESO program participation rates and chef-direct contract penetration assumptions for Toronto fine-dining density.
Practitioners should monitor provincial energy mandate expansion, Health Canada enforcement intensity on preventive control plans, and Asia-Pacific LED supplier consolidation for early signals of forecast deviation. Forecasts reflect assumptions on IESO program continuity and Toronto restaurant density sustaining same-day delivery economics. Material shifts in electricity rate structures or Safe Food for Canadians certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Vertical Farming Market