
 US Vertical Farming Market | 2026-2036
US Vertical Farming Market Size, Share, and Industry Trends Forecast 2026-2036
US Vertical Farming Market Outlook
The EPA's water-efficiency mandates for agricultural operations is broadening the addressable market for closed-loop cultivation systems. AeroFarms leverages proprietary aeroponic platforms to minimize nutrient runoff while maximizing yield density per square foot. Bowery Farming sustains rapid production cycles through its integrated operating system that automates light, irrigation, and climate variables. Plenty Unlimited anchors large-scale deployment with facilities designed for regional produce distribution to major grocery chains.
US Vertical Farming denotes the practice of growing crops in stacked layers or vertically inclined surfaces within controlled indoor environments, typically employing hydroponic, aeroponic, or aquaponic systems with LED spectrum tuning and precise climate management to optimize photosynthesis and resource use. Its primary purpose is to deliver fresh, pesticide-reduced produce proximate to urban consumption centers while decoupling yield from seasonal variability and arable land constraints. Hydroponics leads installed capacity due to lower technical barriers and established supply chains for nutrient solutions and growing substrates. Aeroponics captures expanding investment as operators prioritize water-minimal architectures and accelerated harvest frequencies. Leafy Greens dominates product type revenue, though herbs command premium positioning in restaurant and direct-to-consumer channels.
The USDA administers urban agriculture incentive programs that subsidize indoor farming infrastructure in designated food deserts, while the FDA enforces Produce Safety Rule standards that govern water quality, sanitation, and traceability protocols for controlled-environment agriculture. State-level regulators in California, New York, and Illinois supplement federal frameworks with facility licensing, energy-use reporting, and organic certification pathways specific to soilless cultivation. OSHA standards for agricultural worker safety in enclosed environments additionally shape facility design and operational compliance. Stakeholders must monitor evolving state energy tariffs and carbon accounting rules that will determine operating cost structures and locational competitiveness across metropolitan markets.
Market Dynamics
The USDA's urban agriculture grant programs and EPA water-efficiency mandates are reshaping capital deployment toward closed-loop cultivation systems in metropolitan corridors.
Growth Catalysts
- USDA Urban Agriculture Incentive Programs:Federal subsidies for indoor farming infrastructure in designated food deserts lower barrier-to-entry for new operators in underserved metropolitan zones.
- Grocery Retail Shelf Expansion:Major supermarket chains are carving dedicated space for locally grown produce, creating pull-through demand for regional vertical farming output.
- LED Spectrum Tuning:Advances in photosynthetically active radiation optimization are compressing growth cycles while reducing energy intensity per harvest.
Market Restraints
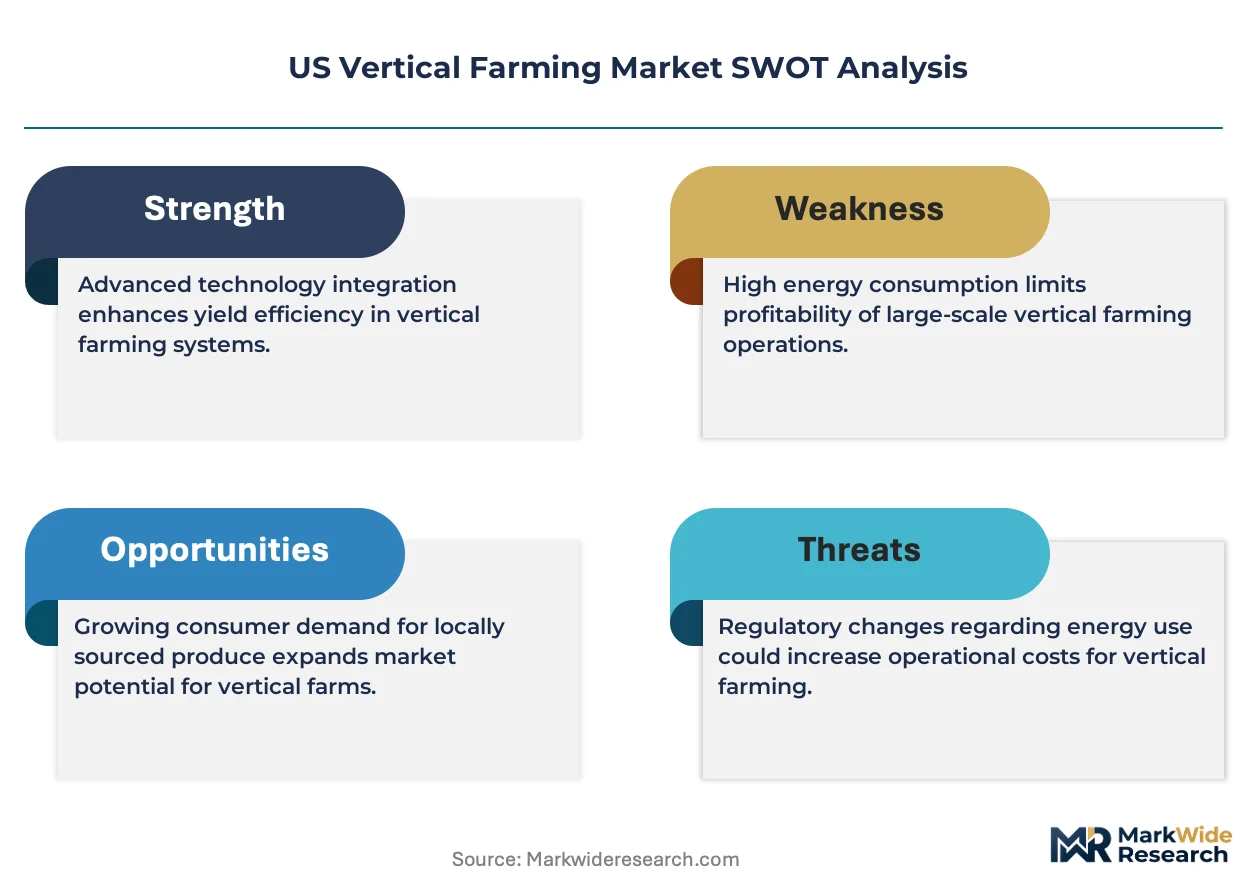
- Energy Input Cost Volatility:Electricity pricing fluctuations in deregulated state markets compress operating margins for climate-controlled facilities running 24/7 environmental systems.
- Supply Concentration in LED Components:Domestic production capacity for horticultural-grade lighting remains concentrated among a narrow supplier base, creating procurement bottlenecks.
- Technical Limitation in Crop Diversification:Current aeroponic and hydroponic architectures remain optimized for leafy greens, limiting revenue mix expansion into higher-value fruiting crops.
Strategic Opportunities
- Underpenetrated Sun Belt Expansion:Arizona, Texas, and Florida present white-space deployment potential where year-round outdoor agriculture reduces competitive pressure from field-grown supply.
- Restaurant Direct Distribution:Chef-to-farmer procurement relationships bypass traditional wholesale channels, capturing premium positioning for heritage herb varieties.
- State-Level Carbon Accounting Rules:Emerging mandates in California and New York create locational advantage for operators with verified low-carbon cultivation credentials.
Industry Challenges
- Controlled Environment Agronomy Talent Gap:The intersection of plant science, automation engineering, and data analytics commands salaries that strain emerging operator budgets.
- OSHA Agricultural Worker Safety Compliance:Enclosed facility standards for chemical handling, confined space protocols, and ergonomic equipment add operational complexity and training overhead.
- Organic Certification Pathway Uncertainty:USDA National Organic Program soil-based requirements create ambiguity for hydroponic and aeroponic operators seeking premium price positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vertical Farming Market |
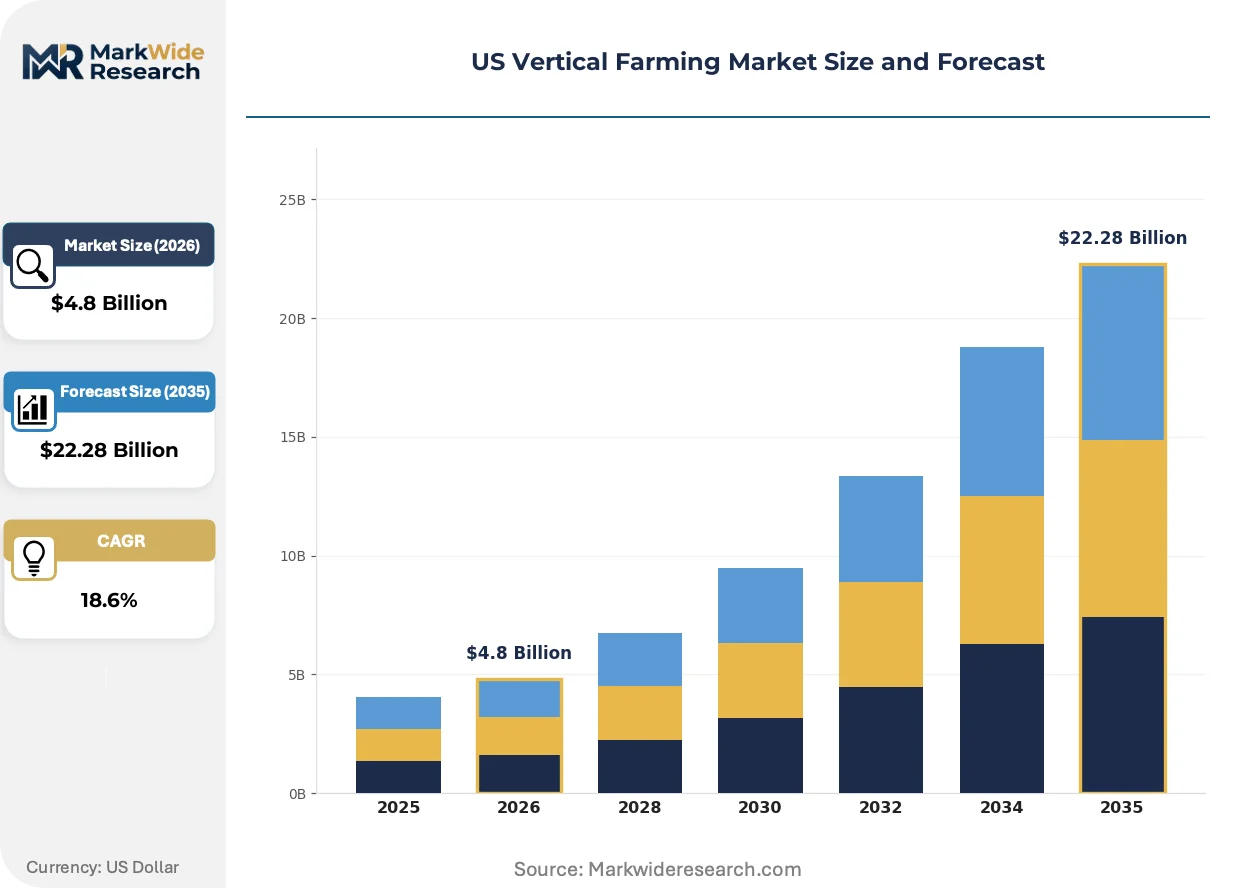
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Aeroponics, Hydroponics, Aquaponics, Soil-based End User: Retail, Restaurants, Home Gardens, Educational Institutions Product Type: Leafy Greens, Herbs, Fruits, Vegetables Distribution Channel: Direct Sales, Online Retail, Wholesalers, Farmers Markets |
| Companies Covered | AeroFarms, Bowery Farming, Plenty Unlimited, Freight Farms, BrightFarms, Gotham Greens, 80 Acres Farms, American Hydroponics, Local Bounti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vertical Farming Market Strategic Shifts
Automation architectures and regulatory carbon accounting are compressing the link between cultivation technology and metropolitan procurement patterns.
Modular grow rack systems are modularizing facility deployment, allowing operators to phase capital expenditure across expansion cycles. Regional grocery distributors and foodservice aggregators are piloting containerized units for hyperlocal supply integration. This modularity is compressing the traditional two-year facility commissioning timeline into six-month activation windows.
The EPA's evolving water-efficiency mandates for agricultural operations are tightening discharge standards for nutrient runoff. Controlled-environment operators leveraging closed-loop irrigation capture structural advantage over field-grown competitors facing remediation costs. Northeast corridor facilities in New York and New Jersey are accelerating compliance investments ahead of anticipated state-level rule finalization.
Chef procurement networks are displacing traditional wholesale distributors for premium herb categories. Restaurant groups with sustainability mandates are contracting directly with single-source vertical farms for traceability documentation. This channel disintermediation concentrates in metropolitan markets where farm-to-table positioning commands menu price premiums.
US Vertical Farming Market Segmentation
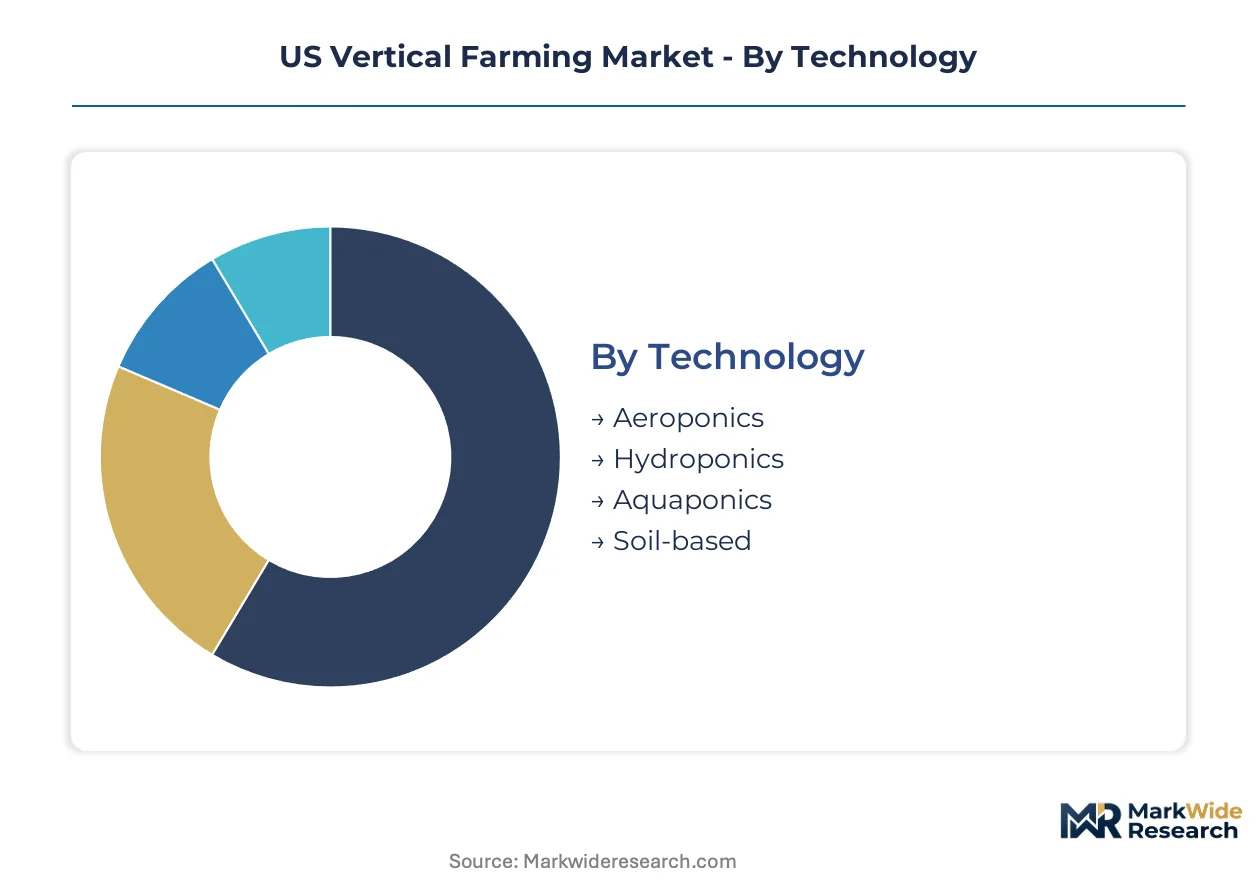
Technology choice dictates capital intensity and operating cost structure for US vertical farming operators. End-user concentration shapes facility scale and geographic placement decisions across metropolitan corridors.
Technology:
Buyers select cultivation systems based on water efficiency mandates and harvest frequency requirements.
- Hydroponics:Nutrient film technique and deep water culture systems dominate installed base due to lower technical barriers and established supply chains for growing substrates. Demand concentrates in New Jersey and Pennsylvania facilities serving Philadelphia and New York metropolitan procurement networks, driven by state-level water-use reporting requirements that favor proven system architectures.
- Aeroponics:Mist-based root delivery minimizes water consumption while accelerating growth cycles through optimized oxygen exposure. Investment flows toward Northeast corridor deployments where EPA discharge standards tighten fastest, with operators prioritizing closed-loop nutrient recovery for regulatory compliance headroom.
- Aquaponics:Integrated fish cultivation provides organic nutrient inputs but adds biological complexity that limits commercial scale.
- Soil-based:Containerized organic systems appeal to operators pursuing USDA National Organic Program certification despite yield density tradeoffs.
Hydroponics leads on scale; aeroponics leads on momentum.
End User:
Customer type determines pricing power and volume contract structures.
- Retail:Grocery chains command standardized pack sizes and traceability documentation that favors large-scale automated facilities. Kroger and Whole Foods Market procurement teams in the Northeast corridor are carving dedicated shelf space for locally grown produce, creating pull-through demand for regional vertical farming output with verified low-carbon credentials.
- Restaurants:Chef procurement networks bypass wholesale channels for heritage herb varieties with premium positioning. New York and Chicago metropolitan restaurant groups with sustainability mandates are contracting directly with single-source vertical farms, capturing menu price premiums through farm-to-table traceability.
- Home Gardens:Consumer countertop units and subscription seedling services address hobbyist cultivation.
- Educational Institutions:University and K-12 programs prioritize demonstration-scale systems for STEM curriculum integration.
Retail commands volume concentration; restaurants capture margin expansion.
Product Type:
Biological constraints limit crop diversification within current facility architectures.
- Leafy Greens:Lettuce, spinach, and kale varieties dominate revenue mix due to short growth cycles and consistent demand from retail and foodservice channels. Production concentrates in New York and New Jersey facilities optimized for rapid harvest turnover, with LED spectrum tuning compressing cycles to three-week intervals.
- Herbs:Basil, cilantro, and specialty varieties command price premiums in direct restaurant distribution. Northeast corridor chef networks are displacing traditional wholesale distributors for premium categories, with single-source contracts providing traceability documentation required by sustainability-mandated restaurant groups.
- Fruits:Strawberry and tomato cultivation requires structural modifications that raise capital intensity.
- Vegetables:Pepper and cucumber production remains limited by technical constraints in controlled environment systems.
Leafy greens anchor revenue scale; herbs drive margin expansion.
Distribution Channel:
Channel selection determines working capital requirements and customer relationship depth.
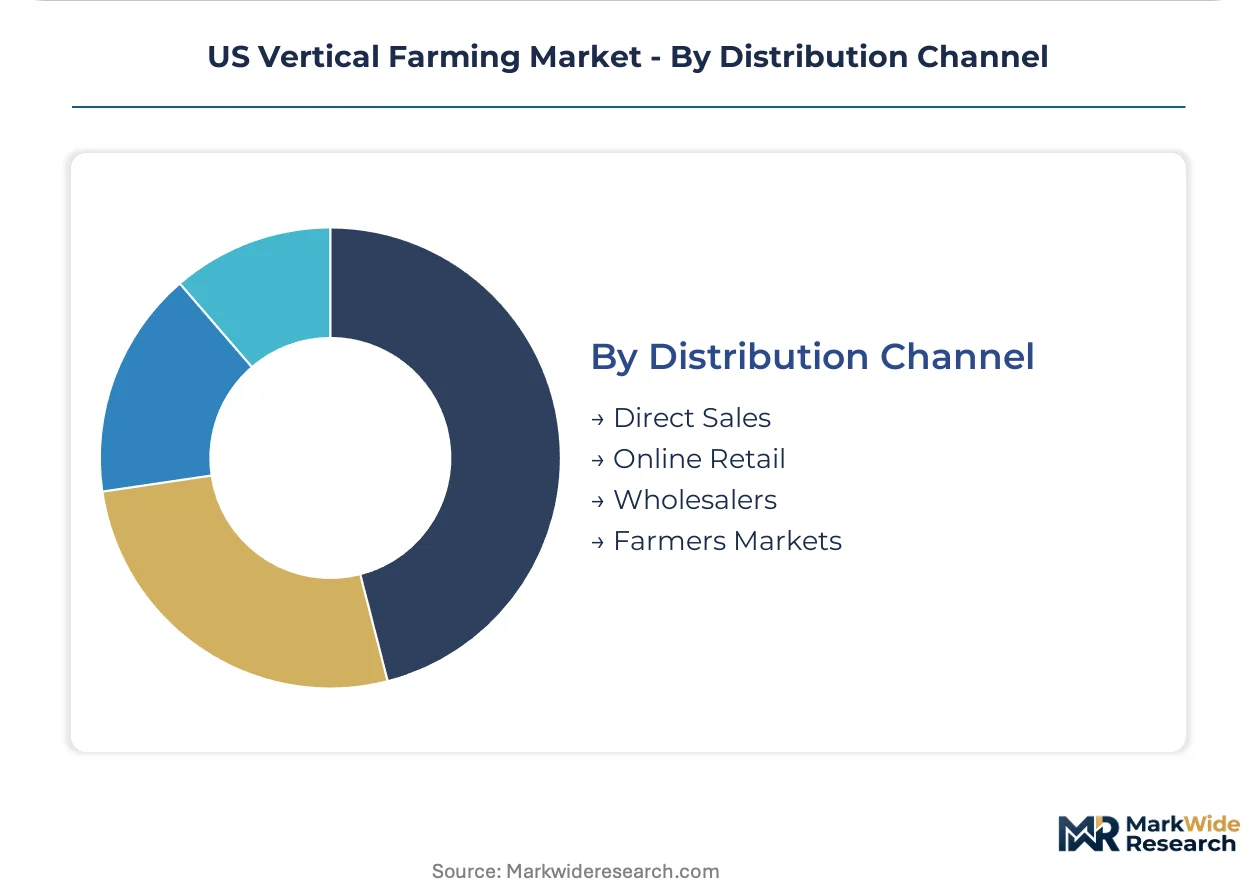
- Direct Sales:Farm-to-restaurant and farm-to-retail contracts eliminate distributor margins while requiring in-house logistics capacity. New York metropolitan operators are building dedicated delivery fleets to serve chef procurement networks, capturing premium positioning through traceability documentation and harvest-to-door timing guarantees.
- Online Retail:Subscription box services and direct-to-consumer platforms address home gardener demand with curated seedling assortments.
- Wholesalers:Traditional produce distributors provide volume aggregation but compress margins through standardized pricing.
- Farmers Markets:Seasonal booth presence builds brand recognition in local communities with limited year-round revenue contribution.
Direct sales expand fastest; wholesalers retain volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertical farming emerged from Cornell University agricultural engineering programs and Cornell Cooperative Extension trials during the early 2000s, with commercial scaling accelerating after 2010 as LED cost curves collapsed and New York City food policy prioritized urban agriculture.
Northeast Corridor
New Jersey and New York metropolitan procurement networks command the densest facility concentration, with Newark and Queens hosting multi-acre aeroponic operations supplying Kroger and Whole Foods Market. New York State's energy-use reporting requirements for controlled-environment agriculture and New Jersey's water discharge standards are accelerating compliance investments ahead of anticipated rule finalization. The Port Newark-Elizabeth Marine Terminal corridor anchors regional distribution infrastructure for same-day produce delivery to Manhattan restaurant groups.
California
Central Valley water scarcity and Sacramento's carbon accounting mandates are redirecting capital toward closed-loop indoor systems in Stockton and Sacramento metropolitan zones. The California Energy Commission's agricultural electrification incentives subsidize solar-integrated facility designs that reduce grid dependency. Bay Area chef procurement networks in San Francisco and Oakland are contracting directly with Salinas Valley-adjacent operators for heritage herb traceability documentation.
Illinois
Chicago's food desert designation under USDA urban agriculture programs unlocks federal infrastructure subsidies for indoor farming deployment in South and West Side neighborhoods. The Illinois Department of Agriculture supplements federal frameworks with facility licensing pathways specific to soilless cultivation. Bedford Park and Bridgeview industrial zones host automated hydroponic facilities optimized for rapid-turnover leafy green production serving Jewel-Osco and Mariano's procurement teams.
Texas
Dallas-Fort Worth and Houston metropolitan expansion presents white-space deployment potential where year-round outdoor agriculture reduces competitive pressure from field-grown supply. The Texas Commission on Environmental Quality's evolving water discharge standards favor closed-loop nutrient recovery architectures. Austin's restaurant density and sustainability-mandated hospitality groups are piloting direct farm-to-chef contracts for premium herb categories bypassing traditional wholesale channels.
Florida
Miami-Dade and Orlando metropolitan zones leverage subtropical climate for hybrid greenhouse-vertical facility designs that reduce cooling energy intensity. The Florida Department of Agriculture and Consumer Services' urban agriculture grant programs subsidize demonstration-scale systems in designated food access priority areas. Tampa Bay logistics infrastructure supports regional distribution to Publix Super Markets procurement networks seeking verified low-carbon cultivation credentials.
US Vertical Farming Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered structure where facility ownership separates from technology licensing and brand operations. The vendor base clusters around three strategic archetypes: integrated operators controlling cultivation through retail distribution, technology licensors monetizing platform patents without production assets, and regional specialists capturing metropolitan procurement relationships through hyperlocal supply positioning. Consolidation pressure concentrates among mid-scale operators lacking differentiated automation architectures or direct channel access. Dominant competitive moves include strategic partnerships with grocery retailers for dedicated shelf space and backward integration into LED component sourcing to reduce supply concentration risk.
Within the integrated operator tier, AeroFarms, Bowery Farming, and Plenty Unlimited exemplify capital-intensive facility deployment with proprietary cultivation platforms. AeroFarms occupies a position emphasizing aeroponic water efficiency for regulatory compliance headroom in discharge-sensitive watersheds. Bowery Farming anchors the automated operating system archetype where software control over environmental variables compresses growth cycle variability. Plenty Unlimited sits within the large-scale regional distribution vector with facility architectures designed for volume contracts with national grocery chains. These three entities collectively represent the dominant competitive positioning against which technology licensors and regional specialists calibrate market entry strategies.
| Leading Market Players |
|---|
| AeroFarms |
| Bowery Farming |
| Plenty Unlimited |
| Freight Farms |
| BrightFarms |
| Gotham Greens |
| 80 Acres Farms |
| American Hydroponics |
| Local Bounti |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of LED horticultural lighting and nutrient solution formulations anchors supply position while insulating integrated operators from component price volatility that compresses margins for asset-light competitors. This vertical control over critical inputs enables premium positioning in restaurant direct channels where traceability documentation commands menu price premiums.
Pricing Analysis
Contract-based long-term offtake agreements with Kroger and Whole Foods Market procurement teams dominate volume transactions, while spot sales through chef networks capture premium positioning for heritage herb varieties. Price differentiation separates USDA Organic-certified produce from conventional soilless cultivation, with carbon accounting credentials in California and New York creating additional tier separation. Cost compression in standard leafy green categories is intensifying because electricity pricing fluctuations in deregulated state markets strain 24/7 climate control operations. Retail grocery chains exhibit highest price sensitivity due to standardized pack size requirements, while sustainability-mandated restaurant groups absorb premiums for single-source traceability.
Supply Chain Analysis
Direct-to-restaurant channels handle hyperscale buyer demand from New York and Chicago metropolitan chef networks, bypassing traditional produce wholesalers for premium herb categories. Component sourcing concentrates in China for horticultural-grade LED substrates, the Netherlands for precision climate control systems, and domestic suppliers for modular grow rack fabrication. Raw material dependencies include phosphor-converted LED diodes, ion-specific nutrient formulations, and food-grade growing substrates. Single-source vulnerability in semiconductor-grade LED driver chips creates procurement bottlenecks when automotive and consumer electronics demand surges. Distribution runs through regional grocery distributors for retail volume, with dedicated delivery fleets serving farm-to-table restaurant contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US vertical farming market functions as a regulatory compounder where EPA water-efficiency mandates and USDA urban agriculture incentive programs structurally expand addressable demand for closed-loop cultivation systems.
For Market Incumbents: Lock in backward integration into LED component sourcing to reduce supply concentration risk from narrow domestic horticultural lighting suppliers. Defend market position by accelerating compliance investments ahead of anticipated New York and New Jersey state-level rule finalization on energy-use reporting and water discharge standards. Prioritize automation architecture R&D to compress the controlled environment agronomy talent gap that strains emerging operator budgets.
For New Entrants and Emerging Players: The price-point gap between premium chef-network herbs and economy-tier retail leafy greens creates entry opportunity for mid-market positioning with heritage variety differentiation. Target Sun Belt expansion in Dallas-Fort Worth and Houston metropolitan zones where year-round outdoor agriculture reduces competitive pressure from field-grown supply. Deploy containerized modular systems for six-month activation timelines versus traditional two-year facility commissioning.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional specialists because consolidation pressure concentrates among operators lacking differentiated automation architectures or direct channel access. Long-term viability hinges on platform standardization across cultivation technology, environmental control software, and traceability documentation systems. Monitor state-level carbon accounting rule finalization in California and New York as inflection indicator for locational competitiveness premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Sourcing | Captive supply of horticultural-grade lighting reduces procurement bottlenecks from concentrated semiconductor suppliers. |
| Chef Network Direct Contracts | Farm-to-table traceability documentation captures menu price premiums from sustainability-mandated restaurant groups. |
| Modular Grow Rack Deployment | Phased capital expenditure compresses facility commissioning from twenty-four months to six-month activation windows. |
| State Carbon Accounting Compliance | Verified low-carbon cultivation credentials create locational advantage in California and New York procurement. |
| Automation Architecture Licensing | Technology monetization without production assets enables asset-light expansion across metropolitan corridors. |
Study Parameters
Direct dialogue with vertical farming operations executives, controlled environment agronomists, grocery retail procurement managers, restaurant sustainability directors, and LED component suppliers grounds qualitative assessment in practitioner perspective. Secondary validation draws from USDA urban agriculture program filings, EPA water discharge standard dockets, state energy commission agricultural electrification records, and SEC filings from publicly traded agritech entities. Bottom-up facility capacity aggregation triangulates against top-down metropolitan produce demand modeling across the analysis window.
Bottom-up segmentation by cultivation technology, end-user channel, and product type feeds into metropolitan corridor demand density mapping. The analytical lens weights hydroponics versus aeroponics adoption curves, retail versus restaurant channel mix shifts, and leafy greens versus herb revenue concentration across the projection horizon. CAGRs derive from facility commissioning timelines, LED cost curve trajectories, and regulatory incentive program budget authorizations. Forecast inputs incorporate electricity pricing volatility assumptions and state-level organic certification pathway resolutions.
Caveats apply where EPA mandate implementation delays, LED supply chain disruptions, or organic certification ambiguity could materially shift the outlook for capital deployment timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Global Grow Lights Market