
 Spain Commercial Green House Market | 2026-2036
Spain Commercial Green House Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Commercial Green House Market Insights
Modular greenhouse configurations is expanding buyer flexibility across Spain's commercial sector. Richel Group SA leverages its European manufacturing footprint to supply scalable bay-width systems. Certhon anchors its position through integrated climate-computer and screening technology. PLASTIKA KRITIS S.A. specializes in durable polyethylene film formulations tailored to Almería's intense UV exposure.
Spain commercial green houses are engineered steel-and-glazing or polymer-clad structures with climate-controlled interiors, typically spanning 3-12 meters in gutter height, designed to optimize photosynthetically active radiation while managing vapor pressure deficit for intensive crop production. Their primary commercial purpose is to decouple vegetable and ornamental production from seasonal weather variability, enabling continuous harvest cycles for supply to retail and foodservice channels. Polyethylene greenhouses occupy the dominant installed base due to lower capital intensity per hectare, while hydroponics technology captures expanding share as water stress intensifies across southern Spain. Glass greenhouse structures retain premium positioning among research institutions and high-value flower producers where precise environmental control justifies elevated construction costs.
Spain's Ministry of Agriculture enforces phytosanitary protocols under EU Plant Health Law, while BREEAM and LEED certification standards increasingly influence greenhouse construction specifications for export-oriented agribusinesses seeking sustainability credentials. The EU Green Deal's Farm to Fork strategy tightens pesticide reduction targets, directly shaping integrated pest management technology adoption timelines. Stakeholders must monitor evolving national water-rights allocations under drought contingency plans, as irrigation access constraints will determine viable expansion zones for new commercial greenhouse developments.
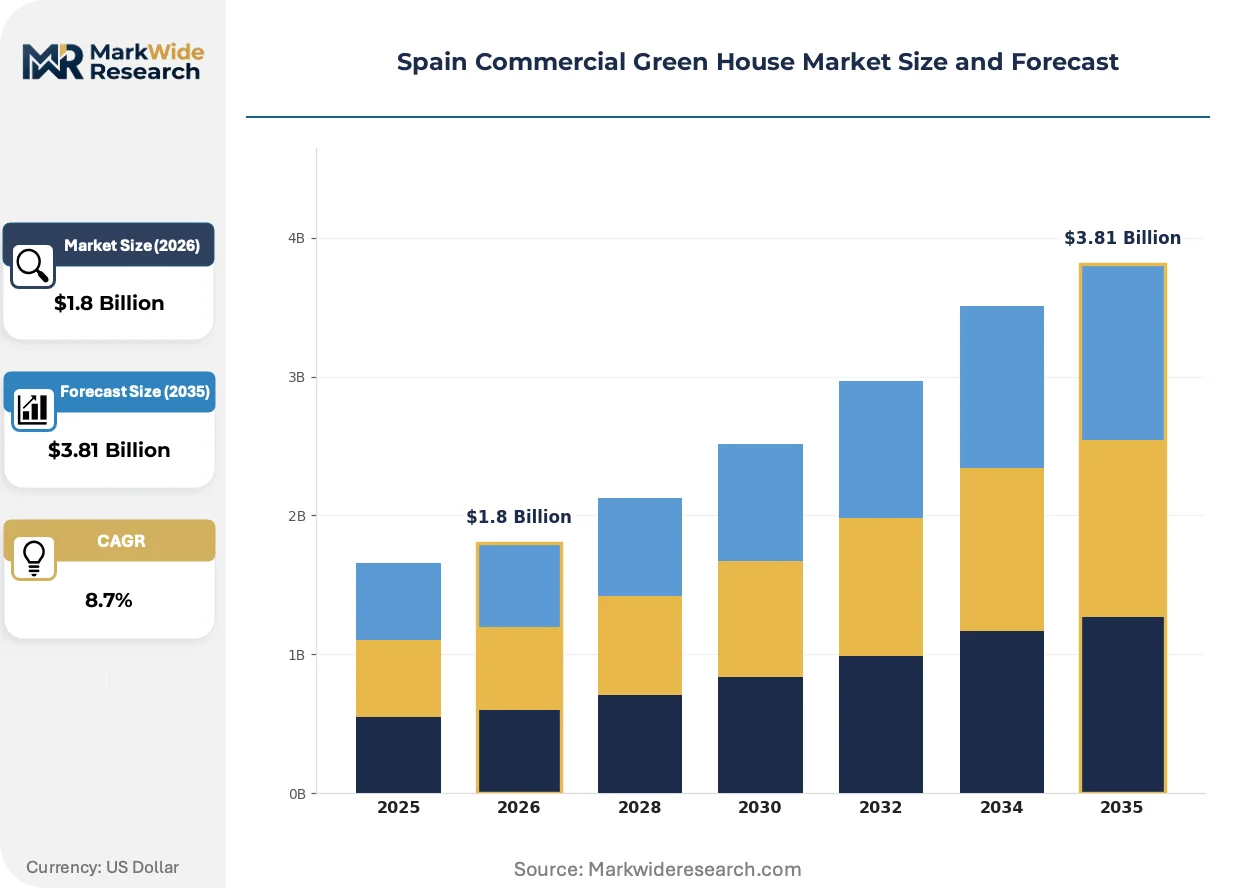
Market Dynamics
Spain's commercial greenhouse sector faces acute water stress forcing rapid automation adoption. The EU Green Deal's Farm to Fork pesticide reduction mandates are compressing technology refresh cycles across Almería's polyethylene-dominated installed base.
Growth Catalysts
- EU Green Deal pesticide targets:The Farm to Fork strategy mandates 50% pesticide reduction by 2030, accelerating integrated pest management technology deployment across Andalusian operations.
- Almería cluster concentration:Dense greenhouse agglomeration enables shared logistics infrastructure, specialized maintenance services, and consolidated input procurement for operators.
- Hydroponics substrate systems:Closed-loop irrigation technology reduces water consumption intensity, aligning with Plan Nacional de Regadíos modernization mandates for southern Spain.
Market Restraints
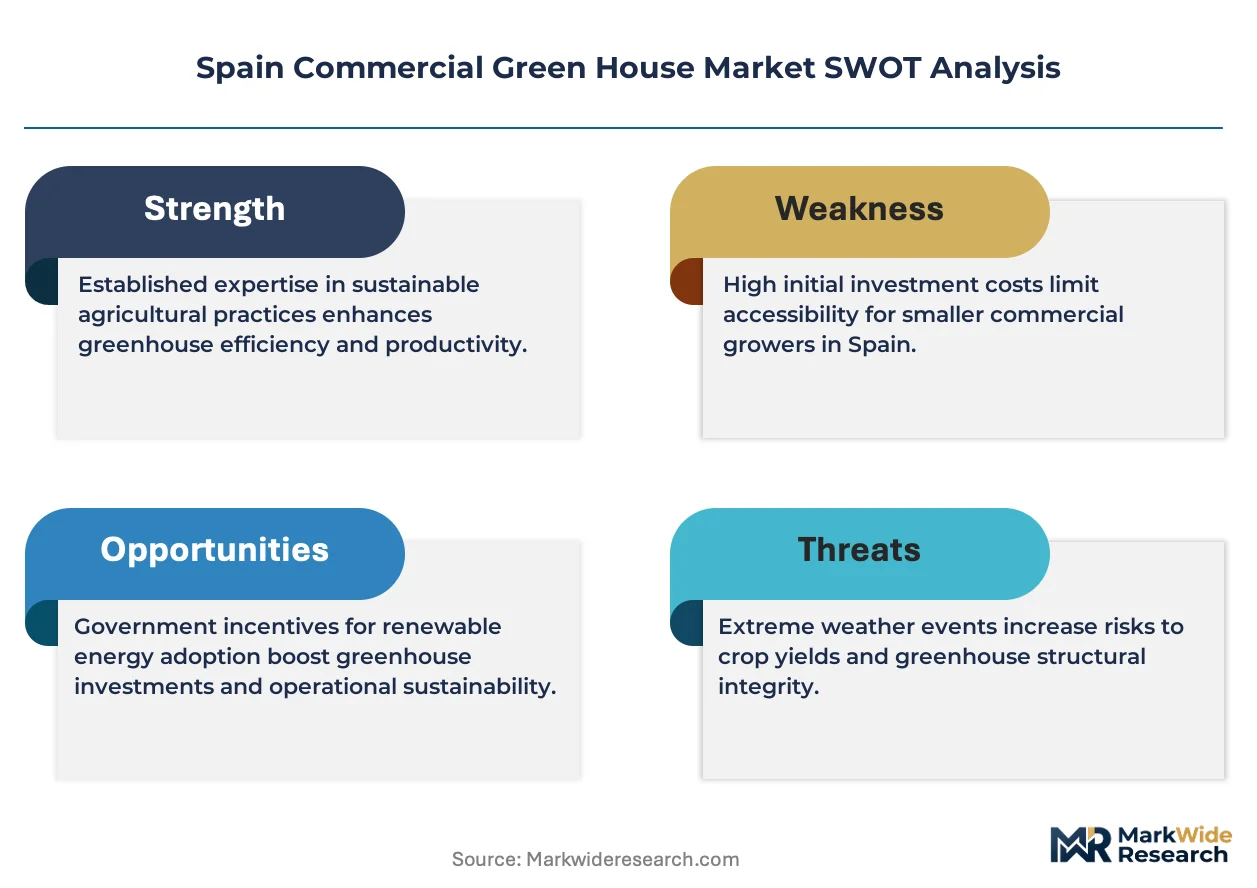
- Steel and polymer input volatility:Galvanized steel frame costs fluctuate with energy-intensive European metallurgy output, compressing project IRRs for new greenhouse construction.
- Glass structure capex barrier:Precise climate control glass systems require capital intensity three to four times polyethylene equivalents, limiting penetration beyond research and floriculture segments.
- Drought contingency water rights:National irrigation allocation reassignments under emergency protocols threaten expansion viability in water-stressed Guadalquivir basin zones.
Strategic Opportunities
- Andalusian automation retrofit wave:Aging polyethylene infrastructure across Almería and Granada provinces presents climate-computer and screening technology insertion opportunities.
- BREEAM-LEED certification premium:Export-oriented agribusinesses pursuing sustainability credentials create specification pull for energy-efficient glazing and renewable-integrated designs.
- Fresh produce retail consolidation:Year-round sourcing commitments from domestic supermarket chains concentrate procurement volume, favoring scaled greenhouse operators with volume guarantee contracts.
Industry Challenges
- Climate technician scarcity:Specialized labor for automated irrigation and environmental control system maintenance remains concentrated among veteran operators, constraining expansion velocity.
- Phytosanitary compliance timelines:EU Plant Health Law enforcement by Spain's Ministry of Agriculture extends certification cycles for new crop varieties and input substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Commercial Green House Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Structure Type: Glass Greenhouses, Polyethylene Greenhouses, PEG Greenhouses, Shade Houses Crop Type: Tomatoes, Cucumbers, Peppers, Flowers Technology: Hydroponics, Aeroponics, Soil-Based Systems, Integrated Pest Management End User: Farmers, Agribusinesses, Research Institutions, Educational Establishments |
| Companies Covered | Richel Group SA, Certhon, Logiqs, Priva, Ridder Group, HortiMaX, PLASTIKA KRITIS S.A., Sotrafa, Luiten Greenhouses, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Commercial Green House Market Trends and Innovations
Automation and resource efficiency imperatives are compressing technology adoption timelines across Spain's greenhouse infrastructure. Three interconnected developments are restructuring competitive capability requirements.
Climate-computer integrated screening systems are rewriting operational benchmarks for vapor pressure deficit management. Large-scale vegetable producers in Almería are deploying these systems at replacement cycle acceleration, enabling precise humidity control that compresses disease pressure windows and reduces chemical intervention frequency.
EU F-Gas Regulation phase-down schedules are forcing refrigeration and cooling technology transitions in climate-controlled greenhouse zones. Spanish operators face equipment replacement deadlines that favor natural refrigerant alternatives, with research institution glass structures leading adoption due to precise temperature control requirements.
Retail procurement consolidation is concentrating volume commitments toward domestic greenhouse operators with traceability certification. Fresh produce chains are displacing seasonal import reliance with year-round supply contracts, a pattern most visible in Madrid and Barcelona distribution hub catchments where logistics proximity commands premium allocation.
Spain Commercial Green House Market Segmentation
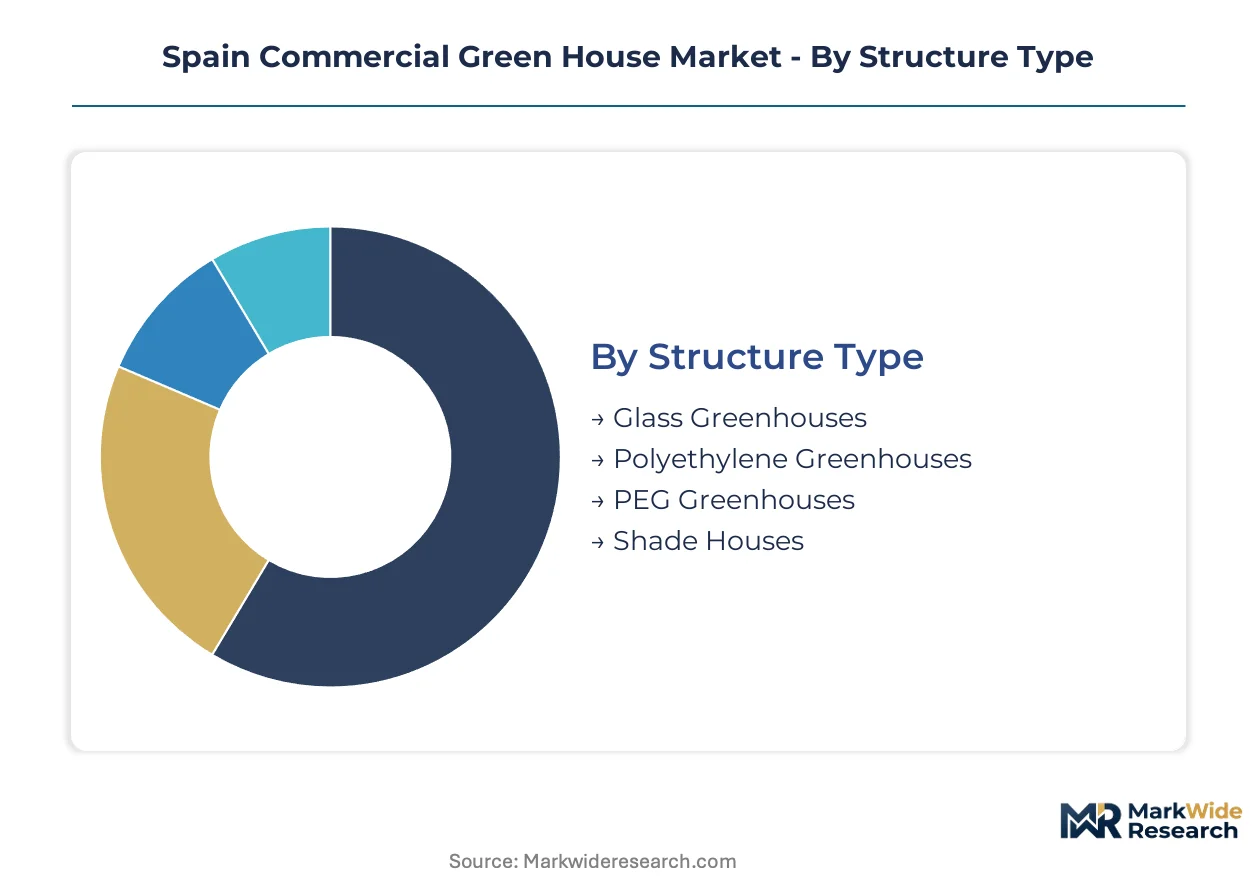
Structural configuration, crop specialization, and automation intensity define competitive positioning across Spain's greenhouse sector. Each segmentation axis carries distinct capital requirements, regulatory exposure, and margin profiles that determine operator viability in water-stressed southern provinces.
Structure Type:
Material composition and cladding technology dictate thermal performance, capital intensity, and climate control precision across Spanish installations.
- Glass Greenhouses:Steel-framed structures with tempered glass cladding deliver superior light transmission and precise vapor pressure deficit management. Research institutions in Valencia and high-value floriculture operations around Madrid concentrate demand here, driven by EU F-Gas Regulation compliance requirements for temperature-sensitive environments.
- Polyethylene Greenhouses:Galvanized steel skeletons sheathed in UV-stabilized polyethylene film dominate Almería's installed base due to capital efficiency per hectare. Andalusian vegetable producers favor these structures for rapid deployment cycles, though rising steel input volatility compresses project returns.
- PEG Greenhouses:Polycarbonate-ethylene-glass hybrid configurations balance durability with moderate capital outlay. Emerging adoption in Granada province targets operators seeking polyethylene replacement without full glass cost exposure.
- Shade Houses:Minimal-structure netting systems provide basic solar radiation moderation for nursery operations and hardening-off phases. Extensive use across Murcia's seedling propagation facilities addresses seasonal intensity management.
Polyethylene greenhouses lead on scale across southern Spain; PEG configurations gain momentum among mid-scale operators seeking structural upgrade pathways.
Crop Type:
Biological requirements for temperature, humidity, and photoperiod drive structural specification and technology stacking decisions.
- Tomatoes:Long-cycle vine crops demand precise climate-computer integration for year-round production. Almería's cooperative networks have consolidated tomato specialization, leveraging hydroponic substrate systems to meet retailer volume commitments for indeterminate varieties.
- Cucumbers:Rapid-turnover climbing crops favor polyethylene structures with automated trellis systems. Intensive production clusters in El Ejido and Níjar municipalities supply Barcelona and Madrid distribution hubs through consolidated logistics.
- Peppers:Thermophilic fruiting vegetables require elevated temperature setpoints that strain cooling infrastructure. Greenhouse operators in southwestern Granada specialize in pepper production, capitalizing on margin premiums for colored specialty varieties.
- Flowers:Ornamental production demands glass or advanced PEG structures for photoperiod manipulation and disease exclusion. Valencia's floriculture belt maintains concentration here, serving European wholesale auction channels.
Tomatoes command the largest cultivated hectare footprint; peppers deliver the steepest expansion trajectory among vegetable categories.
Technology:
Production system architecture determines water efficiency, labor intensity, and phytosanitary compliance capability.
- Hydroponics:Closed-loop substrate systems with drip irrigation and nutrient solution recirculation reduce water consumption intensity. Plan Nacional de Regadíos modernization subsidies accelerate adoption across Andalusian polyethylene retrofits.
- Aeroponics:Root misting configurations maximize oxygen availability and minimize substrate costs. Limited penetration in Spain due to technical complexity and climate technician scarcity constraining operational reliability.
- Soil-Based Systems:Traditional ground cultivation persists in older installations and organic-certified operations. Declining share as water stress intensifies and EU Green Deal pesticide reduction targets pressure chemical intervention frequency.
- Integrated Pest Management:Biological control and predator insect deployment systems address Farm to Fork pesticide reduction mandates. Rapid adoption trajectory across export-oriented agribusinesses seeking BREEAM-LEED certification credentials.
Hydroponics leads on installed capacity expansion; integrated pest management climbs fastest among compliance-driven technology investments.
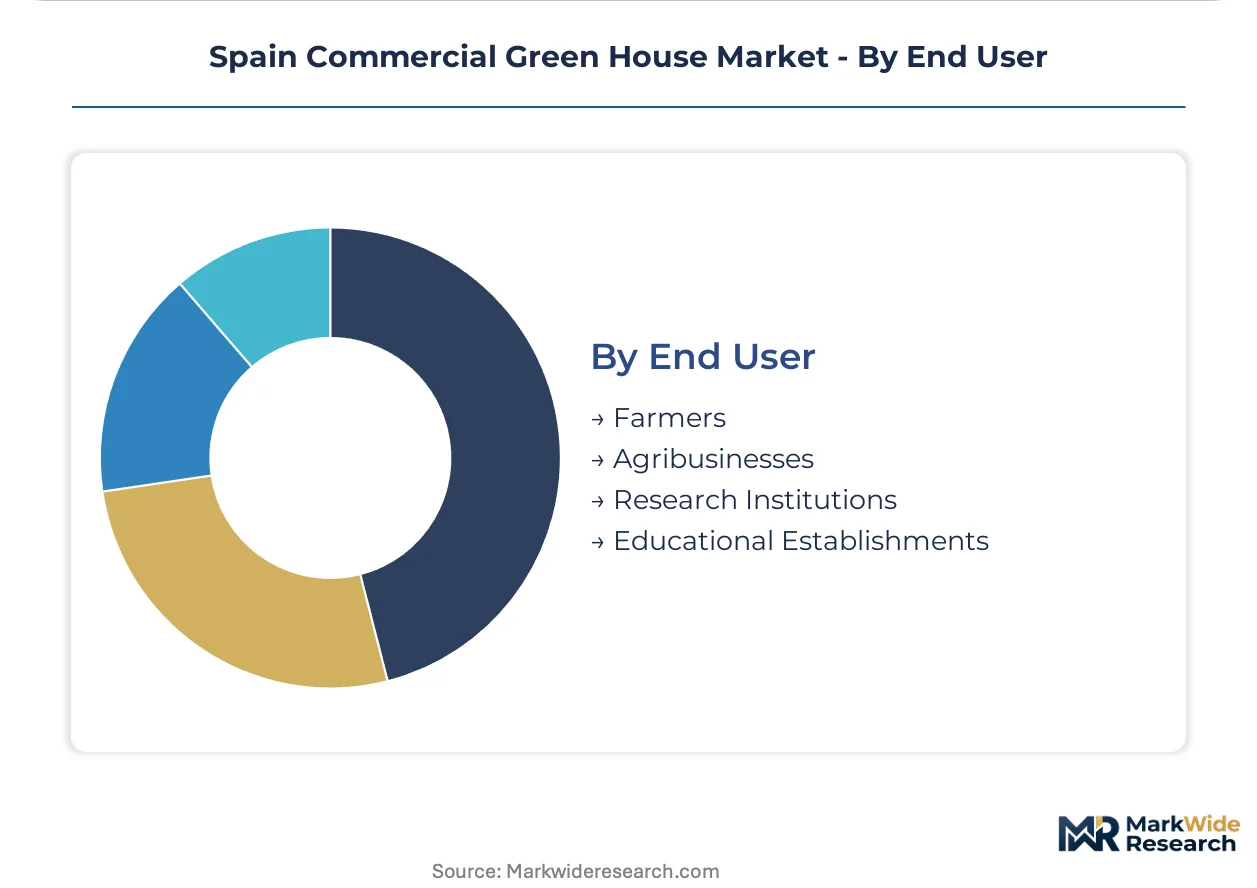
End User:
Organizational scale and strategic orientation shape procurement patterns and technology adoption timelines.
- Farmers:Family-operated holdings under 5 hectares dominate Almería's polycarbonate and polyethylene base. Cooperative membership enables shared input procurement and consolidated retail contract negotiation.
- Agribusinesses:Scaled corporate operators manage multi-hectare installations with in-house technical teams. These entities drive climate-computer and screening technology deployment, securing volume guarantee contracts with Madrid and Barcelona supermarket chains.
- Research Institutions:Universities and agricultural technology centers operate precision-controlled glass structures for cultivar development. CSIC and regional agricultural research stations anchor demand for advanced environmental control systems.
- Educational Establishments:Vocational training centers and agricultural schools maintain demonstration greenhouses for workforce development. Limited commercial output but significant technology showcase function for supplier marketing.
Agribusinesses lead on technology investment scale; research institutions set specifications that diffuse to commercial operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's commercial greenhouse industry traces its modern lineage to Almería's 1960s agricultural transformation, when polyethylene-clad structures converted arid coastal plains into Europe's winter vegetable basket. This Andalusian foundation established the technical and commercial templates now diffusing across Iberian sub-regions.
Andalusia
Almería's El Ejido-Níjar corridor hosts Europe's densest greenhouse agglomeration, with over 30,000 hectares under polyethylene cover. The Junta de Andalucía administers Plan Nacional de Regadíos modernization subsidies that accelerate automated irrigation retrofits. El Ejido's cooperative networks consolidate procurement for tomato and cucumber specialization serving Madrid and Barcelona distribution hubs.
Murcia
Seedling propagation and early-stage nursery operations concentrate across Murcia's Campo de Cartagena. Regional water stress has triggered strict abstraction limits under the Confederación Hidrográfica del Segura drought protocols. Molina de Segura hosts specialized shade house infrastructure for vegetable transplant hardening.
Valencia
Floriculture and ornamental production dominate Valencia's greenhouse footprint, with glass structures prevailing for photoperiod-sensitive crops. The Generalitat Valenciana enforces EU F-Gas Regulation compliance timelines for climate-controlled installations. L'Alcúdia and Alzira anchor the province's flower auction supply chains.
Catalonia
Research-oriented glass greenhouses cluster around Barcelona's agricultural technology corridor, serving CSIC stations and university breeding programs. The Generalitat de Catalunya coordinates with Spain's Ministry of Agriculture on phytosanitary certification for export-bound propagation material. Maresme coastal municipalities host demonstration facilities for climate-computer technology diffusion.
Madrid
Retail procurement consolidation drives demand proximity in Madrid's metropolitan greenhouse belt, with agribusinesses securing volume guarantee contracts from domestic supermarket chains. The Comunidad de Madrid's agricultural department monitors water rights reassignments under Tajo-Segura transfer contingency protocols. Aranjuez and surrounding municipalities supply year-round leafy greens to capital distribution centers.
Spain Commercial Green House Market Competitive Landscape
The competitive structure tilts toward European manufacturing specialists with scalable bay-width system capabilities. Market concentration remains moderate, with Dutch and French engineering groups holding technology leadership positions alongside Greek polymer specialists. Three archetypes dominate: integrated climate-technology providers, structural fabricators with regional manufacturing footprints, and film formulation specialists attuned to Mediterranean UV exposure. Competitive moves center on automation retrofit partnerships and sustainability certification alignment for export-oriented agribusinesses.
Among integrated system providers, Certhon and Priva exemplify the climate-technology archetype, anchoring positions through environmental control hardware and software integration. Richel Group SA represents the structural fabrication tier with French manufacturing origins. PLASTIKA KRITIS S.A. occupies the specialized materials segment, with Greek corporate structure signaling polymer formulation expertise. These three collectively span the value chain from cladding durability to precision climate management.
| Leading Market Players |
|---|
| Richel Group SA |
| Certhon |
| Logiqs |
| Priva |
| Ridder Group |
| HortiMaX |
| PLASTIKA KRITIS S.A. |
| Sotrafa |
| Luiten Greenhouses |
| Others |
Pricing and Supply Chain Analysis
Backward integration into climate-computer hardware and automated screening systems anchors Certhon's supply position and pricing power across Almería's retrofit wave. This captive production capability insulates margin structures from galvanized steel volatility while commanding premium positioning among agribusinesses pursuing BREEAM-LEED certification pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Spanish greenhouse market. Premium tier captures glass-structured installations with integrated climate-computers serving research institutions and floriculture exporters; standard tier dominates polyethylene retrofits with hydroponic substrate systems; economy tier covers basic shade-house configurations for nursery propagation. Price differentiation hinges on certification grade and automation intensity. Cost compression in the standard tier is intensifying because Plan Nacional de Regadíos subsidy dependencies create procurement timing volatility. Agribusinesses with volume guarantee contracts exhibit lowest price sensitivity; family-operated holdings under five hectares demonstrate highest elasticity.
Supply Chain Analysis
Freight cost differentials from Dutch engineering hubs to Almería versus French manufacturing corridors to Granada reshape supplier competitive positioning. Galvanized steel frames draw from Spanish and Italian metallurgy centers; UV-stabilized polyethylene film sources from Greek and Turkish polymer specialists; climate-control hardware hinges on Dutch and Belgian automation clusters. Single-source vulnerability concentrates in precision sensor arrays for vapor pressure deficit management. Distribution runs through Madrid and Barcelona procurement hubs consolidating volume commitments for domestic retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal Farm to Fork pesticide reduction mandates accelerate technology refresh cycles across Andalusia's installed base.
For Market Incumbents: Deepen climate-computer integration partnerships with Almería's cooperative networks to lock in retrofit replacement cycles before subsidy windows narrow. Acquire specialized maintenance capabilities addressing climate technician scarcity constraining competitor expansion velocity. Cement position through Plan Nacional de Regadíos-aligned automation roadmaps that synchronize with drought contingency water rights reassignments. For New Entrants and Emerging Players: The mid-tier pricing gap between premium glass structures and economy polyethylene configurations opens viable positioning for PEG hybrid systems targeting Granada province operators. Focus white-space capture on automated irrigation retrofits for aging Almería infrastructure where incumbent service capacity saturates. Pursue go-to-market alignment with Junta de Andalucía subsidy administration channels accelerating modernization procurement timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale agribusiness aggregators because fragmented family-operated holdings under five hectares lack standalone capital access for climate-computer deployment. Target acquisition archetypes include cooperative-adjacent operators with volume guarantee contracts to Madrid and Barcelona retail chains. Watch for inflection where drought contingency protocols trigger water rights reassignments that strand non-automated capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Computer Retrofit Partnership | Locks in replacement cycles across Almería's aging polyethylene base before subsidy expiration. |
| Integrated Pest Management Certification | Aligns with EU F-Gas Regulation compliance timelines for export-oriented agribusinesses. |
| Hydroponic Subsystem Integration | Reduces water consumption intensity qualifying operators for Plan Nacional de Regadíos modernization funds. |
| Cooperative Network Consolidation | Concentrates procurement volume securing preferential pricing from Dutch automation suppliers. |
| BREEAM-LEED Specification Alignment | Captures sustainability premium from retail chains displacing seasonal import reliance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window combining primary engagement with greenhouse operators, cooperative procurement managers, climate-system technicians, and agricultural department officials with secondary validation against EU F-Gas Regulation filings, Plan Nacional de Regadíos subsidy disbursement records, Junta de Andalucía agricultural statistics, and customs data for greenhouse technology imports. Bottom-up installation counts triangulated against top-down agribusiness revenue disclosures.
Comparable-period anchoring established baseline structural configurations and technology penetration rates before modeling expansion across the projection horizon. Segmentation dimensions spanned structure type, crop specialization, automation intensity, and end-user organizational scale. CAGRs derived from regression analysis of historical subsidy-driven procurement cycles and water stress acceleration patterns. Forecast inputs incorporated drought contingency protocol triggers and retail procurement consolidation timelines.
Caveats apply where drought contingency water rights reassignments or EU Green Deal implementation delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Mexico Vertical Farming Market