
 Hydroponic System Market | 2026-2036
Hydroponic System Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroponic System Market Foresight
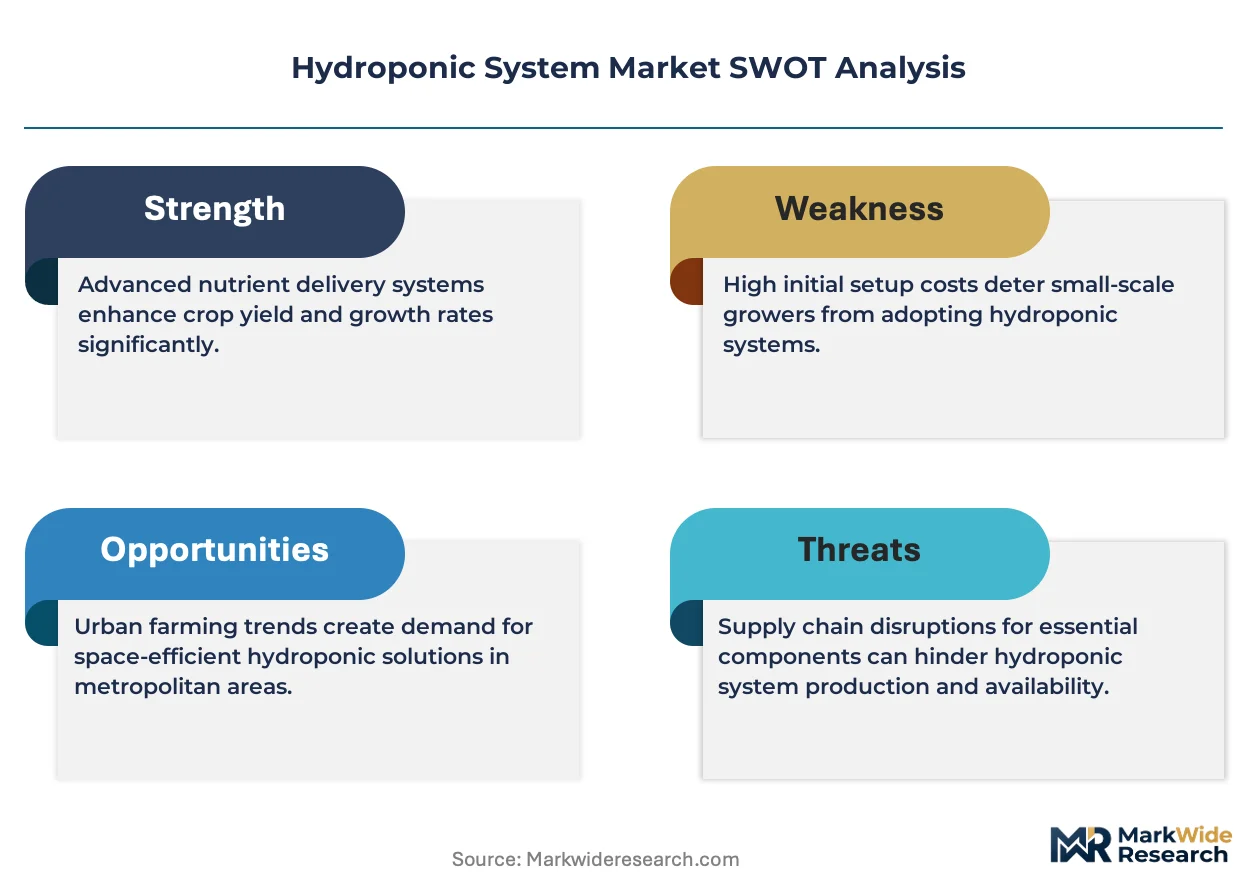
EU F-Gas Regulation is realigning the cost-of-entry calculus for climate-controlled hydroponic operations by restricting synthetic refrigerants in controlled-environment agriculture. Signify Holding leverages its Philips Horticulture LED portfolio to dominate photobiology-optimized spectrum systems for lettuce and tomato propagation. AeroFarms sustains competitive differentiation through proprietary aeroponic misting architectures that reduce water consumption versus substrate-based alternatives. ScottsMiracle-Gro anchors the consumer-facing segment with nutrient formulation and growing media bundles that lower technical barriers for home gardeners entering soilless cultivation.
Hydroponic systems constitute soilless cultivation infrastructure where plant roots contact nutrient-rich aqueous solutions directly, typically incorporating recirculating pumps, pH sensors, and dissolved-oxygen monitors to maintain root-zone parameters within species-specific ranges. Deep Water Culture systems occupy the value-engineering tier for leafy-greens production due to lower capital requirements and simpler maintenance protocols. Aeroponic configurations command premium positioning in vertical farming deployments where space constraints and harvest frequency justify elevated equipment spend. The End User segmentation reveals Agricultural Producers as the margin pool anchor, while Urban Farmers represent the fastest-expanding addressable cohort amid municipal zoning liberalization for rooftop and warehouse agriculture.
FDA produce safety rules shape domestic equipment specifications for US-based commercial operators, while REACH chemical compliance governs nutrient additive formulations across European installations. The USDA organic certification debate over hydroponic eligibility continues to influence producer technology choices and market access pathways. Stakeholders must monitor evolving water-rights adjudication and building-code classifications for indoor agriculture, as these determinations will structure financing availability and insurance underwriting for facility-scale deployments.
Market Dynamics
Water-scarcity mandates and LED spectrum optimization are compressing payback periods for capital-intensive hydroponic installations, redirecting procurement authority toward commercial greenhouse operators with balance-sheet capacity for automated nutrient-dosing infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic refrigerants in controlled-environment agriculture are accelerating equipment replacement cycles among Dutch and Spanish greenhouse operators.
- Urban zoning liberalization:Municipal code revisions in Singapore, Dubai, and Toronto are legalizing warehouse and rooftop agriculture, expanding addressable real estate for vertical farming deployments.
- Aeroponic misting architectures:Proprietary high-pressure nozzle systems reduce water consumption versus substrate-based alternatives, attracting sustainability-focused institutional investors.
Market Restraints
- Phosphorus and potassium input volatility:Fertilizer commodity price swings destabilize operating cost projections for nutrient-dosing-dependent facilities.
- Controller and sensor supply concentration:Precision agriculture electronics manufacturing clusters in Taiwan and South Korea create single-source vulnerability for pH and dissolved-oxygen monitoring hardware.
- USDA organic certification ambiguity:Ongoing eligibility debates over soilless cultivation restrict premium market access for hydroponic producers targeting organic price tiers.
Strategic Opportunities
- India's PLI scheme for food processing:Production-linked incentives for controlled-environment agriculture equipment manufacturing reduce landed costs for domestic greenhouse developers.
- Pharmaceutical-grade botanicals:GMP-compliant hydroponic infrastructure for active pharmaceutical ingredient cultivation commands 3-4x leafy-greens pricing.
- Direct-to-restaurant distribution:Hyperlocal harvest-to-table contracts bypass traditional produce wholesale markups in urban corridors with chef-driven procurement.
Industry Challenges
- Controlled-environment agronomist scarcity:Specialized expertise in crop-specific root-zone parameter management remains concentrated among Dutch and Israeli training institutions.
- Multi-vendor system integration:Proprietary protocols between LED manufacturers, climate controllers, and nutrient-dosing systems create commissioning delays and interoperability failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroponic System Market |
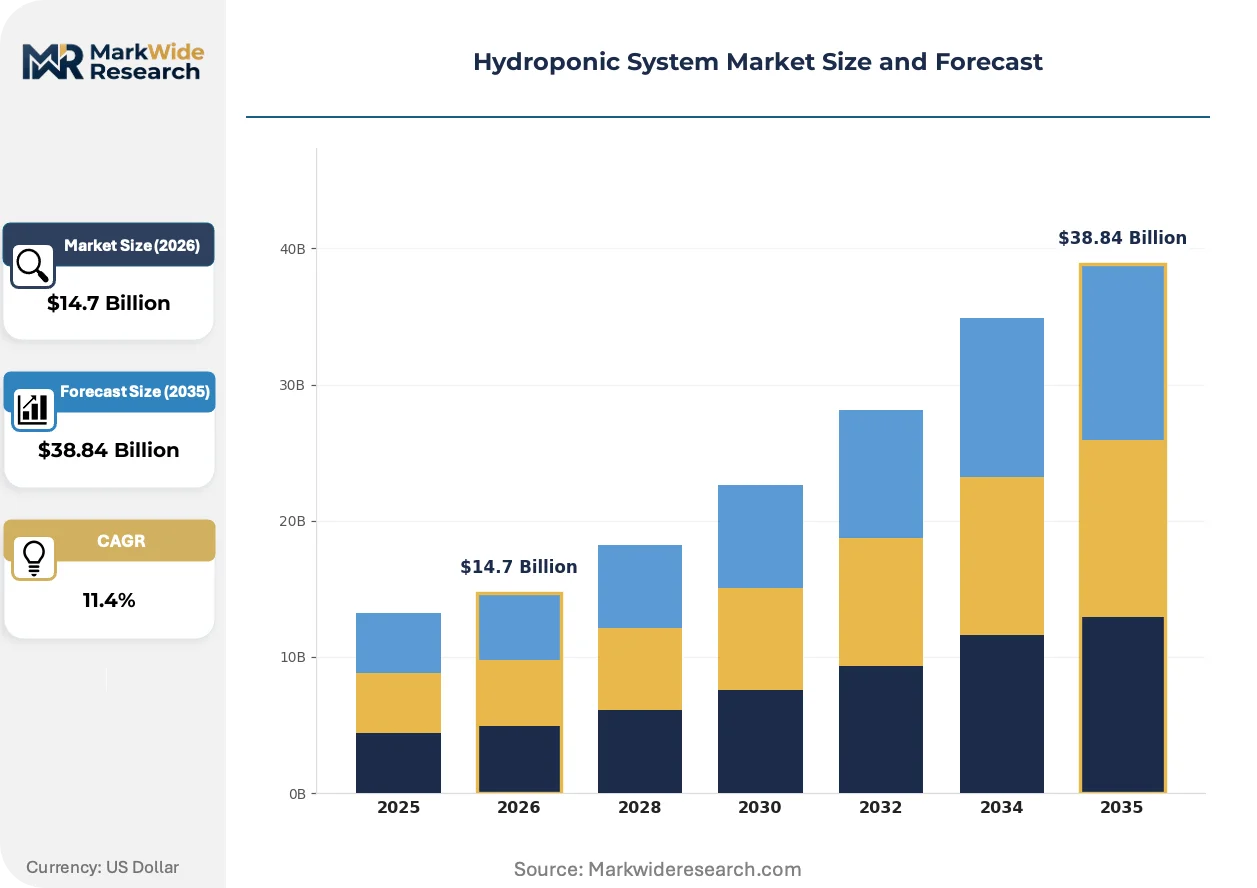
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Nutrient Film Technique, Deep Water Culture, Aeroponics, Ebb and Flow Cultivation Mode: Indoor Farming, Vertical Farming, Greenhouses, Commercial Crop Type: Lettuce, Tomatoes, Herbs, Strawberries End User: Agricultural Producers, Urban Farmers, Research Institutions, Home Gardeners |
| Companies Covered | AmHydro, Argus Control Systems Limited, Heliospectra, Signify Holding, Freight Farms, ScottsMiracle-Gro, AeroFarms, BrightFarms, Logiqs B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroponic System Market Shifts & Advancements
Spectrum-tunable LED arrays and closed-loop water recirculation are converging to redefine unit economics in soilless cultivation, with automation density now determining competitive viability more than scale alone.
Spectral tuning technology is consolidating around tunable white and far-red LED architectures that manipulate photomorphogenesis in lettuce and tomato propagation. Large-scale greenhouse operators in the Netherlands and Canada are retrofitting legacy high-pressure sodium installations at accelerated replacement cycles. This consolidation is compressing differentiation windows for lighting vendors while locking in long-term service contracts.
REACH chemical compliance in Europe is mandating full supply-chain disclosure for nutrient additive formulations, forcing reformulation of chelated micronutrient products. Commercial operators face extended product registration timelines and elevated testing expenditures. German and Dutch installations are responding by vertically integrating nutrient-mixing capabilities to control formulation transparency.
Chef-driven procurement collectives in Copenhagen, Melbourne, and San Francisco are contracting directly with vertical farms for cultivar-specific harvest schedules. Traditional produce distributors are losing volume share in premium restaurant channels. This behavioral pivot is most pronounced in municipalities with Michelin-density dining corridors and municipal food-mile reduction targets.
Hydroponic System Market Segmentation
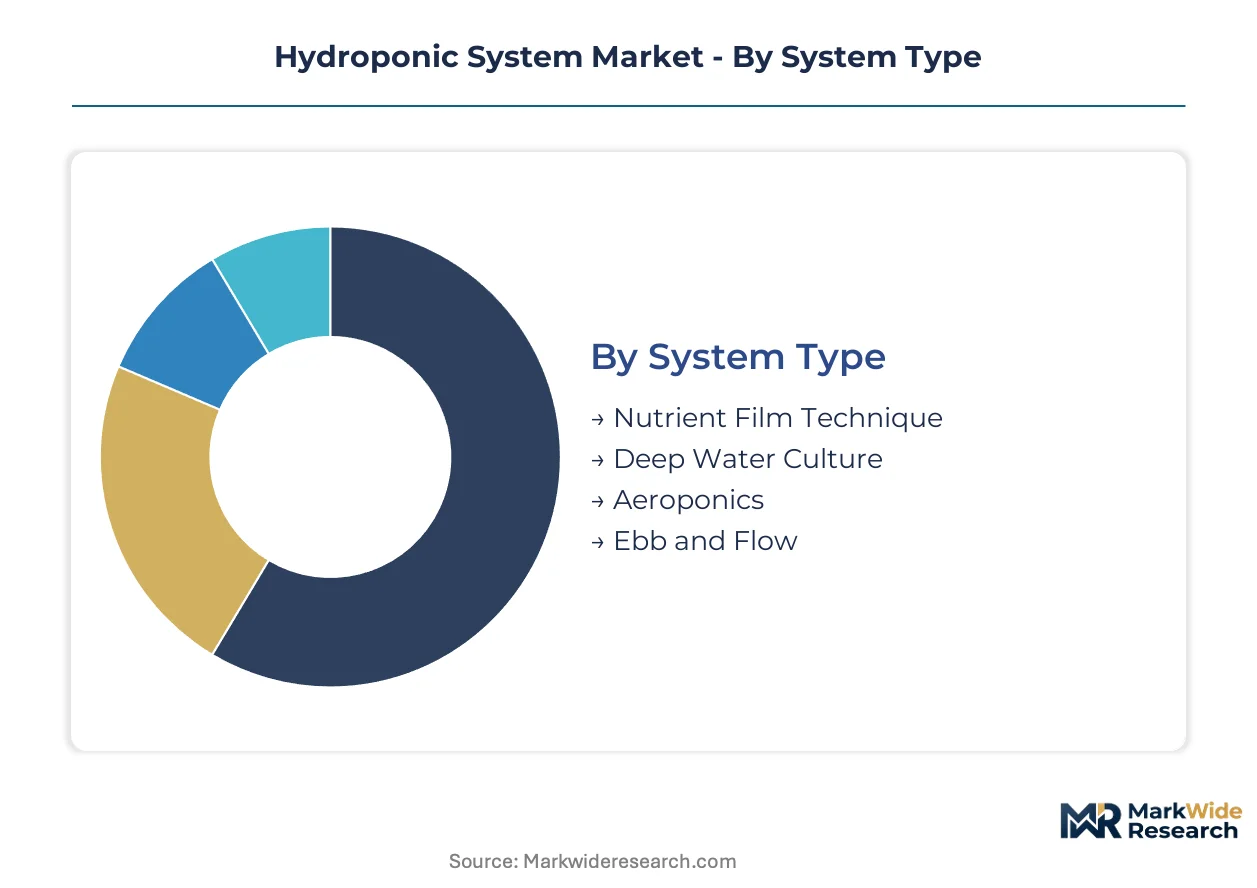
System configuration and cultivation environment dictate capital intensity, operating cost profiles, and payback timelines for hydroponic operators. Procurement patterns diverge sharply between commercial greenhouse developers optimizing for yield per square meter and home gardeners prioritizing simplicity over automation density.
System Type:
Capital deployment thresholds and water-use efficiency targets drive selection among recirculating architectures.
- Nutrient Film Technique:Thin film of recirculating solution flows continuously past suspended root matrices. Dutch greenhouse operators dominate procurement for tomato propagation, where precise flow control maximizes fruit set density per linear meter.
- Deep Water Culture:Roots suspend in oxygenated nutrient reservoirs with minimal mechanical complexity. Commercial lettuce producers in Canada favor this architecture for its lower sensor density and reduced maintenance labor requirements.
- Aeroponics:High-pressure misting delivers nutrients directly to exposed root zones. Vertical farming installations in Singapore deploy these systems where water-scarcity mandates justify premium equipment spend.
- Ebb and Flow:Periodic flooding and draining cycles alternate root exposure to solution and air. Home gardening segments prefer this intermittent operation for its forgiving parameter tolerance.
Volume sits with Deep Water Culture; growth tilts toward Aeroponics.
Cultivation Mode:
Real estate constraints and climate control requirements segment buyers by facility infrastructure investment capacity.
- Indoor Farming:Fully enclosed environments with artificial lighting and HVAC dominate urban warehouse retrofits. Toronto and Dubai municipal zoning revisions are accelerating permitting for these installations.
- Vertical Farming:Stacked cultivation layers multiply productive surface area within fixed footprints. Singapore's land-scarcity policies channel subsidies toward these space-efficient configurations.
- Greenhouses:Transparent envelope structures leverage natural light with supplemental LED arrays. Spanish and Dutch operators are retrofitting legacy structures to comply with EU F-Gas refrigerant restrictions.
- Commercial:Large-scale integrated operations combine multiple system types across dedicated zones. These facilities concentrate procurement authority with balance-sheet capacity for automated nutrient-dosing infrastructure.
Procurement volume clusters in Greenhouses; steepest expansion trajectory belongs to Vertical Farming.
Crop Type:
Harvest frequency and perishability determine automation ROI and distribution channel economics.
- Lettuce:Rapid crop cycles and consistent demand profile make this the reference crop for system validation. Copenhagen chef collectives contract directly with vertical farms for cultivar-specific harvest schedules.
- Tomatoes:Extended vine production requires trellis infrastructure and specialized pollination protocols. Dutch greenhouse operators maintain technology leadership in high-wire cultivation systems.
- Herbs:Concentrated flavor compounds and short shelf lives favor hyperlocal production. Melbourne restaurant corridors drive demand for fresh-cut basil and cilantro delivered within hours of harvest.
- Strawberries:Elevated sugar content and delicate texture challenge post-harvest handling. Japanese protected-culture specialists are developing year-round production protocols for premium varietals.
Lettuce anchors current installed base; strawberries command the steepest technology premium.
End User:
Technical sophistication and capital access stratify buyers across hobbyist, research, and commercial tiers.
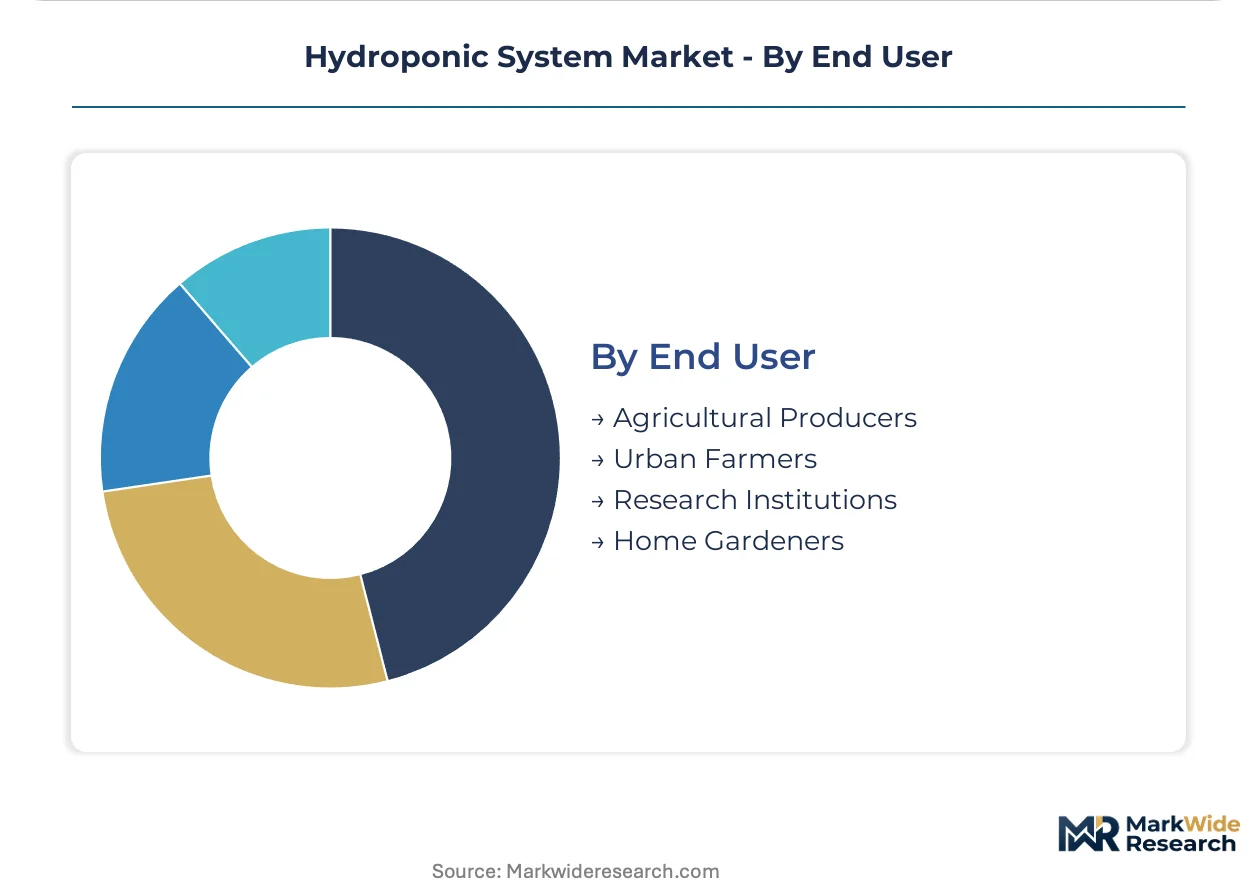
- Agricultural Producers:Professional operations with dedicated agronomy staff and multi-hectare footprints. These buyers specify integrated climate-nutrient-lighting control systems with remote monitoring capabilities.
- Urban Farmers:Municipal zoning beneficiaries operating rooftop and warehouse installations. This cohort gains share fastest where building-code classifications clarify insurance and financing treatment for indoor agriculture.
- Research Institutions:Universities and agricultural extension services validating cultivar performance under controlled conditions. Funding cycles and publication priorities drive irregular procurement patterns.
- Home Gardeners:Consumer segment prioritizing plug-and-play simplicity over yield optimization. Pre-formulated nutrient bundles and compact countertop units dominate this price-sensitive tier.
Agricultural Producers concentrate revenue; Urban Farmers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Westland's greenhouse concentration zone in the Netherlands channels the densest infrastructure investment, while Singapore's land-scarcity policies redirect procurement toward vertical farming configurations.
Netherlands
Export-oriented horticulture clusters in Westland and Aalsmeer sustain capital deployment for automated nutrient-dosing systems. EU F-Gas Regulation accelerates retrofit cycles among legacy greenhouse operators replacing synthetic refrigerant-dependent climate infrastructure. Wageningen University's agronomy programs supply specialized talent for root-zone parameter management across Dutch installations.
United States
Chef-driven procurement collectives in San Francisco and New York Metro contract directly with vertical farms for cultivar-specific harvest schedules. FDA produce safety rules shape equipment specifications for commercial operators targeting restaurant distribution channels. Greater Boston's research institutions validate crop performance protocols for controlled-environment agriculture deployments.
Singapore
Land-scarcity policies channel subsidies toward space-efficient vertical farming configurations with stacked cultivation layers. The national food agency mandates traceability standards that favor integrated climate-nutrient-lighting control systems. Urban zoning liberalization in industrial districts accelerates permitting for warehouse agriculture retrofits.
Canada
Commercial lettuce producers in Ontario and British Columbia favor Deep Water Culture architectures for lower sensor density requirements. Health Canada and PMRA chemical compliance governs nutrient additive formulations across provincial installations. Toronto's municipal zoning revisions clarify building-code classifications for rooftop agriculture insurance and financing treatment.
India
Production-linked incentives for controlled-environment agriculture equipment manufacturing reduce landed costs for domestic greenhouse developers in Gujarat and Maharashtra. FSSAI food safety standards shape nutrient formulation requirements for commercial operators. Karnataka's tech corridor attracts precision agriculture electronics assembly for pH and dissolved-oxygen monitoring hardware.
Hydroponic System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across system configuration tiers. The vendor base stratifies between lighting-centric portfolios, integrated climate control platforms, and cultivation-method specialists. Three archetypes dominate: LED spectrum optimizers, aeroponic architecture developers, and consumer-facing nutrient formulation bundlers. M&A activity concentrates on climate controller and sensor technology acquisitions, while strategic partnerships link greenhouse operators with direct-to-restaurant distribution networks.
Among North American cultivation technology developers, AeroFarms and Freight Farms exemplify vertical farming infrastructure specialists, while ScottsMiracle-Gro anchors the consumer-facing segment with simplified entry points for home gardeners. Signify Holding represents the diversified industrial conglomerate archetype leveraging legacy lighting portfolios into horticulture applications. Logiqs B.V. occupies a position among Dutch greenhouse automation specialists serving export-oriented horticulture clusters.
| Leading Market Players |
|---|
| AmHydro |
| Argus Control Systems Limited |
| Heliospectra |
| Signify Holding |
| Freight Farms |
| ScottsMiracle-Gro |
| AeroFarms |
| BrightFarms |
| Logiqs B.V. |
| Others |
Supply & Pricing Matrix
Dutch controlled-environment agronomist concentration compresses labor-cost differentials between premium automated installations and economy-tier manual systems, widening pricing-tier spreads as expertise scarcity inflates commissioning and maintenance premiums for high-complexity deployments.
Pricing Analysis
Short lead-time premiums apply to pH sensor and dissolved-oxygen monitoring hardware where Taiwanese and South Korean electronics manufacturing clusters face capacity constraints. Three-tier pricing structure across premium, standard, and economy levels separates integrated climate-nutrient-lighting platforms from modular component bundles and DIY home-gardener kits. Price differentiation hinges on automation density and after-sales service bundling, with commercial greenhouse operators least sensitive and home gardeners most responsive to sticker shock. Cost compression in economy-tier nutrient formulations is intensifying because phosphorus and potassium commodity volatility destabilizes input cost projections.
Supply Chain Analysis
Precision agriculture electronics assembly workforce availability in Taiwan, South Korea, and Karnataka's Indian tech corridor concentrates controller and sensor manufacturing. Component sourcing draws from Taiwanese semiconductor fabs for sensing chips, Dutch greenhouse automation specialists for climate controllers, and German chelated micronutrient suppliers for additive formulations. Single-source vulnerability pervades pH and dissolved-oxygen monitoring hardware where manufacturing clusters lack geographic diversification. Distribution runs through direct-to-facility channels for commercial greenhouse developers and retail garden-center networks for consumer-facing nutrient bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectrum-tunable LED arrays are displacing legacy high-pressure sodium installations across commercial greenhouse retrofits, compressing replacement cycles and redirecting procurement authority toward vendors with integrated photobiology expertise.
For Market Incumbents: Lock in long-term service contracts with Dutch and Canadian greenhouse operators retrofitting legacy installations, while acquiring climate controller specialists to close interoperability gaps with nutrient-dosing systems. LED spectrum optimizers face margin pressure from commoditization of tunable white architectures, making captive supply of proprietary photobiology IP the priority defensive lever.
For New Entrants and Emerging Players: Chef-driven procurement collectives in Copenhagen, Melbourne, and San Francisco represent the most penetrable channel partner type for cultivar-specific vertical farming contracts. White-space targets include pharmaceutical-grade botanicals cultivation and India's PLI-subsidized domestic equipment manufacturing. A direct-to-restaurant distribution angle bypasses traditional produce wholesale markups in Michelin-density dining corridors.
For Investors and Strategic Acquirers: Re-rating potential sits with aeroponic architecture developers given Singapore's land-scarcity subsidy channeling and water-mandate acceleration. Long-term viability across the five-to-ten year window favors vendors with GMP-compliant infrastructure capabilities for active pharmaceutical ingredient cultivation. The signal to watch as inflection indicator is USDA organic certification resolution, which would unlock premium price tiers for soilless producers.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Acceleration | Philips Horticulture LED portfolio captures Dutch greenhouse replacement cycles ahead of commoditization. |
| Backward Integration into Nutrient Mixing | German and Dutch operators control REACH compliance costs through in-house chelated micronutrient formulation. |
| Direct-to-Restaurant Distribution | Copenhagen chef collectives contract cultivar-specific harvest schedules bypassing traditional wholesale channels. |
| Climate Controller Acquisition | Multi-vendor system integration failures create M&A targets among sensor and dosing protocol specialists. |
| GMP-Compliant Infrastructure Buildout | Pharmaceutical-grade botanicals command three-to-four-fold leafy-greens pricing with Health Canada validation. |
Research Methodology
Multi-period observation of EU F-Gas retrofit cycles, municipal zoning liberalization timelines, and LED replacement rates anchored the trend analysis, supplemented by interviews with greenhouse automation specialists, controlled-environment agronomists, nutrient formulation chemists, and commercial produce procurement managers. Secondary validation drew from ECHA REACH registration databases, FDA produce safety guidance documents, USDA organic certification dockets, and Wageningen University agronomy research publications. Bottom-up installation tracking across Dutch, Spanish, and Canadian greenhouse clusters triangulated against top-down equipment manufacturer revenue segmentation.
Segment-weighting approaches modeled system configuration tiers, cultivation environment types, crop-specific automation requirements, and end-user technical sophistication levels across the projection horizon. CAGRs were derived from installed-base growth rates, replacement-cycle compression, and penetration assumptions for emerging vertical farming deployments. Industry-specific forecast inputs incorporated water-scarcity mandate acceleration curves and LED cost-per-micromole decline trajectories.
Caveats apply where phosphorus and potassium commodity volatility, USDA organic certification resolution, or water-rights adjudication shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding subsidy continuity in Singapore and India's PLI scheme, regulatory enforcement intensity for EU F-Gas compliance, and chef-driven procurement collective expansion in urban corridors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
US Vertical Farming Market