
 Vertical Farming Technology Market | 2026-2036
Vertical Farming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Farming Technology Market Insights
Controlled-environment agriculture in the Netherlands is decoupling from traditional seasonal constraints. AeroFarms leverages aeroponic root-misting systems to sustain year-round leafy green output. Signify Holding anchors photobiology research through its Philips horticulture LED division. Plenty Unlimited dominates large-scale facility deployment with automated nutrient delivery architecture.
Vertical farming technology encompasses soil-less cultivation systems that stack production layers in enclosed environments, typically employing hydroponic or aeroponic nutrient delivery with LED spectral tuning at 400-700 nanometer PAR ranges to optimize photosynthetic photon flux density. This infrastructure serves urban food security mandates and pharmaceutical-grade botanical sourcing. Hydroponics leads installed capacity due to lower technical barriers and established input supply chains, while aeroponics captures margin concentration through water-use efficiency premiums and pharmaceutical contract cultivation. Container farms represent the fastest-scaling product type as military, disaster-relief, and remote mining operators seek deployable food sovereignty.
The EPA regulates agricultural runoff exemptions that shape hydroponic wastewater classification, while the EU Green Deal's pesticide reduction targets redirect subsidy flows toward soil-less methods. FDA food safety modernization rules enforce hazard analysis for indoor leafy green operations. Stakeholders must monitor energy tariff structures and carbon accounting frameworks as these determine facility siting economics and offtake contract viability.
Market Dynamics
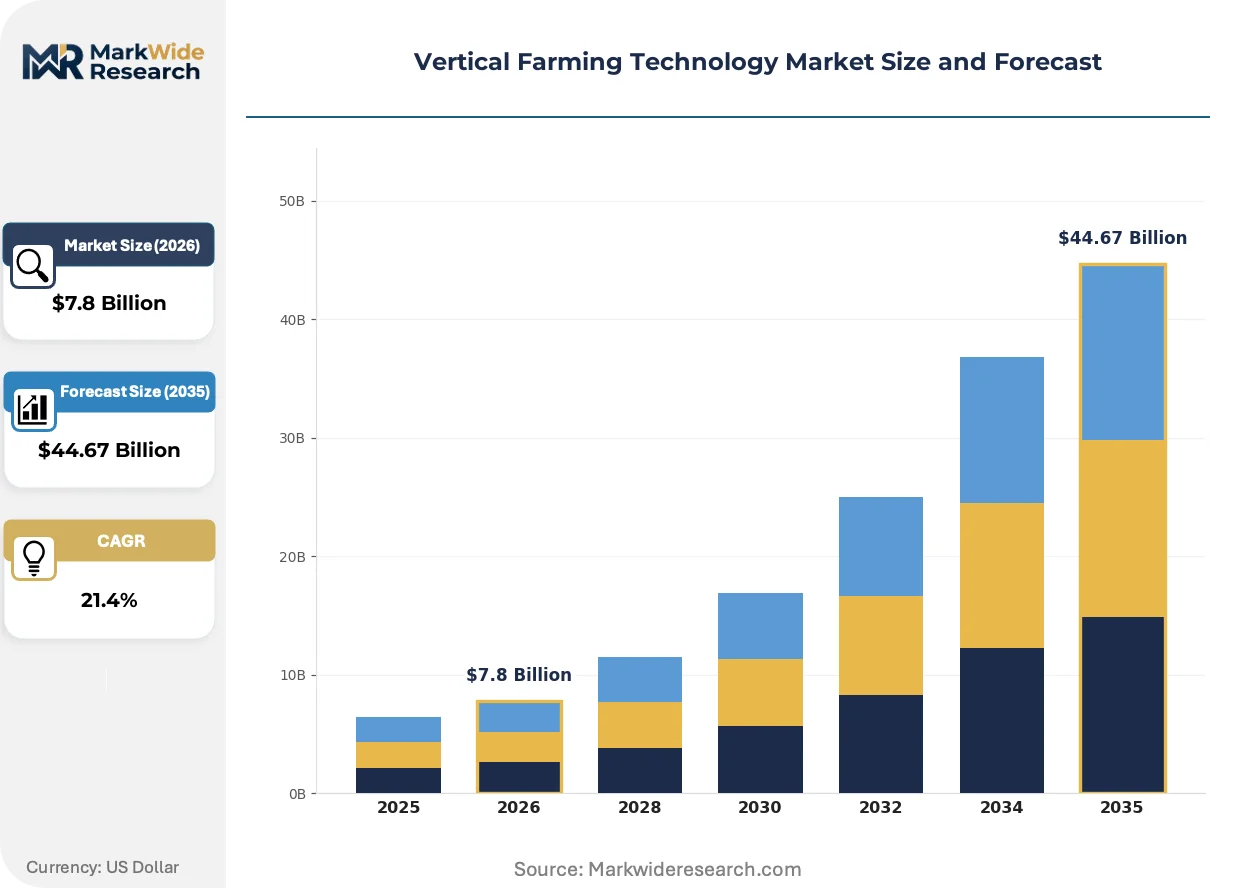
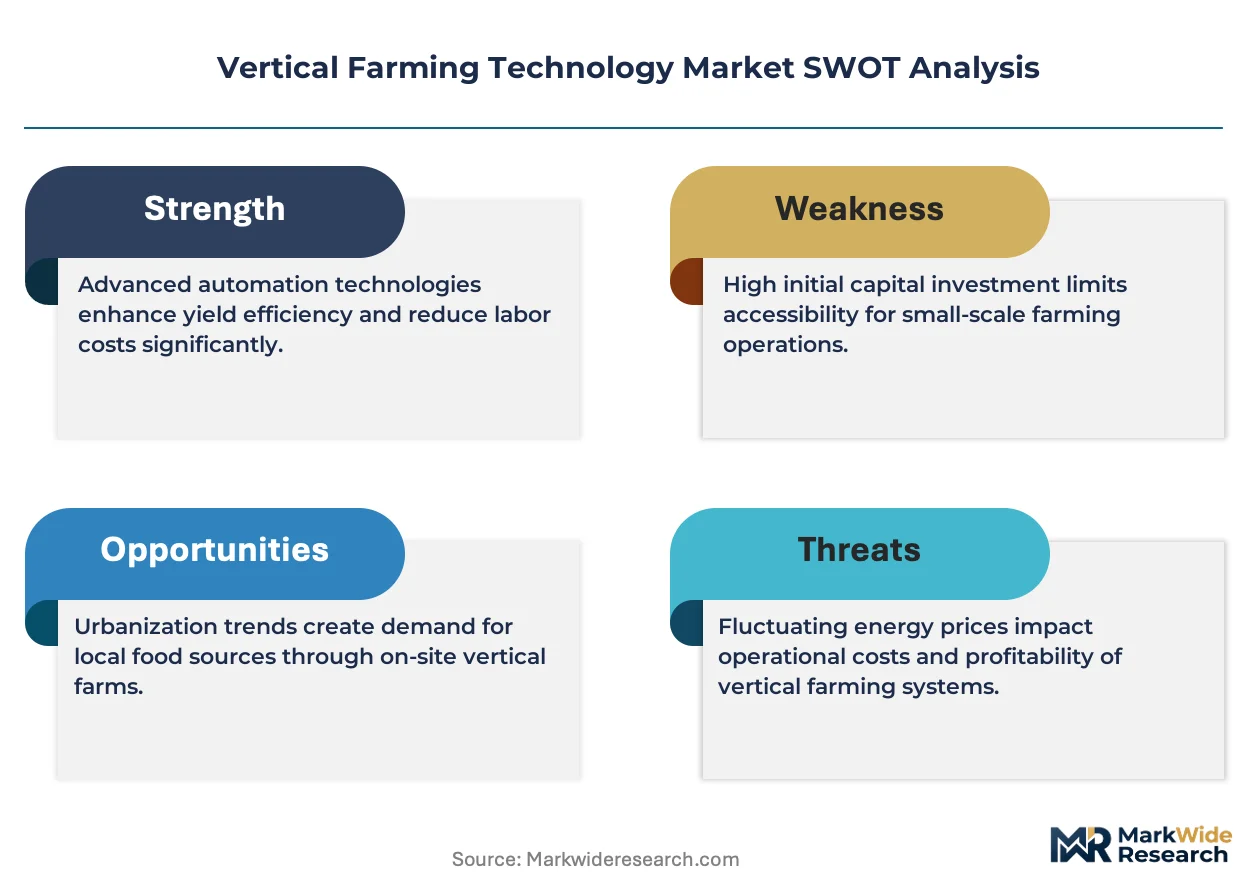
Energy tariff volatility and carbon accounting frameworks are reshaping facility siting economics across controlled-environment agriculture, forcing operators to co-locate with renewable generation or abandon high-grid-cost markets entirely.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding pesticide reduction targets redirect agricultural subsidy flows toward soil-less cultivation methods, accelerating capital deployment into enclosed growing systems.
- Urban food security mandates:Municipal procurement policies in dense metropolitan areas establish minimum local sourcing quotas for institutional food service contracts.
- LED photobiology advances:Spectral tuning at 400-700 nanometer PAR ranges optimizes photosynthetic photon flux density, compressing crop cycle times for leafy greens.
Market Restraints
- Electricity cost concentration:Facility economics depend on industrial tariff structures that vary by utility territory, creating unhedgeable operating expense volatility.
- Input supply bottlenecks:Specialized nutrient formulation chemistry concentrates among German and Dutch chemical suppliers, exposing operators to freight cost spikes.
- Technical yield ceilings:Photosynthetic efficiency limits cap biomass accumulation rates regardless of capital intensity, constraining unit economics improvement curves.
Strategic Opportunities
- Pharmaceutical-grade botanical sourcing:Contract cultivation for active pharmaceutical ingredients commands price premiums through Good Agricultural Practice certification pathways.
- Containerized deployment models:Military, disaster-relief, and remote mining operators seek deployable food sovereignty solutions requiring minimal infrastructure.
- Carbon credit monetization:Avoided agricultural runoff and reduced food-mile emissions qualify for compliance offset markets under evolving verification protocols.
Industry Challenges
- Horticultural lighting engineering talent scarcity:Photobiology expertise sits concentrated at Wageningen University and select research institutes, constraining facility design capacity expansion.
- FDA food safety compliance timelines:Hazard analysis requirements for indoor leafy green operations demand extended validation periods before commercial offtake contracts activate.
- Legacy HVAC integration complexity:Climate control systems must interface with existing building management protocols in retrofitted warehouse conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Farming Technology Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $44.67 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydroponics, Aeroponics, Aquaponics, Soil-Based Product Type: Indoor Farms, Container Farms, Greenhouses, Vertical Racks End User: Retailers, Restaurants, Wholesalers, Research Institutions Deployment: On-Premises, Cloud-Based, Hybrid Systems, Modular |
| Companies Covered | AeroFarms, Freight Farms, Signify Holding, Plenty Unlimited, 80 Acres Farms, American Hydroponics, Everlight Electronics, Heliospectra, Urban Crop Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Farming Technology Market Trends and Innovations
Spectral engineering and automation architectures are compressing the boundary between agricultural production and pharmaceutical manufacturing, creating new quality certification tiers that stratify market access.
Aeroponic root-misting systems are rewriting the water-use efficiency frontier in controlled-environment agriculture. Pharmaceutical contract cultivators are adopting these systems fastest, driven by contamination control requirements. This technology is rewriting margin structures by eliminating substrate costs while enabling precise nutrient dosing for high-value botanical extraction.
The EU Green Deal's pesticide reduction mandates are tightening residue tolerance thresholds for imported produce. This regulatory pressure is redirecting supermarket procurement budgets toward domestic vertical farming suppliers. Fresh produce buyers in Germany and France are responding by signing multi-year offtake agreements with certified indoor operators.
Direct contracting between grocery retailers and vertical farming facilities is displacing traditional wholesale produce distribution channels. This channel compression is most visible in the Netherlands, where supermarket chains operate captive sourcing subsidiaries. Retailers in this market are securing supply through equity stakes in production facilities rather than spot market purchases.
Vertical Farming Technology Market Segmentation
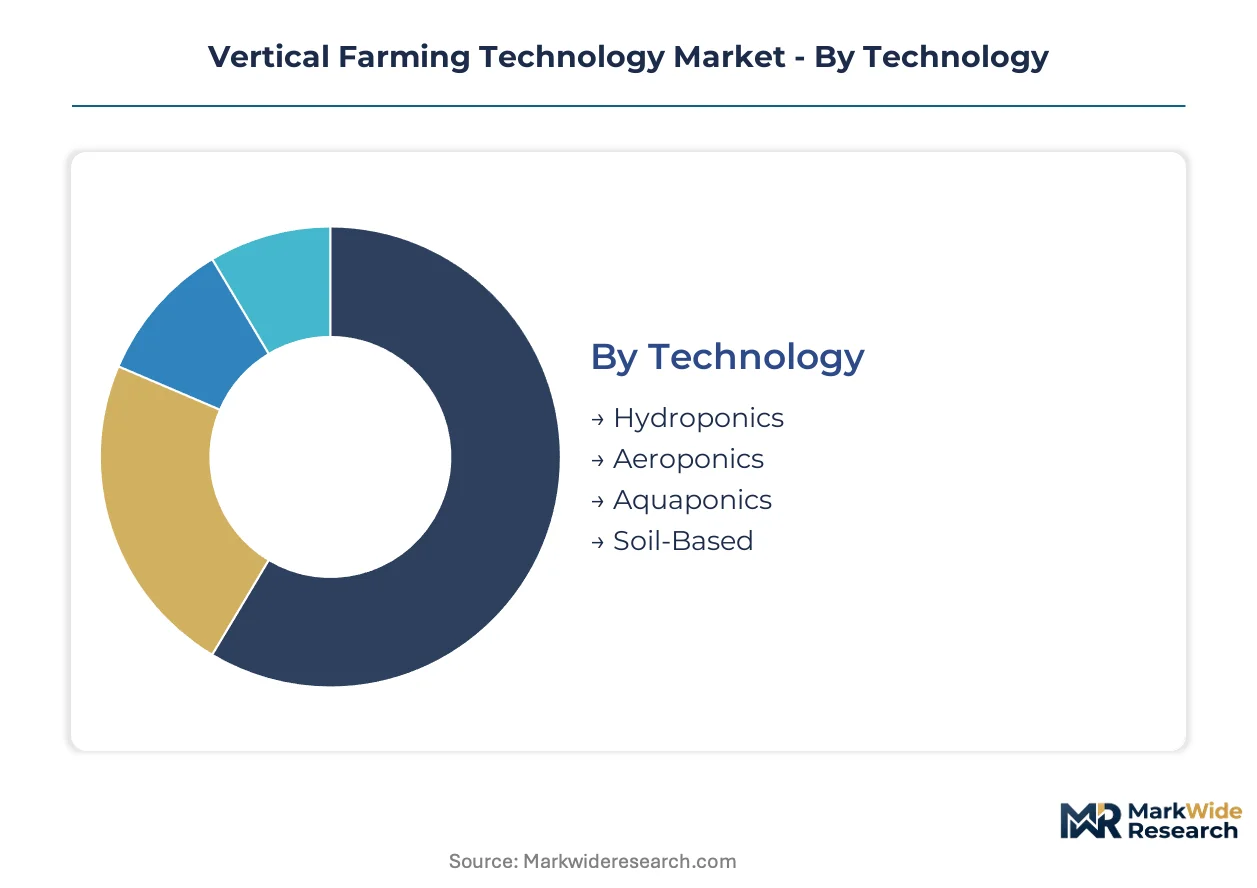
Technology choice in vertical farming determines capital intensity, water efficiency, and crop eligibility. Segmentation reveals how operators balance technical complexity against margin capture and regulatory compliance requirements.
Technology:
Buyers differentiate by water efficiency thresholds and contamination control needs.
- Hydroponics:Nutrient film technique and deep water culture systems suspend roots in oxygenated solution. Demand concentrates among grocery retailers in the Netherlands seeking volume supply contracts, constrained by wastewater classification rules under EPA agricultural runoff exemptions.
- Aeroponics:High-pressure misting delivers nutrients directly to exposed root systems without substrate. Pharmaceutical contract cultivators in Germany adopt these systems fastest, driven by EU Green Deal pesticide residue thresholds and Good Agricultural Practice certification requirements.
- Aquaponics:Integrated fish aquaculture recycles nutrient-rich effluent for plant cultivation. Urban food security mandates in Dutch metropolitan areas sustain niche deployment.
- Soil-Based:Organic substrate systems maintain familiar cultivation protocols for transitioning conventional growers. Limited adoption in controlled-environment facilities due to pest management complexity.
Volume sits with Hydroponics; growth tilts toward Aeroponics.
Product Type:
Facility architecture determines deployment speed and geographic flexibility.
- Indoor Farms:Purpose-built warehouse installations integrate climate control, LED arrays, and automated nutrient delivery. Supermarket chains in France secure supply through equity stakes in large-scale facilities rather than spot purchases.
- Container Farms:Modified shipping containers house self-contained growing systems deployable without permanent infrastructure. Military and disaster-relief operators in remote mining regions drive fastest expansion, seeking food sovereignty with minimal site preparation.
- Greenhouses:Glass or polycarbonate structures supplement natural light with supplemental LED photobiology. Established Dutch horticulture clusters favor retrofitted greenhouse conversions.
- Vertical Racks:Modular stacking systems maximize production density per square meter. Research institutions at Wageningen University deploy these for photobiology trials.
Revenue concentrates in Indoor Farms; deployment velocity favors Container Farms.
End User:
Procurement sophistication and contract duration separate buyer tiers.
- Retailers:Supermarket chains negotiate multi-year offtake agreements with certified indoor operators. German and French fresh produce buyers redirect procurement budgets toward domestic vertical farming suppliers under tightening EU residue standards.
- Restaurants:High-end culinary establishments source specialty herbs and microgreens through direct farm relationships. Urban location requirements limit supplier radius.
- Wholesalers:Traditional produce distributors face channel compression as retailers contract directly with production facilities. Margin pressure accelerates consolidation.
- Research Institutions:Universities and agricultural institutes validate crop protocols and photobiology parameters. Wageningen University clusters commercialize R&D through spinout ventures.
Contract value peaks with Retailers; margin expansion targets Restaurants.
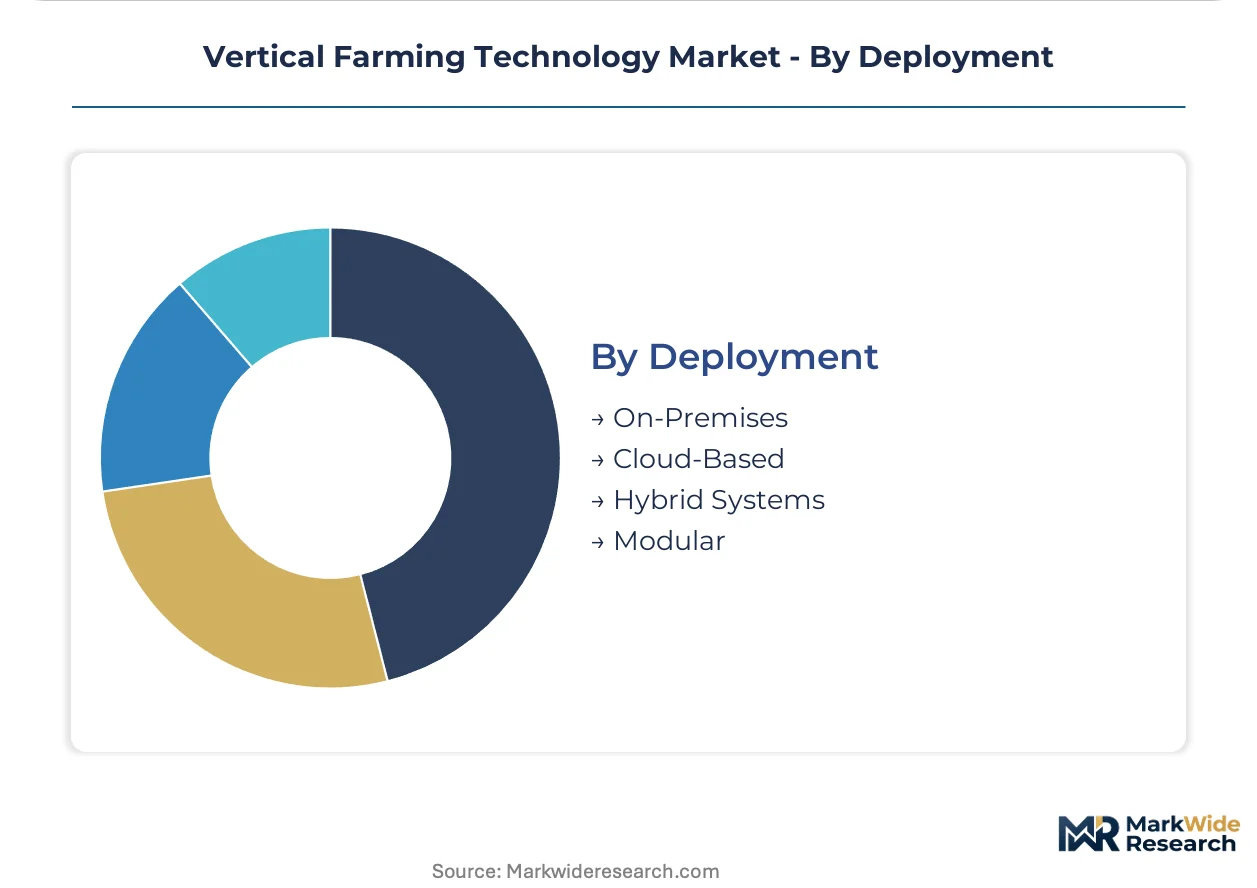
Deployment:
Integration architecture determines scalability and data sovereignty tradeoffs.
- On-Premises:Local server infrastructure maintains operational data within facility boundaries. Pharmaceutical-grade botanical cultivators in Germany require isolated systems for intellectual property protection.
- Cloud-Based:Remote data processing enables predictive analytics and multi-site coordination. Energy tariff monitoring across utility territories relies on centralized optimization.
- Hybrid Systems:Edge computing with cloud backup balances latency-sensitive climate control against analytical scale. Dutch operators favor this architecture for legacy HVAC integration.
- Modular:Standardized subsystems permit incremental capacity expansion without full facility redesign. Container farm operators deploy modular nutrient delivery and lighting arrays.
Installed base favors On-Premises; connectivity investment flows to Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer manufacturing clusters in the Netherlands anchor photobiology LED supply chains for controlled-environment agriculture. Facility siting economics concentrate where renewable energy tariffs and horticultural research infrastructure overlap.
United States
Military and disaster-relief procurement drives container farm deployment for deployable food sovereignty. FDA food safety modernization rules enforce hazard analysis timelines for indoor leafy green operations. Newark-based AeroFarms anchors aeroponic R&D commercialization through university partnerships.
Germany
Pharmaceutical-grade botanical contract cultivation commands GAP-certified price premiums. EFSA residue tolerance thresholds under EU Green Deal Farm to Fork redirect supermarket procurement budgets. Berlin-Brandenburg clusters concentrate nutrient formulation chemistry suppliers serving enclosed growing systems.
Netherlands
Supermarket chains secure supply through equity stakes in captive sourcing subsidiaries rather than spot purchases. Wageningen University commercializes photobiology research through horticulture LED spinout ventures. Randstad metro clusters integrate climate control engineering with legacy greenhouse retrofit expertise.
China
Urban food security mandates in dense metropolitan areas establish minimum local sourcing quotas for institutional contracts. MIIT dual carbon goals redirect subsidy flows toward renewable-co-located controlled-environment facilities. Yangtze River Delta manufacturing bases supply modular LED spectral tuning arrays.
Japan
High-end culinary establishments source specialty herbs through direct farm relationships constrained by urban radius requirements. METI energy tariff structures force operators toward industrial zones with grid-scale renewable access. Kanto region research institutes validate crop protocols for pharmaceutical extraction applications.
Vertical Farming Technology Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and containerized deployment models. The vendor base stratifies across LED photobiology specialists, automated nutrient delivery architects, and integrated facility operators. Three archetypes dominate: research-commercialization hybrids, scale-driven warehouse developers, and modular equipment fabricators. Competitive moves concentrate on strategic partnerships with grocery retailers and technology licensing for HVAC integration.
Within the research-commercialization tier, Signify Holding and Heliospectra occupy positions bridging academic photobiology with industrial LED deployment. AeroFarms exemplifies the integrated facility archetype through its aeroponic root-misting specialization. Among modular equipment specialists, Freight Farms represents containerized deployment architecture for remote and military applications.
| Leading Market Players |
|---|
| AeroFarms |
| Freight Farms |
| Signify Holding |
| Plenty Unlimited |
| 80 Acres Farms |
| American Hydroponics |
| Everlight Electronics |
| Heliospectra |
| Urban Crop Solutions |
| Others |
Pricing and Supply Chain Analysis
LED spectral tuning arrays manufactured in the Yangtze River Delta feed through three pricing tiers determined by photobiology certification levels and HVAC integration complexity. German nutrient formulation chemistry suppliers anchor input costs, with freight exposure propagating downstream to facility operators negotiating multi-year offtake agreements.
Pricing Analysis
Service bundling separates hardware-only transactions from fully integrated facility contracts covering installation, crop protocol validation, and ongoing photobiology optimization. Pricing stratifies across premium, standard, and economy tiers based on Good Agricultural Practice certification status and automated nutrient delivery sophistication. Cost compression in the standard tier intensifies as Dutch supermarket chains consolidate procurement through equity stakes rather than spot purchases. Research institutions exhibit lowest price sensitivity due to grant-funded capital budgets, while remote mining operators demand unbundled equipment pricing to minimize upfront deployment costs.
Supply Chain Analysis
CE marking and FDA food safety compliance gates filter qualified suppliers from commodity equipment vendors, concentrating certified component sourcing among Netherlands, Germany, and China manufacturing bases. Specialized horticulture LED chips, high-pressure misting nozzles, and precision nutrient dosing pumps constitute critical dependencies. Single-source vulnerability sits with German chemical suppliers dominating proprietary nutrient formulations. Distribution runs through direct contracting between production facilities and grocery retailers, displacing traditional wholesale produce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork pesticide reduction targets erect a cost-of-compliance barrier that favors incumbent operators with validated certification pathways and established regulatory relationships.
For Market Incumbents: Deploy photobiology IP licensing as a defensive lever against containerized equipment specialists threatening commoditization. Secure backward integration into LED spectral tuning manufacturing through partnerships with Yangtze River Delta suppliers. Expand capacity in the Randstad metro cluster to exploit Wageningen University commercialization pipelines and legacy greenhouse retrofit expertise. For New Entrants and Emerging Players: Enter via pharmaceutical-grade botanical contract cultivation, where GAP certification premiums and residue tolerance thresholds under EU Green Deal mandates create protected pricing power. Target German EFSA compliance requirements as the most penetrable entry vector. Pursue direct research partnerships with Wageningen University spinout ventures to shortcut photobiology validation timelines. For Investors and Strategic Acquirers: FDA hazard analysis validation completion is the leading indicator that indoor leafy green operators have crossed the commercial offtake threshold for institutional capital deployment. Five-to-ten year viability hinges on renewable energy co-location economics and carbon credit monetization protocols. Acquisition candidates should demonstrate captive supermarket equity relationships or military container farm procurement contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Photobiology IP Licensing | Signify Holding and Heliospectra monetize spectral tuning patents through facility operator royalty streams. |
| Backward Integration into LED Manufacturing | Dutch operators secure supply chain control over 400-700 nanometer PAR range spectral arrays. |
| Pharmaceutical GAP Certification | German cultivators capture price premiums through EFSA residue compliance and active ingredient extraction contracts. |
| Containerized Deployment Architecture | Freight Farms and modular specialists address military and remote mining food sovereignty procurement requirements. |
| Supermarket Equity Partnerships | French and Dutch retailers secure supply through captive sourcing subsidiaries rather than volatile spot markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with controlled-environment agriculture facility operators, horticulture LED procurement managers, supermarket fresh produce buyers, pharmaceutical contract cultivation executives, and nutrient formulation chemistry suppliers. FDA food safety modernization guidance documents, EU Green Deal Farm to Fork strategy filings, EPA agricultural runoff exemption classifications, and EFSA residue tolerance databases provided regulatory boundary conditions. Bottom-up facility deployment counts and top-down grocery procurement budget allocations were triangulated against customs records of LED horticulture lighting imports.
Data-stream reconciliation across installed capacity surveys, energy tariff structure analyses, and offtake contract disclosure patterns informed the projection framework. Segmentation dimensions modeled include cultivation technology type, facility architecture, end-user procurement sophistication, and deployment integration architecture. CAGRs were derived from curve-fitting historical adoption rates against regulatory mandate implementation timelines, incorporating LED photobiology efficiency improvement curves and carbon accounting framework evolution across the analysis window. Renewable energy co-location economics and pharmaceutical extraction demand growth served as industry-specific demand drivers.
Revisions become necessary when EU pesticide residue thresholds tighten beyond current Farm to Fork trajectories, when energy tariff volatility exceeds modeled utility territory ranges, or when FDA hazard analysis validation timelines extend materially. Forecasts reflect documented assumptions regarding subsidy flow redirection and supermarket procurement consolidation patterns. A model refresh is warranted upon material change in carbon credit verification protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Global Indoor Farming Technology Market