
 Plant Growth Chambers Market | 2026-2036
Plant Growth Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Growth Chambers Market Intelligence
Project finance for distributed research infrastructure is tilting competitive dynamics toward vendors who bundle installation with long-term service contracts. Binder GmbH leverages its temperature-humidity control heritage to anchor premium positioning in European research corridors. Thermo Fisher Scientific sustains broad channel reach through its life-sciences distribution network. Conviron specializes in large-format walk-in systems for government-funded crop science programs.
Plant growth chambers are enclosed, climate-controlled enclosures that regulate temperature, humidity, light spectrum, and CO2 concentration to simulate precise environmental conditions for biological cultivation. These systems typically achieve temperature ranges from -10°C to 60°C with ±0.5°C uniformity, serving the fundamental purpose of reproducible plant science experimentation and seedling propagation. Walk-in chambers command the largest installed base due to their scalability for university-scale field-station replication, while benchtop configurations represent the fastest-growing configuration as distributed biotech labs prioritize space-efficient phenotyping. LED lighting technology now dominates new installations because spectral programmability reduces photoperiod stress variability and extends lamp replacement cycles versus legacy fluorescent systems.
EPA energy-efficiency standards for laboratory equipment shape product development priorities for US-bound chamber manufacturers, while REACH compliance in Europe restricts certain insulation and refrigerant chemistries in climate-control assemblies. ISO 17025 accreditation requirements for testing laboratories indirectly drive demand for chambers with validated environmental uniformity documentation. Stakeholders must weigh spectral tuning capabilities against total cost of ownership as research funders tighten capital equipment approval protocols.
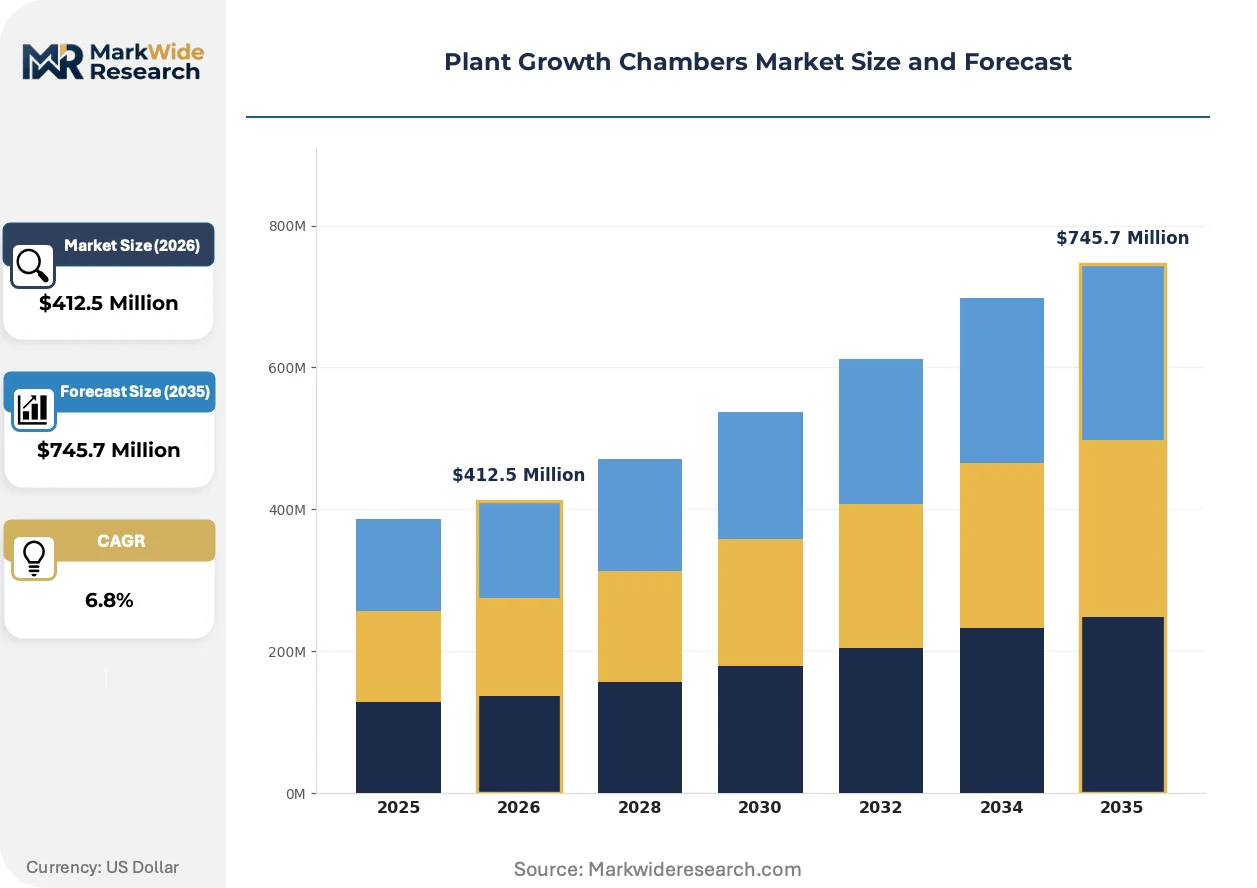
Market Dynamics
LED spectral programmability is compressing energy thresholds for controlled-environment agriculture while REACH refrigerant restrictions force redesigns of thermal management assemblies across European supply chains.
Growth Catalysts
- EU Green Deal decarbonization mandates:Agricultural research institutes in Germany and the Netherlands accelerate chamber procurement to meet net-zero compliance deadlines for laboratory infrastructure.
- Transgenic crop development pipelines:Biotechnology firms expand walk-in chamber installations to support CRISPR-edited strain validation under controlled photoperiod conditions.
- Phenotyping automation:Machine vision integration with LED-tunable spectral arrays enables high-throughput trait screening that manual protocols cannot replicate.
Market Restraints
- Copper and aluminum input volatility:Climate-control coil assemblies face margin pressure from base metal price swings that chamber manufacturers cannot fully pass through to funded research buyers.
- Compressor supply concentration:Precision refrigeration subsystems rely on a narrow German and Japanese supplier base vulnerable to extended lead times.
- Legacy fluorescent lamp phase-out:Existing installed bases with non-LED lighting face accelerated obsolescence as replacement parts exit production channels.
Strategic Opportunities
- Brazilian agricultural research expansion:EMBRAPA facility modernization programs create demand for large-format walk-in systems with tropical humidity simulation capabilities.
- CSRD sustainability reporting requirements:Corporate R&D departments must document controlled-environment experimental reproducibility, validating chamber uniformity documentation as a procurement criterion.
- Cloud-based environmental monitoring:IoT sensor integration with chamber control systems enables remote trial management that reduces on-site technician requirements.
Industry Challenges
- ISO 17025 calibration technician scarcity:Validated environmental uniformity documentation requires specialized metrology skills that university maintenance departments struggle to retain.
- Legacy building HVAC incompatibility:Retrofit installations in aging research facilities face integration friction with existing chilled water and electrical distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Growth Chambers Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-in Chambers, Growth Cabinets, Benchtop Chambers, Custom Chambers Application: Research Laboratories, Educational Institutions, Commercial Horticulture, Indoor Farming Technology: LED Lighting, HID Lighting, Fluorescent Lighting, Aeroponics End User: Biotechnology Firms, Agricultural Researchers, Floriculture Producers, Universities |
| Companies Covered | Binder GmbH, Control Environments Ltd., Thermo Fisher Scientific, Schunk, Darwin Chambers, Conviron, Weiss Technik GmbH, Snijders, Percival Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Growth Chambers Market Strategic Shifts & Innovations
Spectral tunability and predictive maintenance architectures are redefining performance benchmarks while procurement patterns favor comprehensive service bundling over discrete equipment transactions.
Multi-channel LED arrays with programmable far-red and blue wavelength ratios are digitizing photomorphogenesis research protocols. Crop science departments at Wageningen University and Rothamsted Research deploy these systems to compress generational cycle times for stress tolerance screening. The technology is digitizing experimental design by enabling real-time spectral adjustment without chamber entry.
REACH F-Gas Regulation restrictions on high-global-warming-potential refrigerants are forcing thermal engineering redesigns for European-bound equipment. Manufacturers must validate alternative refrigerant performance across extended temperature ranges while maintaining ±0.5°C uniformity specifications. German agricultural research corridors face the steepest compliance timeline, with 2027 phase-out deadlines accelerating replacement cycles.
Research funders now mandate total-cost-of-ownership documentation that unbundles capital expenditure from decade-long service commitments. University procurement offices negotiate performance-based contracts where vendors retain responsibility for calibration, lamp replacement, and uniformity revalidation. This contracting evolution is most pronounced in US land-grant university systems where USDA capital equipment approval protocols have tightened.
Plant Growth Chambers Market Segmentation
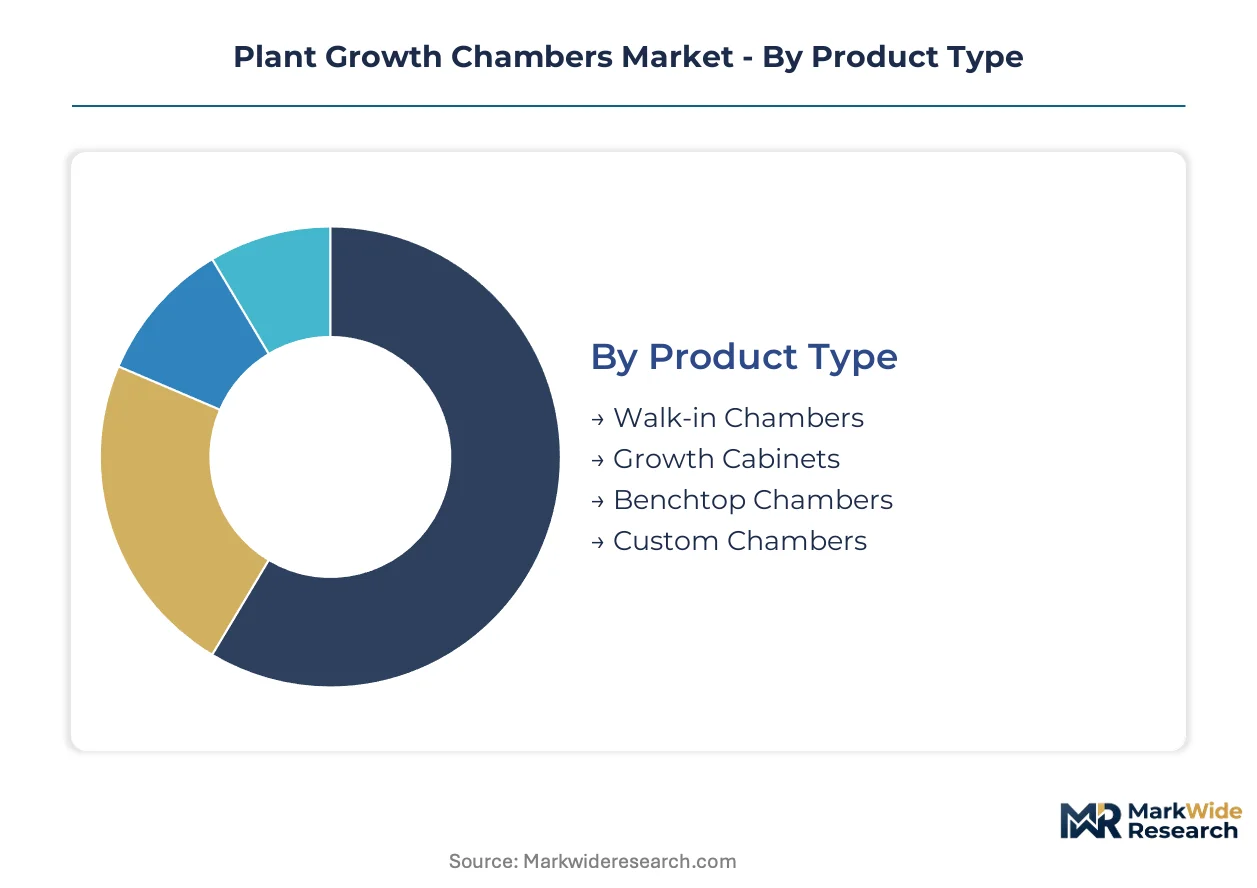
Segmentation in plant growth chambers reflects divergent experimental scales, from university benchtop phenotyping to industrial-scale transgenic validation. Procurement priorities differ sharply between funded research laboratories and commercial horticulture operators.
Product Type:
Research infrastructure spans walk-in field-station replication to distributed benchtop automation, with cost-per-square-meter and HVAC integration driving configuration selection.
- Walk-in Chambers:Large-format enclosures replicate field conditions at university scale, achieving temperature uniformity across 50+ square meter footprints. German agricultural research institutes anchor European demand for these systems as EMBRAPA modernization programs expand Brazilian procurement.
- Growth Cabinets:Self-contained units with precision climate control serve mid-scale experimentation without facility-scale HVAC dependencies. Biotechnology firms in the Netherlands concentrate orders for CRISPR strain validation where space constraints limit walk-in deployment.
- Benchtop Chambers:Compact units prioritize space-efficient phenotyping for distributed biotech laboratories.
- Custom Chambers:Engineered-to-order systems address atypical dimensional or environmental specifications for specialized crop programs.
Established volume favors walk-in configurations; emerging adoption favors benchtop systems.
Application:
End-use concentration tilts toward reproducibility mandates in funded research versus yield optimization in commercial operations.
- Research Laboratories:Facilities demand validated environmental uniformity documentation under ISO 17025 protocols, with calibration traceability embedded in procurement specifications. USDA capital equipment approval protocols at US land-grant universities tighten documentation requirements.
- Educational Institutions:Teaching laboratories prioritize cost containment and safety interlocks over spectral programmability. REACH F-Gas Regulation compliance deadlines accelerate European university replacement cycles.
- Commercial Horticulture:Operators optimize photoperiod control for flowering synchronization and vegetative propagation throughput.
- Indoor Farming:Controlled-environment agriculture facilities integrate chambers for cultivar trialing prior to production-scale deployment.
Research laboratories command premium pricing; commercial horticulture drives volume expansion.
Technology:
Lighting technology selection determines spectral control precision, energy intensity, and lamp replacement economics across installation lifecycles.
- LED Lighting:Multi-channel arrays with programmable far-red and blue wavelength ratios enable real-time photomorphogenesis adjustment without chamber entry. Wageningen University and Rothamsted Research deploy these systems to compress generational cycle times.
- HID Lighting:High-intensity discharge systems retain installed-base presence where spectral tunability requirements remain minimal.
- Fluorescent Lighting:Legacy installations face accelerated obsolescence as replacement parts exit production channels.
- Aeroponics:Root-zone misting integration with climate control enables soilless cultivation protocols for specialized research applications.
LED systems are climbing the fastest; fluorescent technology loses installed-base share.
End User:
Customer-type differentiation separates grant-funded capital equipment protocols from commercial ROI calculations.
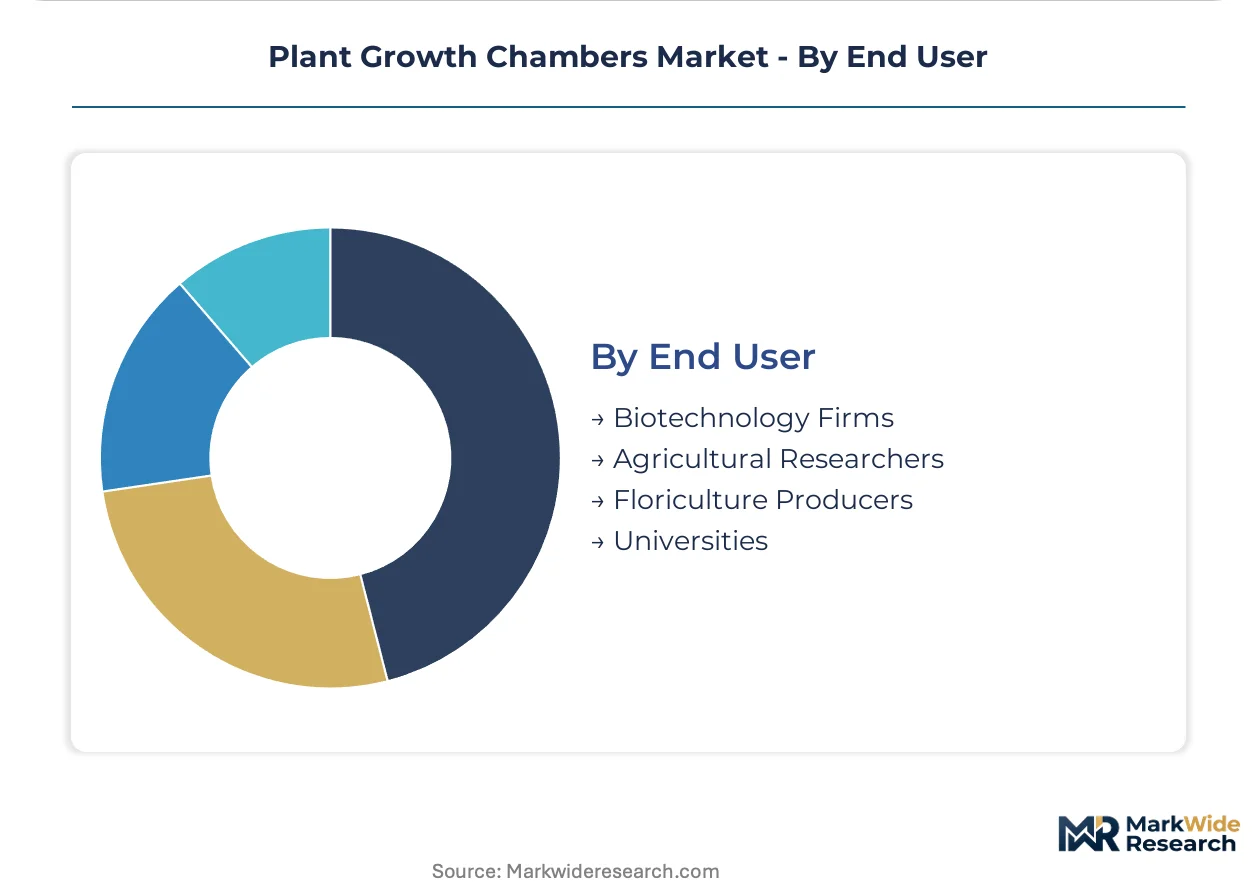
- Biotechnology Firms:CRISPR-edited strain validation pipelines require walk-in installations with controlled photoperiod conditions. These firms now drive equipment procurement for cell culture and transgenic crop development.
- Agricultural Researchers:Government-funded crop science programs anchor large-format system demand with multi-year funding horizons.
- Floriculture Producers:Commercial operators prioritize flowering synchronization and post-harvest quality maintenance.
- Universities:Distributed biotech labs prioritize space-efficient phenotyping as research funders tighten capital equipment approval protocols.
Biotechnology firms expand fastest; universities retain largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology firms and agricultural research institutes concentrate equipment procurement in precision-engineering clusters across Germany, the United States, and Brazil. EMBRAPA modernization programs and EU Green Deal compliance deadlines accelerate replacement cycles in these corridors.
United States
USDA capital equipment approval protocols at land-grant universities tighten documentation requirements for validated environmental uniformity. EPA energy-efficiency standards for laboratory equipment shape product development priorities for domestic-bound chamber manufacturers. Greater Boston and the Pacific Northwest host dense concentrations of CRISPR-edited strain validation pipelines.
Germany
REACH F-Gas Regulation restrictions on high-global-warming-potential refrigerants force thermal engineering redesigns with 2027 phase-out deadlines. Precision engineering clusters in Bavaria and North Rhine-Westphalia serve European agricultural research institutes with temperature-humidity control heritage. German compressor suppliers anchor a narrow but critical refrigeration subsystem base.
Brazil
EMBRAPA facility modernization programs create demand for large-format walk-in systems with tropical humidity simulation capabilities. The country's national agricultural research regulator mandates reproducible field-station replication for cultivar development. São Paulo and Minas Gerais concentrate biotechnology firm expansion for transgenic crop pipelines.
Netherlands
Wageningen University deploys multi-channel LED arrays with programmable far-red and blue wavelength ratios to compress generational cycle times. EU Green Deal decarbonization mandates accelerate chamber procurement to meet net-zero compliance deadlines for laboratory infrastructure. The Randstad corridor anchors phenotyping automation integration with machine vision systems.
China
Dual carbon goals and MEE emissions standards reshape thermal management assembly specifications for domestic manufacturers. Yangtze River Delta research institutes prioritize space-efficient benchtop configurations for distributed phenotyping. Shanghai and Beijing-Tianjin-Hebei clusters concentrate government-funded crop science program demand.
Plant Growth Chambers Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base separates into three strategic archetypes: temperature-humidity heritage specialists, life-sciences distribution networks, and large-format walk-in system engineers. Competitive moves concentrate on bundling installation with long-term service contracts and integrating IoT sensor architectures for remote trial management.
Within the temperature-humidity heritage tier, Binder GmbH and Weiss Technik GmbH exemplify German-engineered precision positioning. Among North American fabricators, Darwin Chambers and Percival Scientific occupy positions in research-scale system supply. Thermo Fisher Scientific anchors the life-sciences distribution archetype through broad channel reach.
| Leading Market Players |
|---|
| Binder GmbH |
| Control Environments Ltd. |
| Thermo Fisher Scientific |
| Schunk |
| Darwin Chambers |
| Conviron |
| Weiss Technik GmbH |
| Snijders |
| Percival Scientific |
| Others |
Cost & Logistics Intelligence
Undercapacity in precision refrigeration subsystems is tightening supplier leverage and compressing margin flexibility for chamber manufacturers serving European agricultural research corridors. German and Japanese compressor suppliers now command extended lead times that force equipment vendors to pre-position inventory or absorb escalation clauses in funded research procurement cycles.
Pricing Analysis
Cost-plus contracts with copper and aluminum indexation dominate procurement between chamber manufacturers and research institutes, transferring base metal volatility to end-users through semi-annual price adjustments. Three-tier pricing structure across premium validation-grade, standard research-grade, and economy teaching-grade levels separates ISO 17025-accredited systems from basic climate-control units. Pricing pressure stems from REACH F-Gas Regulation compliance costs that manufacturers cannot fully recover in competitive European tenders. Universities and educational institutions exhibit highest price sensitivity due to fixed capital equipment budgets, while biotechnology firms prioritize spectral programmability over unit cost.
Supply Chain Analysis
Contract manufacturing for thermal management assemblies concentrates in Germany, Japan, and China, with Bavarian precision engineering clusters anchoring European refrigeration subsystem capacity. Climate-control coil assemblies draw from copper processing in Chile and aluminum smelting in Russia, creating raw material exposure to commodity price swings. Single-source vulnerability in German compressor suppliers generates supply chain risk as REACH phase-out deadlines accelerate replacement demand. Distribution runs through life-sciences channel partners and direct OEM relationships with agricultural research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant growth chambers market is cycling through a replacement-driven recovery as EU Green Deal decarbonization mandates and REACH F-Gas Regulation deadlines force infrastructure modernization across European agricultural research corridors.
For Market Incumbents: Entrench service-contract bundling as the primary retention mechanism against emerging IoT-enabled remote monitoring competitors. Binder GmbH and Weiss Technik GmbH should deepen backward integration into compressor subsystem production to mitigate German supplier concentration risk. Thermo Fisher Scientific must defend its life-sciences distribution network against direct-to-institution digital procurement platforms.
For New Entrants and Emerging Players: Pursue benchtop chamber white-space in Chinese Yangtze River Delta research institutes where distributed phenotyping demand outpaces established vendor coverage. Brazilian EMBRAPA modernization programs offer the most penetrable geography for tropical humidity simulation specialists lacking incumbent relationships. Cloud-based environmental monitoring integration provides the strongest go-to-market angle against legacy hardware-only vendors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across LED-tunable spectral array manufacturing as multi-channel programmable systems displace legacy fluorescent installations. Long-term viability favors vendors with captive service infrastructure capable of decade-long calibration and uniformity revalidation commitments. Acquisition targets should display ISO 17025 metrology capabilities and installed-base density in land-grant university corridors. The signal to monitor is USDA capital equipment approval protocol tightening that elevates documentation-heavy vendors over price competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Spectral Array Manufacturing Scale-Up | Multi-channel programmable systems at Wageningen University compress generational cycle times for stress tolerance screening. |
| REACH F-Gas Alternative Refrigerant Validation | Thermal engineering redesigns for 2027 phase-out deadlines force European-bound equipment specification changes. |
| Cloud-Based Environmental Monitoring Integration | IoT sensor architectures enable remote trial management that reduces on-site technician requirements for distributed biotech labs. |
| Performance-Based Service Contract Expansion | USDA capital equipment approval protocols at land-grant universities favor vendors retaining decade-long calibration responsibility. |
| Tropical Humidity Simulation Capability Development | EMBRAPA facility modernization programs in São Paulo and Minas Gerais create demand for large-format walk-in systems. |
Research Approach
Cross-validation between primary interviews with chamber procurement officers at agricultural research institutes and secondary analysis of EPA energy-efficiency filings anchors the qualitative findings. The research team conducted structured discussions with plant science department heads, university capital equipment managers, biotechnology firm facilities directors, and aftermarket service technicians. Secondary sources include USDA capital equipment approval documentation, REACH F-Gas Regulation compliance databases, EMBRAPA procurement disclosures, and SEC filings from life-sciences equipment distributors. Bottom-up unit demand modeling triangulates against top-down research funding allocation analysis.
Calibration against historical replacement cycles and funded research budget trajectories shapes the projection framework across the analysis window. Segmentation dimensions include product configuration (walk-in, growth cabinet, benchtop), lighting technology (LED, HID, fluorescent), end-user archetype (biotechnology firm, agricultural researcher, university), and regional regulatory cluster (EPA-governed, REACH-governed, MEE-governed). CAGRs derive from weighted average of equipment procurement pipelines and infrastructure modernization program announcements. Key forecast inputs incorporate EU Green Deal decarbonization timeline acceleration and copper price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in research funding appropriations or base metal price trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding REACH implementation adherence and LED cost curves. Quarterly review of EMBRAPA procurement announcements and German compressor supplier lead time indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Middle East Vertical Farming Market