
 Controlled Environment Agriculture Market | 2026-2036
Controlled Environment Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Controlled Environment Agriculture Market Analysis
Multi-source sourcing of leafy greens and herbs is hardening as supermarket chains and restaurant groups diversify supplier bases beyond traditional field agriculture. Gotham Greens leverages controlled greenhouse networks near major metropolitan areas to reduce transport miles and preserve shelf life. AeroFarms anchors its position through proprietary aeroponic systems that maximize yield per square meter in vertical configurations. Mirai dominates Japanese retail channels with large-scale plant factories delivering consistent quality regardless of seasonal conditions.
Controlled environment agriculture refers to the cultivation of crops within enclosed structures where operators actively manage temperature, humidity, light spectrum, CO2 concentration, and nutrient delivery—typically achieving 95% water savings versus open-field methods. The primary commercial purpose is to decouple food production from geographic and climatic constraints, enabling harvest scheduling that aligns with buyer contracts. Hydroponics and vertical farming command the largest technology shares, with hydroponics sustaining mature margin pools in greenhouse vegetables while vertical farming absorbs the fastest capital inflows for urban deployment. Product type segmentation shows greenhouses retaining volume leadership, though container farms are gaining traction in remote and institutional settings where modular installation outweighs per-unit cost premiums.
The EPA regulates agricultural runoff and pesticide applications that conventional farming discharges, indirectly elevating the compliance appeal of closed-loop indoor systems. The EU Green Deal and REACH frameworks impose escalating sustainability requirements on imported produce, channeling European procurement toward certified low-carbon suppliers. FDA food safety rules for fresh produce traceability further advantage controlled environment operators with integrated monitoring and batch-tracking infrastructure. Stakeholders must weigh capital intensity against offtake contract duration, as facility payback periods remain sensitive to energy price trajectories and utility rate structures.
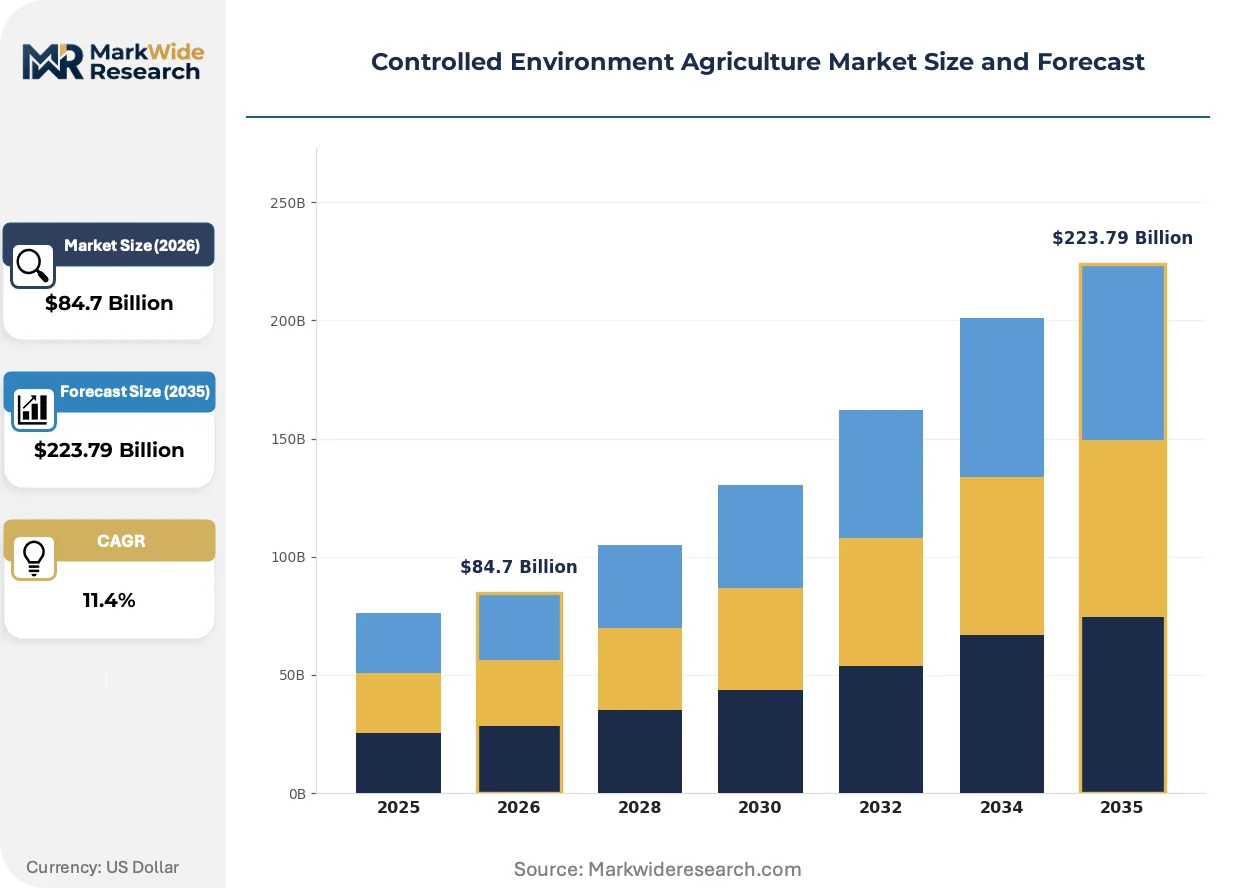
Market Dynamics
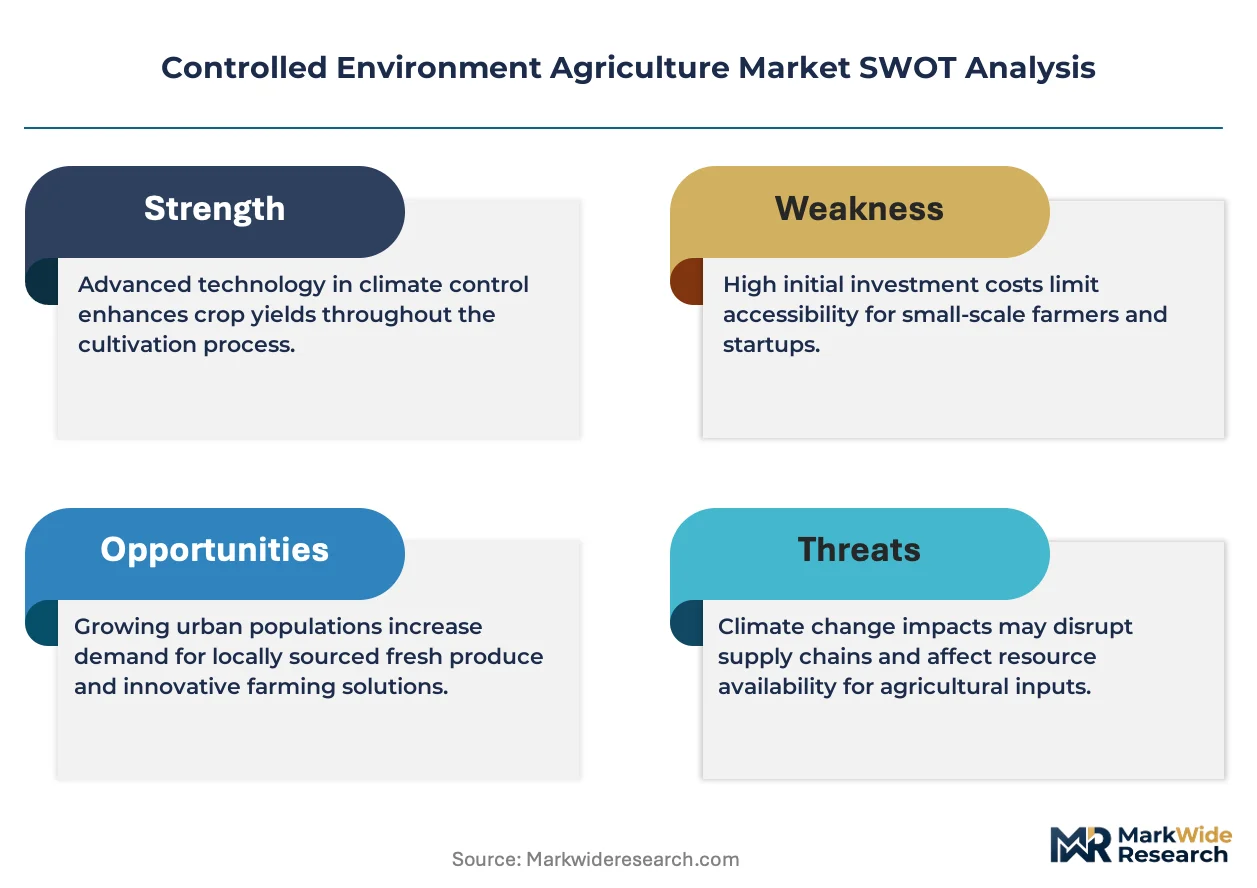
Energy price volatility is compressing facility payback periods and forcing operators toward on-site renewable generation and utility-scale power purchase agreements to stabilize operating margins.
Growth Catalysts
- EU Green Deal carbon mandates:European procurement rules now favor certified low-carbon produce, channeling supermarket and foodservice contracts toward soilless indoor operators with verified water and pesticide savings.
- Urban foodservice procurement:Restaurant groups and institutional caterers in dense metropolitan areas are contracting directly with nearby greenhouse networks to guarantee year-round supply of leafy greens and herbs.
- Horticultural LED efficiency gains:Spectral-tuning advancements in solid-state lighting are reducing per-kilogram energy costs for vertical farming configurations, improving unit economics in high-labor-cost markets.
Market Restraints
- Natural gas price exposure:Greenhouse heating costs in the Netherlands and northern European clusters remain vulnerable to wholesale energy market swings, eroding margin buffers during winter production cycles.
- Equipment import concentration:Climate-control systems and sensor hardware for large-scale plant factories concentrate among German and Dutch engineering suppliers, creating lead-time vulnerability for non-European buildouts.
- Field agriculture substitution:Open-field vegetable production in southern Spain and Morocco retains cost advantages for commodity tomatoes and peppers during conventional growing seasons.
Strategic Opportunities
- Middle East institutional demand:Food security mandates in the UAE and Saudi Arabia are funding desalination-integrated plant factories for domestic leafy green production, reducing import dependency.
- Pharmaceutical-grade botanicals:Controlled environment operators with GMP-compliant facilities can supply standardized active compounds to CDMOs and nutraceutical formulators seeking batch consistency.
- Container farm remote deployment:Modular units are penetrating mining camps, military installations, and research stations where logistics costs for fresh produce exceed capital premiums.
Industry Challenges
- Plant science talent scarcity:Commercial-scale operations require crop physiologists and data scientists capable of optimizing light recipes and nutrient formulations, competing with pharmaceutical and seed-genetics employers for specialized labor.
- Multi-jurisdiction certification:Export-oriented facilities must simultaneously satisfy FDA traceability rules, EU organic-equivalent standards, and destination-country phytosanitary protocols, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Controlled Environment Agriculture Market |
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $223.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydroponics, Aeroponics, Aquaponics, Vertical Farming Product Type: Greenhouses, Indoor Farms, Container Farms, Environments Crop Type: Vegetables, Fruits, Herbs, Flowers End User: Commercial Growers, Research Institutions, Home Gardeners, Food Producers |
| Companies Covered | Mirai, Gotham Greens, AeroFarms, YesHealth Group, Planet Farms, Jingpeng, Lufa Farms, GrowUp Farms, Bowery Farming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Controlled Environment Agriculture Market Emerging Trajectories
Automation and artificial intelligence are converging with biological sensing to transform cultivation from experience-based craft into data-driven manufacturing, compressing cycle-to-cycle learning curves.
Computer vision systems paired with environmental sensors are integrating real-time plant health diagnostics into automated climate adjustments. Large greenhouse operators in the Netherlands and Canada are deploying these platforms to reduce human scouting labor and accelerate stress-response timing. The technology is integrating phenotypic data streams with enterprise resource planning systems, enabling harvest scheduling that locks in contract pricing before maturity.
REACH chemical safety frameworks in Europe are tightening residue limits on imported fresh produce, indirectly elevating compliance costs for conventional exporters while advantaging closed-loop indoor operators with integrated pest management. The regulation is redirecting procurement volumes toward certified low-carbon suppliers with documented input traceability. Dutch retailers are responding by consolidating vendor lists around greenhouse operators with third-party carbon accounting.
Direct contracting between indoor farms and institutional buyers is displacing traditional produce distribution intermediaries in major metropolitan corridors. Hospital systems and corporate cafeteria operators are establishing multi-year supply agreements with nearby greenhouse networks, prioritizing shelf-life reliability over spot-market price flexibility. This pattern is most visible in the northeastern United States and Japanese urban prefectures where land constraints have historically amplified logistics costs for field-grown vegetables.
Controlled Environment Agriculture Market Segmentation
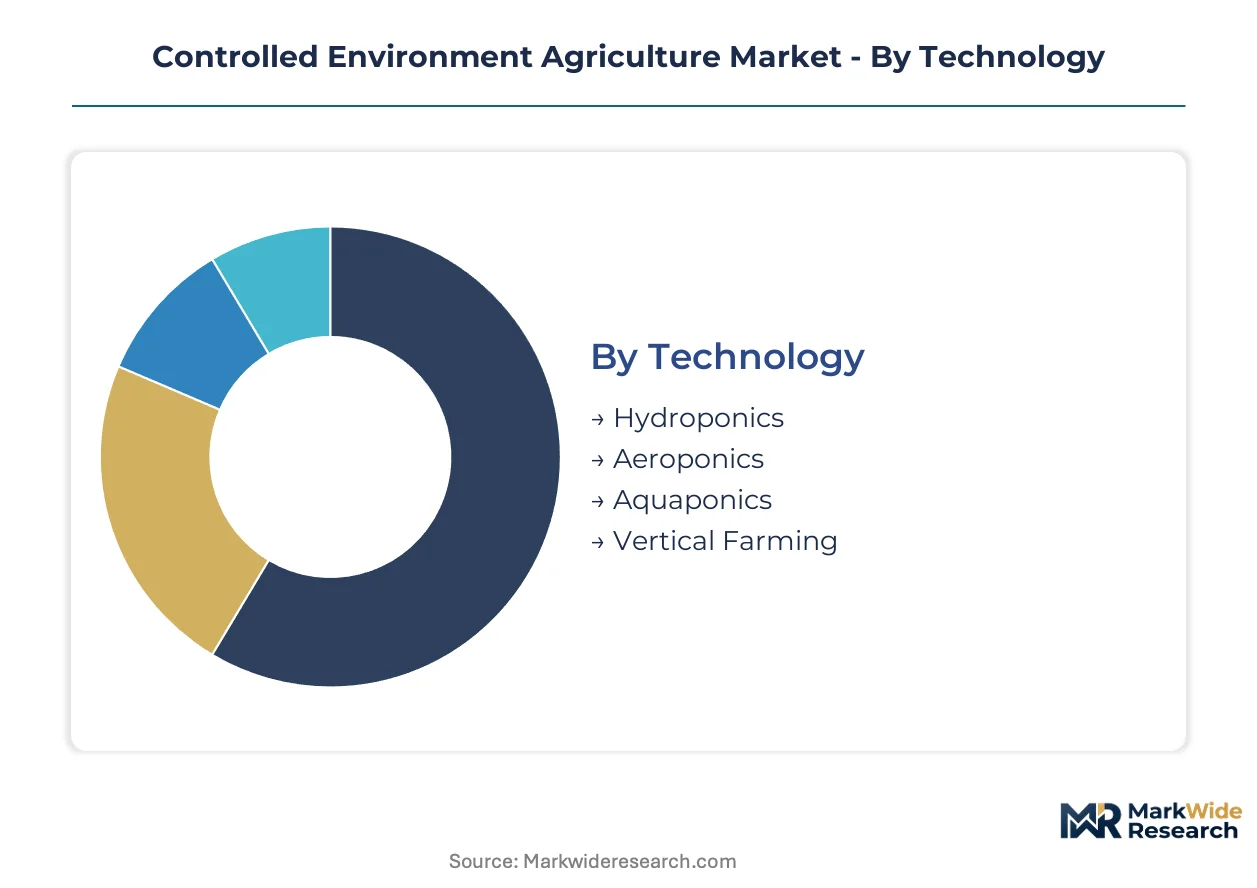
Technology choice determines capital intensity and operating cost structures for controlled environment operators. Product configuration shapes facility scalability and geographic deployment flexibility. Crop selection and end-user targeting further refine revenue stability and contract duration profiles.
Technology:
Supply concentration among Dutch and German engineering houses creates lead-time vulnerability for climate-control hardware, pushing operators toward technology platforms with localized component sourcing.
- Hydroponics:Nutrient film and deep-water culture systems circulate mineral solutions through closed loops, eliminating soil-borne pathogens. Dutch greenhouse clusters deploy these systems at scale for tomato and cucumber production, leveraging mature supplier networks near Rotterdam port infrastructure.
- Vertical Farming:Stacked growing layers under LED arrays maximize yield per square meter in urban constraints. Singapore and Tokyo operators favor this configuration where land scarcity amplifies real estate costs and municipal food security mandates justify capital premiums.
- Aeroponics:Mist-based nutrient delivery reduces water consumption below hydroponic baselines. NASA-derived research platforms and pharmaceutical botanical suppliers adopt this precision for rare compound cultivation.
- Aquaponics:Integrated fish-tank nutrient cycling serves niche educational and permaculture markets with dual-output economics.
Hydroponics absorbs the bulk of installed capacity; vertical farming is expanding most quickly.
Product Type:
Cost tier differentiation separates capital-heavy permanent structures from modular units that trade per-unit premiums against deployment speed.
- Greenhouses:Glass or polymer-clad structures with passive solar gain and active heating dominate temperate-zone vegetable production. Netherlands operators achieve scale economies through clustered horticultural technology districts with shared logistics infrastructure.
- Indoor Farms:Fully enclosed warehouse conversions eliminate daylight dependency, enabling multi-story cultivation in dense metropolitan cores. New York and Chicago foodservice procurement contracts increasingly specify these facilities for year-round herb supply.
- Container Farms:Retrofitted shipping units with integrated climate systems penetrate remote mining camps and military installations where logistics costs for fresh produce exceed capital outlay.
- Environments:Research-grade chambers with precise atmospheric control serve university breeding programs and seed-genetics validation.
Greenhouses retain volume leadership across mature markets; container farms are climbing the fastest as institutional buyers prioritize deployment flexibility.
Crop Type:
Application requirements dictate environmental parameter precision, with pharmaceutical and food-safety standards driving facility investment thresholds.
- Vegetables:Leafy greens and vine crops dominate commercial output, with lettuce and spinach commanding the highest automation compatibility for harvest robotics.
- Herbs:Basil, cilantro, and specialty mint varieties attract premium pricing from restaurant groups and packaged-food manufacturers seeking consistent volatile oil profiles.
- Fruits:Strawberry and tomato production concentrates in greenhouse environments where pollination management and extended crop cycles justify infrastructure investment.
- Flowers:Ornamental and cut-flower segments serve event industries and retail floristry with cultivar-specific climate protocols.
Vegetables command the largest cultivation footprint; herbs are gaining share fastest through direct foodservice contracting.
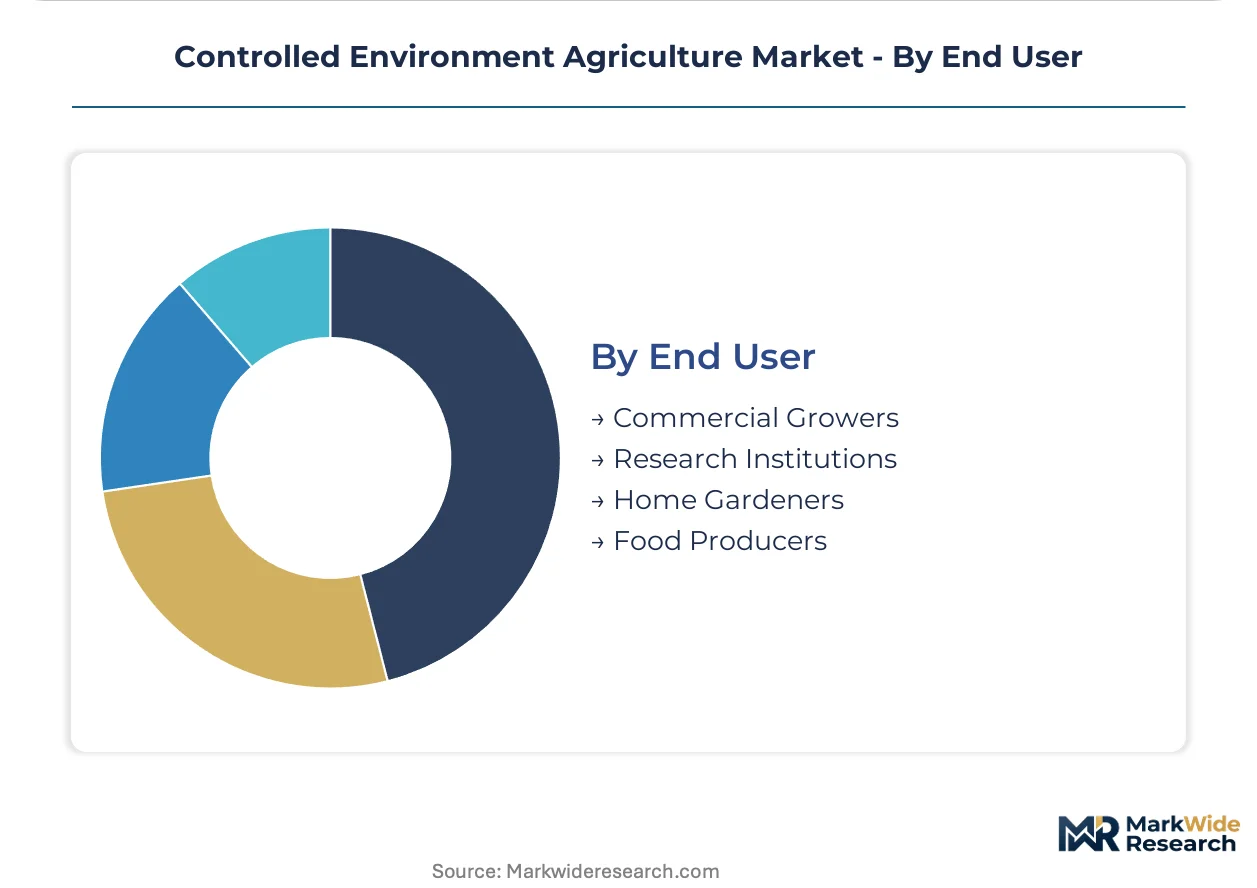
End User:
Customer type determines contract structure, with institutional buyers favoring multi-year supply agreements over spot-market exposure.
- Commercial Growers:Large-scale operators supplying supermarket chains and wholesale distributors drive technology standardization through volume procurement.
- Food Producers:Processed-food manufacturers and ready-meal assemblers contract for ingredient-grade consistency with specified brix and moisture content.
- Research Institutions:Agricultural universities and seed companies fund phenotype validation and breeding acceleration in controlled settings.
- Home Gardeners:Consumer-grade countertop units and small greenhouse kits serve hobbyist markets with limited price elasticity.
Commercial growers anchor facility utilization rates; food producers are expanding contract volumes fastest as traceability requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement contracts concentrate demand in the Netherlands, where clustered greenhouse infrastructure and Rotterdam port access create scale advantages for soilless vegetable exporters. National carbon mandates and water scarcity pressures are redirecting capital toward indoor production across temperate and arid zones alike.
Netherlands
EU Green Deal carbon accounting requirements are consolidating Dutch retailer procurement around greenhouse operators with verified low-carbon certifications. The country's national environmental agency enforces strict nitrogen emission limits that favor closed-loop hydroponic systems over open-field cultivation. Westland municipality hosts the densest concentration of glasshouse technology, where operators supply year-round tomatoes and cucumbers to German and British supermarket chains.
United States
Foodservice operators in New York and Chicago are contracting directly with nearby indoor farms to secure herb supply independent of California field harvests. FDA traceability rules for fresh produce mandate lot-level tracking that advantages controlled environment facilities with integrated sensor infrastructure. The Northeast corridor sees rapid warehouse conversion activity, while California's Central Valley maintains greenhouse leadership for strawberry propagation.
Japan
Metropolitan food security mandates in Tokyo and Osaka are funding large-scale plant factories to reduce vegetable import dependency from China and Southeast Asia. METI subsidizes LED horticulture adoption through energy-efficiency programs targeting commercial growers. Chiba Prefecture hosts the highest density of vertical farming installations, where operators deliver consistent leafy greens to convenience store chains regardless of typhoon disruptions.
United Arab Emirates
Domestic food production targets under the National Food Security Strategy are financing desalination-integrated greenhouses in Dubai and Abu Dhabi. MOHAP regulates agricultural input safety while federal investment funds prioritize water-efficient technologies. Al Ain and Dubai Industrial City concentrate the emirates' controlled environment capacity, supplying hospitality and retail sectors that previously relied entirely on air-freighted European produce.
Singapore
Thirty-by-thirty food self-sufficiency targets are accelerating rooftop and warehouse farm deployment in this land-constrained city-state. The Singapore Food Agency licenses indoor vegetable production with stringent pesticide residue standards that exclude most Malaysian field imports. Lim Chu Kang and industrial zones in Jurong host the majority of vertical farming operations, where producers contract directly with NTUC FairPrice and Cold Storage supermarket networks.
Controlled Environment Agriculture Market Vendor Landscape
Capacity expansion dominates the current landscape as operators race to lock in multi-year supply agreements with institutional buyers before field agriculture recovers cost advantages. The vendor base separates into three tiers: venture-backed vertical farming specialists, established greenhouse networks with decades of cultivar expertise, and modular container farm fabricators targeting remote deployment. Technology licensing and strategic partnerships represent the primary competitive moves, with equipment suppliers bundling climate-control systems with cultivation management software to secure long-term service contracts.
Among North American greenhouse specialists, Gotham Greens and Lufa Farms exemplify the metropolitan-proximity archetype, positioning enclosed production facilities within distribution range of dense urban foodservice markets. AeroFarms anchors the vertical farming tier with stacked aeroponic configurations designed for maximum yield per square meter in high-real-estate-cost environments. These three entities represent distinct capital intensity profiles, from the moderate infrastructure requirements of glasshouse conversion to the substantial LED and climate-system investment demanded by fully enclosed warehouse operations.
| Leading Market Players |
|---|
| Mirai |
| Gotham Greens |
| AeroFarms |
| YesHealth Group |
| Planet Farms |
| Jingpeng |
| Lufa Farms |
| GrowUp Farms |
| Bowery Farming |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting requirements gate qualified supply access and premium-tier pricing for controlled environment agriculture operators, with Dutch and German supermarket chains now requiring verified low-carbon certifications as table stakes for contract eligibility. This regulatory filter compresses margin pools for uncertified field agriculture while elevating price floors for indoor operators with documented water and pesticide savings.
Pricing Analysis
Volume leadership concentrates in hydroponic greenhouse tomatoes and cucumbers where Dutch operators compete on scale, while margin capture concentrates in vertical farming configurations serving metropolitan foodservice contracts with just-in-time herb delivery. Three-tier pricing structure across premium, standard, and economy levels separates GMP-compliant pharmaceutical botanical facilities from retail-grade greenhouse operations and commodity container farm outputs. Pricing pressure stems from natural gas exposure in northern European heating cycles, eroding winter margins for glasshouse operators. Food producers with traceability mandates show lowest price sensitivity; institutional caterers with spot-market alternatives remain most elastic.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale buyer demand from hospital systems and corporate cafeteria operators, displacing traditional produce distribution intermediaries in New York and Tokyo metropolitan corridors. Climate-control hardware concentrates among Dutch and German engineering suppliers, with LED arrays and sensor platforms drawing from semiconductor fabrication in Taiwan and South Korea. Single-source vulnerability runs through Rotterdam port infrastructure for greenhouse technology clusters. Distribution runs through consolidated vendor lists at major European retailers, with third-party carbon accounting now required for contract renewal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH residue limits and FDA traceability rules create barrier-to-entry moats for operators with integrated monitoring infrastructure, advantaging incumbents with capitalized certification investments over field agriculture exporters facing escalating compliance costs.
For Market Incumbents: Cement multi-year offtake agreements with institutional buyers before field agriculture recovers seasonal cost advantages, prioritizing contract duration over spot-market price flexibility. Lock in utility-scale power purchase agreements to hedge natural gas exposure in northern European production cycles. Deepen backward integration into LED horticulture hardware through strategic partnerships with Dutch engineering suppliers, reducing lead-time vulnerability for climate-control system replacement. For New Entrants and Emerging Players: E-commerce direct-to-consumer subscription channels offer the lowest competitive density for specialty herb varieties with volatile oil profile consistency. Target Middle East institutional demand in UAE and Saudi Arabia, where food security mandates fund desalination-integrated plant factories with reduced import dependency. Penetrate through container farm deployment for remote mining camps and military installations, where logistics cost premiums outweigh capital intensity barriers. For Investors and Strategic Acquirers: METI subsidy announcements for LED horticulture adoption in Japan are the leading indicator that capital allocation toward controlled environment agriculture is accelerating across Asian food security mandates. Prioritize acquisition targets with GMP-compliant facilities capable of supplying pharmaceutical-grade botanicals to CDMOs, where batch consistency commands pricing premiums. Watch for consolidation signals when venture-backed vertical farming specialists face refinancing pressure from energy cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Equipment suppliers bundling climate-control systems with cultivation software secure long-term service contracts. |
| Strategic Partnership | Greenhouse operators partnering with Dutch engineering houses reduce lead times for sensor hardware procurement. |
| Capacity Expansion | Vertical farming specialists adding stacked growing layers in Singapore and Tokyo capture land-scarcity premiums. |
| Backward Integration | Indoor farms developing proprietary LED spectral-tuning recipes compress per-kilogram energy costs. |
| Geographic Expansion | Container farm fabricators penetrating UAE mining camps convert logistics cost premiums into margin capture. |
Methodological Framework
Multi-period observation of EU Green Deal procurement shifts, FDA traceability rule implementation, and METI subsidy disbursements anchored the trend analysis, supplemented by interviews with greenhouse operations directors, foodservice procurement managers, climate-control equipment suppliers, and pharmaceutical CDMO sourcing leads. Secondary validation drew from ECHA REACH filings, FDA fresh produce safety guidance, customs data on horticultural technology imports, and SEC disclosures from venture-backed vertical farming operators. Bottom-up facility capacity estimates triangulated against top-down supermarket procurement contract values.
Segment-weighting approaches modeled technology choice, product configuration, crop type, and end-user contract structure across the analysis window. CAGRs derived from fitted growth curves applied to base-year capacity installations, with trajectory adjustments for energy price scenarios and regulatory enforcement timing. Forecast inputs incorporated LED efficiency improvement curves, desalination cost trends in arid regions, and carbon border adjustment mechanism implementation schedules.
The model holds under stable utility rate structures and sustained carbon mandate enforcement; deviation in wholesale natural gas spikes or phytosanitary protocol fragmentation would shift facility payback assumptions. Forecasts reflect base-case assumptions on technology cost decline and buyer contract duration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
China Greenhouse Horticulture Market