
 GCC Grow Light Market | 2026-2036
GCC Grow Light Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Grow Light Market Intelligence
Buyer concentration in the GCC Grow Light Market is shifting from fragmented small-scale greenhouse operators toward consolidated commercial agricultural enterprises and sovereign-backed food security ventures. Signify Holding leverages its Philips Horticulture LED portfolio to dominate premium greenhouse installations across the Gulf. OSRAM GmbH anchors the professional cultivation segment with high-output LED modules engineered for arid-climate performance. Gavita International B.V. competes through its legacy HID-to-LED transition programs targeting existing greenhouse infrastructure retrofits.
GCC grow lights are electrically powered luminaires engineered to emit photosynthetically active radiation in the 400–700 nanometer range, with modern LED systems achieving photosynthetic photon flux densities exceeding 2.7 μmol/J while integrating active thermal management for ambient temperatures above 40°C. Their primary commercial purpose is to supplement or replace solar irradiance in controlled-environment agriculture facilities where natural light is insufficient or seasonal. LED product types now capture the dominant margin pool as energy efficiency mandates intensify across Gulf utilities, while full-spectrum technology leads R&D investment by eliminating yield gaps between artificial and natural light spectra. Indoor farming applications sustain the fastest growth trajectory as Dubai and Riyadh-based ventures scale multi-story vertical production facilities.
SASO efficiency labeling requirements and UAE ESMA technical regulations for electrical appliances are tightening minimum efficacy standards for imported horticultural luminaires, effectively filtering low-performance suppliers from Gulf markets. The Saudi Food Security Initiative and UAE National In-Country Value programs are channeling procurement toward locally certified equipment vendors who demonstrate supply chain localization. Stakeholders must monitor how evolving Gulf standardization frameworks and sovereign agricultural investment timelines reshape vendor qualification criteria and project finance structures.
Market Dynamics
LED spectrum-tunable systems are compressing payback periods for controlled-environment agriculture operators across the Gulf, triggering wholesale replacement of legacy HID infrastructure in commercial greenhouses.
Growth Catalysts
- Saudi Food Security Initiative:Sovereign capital allocation is accelerating controlled-environment agriculture buildouts in Riyadh and Qassim provinces, creating guaranteed offtake for high-efficacy horticultural luminaires.
- LED thermal management advances:Active cooling architectures rated for ambient temperatures exceeding 40°C are eliminating performance derating penalties that previously constrained Gulf deployment.
- UAE National In-Country Value programs:Procurement preference scoring for localized supply chains is redirecting vendor qualification toward established regional distributors with SASO certification capabilities.
Market Restraints
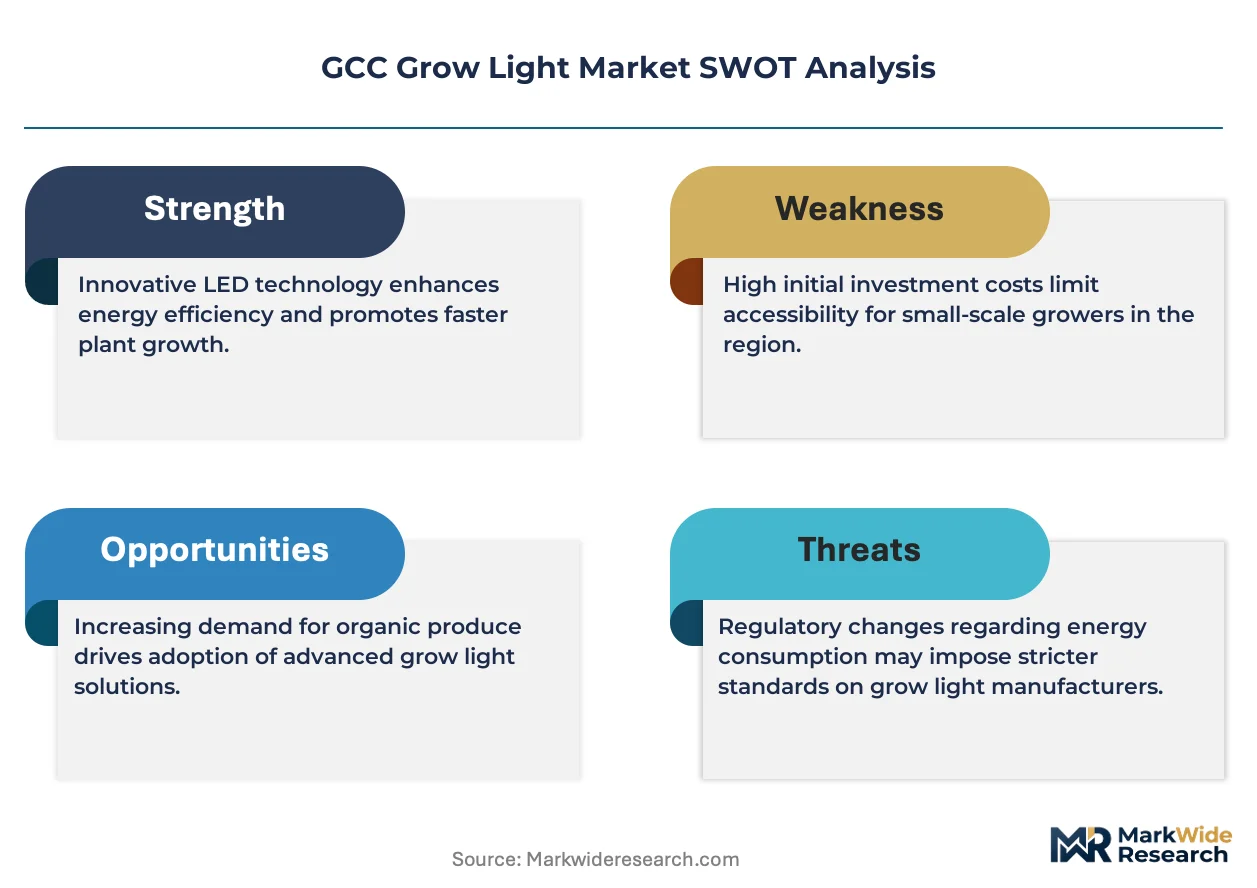
- Import-dependent LED chip supply:Gulf-based luminaire assemblers remain captive to East Asian substrate manufacturers, exposing margin compression from currency volatility and shipping lane disruptions.
- SASO efficacy threshold escalation:Biennial tightening of minimum photosynthetic photon efficacy standards forces premature obsolescence of LED modules that fail to achieve 2.7 μmol/J benchmarks.
- Grid capacity constraints in secondary cities:Utility infrastructure in Dammam and Sharjah industrial zones lacks redundant feeder capacity for multi-megawatt vertical farming loads, delaying project energization.
Strategic Opportunities
- Oman and Bahrain penetration:Nascent controlled-environment agriculture sectors in Muscat and Manama present first-mover advantages for vendors with established UAE-Saudi certification pathways.
- Photobiology-as-a-service models:Spectral recipe optimization bundled with hardware leases is displacing capital-heavy luminaire purchases among mid-scale greenhouse operators.
- Integrated environmental control convergence:Grow light systems merging with HVAC and irrigation telemetry are capturing premium positioning in Dubai's automated vertical farming facilities.
Industry Challenges
- Horticultural lighting engineering talent scarcity:Gulf universities produce minimal photobiology specialists, forcing reliance on expatriate technical staff with limited regional tenure stability.
- Multi-standard certification complexity:Simultaneous SASO, ESMA, and G-Mark compliance requirements extend product launch timelines by eight to fourteen months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Grow Light Market |
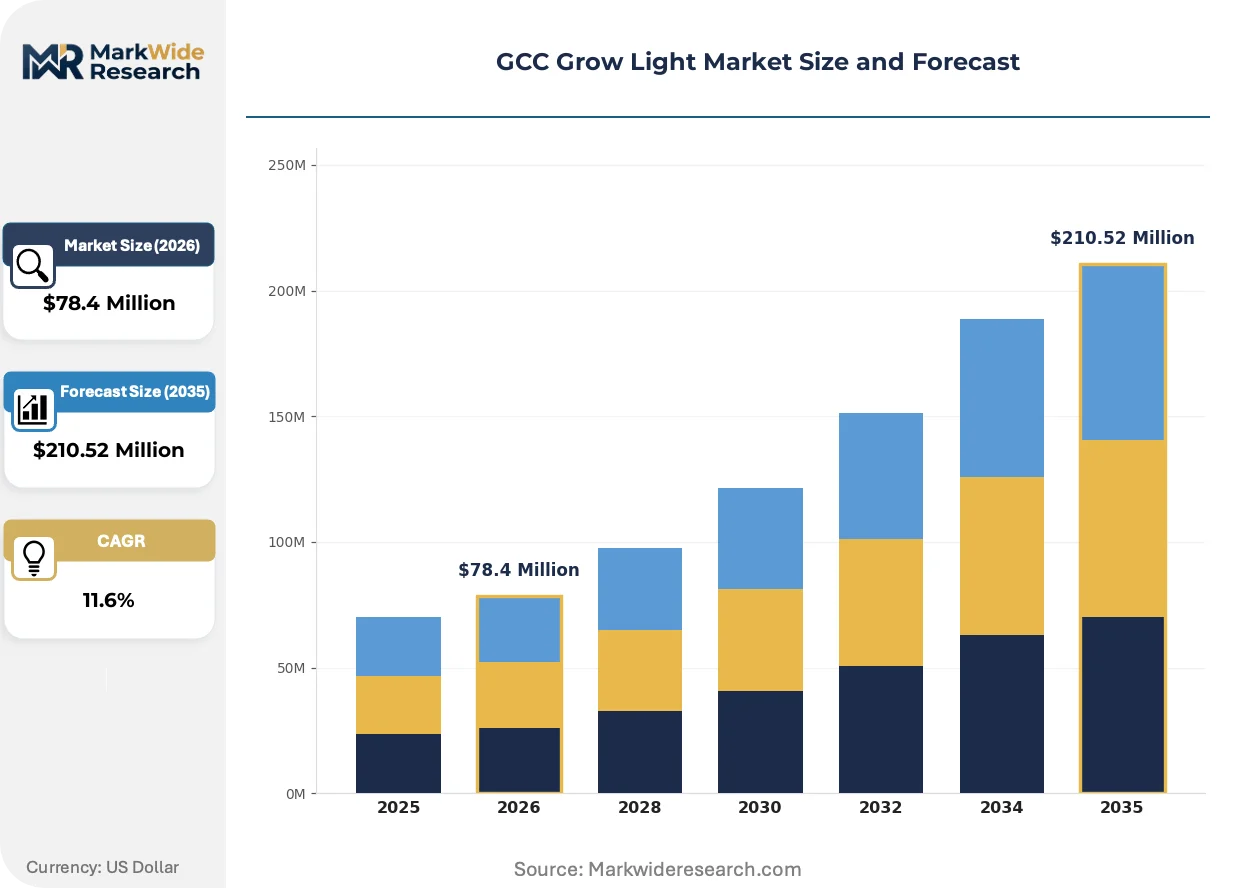
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $210.52 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HID, Fluorescent, HPS Application: Indoor Farming, Greenhouses, Vertical Farming, Hydroponics Technology: Smart Lights, Full Spectrum, T5, T8 End User: Commercial Growers, Home Gardeners, Research Institutions, Agricultural Enterprises |
| Companies Covered | Signify Holding, OSRAM GmbH, ams-OSRAM AG, Heliospectra AB, Gavita International B.V., Savant Systems Inc., EVERLIGHT ELECTRONICS CO., LTD, Lemnis Oreon B.V., Hortilux Schréder, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Grow Light Market Strategic Shifts & Innovations
Spectral precision engineering and integrated environmental control architectures are compressing the performance gap between artificial and solar irradiance, enabling crop varieties previously considered impossible under Gulf climate conditions.
Dynamic full-spectrum LED arrays with per-channel dimming granularity down to one-percent increments are rewriting yield optimization protocols for high-value leafy greens and vine crops. Commercial greenhouse operators in Saudi Arabia's Al-Kharj corridor are deploying these systems at scale, collapsing the historical yield penalty between controlled-environment and open-field production for premium export varieties.
UAE ESMA technical regulations for electrical appliances now mandate minimum efficacy thresholds and electromagnetic compatibility testing for all imported horticultural luminaires, effectively filtering uncertified suppliers from Dubai and Abu Dhabi procurement channels. Professional cultivation facilities are responding by consolidating vendor relationships around established SASO-certified manufacturers with in-country technical support infrastructure.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale greenhouse operators in Riyadh and Jeddah. Spectral performance guarantees bundled with predictive maintenance subscriptions transfer operational risk from grower to vendor, aligning luminaire provider incentives with crop outcome metrics rather than hardware shipment volumes.
GCC Grow Light Market Segmentation
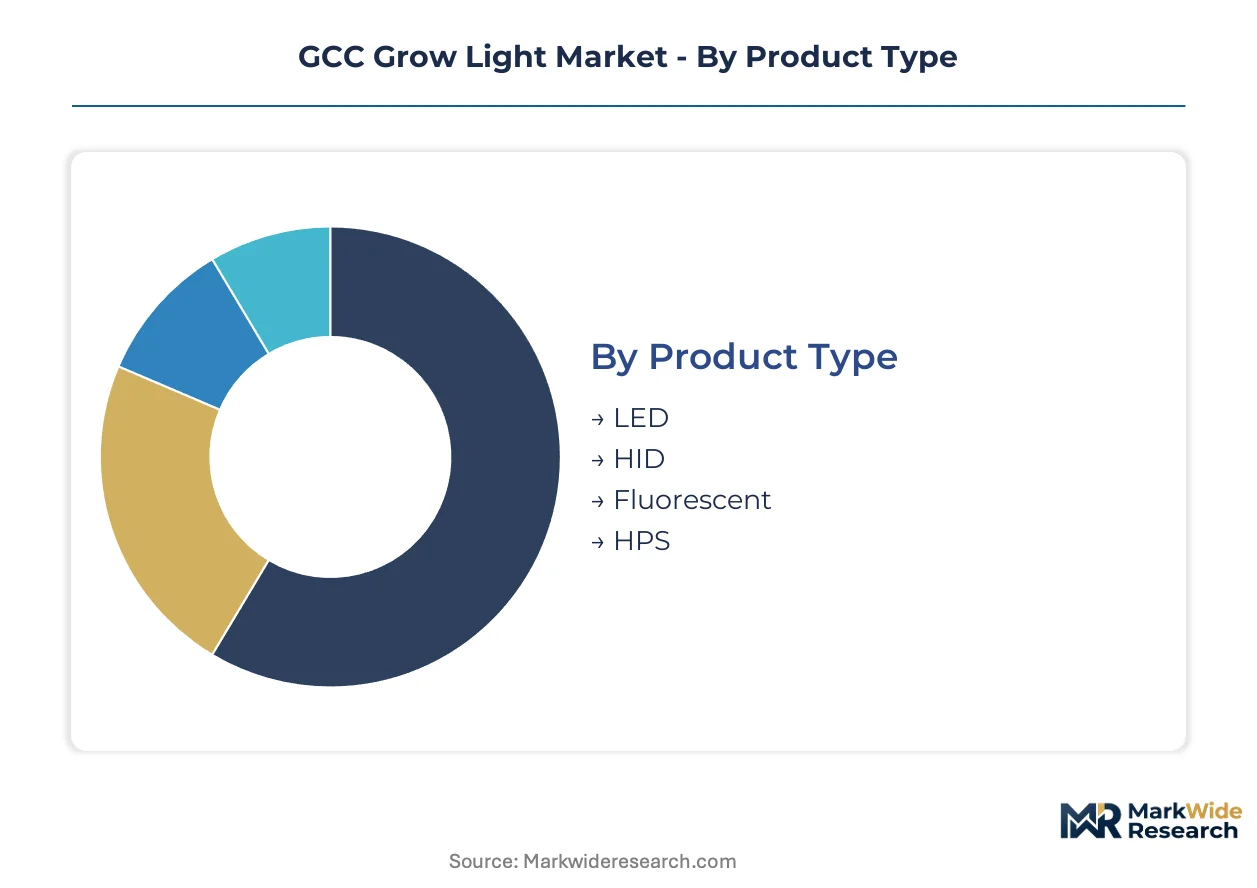
GCC grow light procurement divides sharply across certification requirements, with SASO and ESMA mandates filtering supplier eligibility by product architecture. Segmentation clarity enables vendors to map technical specifications against regulatory pathways and end-use economics.
Product Type:
LED modules require ESMA electromagnetic compatibility testing and SASO energy efficiency labeling, while HID systems face phased efficacy threshold escalations that compress retrofit windows.
- LED:Solid-state arrays achieving photosynthetic photon flux densities above 2.7 μmol/J with active thermal management rated for 40°C-plus ambient operation. Demand concentrates in Riyadh commercial greenhouse retrofits where Saudi Food Security Initiative funding prioritizes SASO-certified high-efficacy installations.
- HID:High-intensity discharge lamps including metal halide and sodium vapor architectures with legacy ballast infrastructure. Operators across Dubai's Al-Aweer agricultural corridor deploy these for transitional hybrid systems while awaiting LED capital allocation cycles.
- Fluorescent:T5 and T8 tube configurations for low-intensity propagation stages.
- HPS:High-pressure sodium systems dominant in legacy greenhouse infrastructure across Qassim province.
Leading the category by volume: LED. Growing fastest: LED.
Application:
Application selection determines grid interconnection scale and utility tariff exposure, with multi-megawatt vertical farms triggering dedicated feeder investments in Dubai and Riyadh.
- Indoor Farming:Fully enclosed cultivation facilities with zero solar dependency requiring 18-24 hour photoperiod management. Dubai-based multi-story ventures in Al-Quoz industrial zone scale these systems for premium herb export production.
- Greenhouses:Solar-supplemented structures using grow lights for season extension and DLI augmentation. Saudi Arabia's Al-Kharj corridor operators deploy spectrum-tunable LED arrays to collapse yield gaps with open-field premium varieties.
- Vertical Farming:Stacked production architectures with precise environmental control integration.
- Hydroponics:Soilless cultivation systems with nutrient film technique pairing.
Vertical farming commands the steepest expansion trajectory. Greenhouses retain the largest installed base.
Technology:
Technology tiering aligns with customer sophistication and outcome-risk tolerance, with smart systems requiring predictive maintenance infrastructure.
- Smart Lights:Networked luminaires with per-channel spectral dimming, environmental sensor integration, and cloud-based recipe management. UAE National In-Country Value procurement scoring favors these systems when bundled with regional technical support.
- Full Spectrum:Broad-wavelength LED arrays engineered to replicate solar spectral distribution across 400-700 nanometer photosynthetic range. Research institutions in Qatar's Education City cluster specify these for comparative photobiology studies.
- T5:Compact fluorescent propagation systems for seedling and cloning stages.
- T8:Standard fluorescent tube configurations for low-intensity supplemental lighting.
Smart lights capture premium positioning. Full spectrum systems gain share fastest in research and export-oriented commercial operations.
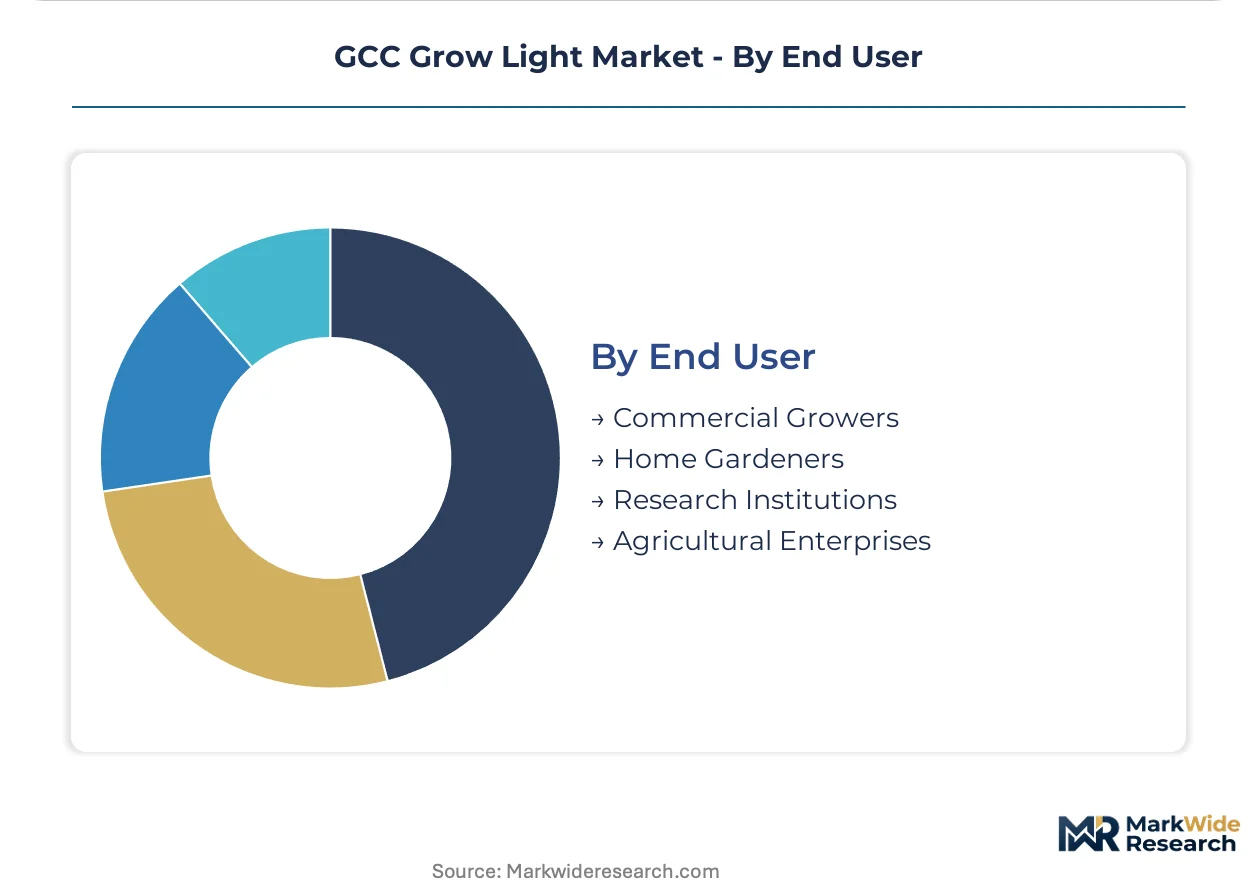
End User:
End-user category determines contract structure, with agricultural enterprises driving equipment-as-a-service adoption and home gardeners constrained by retail channel availability.
- Commercial Growers:Professional greenhouse operators with hectare-scale controlled-environment facilities. Saudi sovereign-backed ventures in Qassim province consolidate procurement around SASO-certified vendors with in-country spare parts logistics.
- Agricultural Enterprises:Vertically integrated food production companies with multi-site operations. Dubai-based entities leverage UAE National In-Country Value scoring to secure long-term spectral performance guarantees bundled with predictive maintenance.
- Home Gardeners:Residential-scale hobbyist cultivators purchasing through retail channels.
- Research Institutions:University and government laboratories conducting photobiology and crop science studies.
Agricultural enterprises lead capital deployment. Commercial growers represent the deepest retrofit opportunity pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia and the UAE, where sovereign food security programs and commercial vertical farming ventures drive procurement of high-efficacy LED systems. SASO and ESMA certification requirements filter supplier eligibility across Gulf markets.
Saudi Arabia
The Saudi Food Security Initiative channels capital toward controlled-environment agriculture buildouts in Riyadh and Qassim provinces. SASO mandates biennial tightening of minimum photosynthetic photon efficacy standards for imported horticultural luminaires. Al-Kharj corridor operators deploy spectrum-tunable LED arrays to collapse yield gaps with open-field premium varieties.
United Arab Emirates
Multi-megawatt vertical farming projects in Dubai's Al-Quoz industrial zone scale fully enclosed cultivation for premium herb export production. UAE National In-Country Value programs redirect procurement toward vendors with localized supply chains and ESMA certification capabilities. Dubai and Abu Dhabi consolidate vendor relationships around established SASO-certified manufacturers with in-country technical support infrastructure.
Oman
Nascent controlled-environment agriculture sectors in Muscat present first-mover advantages for vendors with established UAE-Saudi certification pathways. The country's national standards body aligns horticultural equipment regulations with Gulf Cooperation Council technical harmonization frameworks. Muscat-based agricultural ventures pilot LED retrofits for greenhouse season extension.
Qatar
Research institutions in Qatar's Education City cluster specify full-spectrum LED arrays for comparative photobiology studies. The national food security strategy emphasizes technology transfer partnerships for controlled-environment agriculture infrastructure. Doha-area demonstration facilities test integrated environmental control systems merging grow lights with HVAC telemetry.
Bahrain
Manama's emerging commercial greenhouse sector attracts vendors leveraging existing Gulf certification portfolios. The electricity and water authority evaluates dedicated feeder capacity for agricultural load clusters. Northern Governorate farming cooperatives pilot equipment-as-a-service contracting models for mid-scale operations.
GCC Grow Light Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue spectrum-as-a-service and integrated environmental control bundling. The vendor base stratifies across three tiers: multinational lighting conglomerates with horticulture divisions, specialized LED module fabricators, and regional assemblers serving price-sensitive retrofit segments. Strategic archetypes include certification-heavy incumbents, thermal-engineering specialists, and pay-for-performance service innovators. Dominant competitive moves center on SASO/ESMA certification pre-positioning and predictive maintenance subscription bundling.
Among Netherlands-based horticultural lighting specialists, Signify Holding and Gavita International B.V. exemplify the certification-heavy incumbent archetype, leveraging established Gulf regulatory pathways. OSRAM GmbH anchors the German-engineered professional cultivation segment. These three entities occupy positions across the premium-to-standard tier boundary, with their geographic origins signaling divergent technical heritage and market access strategies.
| Leading Market Players |
|---|
| Signify Holding |
| OSRAM GmbH |
| ams-OSRAM AG |
| Heliospectra AB |
| Gavita International B.V. |
| Savant Systems Inc. |
| EVERLIGHT ELECTRONICS CO., LTD |
| Lemnis Oreon B.V. |
| Hortilux Schréder |
| Others |
Cost & Logistics Intelligence
Sovereign-backed agricultural enterprises in Saudi Arabia and the UAE concentrate procurement volume, compressing supplier margins through long-term performance-based contracts and SASO certification requirements. Their scale dominance forces tiered pricing structures that separate premium LED systems with active thermal management from standard retrofit modules and economy fluorescent propagation units.
Pricing Analysis
Volume concentrates in the mid-tier, while margins pool in premium smart-lighting subscriptions bundled with spectral recipe optimization. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service depth. Pricing pressure stems from biennial SASO efficacy threshold escalations that obsolete sub-2.7 μmol/J modules. Small-scale greenhouse operators exhibit highest price sensitivity; agricultural enterprises with sovereign backing absorb premium positioning for outcome-guaranteed installations.
Supply Chain Analysis
Workforce scarcity for horticultural lighting engineering in the Gulf forces reliance on East Asian manufacturing clusters in China, South Korea, and Taiwan for LED substrate fabrication. Luminaire assemblers in the UAE and Saudi Arabia draw from imported LED chips, aluminum heat sinks, and driver electronics. Single-source vulnerability to East Asian substrate manufacturers exposes margin compression from currency volatility. Distribution runs through SASO-certified regional distributors with in-country technical support infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC grow light market is becoming a vertical-integration race, with players pursuing backward control over LED chip supply and captive spectral recipe development capabilities to escape East Asian substrate dependency.
For Market Incumbents: Hedge against emerging pay-for-performance service innovators by consolidating certification-heavy positioning through accelerated ESMA electromagnetic compatibility pre-clearance. Defensive capacity addition in Riyadh and Dubai industrial zones captures sovereign-backed project pipelines. Deepen backward integration into driver electronics assembly to offset LED chip import exposure.
For New Entrants and Emerging Players: Begin with Oman and Bahrain's nascent controlled-environment agriculture sectors, where established UAE-Saudi certification pathways create first-mover shelter from incumbent saturation. Muscat-based greenhouse retrofits present the most penetrable geography. A photobiology-as-a-service go-to-market angle displaces capital-heavy luminaire purchases among mid-scale operators.
For Investors and Strategic Acquirers: The window for entry favors thermal-engineering specialists with active cooling architectures rated for 40°C-plus ambient operation. Long-term viability hinges on spectral precision capabilities converging with integrated environmental control systems. Watch for SASO efficacy threshold announcements as the inflection signal triggering replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Pre-Positioning | Biennial efficacy escalations filter uncertified suppliers from Riyadh and Dubai procurement channels. |
| Predictive Maintenance Subscription Bundling | Equipment-as-a-service contracts transfer operational risk from Saudi growers to luminaire vendors. |
| Backward Integration into Driver Electronics | In-house production of thermal management components reduces East Asian substrate dependency exposure. |
| Spectral Recipe Development Capability | Captive photobiology expertise enables premium positioning in Dubai's automated vertical farming facilities. |
| Regional Distribution Infrastructure Buildout | UAE National In-Country Value scoring favors vendors with localized spare parts logistics networks. |
Research Approach
Multi-period observation of SASO efficacy threshold escalations, sovereign agricultural investment timelines, and LED thermal management patent filings anchored the trend analysis, supplemented by interviews with commercial greenhouse operators, luminaire procurement managers at agricultural enterprises, spectral engineering specialists, and regional certification consultants. Secondary validation drew from ESMA technical regulation filings, SASO energy efficiency labeling databases, GCC customs trade records, and utility interconnection data for controlled-environment agriculture facilities. Bottom-up project pipeline enumeration triangulated against top-down sovereign budget allocation disclosures.
Input-output matrices mapped photosynthetic photon flux density requirements across application segments—indoor farming, greenhouses, vertical farming, and hydroponics—against technology tiers including smart lights, full spectrum, and legacy fluorescent systems. CAGRs were derived from installed base replacement cycles, retrofit windows for HID-to-LED transitions, and sovereign funding commitment trajectories across the analysis window. Forecast inputs incorporated grid capacity expansion timelines in secondary cities and spectral precision engineering R&D investment flows.
Regulatory timeline acceleration, LED chip supply disruption severity, and sovereign agricultural budget reallocation are the dominant revision risks to projection assumptions. Material deviation in any trigger warrants strategic pause and re-evaluation of vendor qualification criteria and project finance structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Vertical Farming Lighting Market