
 Aeroponics Market | 2026-2036
Aeroponics Market Size, Share, and Industry Trends Forecast 2026-2036
Aeroponics Market Intelligence
CE marking under the EU Machinery Directive is redrawing competitive boundaries for equipment suppliers seeking European market access. AeroFarms sustains technology leadership through proprietary LED recipes and closed-loop nutrient architectures. Freight Farms dominates containerized system deployment with modular units engineered for extreme climates. LettUs Grow Ltd. differentiates through ultrasonic misting technology that eliminates clogging in high-pressure delivery lines.
Aeroponics suspends plant roots in air and delivers nutrients via atomized mist, achieving water-use efficiency above ninety percent compared with conventional soil cultivation while requiring precise control of droplet size between twenty and fifty microns. The primary commercial purpose centers on year-round production of high-value crops in environments where arable land or freshwater constraints render traditional agriculture uneconomical. Vertical system configurations currently anchor the largest installed base, though container formats are gaining fastest among commercial growers seeking rapid deployment and relocation flexibility. Leafy greens occupy the dominant crop category by volume, while microgreens command premium pricing through restaurant and direct-to-consumer channels.
FDA food safety modernization rules, USDA organic certification standards, and EPA agricultural water quality frameworks collectively shape compliance costs and operational protocols for domestic operators. The EU Green Deal and F-Gas Regulation are accelerating refrigerant transitions and energy-efficiency mandates across European installations. Stakeholders must monitor evolving national organic equivalency agreements and local building codes for vertical farm structures as these determine where capital can deploy profitably.
Market Dynamics
Water scarcity across arid regions is compressing payback periods for mist-based cultivation systems, while CE marking under the EU Machinery Directive is fragmenting equipment supplier access to European commercial growers.
Growth Catalysts
- Desert farming initiatives:The United Arab Emirates government-backed food security programs are accelerating capital deployment into controlled-environment agriculture for domestic production.
- EU F-Gas Regulation:Refrigerant transition mandates are forcing energy-efficiency upgrades across European installations, favoring closed-loop nutrient architectures.
- Ultrasonic misting:Commercial growers in water-stressed regions are adopting clog-free delivery systems to reduce maintenance downtime in high-pressure lines.
Market Restraints
- Precision component costs:Droplet control systems requiring twenty-to-fifty micron calibration depend on specialized nozzle manufacturing concentrated in German and Japanese supply bases.
- USDA organic certification pathways:Indoor agriculture operators face tightening compliance timelines and audit costs that extend facility commissioning by six to eighteen months.
- Soil-based greenhouse substitution:Substrate cultivation in the Netherlands and Spain retains cost advantages for commodity leafy greens in moderate climates.
Strategic Opportunities
- Saudi Arabia NEOM project:Giga-scale urban developments are embedding vertical farm infrastructure into master-planned food districts with sovereign capital backing.
- Container format deployment:Modular units engineered for extreme climates enable rapid relocation flexibility for commercial growers pursuing contract farming arrangements.
- FDA food safety modernization:Preventive control mandates for agricultural water quality are creating competitive differentiation for operators with validated closed-loop systems.
Industry Challenges
- Control systems integration:Facility engineers report skill gaps in programming nutrient dosing algorithms synchronized with LED spectral output.
- Building code fragmentation:Local jurisdictions lack standardized classifications for vertical farm structures, delaying permitting in California, Texas, and Illinois municipalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeroponics Market |
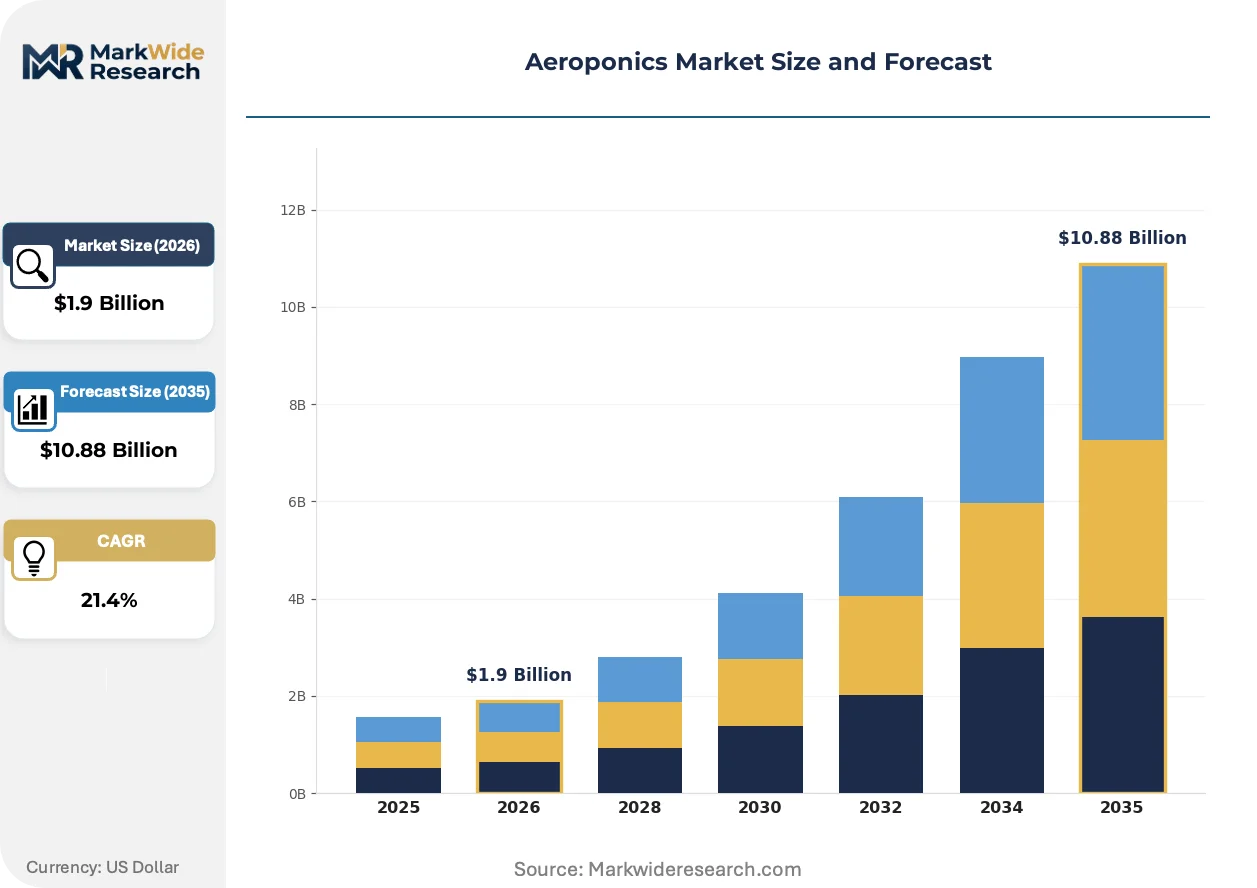
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Vertical, Mobile, Tower, Container Crop Type: Leafy Greens, Herbs, Fruits, Microgreens Technology: Automation, Sensors, Lighting, Nutrient Delivery End User: Agriculture, Research Institutions, Homeowners, Commercial Growers |
| Companies Covered | AeroFarms, Freight Farms, LettUs Grow Ltd., Aponic Ltd., Aeroponic Systems Ltd., BrightFarms, AERO Development Corp, Evergreen Farm Oy, Living Greens Farm Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeroponics Market Strategic Shifts & Innovations
Atomization technology is compressing operational boundaries between precision agriculture and pharmaceutical-grade manufacturing, while regulatory energy mandates are redrawing equipment specification requirements.
Ultrasonic mist generation is decomposing the legacy high-pressure pump architecture that dominated aeroponics infrastructure for three decades. Commercial operators in the United Arab Emirates and Saudi Arabia are retrofitting existing vertical facilities with piezoelectric transducer systems. This transition is decomposing maintenance cost structures and enabling continuous operation in high-salinity water conditions that previously caused catastrophic nozzle failure.
The EU Green Deal and accompanying F-Gas Regulation are accelerating refrigerant phase-down timelines for climate control systems in controlled-environment agriculture. European equipment suppliers must now certify heat pump and cooling units against stricter global warming potential thresholds. Installations in the Netherlands and Denmark are responding with ammonia-based and CO2 transcritical systems that exceed baseline efficiency mandates.
Direct-to-consumer subscription models are displacing traditional wholesale distribution for microgreens and specialty herbs. Restaurant procurement departments in New York, London, and Singapore are contracting directly with container-farm operators for just-in-time delivery. This channel compression is most visible in premium urban markets where traceability certifications command fifteen-to-thirty percent price premiums over conventional supply.
Aeroponics Market Segmentation
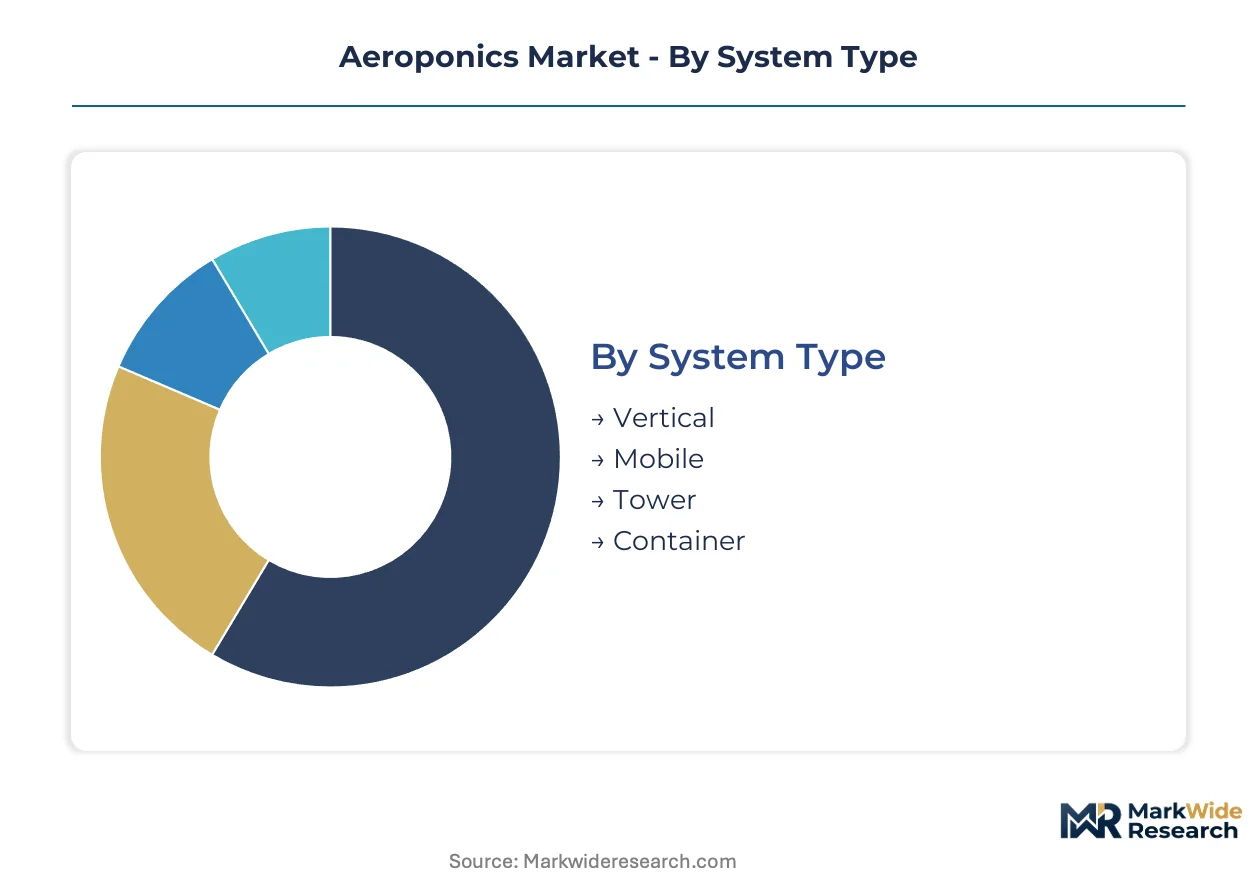
Aeroponics deployments fragment across four structural dimensions that determine capital intensity, operational complexity, and channel economics. System configuration and crop selection anchor upfront investment decisions, while technology stack and end-user profile dictate recurring revenue streams and service attach rates.
System Type:
Vertical configurations dominate wholesale produce channels, while container and mobile formats flow through direct-to-restaurant and subscription retail pathways.
- Vertical:Stacked growing columns maximize cubic footage utilization in fixed warehouse facilities. Demand concentrates in the United Arab Emirates and Saudi Arabia desert farming zones where land scarcity justifies premium structural costs. These systems anchor the largest installed base through government-backed food security capital deployment.
- Container:Repurposed shipping units engineered for rapid deployment and climate isolation. Commercial growers in water-stressed Texas and Arizona municipalities favor this format for contract farming flexibility and permitting speed. The modular architecture enables relocation following lease expiration or utility rate changes.
- Mobile:Trailer-mounted systems designed for seasonal repositioning across agricultural zones. Compact footprint suits research institutions conducting multi-site cultivar trials.
- Tower:Cylindrical configurations optimizing light exposure for high-density herb production. Homeowner segments in Singapore and Tokyo metropolitan areas drive residential adoption.
By volume, Vertical leads. By growth pace, Container formats are expanding most quickly.
Crop Type:
Leafy greens and microgreens command divergent margin structures, with the former flowing through mass retail and the latter extracting premium pricing through chef-direct channels.
- Leafy Greens:Lettuce, spinach, and kale varieties constitute the primary commercial volume. UAE government procurement programs and Saudi NEOM food district contracts anchor demand for consistent year-round supply. FDA food safety modernization rules favor these crops due to established preventive control protocols.
- Microgreens:Concentrated nutrient density drives fifteen-to-thirty percent price premiums in New York, London, and Singapore restaurant markets. Direct-to-consumer subscription models are displacing traditional wholesale distribution for this category.
- Herbs:Basil, cilantro, and specialty varieties target culinary procurement departments. Shorter growth cycles enable rapid inventory turnover for container-farm operators.
- Fruits:Strawberry and tomato cultivars require extended LED spectral programming and elevated nutrient calibration. Research institutions in the Netherlands and Denmark lead experimental deployment.
Leafy Greens generates the highest absolute revenue. Microgreens delivers the steepest expansion trajectory through channel compression.
Technology:
Cost tiers stratify sharply between basic sensor packages and integrated automation stacks that synchronize nutrient dosing with LED output.
- Automation:Programmable logic controllers managing pH, EC, and misting intervals with minimal human intervention. Commercial growers in the United Arab Emirates retrofit facilities to reduce labor costs in high-wage environments.
- Sensors:Real-time monitoring of root zone moisture, ambient humidity, and CO2 concentration. Standard inclusion in mid-tier system specifications.
- Lighting:Proprietary LED spectral recipes optimizing photosynthetic photon flux density for specific cultivars. AeroFarms maintains technology leadership through closed-loop nutrient-light integration.
- Nutrient Delivery:High-pressure pump and ultrasonic misting architectures competing for replacement cycle investment. Piezoelectric transducer systems from LettUs Grow Ltd. eliminate clogging in saline water conditions prevalent in Gulf Cooperation Council installations.
Automation commands the highest attach rate in new installations. Nutrient Delivery technology is gaining share fastest through retrofit demand.
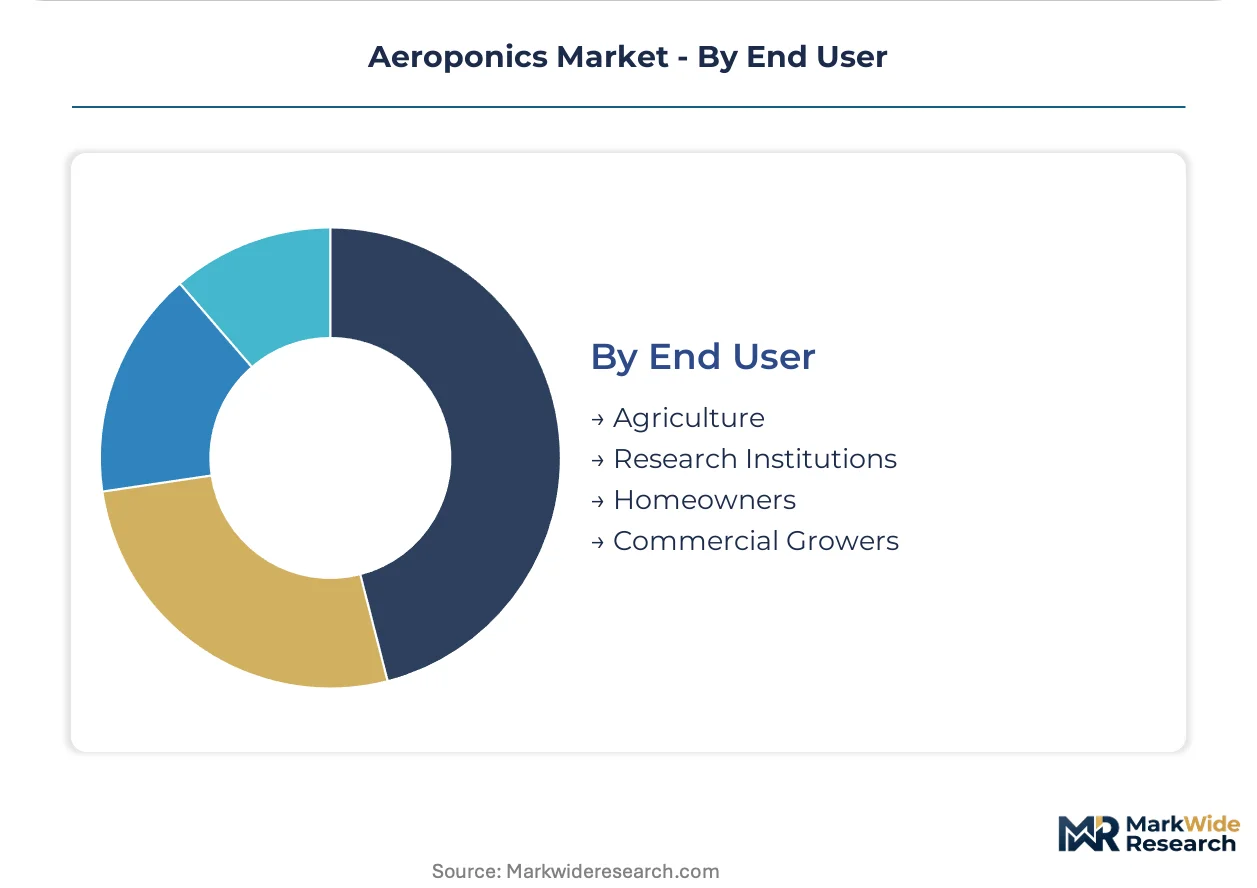
End User:
Customer maturity determines service intensity, with commercial growers requiring full-stack integration and homeowners purchasing simplified turnkey packages.
- Commercial Growers:Professional operators deploying acreage-scale facilities for wholesale and foodservice supply. USDA organic certification pathways and FDA preventive control mandates shape compliance investment. This segment concentrates procurement authority for system vendors.
- Agriculture:Traditional farming enterprises diversifying into controlled-environment production. Water scarcity across arid regions compresses payback period calculations for mist-based adoption.
- Research Institutions:Universities and agricultural extension services conducting cultivar optimization and climate resilience studies. Funding flows through EU Green Deal innovation programs and Saudi sovereign research endowments.
- Homeowners:Residential enthusiasts operating countertop and tower systems for personal consumption. Lower price sensitivity enables premium positioning for design-forward equipment.
Commercial Growers account for the dominant revenue share. Agriculture segment adoption is climbing the fastest as drought conditions intensify capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers and government procurement departments concentrate capital deployment in water-stressed jurisdictions with sovereign food security mandates. Desert farming initiatives and FDA preventive control compliance are reshaping facility location decisions across North America, Europe, and the Gulf Cooperation Council.
United States
Container-farm operators in Texas and Arizona municipalities pursue contract farming arrangements with restaurant procurement departments. FDA food safety modernization rules mandate validated agricultural water quality systems for leafy green production. The Southwest cluster around Phoenix anchors retrofit demand for ultrasonic misting infrastructure.
United Arab Emirates
Government-backed food security programs accelerate vertical facility construction in Dubai and Abu Dhabi. MOHAP regulations govern controlled-environment agriculture licensing for domestic produce supply. Desert farming zones in Al Ain concentrate the largest installed base of stacked growing columns outside North America.
Saudi Arabia
NEOM giga-scale urban developments embed vertical farm infrastructure into master-planned food districts with sovereign capital backing. SFDA food safety protocols align with import substitution targets under Vision 2030. The Riyadh-Eastern Province corridor hosts experimental strawberry and tomato cultivar trials.
Netherlands
EU F-Gas Regulation refrigerant phase-down timelines force ammonia-based and CO2 transcritical climate control upgrades. EFSA standards for novel food production shape closed-loop nutrient architecture specifications. The Westland greenhouse cluster retrofits existing facilities with piezoelectric transducer misting systems.
United Kingdom
CE marking under the EU Machinery Directive fragments equipment supplier access despite post-Brexit regulatory divergence. Defra sustainable farming incentives support research institution cultivar optimization programs. The Greater London metropolitan area drives direct-to-consumer subscription demand for microgreens through chef-direct channels.
Aeroponics Market Key Industry Players
Player mix skews toward specialized vertical farm technology developers and modular system fabricators. The vendor base concentrates around three strategic archetypes: proprietary LED recipe specialists, container-format engineers, and ultrasonic misting innovators. Competitive moves center on technology licensing agreements and sovereign capital joint ventures for desert farming megaprojects.
Among North American technology developers, AeroFarms and Freight Farms occupy distinct positioning vectors within the premium equipment tier. AeroFarms exemplifies the closed-loop nutrient-light integration archetype through proprietary spectral programming. Freight Farms anchors the container-format deployment segment with modular architecture engineered for extreme climate isolation. LettUs Grow Ltd. represents the ultrasonic misting specialist category, eliminating legacy high-pressure pump dependencies for Gulf Cooperation Council installations.
| Leading Market Players |
|---|
| AeroFarms |
| Freight Farms |
| LettUs Grow Ltd. |
| Aponic Ltd. |
| Aeroponic Systems Ltd. |
| BrightFarms |
| AERO Development Corp |
| Evergreen Farm Oy |
| Living Greens Farm Inc. |
| Others |
Cost & Logistics Intelligence
CE marking under the EU Machinery Directive gates both equipment qualification and price tiering simultaneously, forcing suppliers to absorb certification costs into premium positioning while uncertified competitors retreat to price-sensitive emerging markets. This regulatory filter concentrates margin capture among validated vendors serving commercial growers in the United Arab Emirates and Saudi Arabia, where sovereign procurement mandates favor compliant sourcing.
Pricing Analysis
Cost-plus contracts with aluminum and semiconductor indexation dominate equipment procurement between system vendors and Gulf Cooperation Council developers. Three-tier pricing structure across premium automation stacks, standard sensor packages, and economy lighting modules stratifies by certification depth and after-sales service bundling. Pricing pressure stems from piezoelectric transducer commoditization as Chinese manufacturers enter the ultrasonic misting segment. Commercial growers exhibit highest price sensitivity, while research institutions accept premium positioning for cultivar-specific spectral programming.
Supply Chain Analysis
Just-in-time component flows from German nozzle specialists and Japanese precision pump manufacturers dominate tier-one system assembly, though strategic stockpiling of LED driver modules has emerged following semiconductor allocation volatility. Supply concentration in China for aluminum extrusions and Taiwan for programmable logic controllers creates tariff exposure for North American container-farm fabricators. Distribution runs through direct vendor relationships with sovereign food security programs in the Gulf Cooperation Council and regional equipment distributors serving Texas and Arizona contract farming clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as closed-loop nutrient-light integration creates interoperability dependencies between hardware vendors and cultivar optimization software providers. Ecosystem control points are shifting toward data-layer aggregation.
For Market Incumbents: Shield proprietary LED recipe portfolios through patent thickets around spectral-nutrient synchronization algorithms. Deepen backward integration into piezoelectric transducer manufacturing to neutralize Chinese cost threats in the ultrasonic misting tier. Prioritize certification maintenance under evolving FDA preventive control mandates to lock out unvalidated competitors from foodservice procurement channels. For New Entrants and Emerging Players: USDA organic certification fast-tracks offer penetration pathways into premium retail channels where established players carry legacy compliance debt. Target container-format deployment in water-stressed Texas municipalities where permitting velocity exceeds vertical system timelines. Lead with subscription-based nutrient dosing software to capture recurring revenue before hardware commoditization accelerates. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant phase-down deadlines reshape the acquisition landscape toward ammonia-based climate control specialists with validated European installations. Long-term viability centers on vendors controlling both hardware deployment and cultivar-specific data assets. Monitor SFDA alignment with FDA protocols as the signal indicating Saudi sovereign capital allocation acceleration under Vision 2030 food security targets.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Misting Retrofit Programs | Piezoelectric transducer adoption eliminates nozzle maintenance costs in saline Gulf Cooperation Council water conditions. |
| CE Marking Acceleration Pathways | EU Machinery Directive compliance unlocks procurement access to Netherlands and Denmark greenhouse retrofit demand. |
| Closed-Loop Nutrient Architecture Licensing | Technology transfer agreements capture royalty streams from Saudi NEOM and UAE government-backed vertical farm deployments. |
| Direct-to-Consumer Subscription Platform Buildout | Channel compression in New York and London microgreens markets commands fifteen-to-thirty percent traceability premiums. |
| Ammonia-Based Climate Control Upgrade Partnerships | F-Gas Regulation mandates force efficiency transitions across European installations exceeding baseline global warming potential thresholds. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC equipment supplier filings, EU F-Gas Regulation implementation guidance, and UAE Ministry of Health and Prevention licensing databases. Interviews with vertical farm facility engineers, controlled-environment agriculture procurement officers at sovereign wealth funds, LED spectral programming specialists, and container-farm operators in Texas and Arizona informed demand-side validation. Bottom-up installation counts across Dubai, Abu Dhabi, and Riyadh-Eastern Province corridors triangulate against top-down capital deployment estimates from food security program budgets.
Segmentation dimensions modeled span system configuration, crop category, technology stack tier, and end-user maturity across the projection horizon. CAGRs derive from capacity expansion announcements, retrofit cycle assumptions, and channel shift elasticities in direct-to-consumer microgreens distribution. Cultivar-specific LED recipe adoption curves and ultrasonic misting replacement rates constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained sovereign capital commitment in Gulf Cooperation Council jurisdictions or accelerated FDA enforcement timelines would require recalibration. Forecasts reflect assumptions regarding water scarcity intensity, refrigerant phase-down adherence, and organic certification pathway stability. Revision becomes warranted when container-format permitting velocity in Southwest US municipalities crosses thresholds indicating mainstream adoption inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
United States Grow Light Market