
 Cannabis Vertical Farming Market | 2026-2036
Cannabis Vertical Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Vertical Farming Market Analytics
LED spectral tuning and closed-loop climate control is tilting cultivation economics toward indoor vertical architectures with predictable yields. Agrify Corporation leverages integrated hardware-software platforms to command premium positioning among large-scale operators. Hydrofarm Holdings sustains broad distribution reach across North American growing supply channels. Plenty Unlimited Inc. anchors its model on proprietary crop science adapted from leafy greens to high-value cannabis cultivars.
Cannabis vertical farming deploys stacked grow layers with hydroponic or aeroponic irrigation, precision LED lighting calibrated to 400-700 nm photosynthetic active radiation, and environmental controls maintaining 18-24 hour photoperiods to force flowering or vegetative states; the method exists to maximize biomass per square meter while eliminating pesticide residues and geographic seasonality. Hydroponics and aeroponics installations dominate operational deployments due to mature equipment ecosystems and faster payback periods on capital-intensive buildouts. Commercial growers represent the deepest end-user segment, with research institutions emerging as a high-margin niche for phenotype stabilization and novel cannabinoid production.
FDA guidance on cannabis-derived compounds, state-level track-and-trace mandates such as California's METRC system, and Health Canada's GPP standards for licensed producers collectively dictate facility design, testing protocols, and interstate or international market access. Compliance costs favor operators with capital reserves for validation and documentation infrastructure. Stakeholders must weigh jurisdiction-specific licensing timelines against technology refresh cycles when committing to multi-year facility investments.
Market Dynamics
LED spectral tuning is compressing grow cycles from 12-14 weeks to 8-10 weeks while tightening cannabinoid consistency, forcing legacy greenhouse operators to retool or exit as vertically farmed biomass floods licensed channels.
Growth Catalysts
- California METRC track-and-trace mandates:Compliance infrastructure investments favor capitalized vertical farm operators over small cultivators, consolidating supply relationships with dispensaries seeking audit-ready documentation.
- Closed-loop hydroponic systems:Water recirculation and precision nutrient dosing eliminate pesticide residues while reducing input costs, meeting Health Canada GPP standards for contaminant-free export-grade product.
- Canada's mature provincial distribution frameworks:Ontario Cannabis Store and Alberta Gaming, Liquor and Cannabis procurement specifications now preference indoor-grown flower with verified terpene profiles, locking in multi-year supply agreements.
Market Restraints
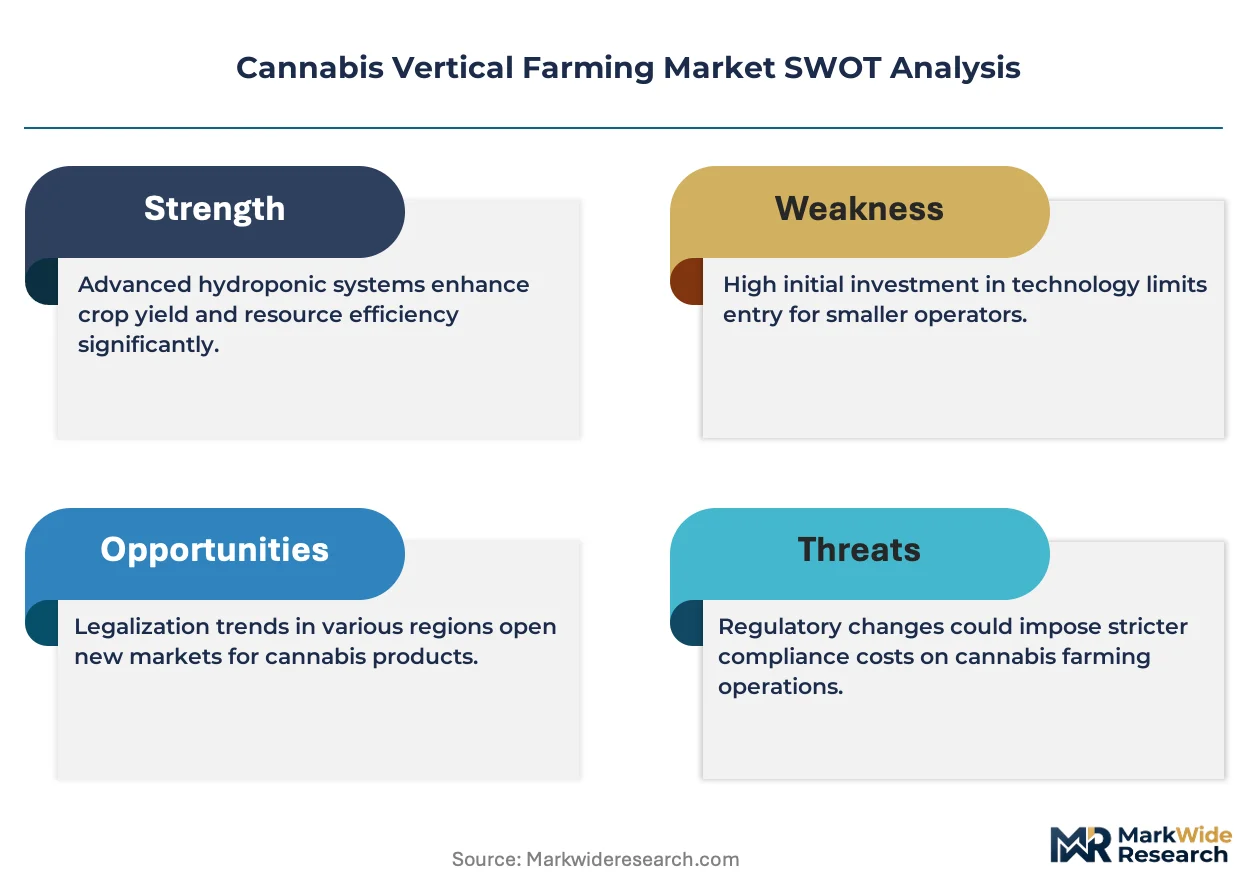
- Capital intensity of LED retrofits:Full-spectrum fixture arrays and climate control infrastructure require USD 800-1,200 per square meter upfront, freezing out undercapitalized entrants.
- Power grid concentration risk:California's rolling blackout exposure and Germany's industrial electricity tariffs create operational vulnerability for facilities without on-site generation or battery storage.
- Substitution from greenhouse-grown biomass:Sun-assisted operations in Colombia and Lesotho deliver comparable THC content at 40-60% lower energy input costs, pressuring indoor premium pricing.
Strategic Opportunities
- Minor cannabinoid isolation:CBG and CBN phenotype stabilization commands 3-5x wholesale premiums over standard THC flower, rewarding facilities with in-house breeding programs and analytical chemistry capabilities.
- German cannabis legalization implementation:Federal Institute for Drugs and Medical Devices (BfArM) licensing opens import pathways for GMP-certified Canadian and Dutch vertical farm output into Europe's largest reimbursed medical market.
- AI-driven environmental optimization:Machine learning integration with sensor networks predicts VPD (vapor pressure deficit) drift before crop stress manifests, compressing R&D cycles for new cultivar introductions.
Industry Challenges
- Master grower talent scarcity:Cross-disciplinary expertise spanning plant physiology, HVAC engineering, and regulatory documentation commands premium compensation, constraining facility expansion timelines.
- Validation protocol complexity:ISO/IEC 17025 accreditation for in-house testing labs requires 18-24 month implementation cycles, delaying product release and cash conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Vertical Farming Market |
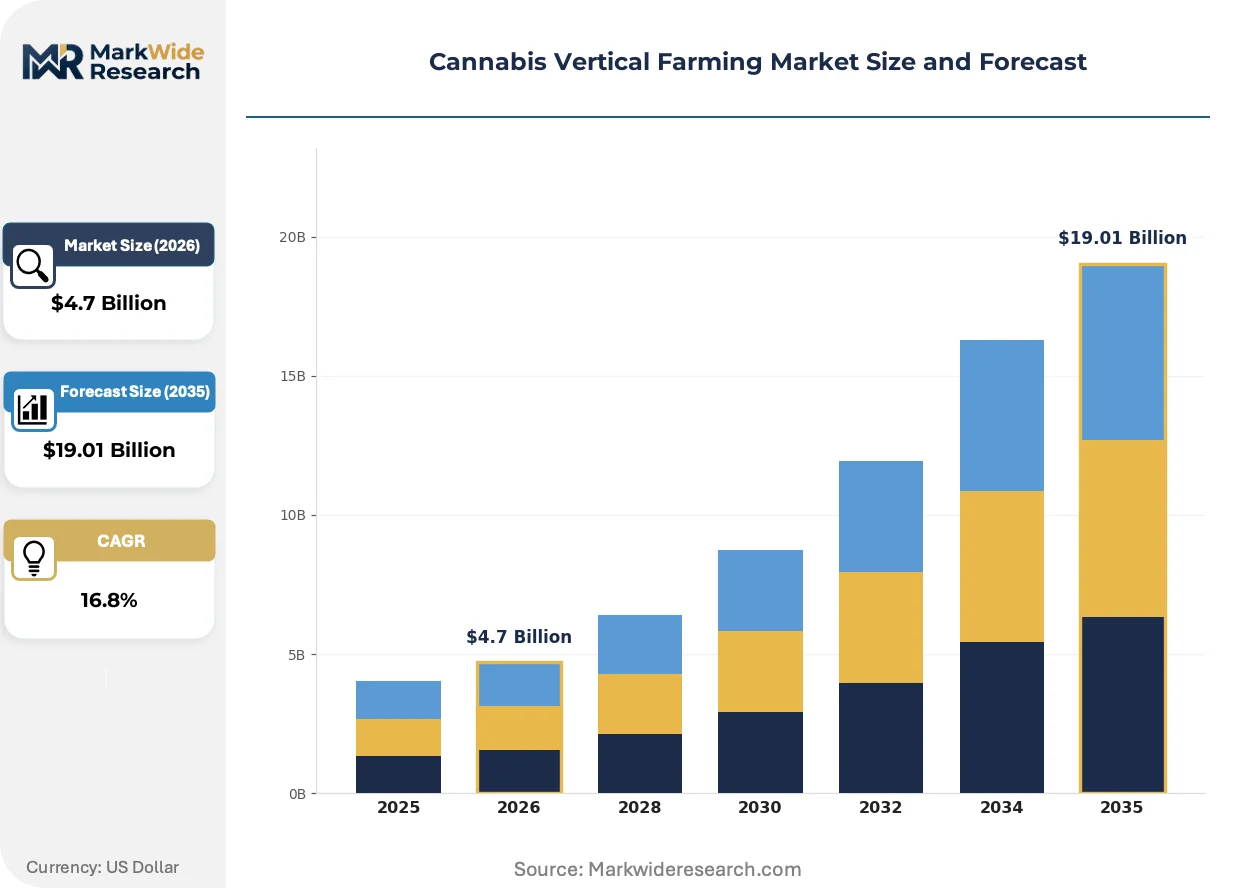
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydroponics, Aeroponics, Nutrient Film Technique, Deep Water Culture Product Type: Seeds, Nutrients, Grow Fixtures, Growth Systems End User: Commercial Growers, Dispensaries, Research Institutions, Home Growers Installation: Indoor Facilities, Greenhouses, Shipping Containers, Retail Outlets |
| Companies Covered | Agrify Corporation, iPower, Village Farms International, Grow Pod Solutions, CubicFarm Systems Corp., Hydrofarm Holdings, Urban-Gro, Plenty Unlimited Inc., GrowGeneration Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Vertical Farming Market Evolving Landscape
Digital twin architectures are replacing physical pilot rooms, compressing cultivar development cycles and reducing wasted biomass during environmental parameter optimization.
Spectral virtualization software is virtualizing the grow environment by simulating photoperiod, spectrum, and intensity combinations before physical deployment. Large-scale Canadian licensed producers are adopting these platforms for phenotype screening, cutting R&D facility requirements by half. The technology is virtualizing capital allocation decisions, shifting investment from redundant grow rooms toward single validation bays with rapid iteration capability.
Health Canada's GPP (Good Production Practices) amendment for microbial testing frequency is tightening facility hygiene protocols. Operators must now implement continuous environmental monitoring rather than batch sampling, driving demand for integrated IoT sensor networks. European Union import specifications are mirroring these standards, forcing export-oriented facilities to upgrade HEPA filtration and surface sanitation systems ahead of German market entry.
Dispensary procurement teams are consolidating supplier relationships around vertically integrated cultivators with verified batch consistency. California's delivery-only licensees and Colorado's hospitality-integrated consumption lounges represent emerging channel concentration, displacing traditional wholesale broker intermediaries. British Columbia's direct farm-to-retail pilot programs are accelerating this disintermediation, rewarding operators with in-house distribution infrastructure.
Cannabis Vertical Farming Market Segmentation
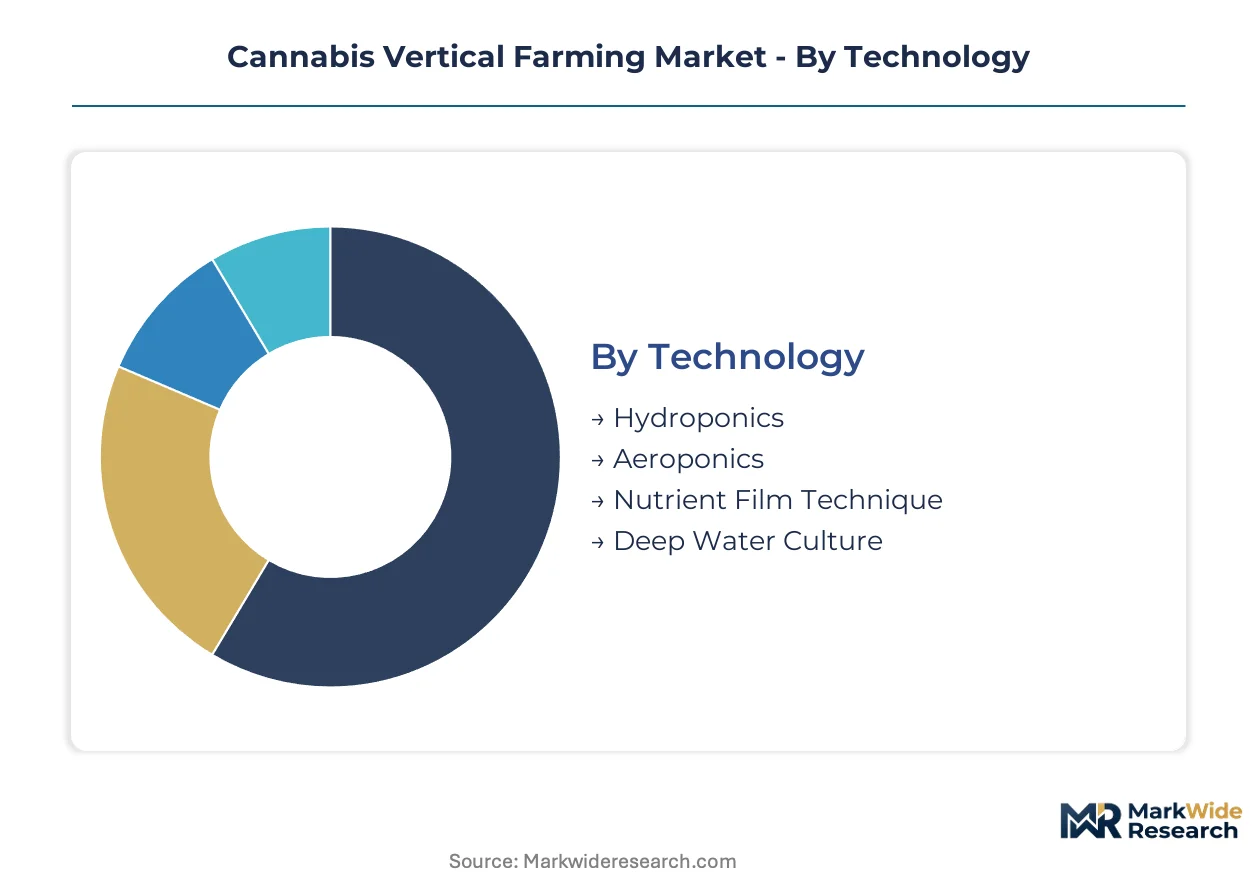
Segmentation in cannabis vertical farming reveals how capital deployment, operational complexity, and regulatory exposure vary across technology choices and customer archetypes. Operators configure their stack based on whether they prioritize speed to revenue, research differentiation, or retail proximity.
Technology:
Cycle times compress dramatically based on irrigation method, with some systems delivering harvest-ready biomass in eight weeks while others extend vegetative phases for phenotype refinement.
- Hydroponics:Water-based nutrient delivery through inert media like rockwool or coco coir dominates commercial deployments due to equipment maturity and predictable root-zone management. California's METRC-tracked cultivators favor this method for batch documentation compliance.
- Aeroponics:Mist-based root feeding maximizes oxygen exposure and accelerates biomass accumulation per square meter, though nozzle maintenance demands specialized technical staff. Health Canada GPP-certified facilities in Ontario deploy this for export-grade flower production.
- Nutrient Film Technique:Thin film recirculation suits high-turnover clone propagation and mother plant maintenance rather than full-cycle flowering.
- Deep Water Culture:Submerged root systems with oxygen injection deliver consistent results for research institutions validating cannabinoid stability across environmental variations.
Hydroponics anchors the volume base while aeroponics gains share at the steepest rate.
Product Type:
Margin structures diverge sharply between consumable inputs with recurring revenue potential and capital equipment requiring multi-year depreciation schedules.
- Grow Fixtures:Full-spectrum LED arrays with tunable diodes command premium positioning due to spectral programmability and energy efficiency metrics. Colorado's licensed operators prioritize DLC-certified fixtures for utility rebate eligibility.
- Growth Systems:Integrated racking, irrigation, and climate control platforms bundle hardware with software analytics, reducing facility commissioning timelines. Large-scale Canadian LPs standardize on these for provincial procurement compliance.
- Nutrients:Precision-formulated hydroponic solutions with batch traceability support contaminant-free certification requirements.
- Seeds:Feminized and auto-flowering genetics with verified cannabinoid profiles enable phenotype consistency for dispensary contract farming.
Growth systems generate the highest contract values while nutrients deliver the most predictable recurring revenue streams.
End User:
Customer sophistication determines whether procurement prioritizes yield optimization, compliance documentation, or experimental flexibility.
- Commercial Growers:Multi-facility operators with provincial supply agreements demand integrated platforms with predictive maintenance and remote monitoring. British Columbia's direct farm-to-retail pilots concentrate demand here.
- Dispensaries:Vertically integrated retail licensees in California and Colorado seek captive cultivation to secure consistent inventory and margin capture.
- Research Institutions:Universities and biotech firms isolate minor cannabinoids for pharmaceutical applications, requiring GMP-grade environmental controls.
- Home Growers:Small-scale enthusiasts drive demand for compact all-in-one systems with simplified automation.
Commercial growers anchor the volume base while research institutions expand most quickly as minor cannabinoid isolation attracts pharmaceutical investment.
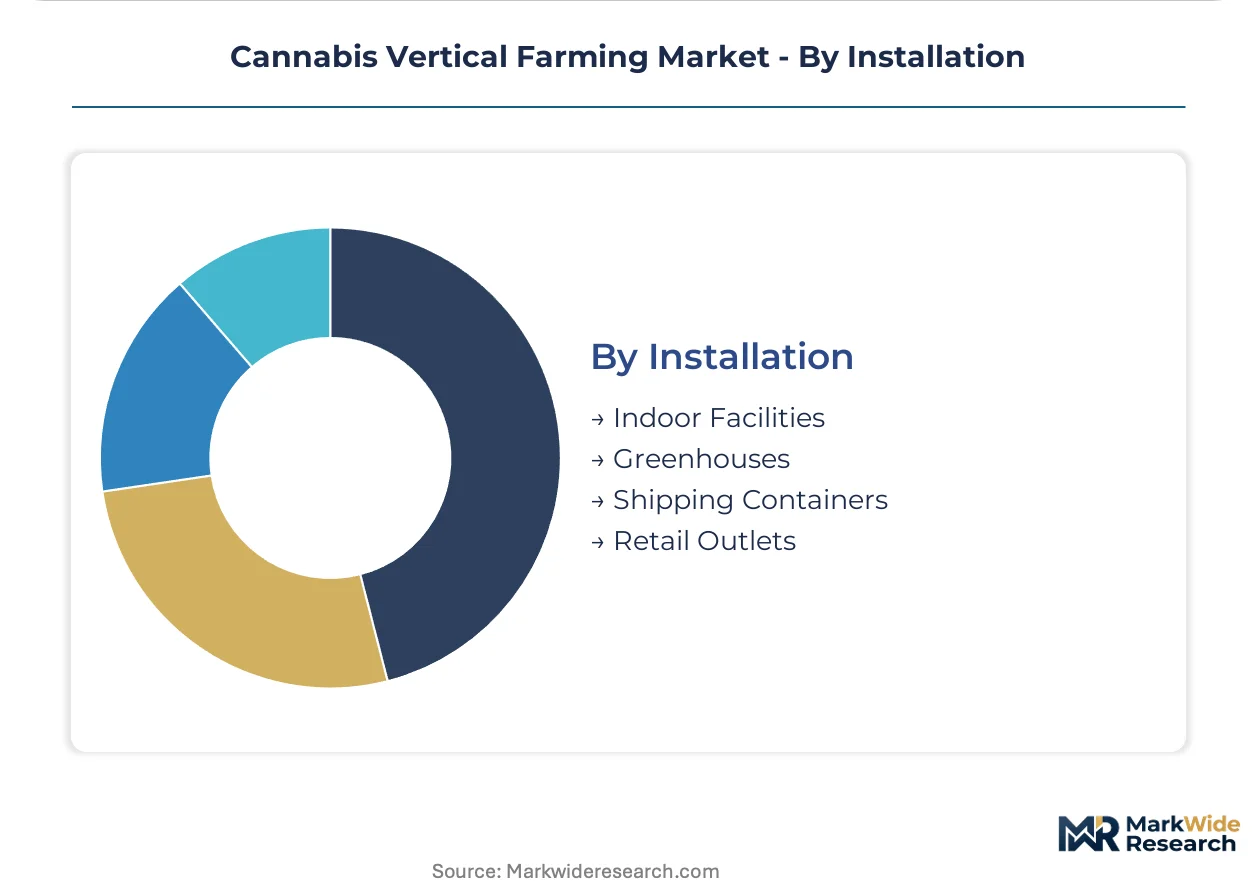
Installation:
Facility architecture dictates capital intensity, regulatory pathway, and proximity to end markets.
- Indoor Facilities:Purpose-built warehouse conversions with redundant HVAC and blackout capabilities support year-round production regardless of external climate. Alberta Gaming, Liquor and Cannabis procurement specifications favor these for terpene profile verification.
- Shipping Containers:Modular deployable units enable rapid market entry in jurisdictions with licensing backlogs, though per-square-meter costs run higher than permanent buildouts. German BfArM import applicants use these for initial GMP qualification.
- Greenhouses:Hybrid light-assisted structures reduce energy costs in favorable climates while maintaining environmental control for flowering phases.
- Retail Outlets:Micro-cultivation co-located with consumption lounges in Colorado and emerging hospitality-integrated channels.
Indoor facilities anchor the volume base while shipping containers gain share fastest among new market entrants seeking licensing speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented Canadian producers command premium positioning in Germany's reimbursed medical cannabis market, while California's domestic oversupply constrains cross-state shipment economics. Import demand from emerging European markets is reshaping facility investment timelines across North American cultivation zones.
United States
California's METRC track-and-trace infrastructure and Colorado's hospitality-integrated consumption lounges concentrate procurement demand for consistent indoor-grown biomass. State-level licensing fragmentation prevents interstate commerce, forcing multi-jurisdiction operators to replicate facilities. Los Angeles and Denver anchor the highest density of vertically integrated dispensary-cultivator operations.
Canada
Ontario Cannabis Store and Alberta Gaming, Liquor and Cannabis procurement specifications now preference verified terpene profiles from controlled-environment production. Health Canada's GPP standards for microbial testing drive facility upgrade cycles among licensed producers. British Columbia's direct farm-to-retail pilot programs accelerate disintermediation, rewarding operators with captive distribution infrastructure.
Germany
Federal Institute for Drugs and Medical Devices licensing opens import pathways for GMP-certified North American vertical farm output into Europe's largest reimbursed medical market. Industrial electricity tariffs and stringent building codes elevate capital requirements for domestic cultivation. Berlin and Hamburg concentrate import distribution infrastructure for pharmacy-channel fulfillment.
Netherlands
Office of Medicinal Cannabis specifications for standardized cannabinoid content align with vertically farmed production consistency. Research institutions in Wageningen pioneer phenotype stabilization protocols for minor cannabinoid isolation. The country's greenhouse horticulture expertise transfers to controlled-environment cannabis architecture, though energy transition policies complicate fossil-fuel-dependent climate control.
Colombia
Equatorial sun-assisted greenhouse operations deliver comparable THC content at reduced energy input costs, pressuring indoor premium pricing in export markets. National licensing frameworks for psychoactive cannabis exports remain under development, constraining facility investment certainty. Bogotá and Medellín concentrate regulatory advocacy and early pilot cultivation zones.
Cannabis Vertical Farming Market Competitive Landscape
On the supply side, the industry is consolidating around capitalized operators with multi-facility footprints and integrated hardware-software platforms. Tiered competitive positioning separates integrated cultivation-technology providers from pure-play equipment vendors and regional cultivation specialists. Dominant competitive moves include strategic partnerships between lighting manufacturers and climate control specialists, plus capacity expansion into German import-qualified production.
Among North American integrated platform providers, Agrify Corporation and Hydrofarm Holdings exemplify contrasting archetypes: the former anchors bundled hardware-software offerings for large-scale operators, while the latter sustains broad distribution reach across supply channels. Plenty Unlimited Inc. occupies a distinct position translating proprietary crop science from leafy greens to high-value cannabis cultivars.
| Leading Market Players |
|---|
| Agrify Corporation |
| iPower |
| Village Farms International |
| Grow Pod Solutions |
| CubicFarm Systems Corp. |
| Hydrofarm Holdings |
| Urban-Gro |
| Plenty Unlimited Inc. |
| GrowGeneration Corp. |
| Others |
Value Network & Pricing Analysis
California METRC compliance infrastructure acts as a regulatory chokepoint that widens pricing spreads between audit-ready premium tiers and undocumented economy supply while simultaneously concentrating procurement relationships around capitalized operators with validated batch documentation systems.
Pricing Analysis
Full-spectrum LED fixture pricing gaps separate current-generation tunable diode arrays from prior-generation fixed-spectrum units and next-generation AI-integrated spectral virtualization platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with Health Canada GPP-certified biomass commanding wholesale premiums over non-validated output. Pricing pressure stems from Colombian sun-assisted greenhouse imports delivering comparable THC content at reduced energy input costs. Dispensary procurement teams exhibit lowest price sensitivity for verified terpene consistency, while wholesale broker intermediaries face margin compression from direct farm-to-retail channel disintermediation.
Supply Chain Analysis
Contract manufacturing concentration for LED grow fixtures centers on specialized horticultural lighting foundries in China, South Korea, and the Netherlands, with climate control equipment production anchored in Germany and the United States. Critical input dependencies span precision nutrient formulations, feminized seed genetics, and HEPA filtration systems. Single-source vulnerability concentrates in advanced spectral diode supply, where semiconductor fabrication capacity constraints create procurement bottlenecks for large-scale facility retrofits. Distribution runs through provincial cannabis distribution authorities in Canada, licensed dispensary direct procurement in California and Colorado, and pharmacy-channel fulfillment networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cannabis vertical farming exhibits structural fragmentation across technology tiers, cultivation scales, and regulatory jurisdictions, with minor cannabinoid isolation creating specialized niches for phenotype stabilization expertise.
For Market Incumbents: Harden compliance documentation infrastructure against Health Canada GPP amendment requirements for continuous environmental monitoring rather than batch sampling. Deepen backward integration into feminized seed breeding programs to secure captive supply of verified cannabinoid profiles. Defend market position by accelerating AI-driven environmental optimization deployment before greenhouse import competition intensifies. For New Entrants and Emerging Players: Establish a beachhead in German BfArM import qualification pathways for GMP-certified Canadian output, where domestic cultivation capital requirements create supply gaps. Target shipping container modular deployments for rapid licensing in jurisdictions with facility approval backlogs. Pursue research institution partnerships for minor cannabinoid phenotype stabilization contracts as the most penetrable high-margin segment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors capitalized operators with multi-facility footprints and integrated hardware-software platforms. Long-term viability hinges on regulatory compliance infrastructure amortization across multi-year provincial supply agreements. Prioritize acquisition targets with in-house analytical chemistry capabilities and ISO/IEC 17025 accreditation progress. Monitor German Federal Institute for Drugs and Medical Devices import license issuance velocity as the critical inflection signal for North American export demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Environmental Optimization | Machine learning integration with sensor networks compresses cultivar development cycles for Canadian licensed producers. |
| GMP Certification Investment | Health Canada GPP standards and German BfArM requirements create qualification barriers for export-market access. |
| Minor Cannabinoid Breeding Programs | CBG and CBN phenotype stabilization commands wholesale premiums from pharmaceutical research institutions. |
| Direct Farm-to-Retail Infrastructure | British Columbia pilot programs and California delivery-only licenses displace traditional wholesale broker intermediaries. |
| Spectral Virtualization Platform Deployment | Digital twin architectures reduce R&D facility requirements by half for large-scale phenotype screening operations. |
Research Methodology
Cross-validation between primary interviews with licensed cultivator operations managers, provincial procurement officers at Ontario Cannabis Store and Alberta Gaming Liquor and Cannabis, master growers, and regulatory compliance directors anchors the qualitative findings against secondary validation from Health Canada GPP amendment filings, FDA guidance documents on cannabis-derived compounds, California METRC track-and-trace system documentation, and SEC filings from publicly traded cultivation technology providers. Bottom-up facility capacity modeling and top-down provincial distribution volume data triangulate market sizing across the analysis window.
Calibration against historical facility commissioning timelines and technology refresh cycles informs the projection framework. Segmentation dimensions span irrigation technology, product type, end-user archetype, and installation architecture, with regulatory jurisdiction clusters modeled separately. CAGRs derive from facility expansion pipeline tracking and provincial supply agreement duration analysis. Industry-specific forecast inputs include LED spectral tuning adoption curves and German import license application velocity.
Stress conditions across electricity tariff volatility, Colombian import competition intensity, and master grower talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline stability and technology cost reduction trajectories. Quarterly review of Health Canada GPP enforcement patterns, German BfArM licensing decisions, and California METRC compliance violation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Europe Grow Light Market