
 Cathode Stripping Machines Market | 2026-2036
Cathode Stripping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cathode Stripping Machines Market Insights
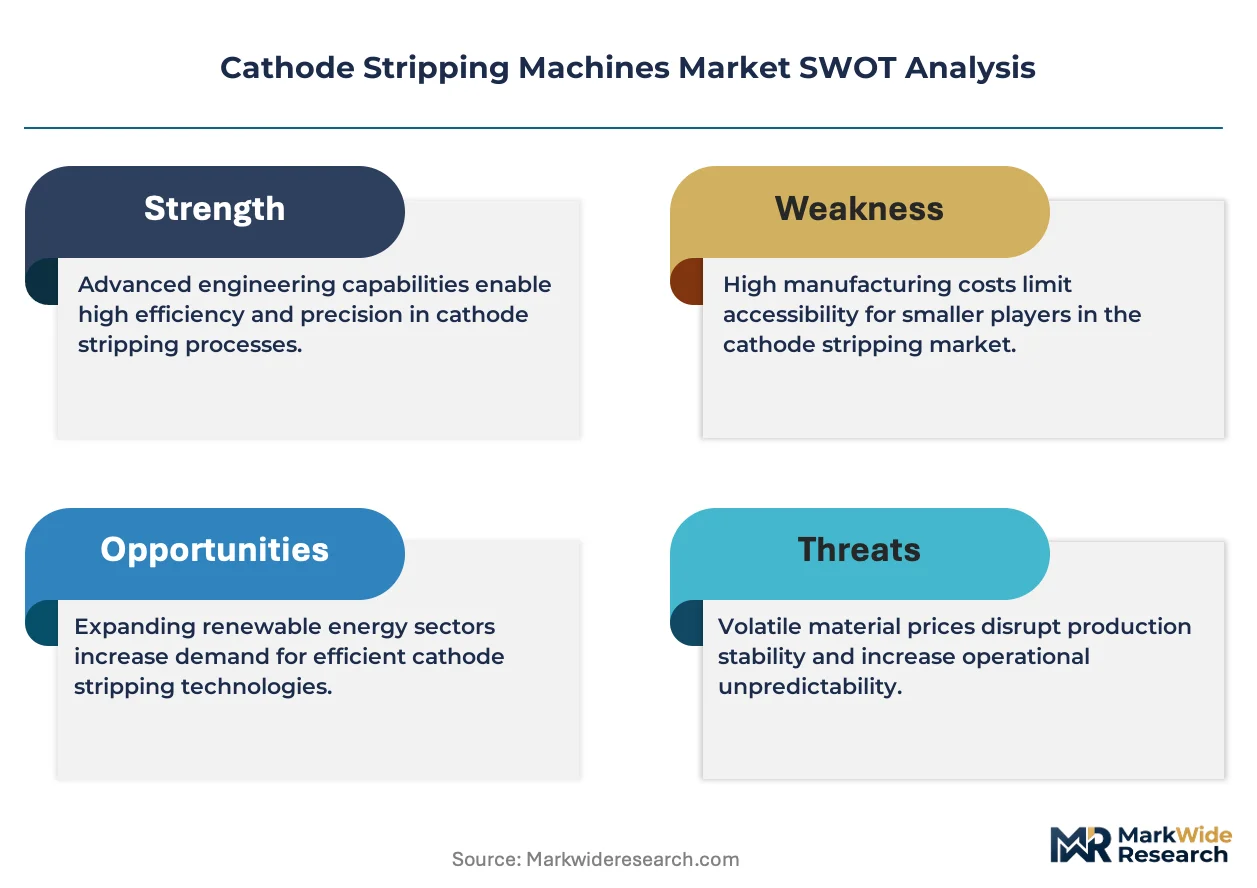
EU Battery Regulation is realigning the cost-of-entry calculus for cathode stripping equipment across European cell plants. Hitachi High-Tech leverages its precision automation heritage to sustain premium positioning in Japanese and Korean battery supply chains. Siemens AG anchors its portfolio through digital twin integration that reduces commissioning time for stripping line retrofits.
Cathode stripping machines remove deposited metal layers from reusable starter sheets in electrowinning and electrorefining operations, typically achieving stripping forces between 15 and 45 kN depending on cathode dimensions and deposit adhesion strength. The equipment serves primary copper and cobalt production as well as emerging battery material recycling flows. Automatic stripping systems occupy the dominant revenue position due to throughput requirements in gigafactory-scale battery plants, while robotic stripping variants represent the fastest-growing product category as vision-guided systems reduce cathode damage rates. Hydraulic technology leads installed base share in heavy-duty mining electrowinning, though pneumatic systems are displacing legacy mechanical designs in electronics-focused applications where vibration control matters.
EPA emissions standards and OSHA workplace exposure limits shape equipment design for North American installations, while REACH compliance in Europe restricts certain hydraulic fluid chemistries used in stripping actuators. China's GB standards and MIIT equipment certification requirements create a separate compliance pathway for domestic suppliers like Shenzhen Yinghe Technology. Stakeholders must monitor how evolving battery passport traceability rules alter stripping precision specifications for recycled cathode materials.
Market Dynamics
Battery gigafactory buildouts are compressing cathode stripping machine procurement cycles, forcing equipment vendors to compress delivery timelines while maintaining precision tolerances for recycled material recovery.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Minimum thresholds for recovered lithium, nickel, and cobalt in new cells require stripping precision that legacy equipment cannot achieve, forcing European cell plants to upgrade automation.
- Electrowinning capacity expansion:Copper and cobalt producers in the Democratic Republic of Congo and Zambia are adding stripping lines to match cathode output from expanded solvent extraction circuits.
- Robotic vision systems:Machine learning-guided stripping heads reduce cathode damage rates below 2%, enabling higher-value material recovery flows that manual or hydraulic systems cannot replicate.
Market Restraints
- Hydraulic fluid chemistry constraints:REACH restrictions on certain mineral oil formulations force European operators to reformulate actuators or absorb higher synthetic fluid costs.
- Supply concentration in precision motion components:Linear actuator and servo motor production clusters in Germany and Japan create vulnerability for non-integrated equipment assemblers.
- Mechanical stripping legacy lock-in:Existing electrowinning plants in South America and Central Africa carry fully depreciated manual stripping infrastructure with no capital allocation for replacement.
Strategic Opportunities
- Indonesian nickel processing integration:New HPAL-to-cathode complexes in Sulawesi and Halmahera lack established stripping equipment suppliers, creating first-mover positioning for automated system vendors.
- Battery passport traceability alignment:EU-mandated digital material passports reward stripping precision that delivers batch-level purity documentation, favoring equipment with integrated spectroscopic verification.
- AI-driven predictive maintenance bundling:Equipment vendors can attach recurring revenue streams by embedding vibration and force sensors that forecast blade wear and actuator fatigue.
Industry Challenges
- Cross-disciplinary commissioning teams:Stripping line installation requires simultaneous expertise in electrochemical process engineering, precision automation, and battery material specifications that few contractors possess.
- MIIT certification timelines:China's equipment safety and electromagnetic compatibility approvals add 4-6 months to product introduction for foreign vendors, compressing effective sales windows in fast-moving gigafactory procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cathode Stripping Machines Market |
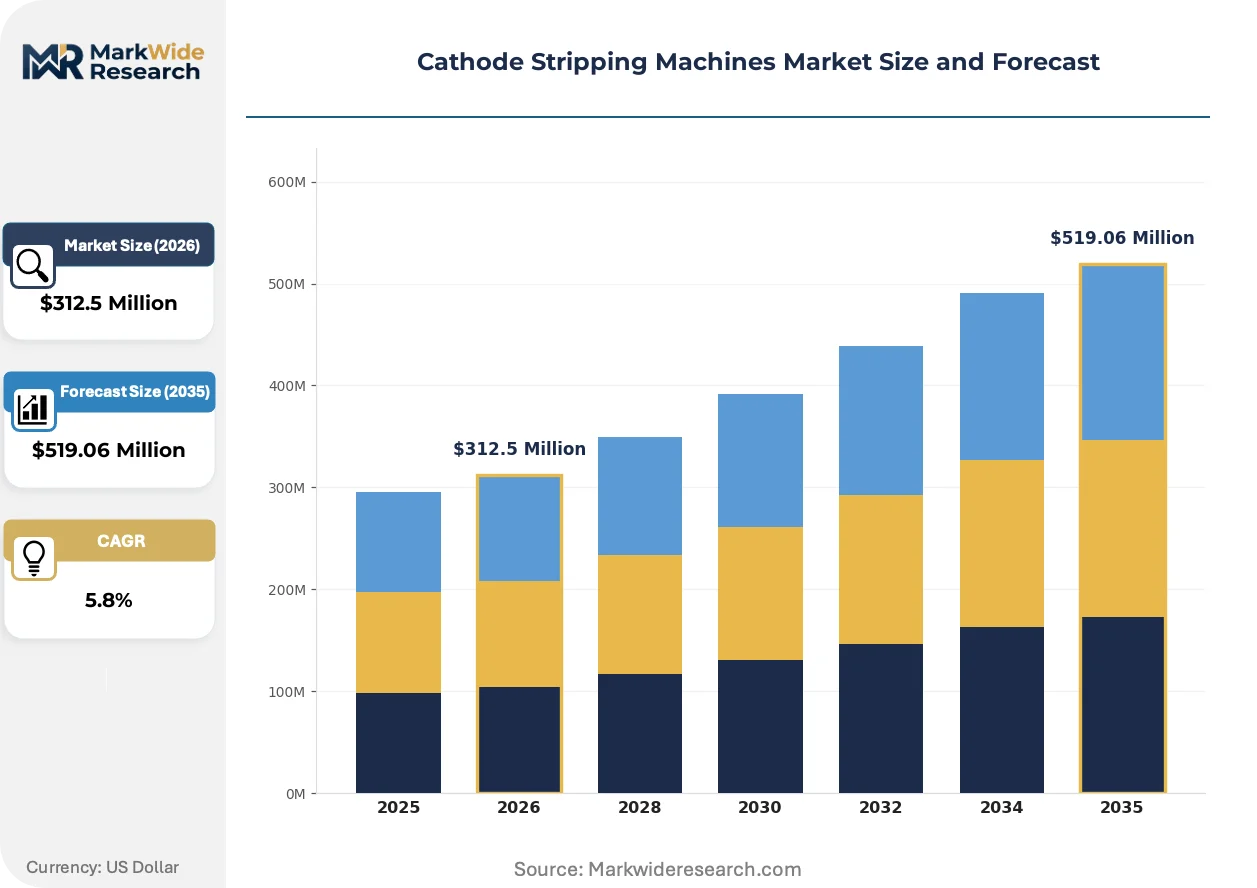
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Stripping, Automatic Stripping, Semi-Automatic Stripping, Robotic Stripping Application: Battery Manufacturing, Aerospace, Electronics, Renewable Energy End User: OEMs, Tier-1 Suppliers, Component Manufacturers, Research Institutions Technology: Hydraulic, Pneumatic, Thermal, Mechanical |
| Companies Covered | Hitachi High-Tech, Siemens AG, Metso, Shenzhen Yinghe Technology, Manz AG, EPIQ Hydromet, Toray Engineering, PNT Corp, Glencore Technology (ISAKIDD), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cathode Stripping Machines Market Trends and Innovations
Digital twin simulation and closed-loop force control are compressing commissioning timelines while enabling remote optimization of stripping parameters across distributed battery material recovery operations.
Vision-guided robotic stripping is integrating 3D surface profiling with adaptive force feedback to handle variable cathode thickness and deposit adhesion without manual parameter adjustment. Korean battery recyclers are deploying these systems at pilot scale to process mixed-chemistry feedstocks from end-of-life EV packs. The technology is integrating quality control and material sorting into a single automated cell, eliminating intermediate handling steps that previously introduced contamination risk.
REACH compliance enforcement is tightening disclosure requirements for hydraulic fluid compositions used in stripping actuators, forcing reformulation toward bio-based or synthetic alternatives with equivalent pressure ratings. Equipment vendors serving European battery material plants must now certify full chemical composition chains upstream of actuator delivery. The regulatory pressure is concentrating procurement decisions on vendors with established European substance compliance documentation.
After-sales service unbundling is separating hardware procurement from maintenance contracts and software update subscriptions, particularly among Chinese gigafactory operators seeking to internalize routine upkeep. Equipment vendors are responding with tiered support packages that reserve predictive analytics and remote diagnostics for premium tiers. This behavioral shift is most pronounced in Jiangsu and Fujian provinces where domestic equipment makers compete aggressively on upfront capital cost.
Cathode Stripping Machines Market Segmentation
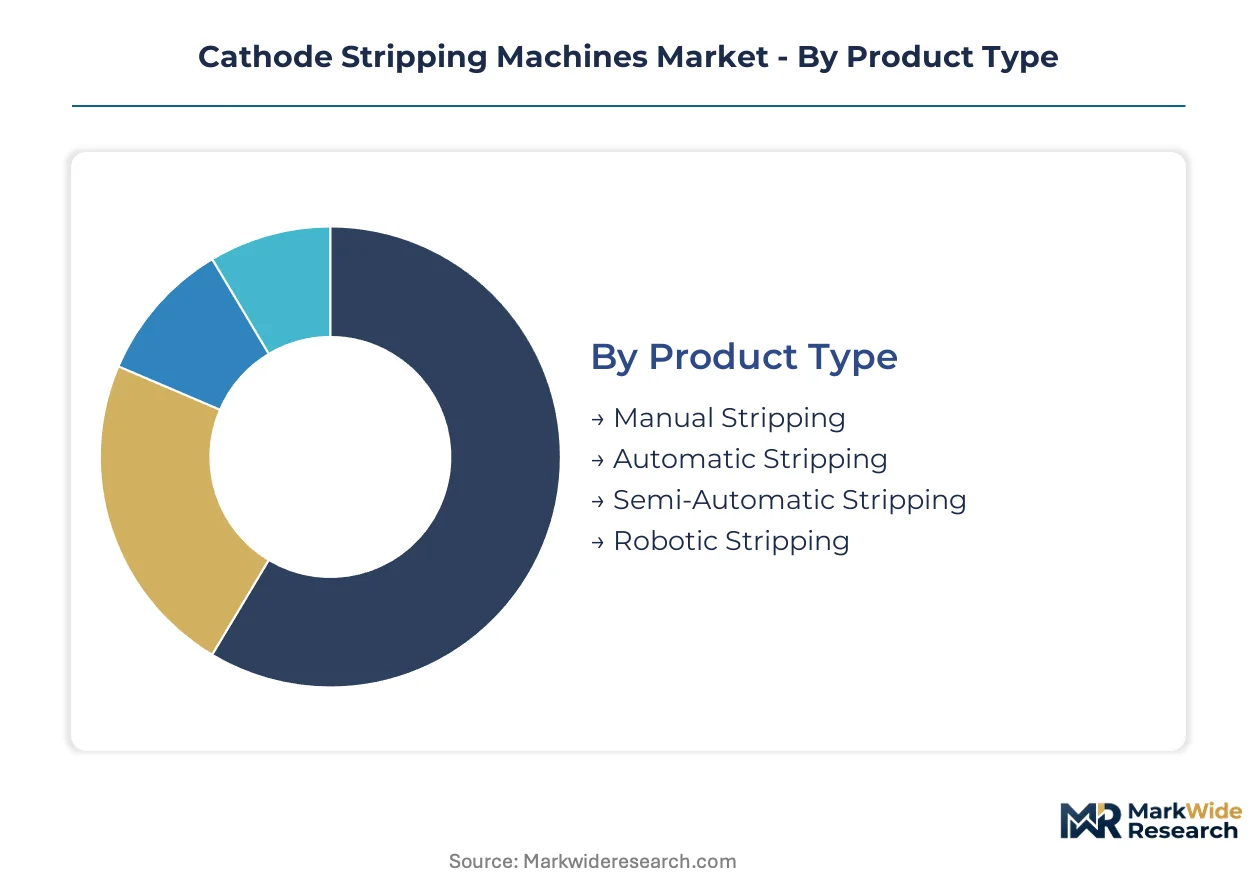
Cathode stripping equipment varies dramatically in automation intensity and force delivery mechanisms, with procurement decisions hinging on throughput targets, material recovery precision, and regulatory compliance burdens. Understanding how these technical axes fragment demand reveals where equipment vendors must concentrate R&D investment and service bundling.
Product Type:
Automation intensity determines capital expenditure thresholds, operating labor requirements, and achievable stripping precision for battery material recovery flows.
- Automatic Stripping:Systems deploy programmable logic controllers with fixed stripping heads operating at 15-45 kN force ranges. Battery gigafactories in China and Germany specify these for cathode output volumes exceeding 10 GWh annually, where manual intervention would create throughput bottlenecks and contamination risks.
- Robotic Stripping:Vision-guided articulating arms with adaptive force feedback reduce cathode damage rates below 2% on variable-thickness deposits. Korean battery recyclers pilot these for mixed-chemistry EV pack processing where deposit adhesion strength varies batch-to-batch.
- Manual Stripping:Lever-actuated or pneumatic hand tools persist in Central African copper electrowinning operations where capital constraints and low labor costs defer automation.
- Semi-Automatic Stripping:Operator-supervised systems with automated blade positioning but manual cathode loading suit mid-scale Indonesian nickel processing complexes transitioning from pilot to commercial output.
Automatic stripping leads on scale; robotic stripping leads on momentum.
Application:
End-use specifications diverge sharply in cathode thickness tolerance, surface quality requirements, and allowable contamination thresholds.
- Battery Manufacturing:Cell plants demand stripping precision that preserves starter sheet integrity across thousands of cycles. EU Battery Regulation recycled content mandates force European installations toward robotic systems with integrated spectroscopic verification for batch-level purity documentation.
- Electronics:Miniaturized component production requires pneumatic stripping with vibration damping below 0.5 mm displacement to protect delicate substrate layers. Japanese PCB fabricators specify these for cobalt recovery from plating line effluent.
- Aerospace:Specialty alloy electrowinning for turbine blade coatings tolerates wider thickness variation but demands full material traceability chains compliant with AS9100 quality standards.
- Renewable Energy:Grid-scale battery storage manufacturing in the US follows IRA domestic content rules that favor North American-assembled stripping equipment regardless of automation tier.
Battery manufacturing concentrates procurement volume; electronics applications impose the tightest precision constraints.
End User:
Customer organizational structure shapes contract negotiation dynamics, after-sales service expectations, and technology upgrade cadences.
- OEMs:Integrated battery cell producers like CATL and BYD internalize stripping line design specifications, forcing equipment vendors into co-development arrangements with shared IP on process parameters.
- Tier-1 Suppliers:Cathode active material specialists such as Umicore and Posco Chemical purchase stripping systems as part of integrated precursor-to-cathode production lines, demanding seamless handoff with upstream HPAL and downstream calcination equipment.
- Component Manufacturers:Smaller copper and cobalt producers in the Democratic Republic of Congo prioritize equipment durability in high-humidity environments over automation sophistication.
- Research Institutions:National laboratories and university pilot lines drive adoption of modular stripping platforms with rapid reconfiguration between electrowinning chemistries.
OEMs anchor capital expenditure; research institutions pilot next-generation configurations.
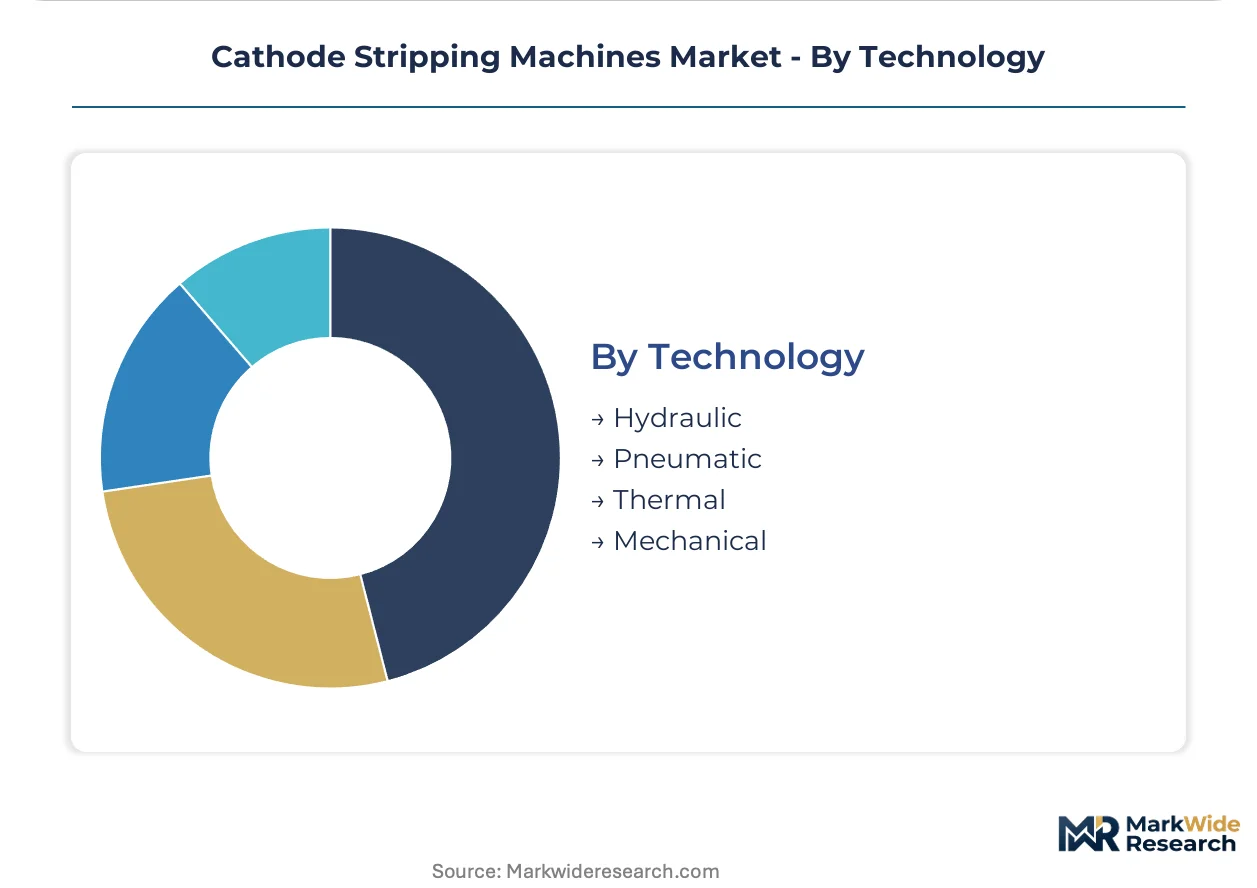
Technology:
Actuation mechanism selection trades force density, precision control, and fluid chemistry compliance against installed base familiarity.
- Hydraulic:Mineral oil-based systems deliver highest force density for heavy-duty mining electrowinning but face REACH reformulation mandates in European battery material plants. Zambian copper producers expand installed base despite environmental compliance headwinds elsewhere.
- Pneumatic:Compressed air actuation displaces legacy mechanical designs in electronics-focused applications where vibration isolation and cleanroom compatibility outweigh force requirements. Shenzhen equipment makers dominate this segment for domestic Chinese battery component plants.
- Thermal:Induction heating-assisted stripping reduces mechanical stress on thin cathode substrates during deposit removal. Pilot deployments in German battery recycling facilities test integration with pyrometallurgical recovery flows.
- Mechanical:Rack-and-pinion or cam-driven systems persist in fully depreciated South American electrowinning infrastructure with no capital replacement cycles scheduled.
Hydraulic technology retains installed base dominance; pneumatic systems gain share fastest in regulated environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automation engineers and electrochemical process specialists cluster in industrial corridors where battery gigafactories and copper electrowinning operations overlap. This workforce concentration shapes equipment procurement patterns and technology transfer pathways across four dominant geographies.
China
Domestic equipment makers now supply most new gigafactory installations in Jiangsu and Fujian provinces. MIIT certification requirements add 4-6 months to foreign vendor product introductions, compressing effective sales windows. Shenzhen and Dongguan host precision motion component clusters feeding stripping line assemblers.
Germany
European cell plants upgrade automation to meet EU Battery Regulation recycled content thresholds. ECHA REACH restrictions on hydraulic fluid chemistries force reformulation toward bio-based alternatives. North Rhine-Westphalia anchors stripping line retrofit demand from legacy industrial electrowinning sites.
United States
IRA domestic content rules favor North American-assembled stripping equipment for grid-scale battery storage manufacturing. EPA emissions standards and OSHA workplace exposure limits shape equipment design for copper and cobalt recovery operations. Michigan and Nevada gigafactory clusters drive specification standardization.
Democratic Republic of Congo
Copper and cobalt producers expand stripping lines to match cathode output from expanded solvent extraction circuits. Capital constraints and low labor costs defer automation in existing electrowinning infrastructure. Kolwezi and Lubumbashi concentrate new capacity additions.
Indonesia
New HPAL-to-cathode complexes in Sulawesi and Halmahera lack established stripping equipment suppliers, creating first-mover positioning for automated system vendors. The country's nickel processing integration attracts foreign automation specialists. Morowali Industrial Park hosts pilot robotic stripping deployments.
Cathode Stripping Machines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. The market fragments across three strategic layers: precision automation heritage players, mining-technology diversifiers, and domestic Chinese equipment assemblers. Consolidation pressure intensifies as gigafactory procurement cycles compress delivery timelines. Dominant competitive moves include co-development arrangements with integrated cell producers and predictive maintenance service bundling.
Among precision automation specialists, Hitachi High-Tech and Siemens AG occupy positions shaped by digital twin integration and force control heritage. Shenzhen Yinghe Technology exemplifies the domestic Chinese archetype competing aggressively on upfront capital cost. These three represent divergent strategic postures: premium-tier precision engineering, industrial software-anchored solutions, and scale-driven manufacturing efficiency.
| Leading Market Players |
|---|
| Hitachi High-Tech |
| Siemens AG |
| Metso |
| Shenzhen Yinghe Technology |
| Manz AG |
| EPIQ Hydromet |
| Toray Engineering |
| PNT Corp |
| Glencore Technology (ISAKIDD) |
| Others |
Pricing and Supply Chain Analysis
Automatic versus robotic stripping system bifurcation creates divergent cost structures across procurement portfolios, with precision automation commanding substantial premiums while commodity hydraulic units face relentless cost compression from Chinese domestic assemblers. This tier divergence manifests in supply chain configurations where premium vendors anchor production in German and Japanese precision motion clusters, while economy-tier equipment flows through Shenzhen component ecosystems.
Pricing Analysis
Bundled versus unbundled service splits now dominate contract negotiations, with Chinese gigafactory operators aggressively separating hardware procurement from maintenance subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with REACH-compliant European systems commanding substantial premiums over baseline hydraulic units. Price erosion runs through the economy tier as Shenzhen Yinghe Technology and domestic competitors compress upfront capital costs. OEMs like CATL and BYD exhibit lowest price sensitivity due to co-development arrangements, while Central African copper producers remain highly cost-conscious.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated cell producers, while distributor networks serve mid-scale Indonesian nickel processors and African mining operations. Linear actuator and servo motor production clusters in Germany, Japan, and Shenzhen create geographic supply concentration that non-integrated equipment assemblers must navigate. Stripping line production draws from precision steel forgings, high-pressure hydraulic seals, and machine vision components. Single-source vulnerability in European linear motion supply creates structural risk for vendors serving REACH-regulated battery material plants. Distribution runs through equipment integrators for retrofits and direct manufacturer relationships for greenfield gigafactory installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cathode Stripping Machines Market functions as a stable compounder anchored by irreversible battery gigafactory buildouts and mandatory recycled content thresholds that lock in equipment replacement cycles.
For Market Incumbents: Lock in predictive maintenance subscription revenue by embedding force sensors and vibration analytics that forecast blade wear before failure. Defend margin position through MIIT certification pre-positioning in China, eliminating the 4-6 month approval disadvantage that foreign vendors face. Prioritize co-development IP arrangements with CATL and BYD that embed process parameters into proprietary control systems, creating switching costs against emerging domestic competitors. For New Entrants and Emerging Players: Capture first-mover positioning in Indonesian HPAL-to-cathode complexes in Sulawesi and Halmahera where established stripping equipment suppliers remain absent. Target battery passport traceability alignment as the most penetrable specification wedge, offering integrated spectroscopic verification that legacy vendors lack. Pursue pilot-to-scale partnerships with Korean battery recyclers processing mixed-chemistry EV packs, using vision-guided robotic stripping demonstrations to prove damage-rate superiority. For Investors and Strategic Acquirers: Consolidation pressure builds where precision automation heritage overlaps with battery material recovery expertise, creating scarcity value for vendors with both capabilities. Long-term viability favors equipment makers with software-anchored service revenue streams rather than pure hardware transactional models. Target acquisition profiles should emphasize vendors with established European substance compliance documentation and predictive analytics infrastructure. Watch for inflection when EU Battery Regulation enforcement tightens recycled content verification requirements, accelerating replacement demand beyond natural depreciation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Siemens AG reduces stripping line commissioning timelines through virtual commissioning before physical installation. |
| Predictive Maintenance Bundling | Vibration and force sensors create recurring revenue streams by forecasting blade wear and actuator fatigue. |
| Backward Integration into Precision Motion | Control over linear actuator supply mitigates vulnerability from German and Japanese component concentration. |
| MIIT Certification Pre-Positioning | Domestic Chinese compliance eliminates 4-6 month approval delays that compress foreign vendor sales windows. |
| Battery Passport Traceability Alignment | Integrated spectroscopic verification captures EU-mandated digital material passport requirements ahead of competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at battery gigafactories, procurement leads at cathode active material specialists, aftermarket service heads at equipment vendors, and automation integration specialists with secondary validation. Trade data from Chinese customs authorities, MIIT equipment certification registries, SEC filings from diversified industrial conglomerates, and EU Battery Regulation implementation guidance provided foundational demand indicators. Bottom-up project pipeline tracking across announced gigafactory installations triangulated against top-down electrowinning capacity expansion announcements in copper and cobalt production.
Segment-weighting approaches distributed total addressable market across automation intensity tiers, actuation technology categories, and end-use applications before applying regional demand coefficients. Product type segmentation modeled automatic, robotic, semi-automatic, and manual stripping systems against application-specific precision requirements in battery manufacturing, electronics, and electrowinning operations. CAGRs derived from equipment procurement cycle analysis, replacement rate assumptions for legacy infrastructure, and regulatory mandate compliance deadlines. Force density requirements and REACH fluid chemistry compliance thresholds served as industry-specific forecast inputs.
Regulatory enforcement delays, battery gigafactory construction postponements, and hydraulic fluid reformulation cost pass-through failures are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about MIIT certification timeline stability and EU Battery Regulation recycled content threshold adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market