
 Very Small Aperture Terminal (VSAT) Market | 2026-2036
Very Small Aperture Terminal (VSAT) Market Size, Share, and Industry Trends Forecast 2026-2036
Very Small Aperture Terminal (VSAT) Market Analysis
Modular antenna kits bundled with managed network services is pivoting how enterprise buyers evaluate total cost of ownership against standalone hardware procurement. Viasat, Inc. leverages its vertically integrated satellite capacity to control end-to-end service margins. Gilat Satellite Networks Ltd. specializes in compact hub architectures that reduce ground infrastructure footprints for rural deployments. Hughes Satellite Systems Corporation anchors North American consumer broadband through high-volume subscriber economics.
A Very Small Aperture Terminal is a two-way satellite ground station with a parabolic antenna typically measuring under 2.4 meters in diameter, operating through geostationary or low earth orbit satellites to transmit and receive data, voice, and video signals across Ku-Band, Ka-Band, C-Band, or Q-Band frequencies. Packet switching architectures now dominate enterprise deployments where bursty IP traffic patterns favor statistical multiplexing over dedicated circuit-switched channels. Ku-Band equipment retains the largest installed base but Ka-Band terminals are capturing the fastest growth in consumer broadband due to higher throughput density per transponder. Disaster recovery applications command premium pricing because mission-critical uptime requirements justify dedicated backup links with sub-60-second activation protocols.
The FCC governs spectrum licensing and orbital slot coordination for US operators, while the ITU-R framework shapes international frequency allocation and interference mitigation standards that manufacturers must embed in terminal designs. ETSI technical specifications enforce European terminal interoperability and electromagnetic compatibility thresholds that gate market access. Brazil's national telecom regulator Anatel mandates local certification for satellite terminals deployed in offshore energy zones. Stakeholders must monitor spectrum auction timelines and orbital debris mitigation rules that could reshape terminal power requirements and antenna pointing accuracy specifications.
Market Dynamics
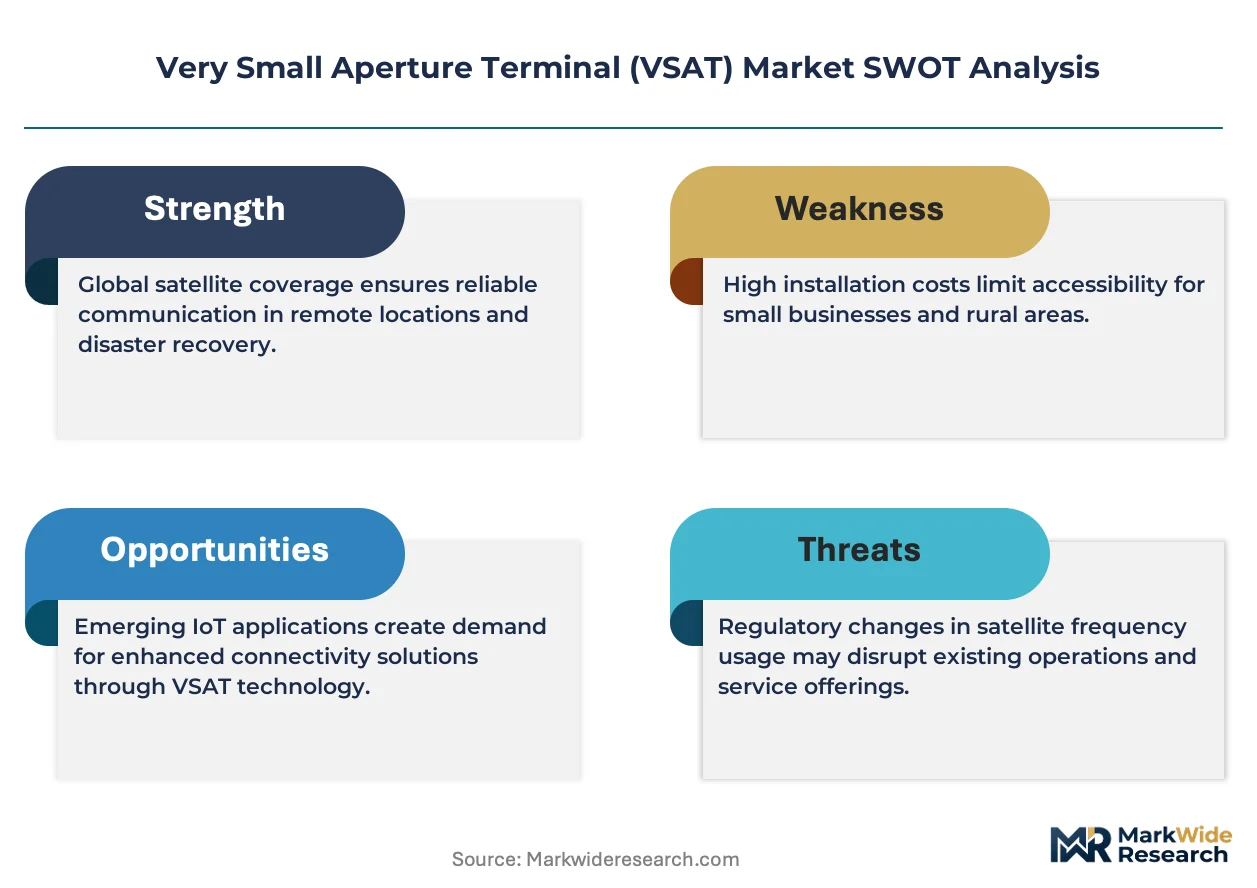
FCC spectrum reallocation mandates are compressing Ku-Band availability while Ka-Band deployment accelerates, forcing terminal manufacturers to redesign RF front-ends and maritime operators to retest fleet-wide link budgets against new interference profiles.
Growth Catalysts
- Offshore Energy Telemetry:Brazil's offshore pre-salt fields require real-time drilling data transmission. Anatel certification requirements for hazardous zone terminals are standardizing ruggedized VSAT specifications across South American energy corridors.
- LEO Constellation Backhaul:Low earth orbit satellite networks are reducing latency for enterprise VPN applications. Rural banking branches in sub-Saharan Africa are adopting hybrid GEO-LEO terminal architectures for transactional reliability.
- Managed Service Bundling:Enterprise buyers are favoring subscription-based network operations over capital-intensive hub ownership. This procurement shift reduces internal IT satellite competency requirements for agricultural cooperatives.
Market Restraints
- RF Component Concentration:Gallium nitride power amplifier foundries cluster in Taiwan and the United States. Geopolitical export controls on compound semiconductor substrates create single-source vulnerability for high-efficiency block upconverters.
- Orbital Slot Scarcity:ITU-R coordination procedures for geostationary arc positions impose multi-year licensing timelines. Emerging market operators face priority disadvantages against incumbent satellite fleet operators with grandfathered filings.
- Terrestrial Fiber Substitution:Submarine cable extensions into West African coastal zones are displacing satellite backhaul for urban telco aggregation points. Price-per-megabit compression threatens C-Band enterprise terminal economics in cable-landing zones.
Strategic Opportunities
- Defense Mobility Gaps:NATO expeditionary communication requirements for beyond-line-of-sight tactical data are outpacing legacy military satellite terminal refresh cycles. Dual-use Ka-Band flat panel antennas certified to MIL-STD-810G specifications address this white space.
- Precision Agriculture Unlocks:Brazilian Mato Grosso soy operations lack terrestrial connectivity for autonomous harvester telemetry. Solar-powered VSAT terminals with integrated LoRa gateways enable farm-equipment OEMs to offer predictive maintenance subscriptions.
- EU Green Deal Alignment:CSRD reporting mandates require shipping operators to document voyage emissions. Satellite-connected engine monitoring systems satisfy MRV regulation compliance while generating fuel optimization analytics for container fleets.
Industry Challenges
- RF Engineering Talent Pipeline:Microwave circuit design expertise for phased array antennas concentrates in defense-aerospace clusters. Commercial terminal manufacturers compete for finite pools of electromagnetic simulation specialists fluent in CST Studio Suite.
- Multi-Orbit Integration Complexity:Enterprise buyers demand seamless handoff between GEO, MEO, and LEO constellations. Terminal firmware must simultaneously track inclined orbit shells and geostationary arc positions, complicating antenna control unit validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Very Small Aperture Terminal (VSAT) Market |
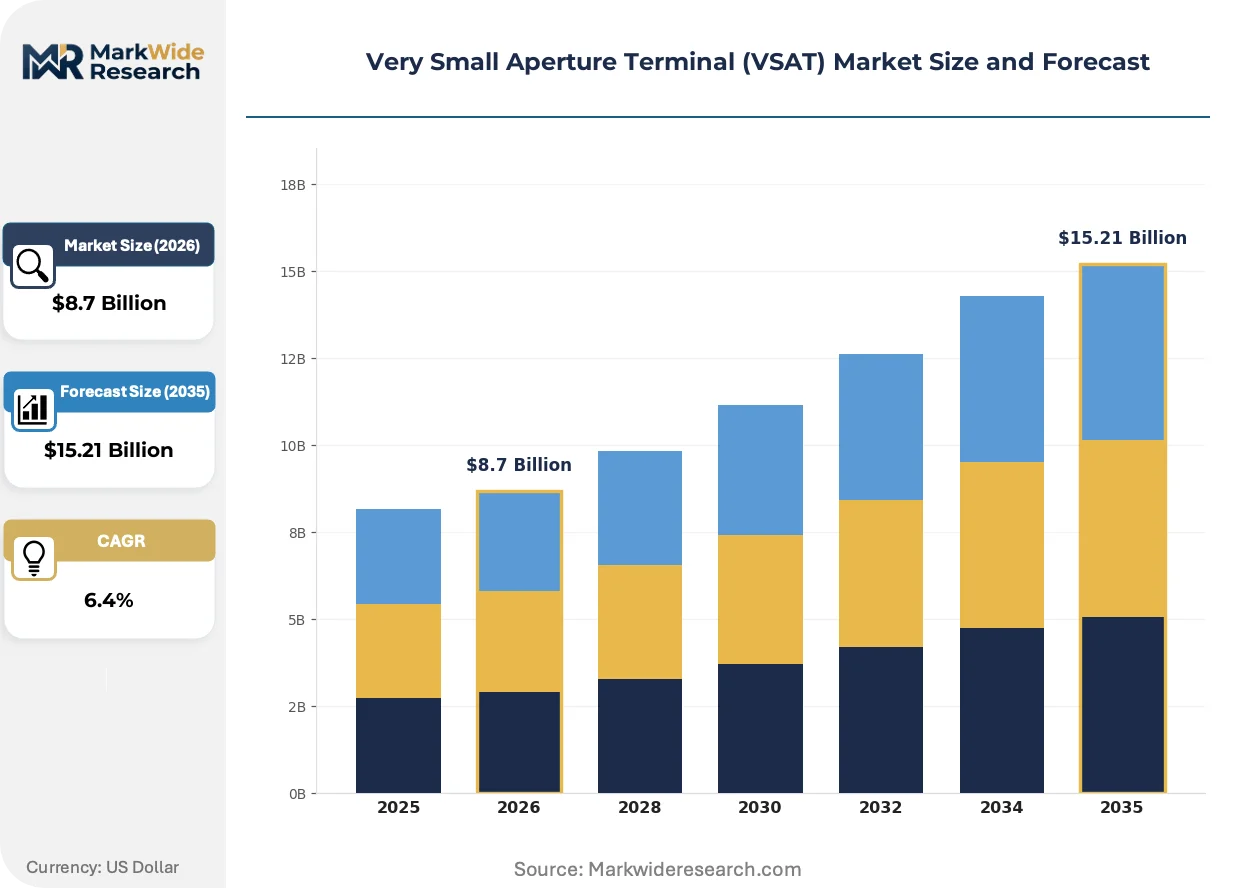
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Switching, Packet Switching, Hybrid Systems, Low Earth Orbit Systems End User: Energy Sector, Marine Industry, Government, Telecommunications Technology: Ku-Band, Ka-Band, C-Band, Q-Band Application: Remote Monitoring, Disaster Recovery, Internet Access, Emergency Communication |
| Companies Covered | Cobham Satcom Ltd., ST Engineering Ltd., Viasat, Inc., L3Harris Technologies Inc., Intelsat S.A., Hughes Satellite Systems Corporation, Marlink Group, SpeedCast International Limited, Gilat Satellite Networks Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Very Small Aperture Terminal (VSAT) Market Emerging Trajectories
Packet-switched architectures are displacing circuit-switched backbones across maritime and enterprise deployments, compressing activation intervals from weeks to hours while enabling bandwidth-on-demand metering models that reshape operator cash flow profiles.
Electronically steered flat panel antennas are consolidating mechanical complexity into solid-state beamforming arrays. Cruise lines including Carnival Corporation and Royal Caribbean International are retrofitting vessel superstructures with low-profile radomes that eliminate stabilized pedestal maintenance. This consolidation is reducing below-deck volume requirements by sixty percent and enabling installation on smaller coastal ferries previously excluded by stability constraints.
REACH restrictions on persistent organic pollutants are mandating lead-free solder transitions in European-sourced RF assemblies. Terminal manufacturers serving EU maritime fleets must requalify waveguide interconnects and printed circuit board laminates under ECHA substance authorization procedures. Ka-Band consumer broadband terminals face the steepest compliance timeline pressure due to high-volume production runs and thin margin structures that resist engineering change order absorption.
Enterprise procurement teams are unbundling hardware ownership from network operations, treating satellite capacity as a utility expense rather than capital equipment. Managed service providers including Speedcast and Marlink are capturing multi-year connectivity contracts from mining camps in Western Australia and Chilean Atacama copper operations. This behavioral shift concentrates buyer power among fleet-scale aggregators and compresses standalone terminal vendor margins to single-digit percentages.
Very Small Aperture Terminal (VSAT) Market Segmentation
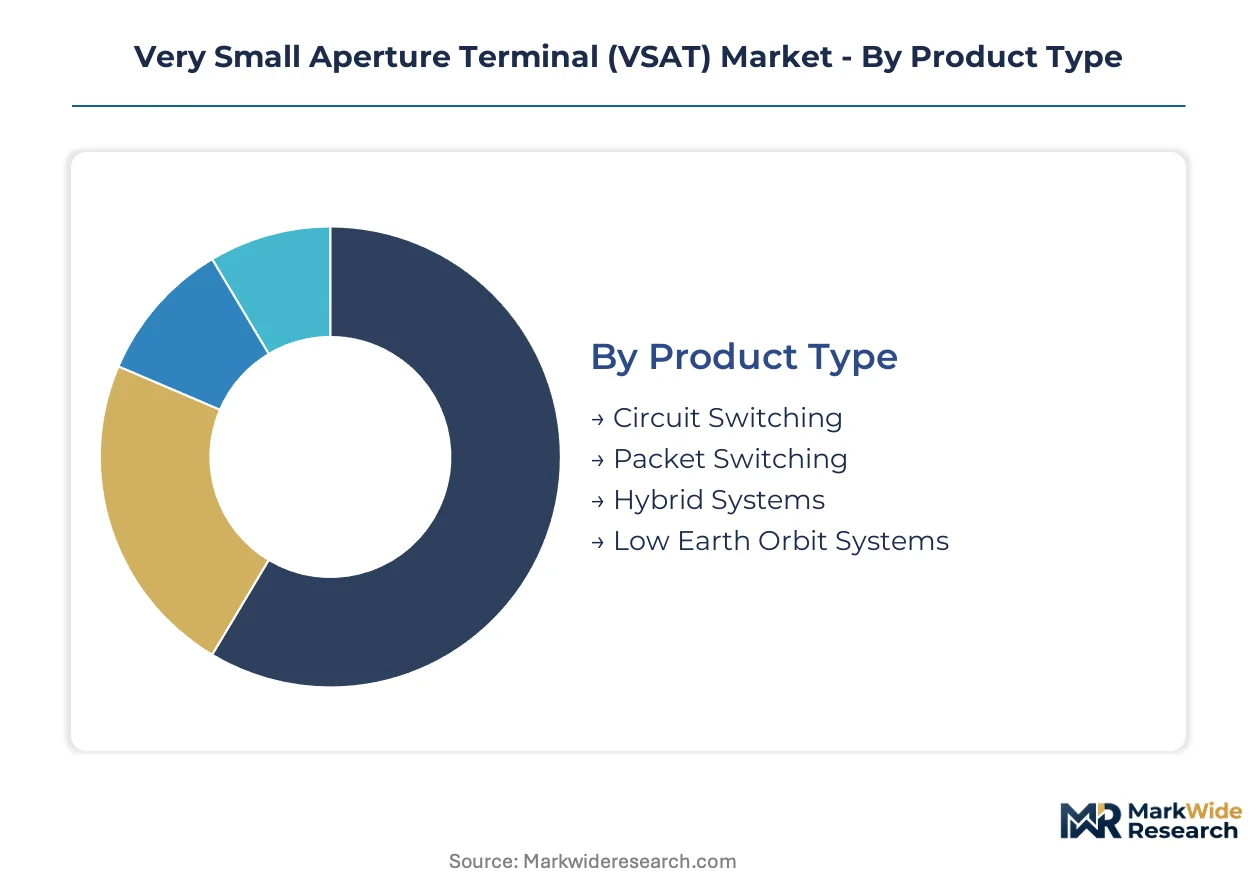
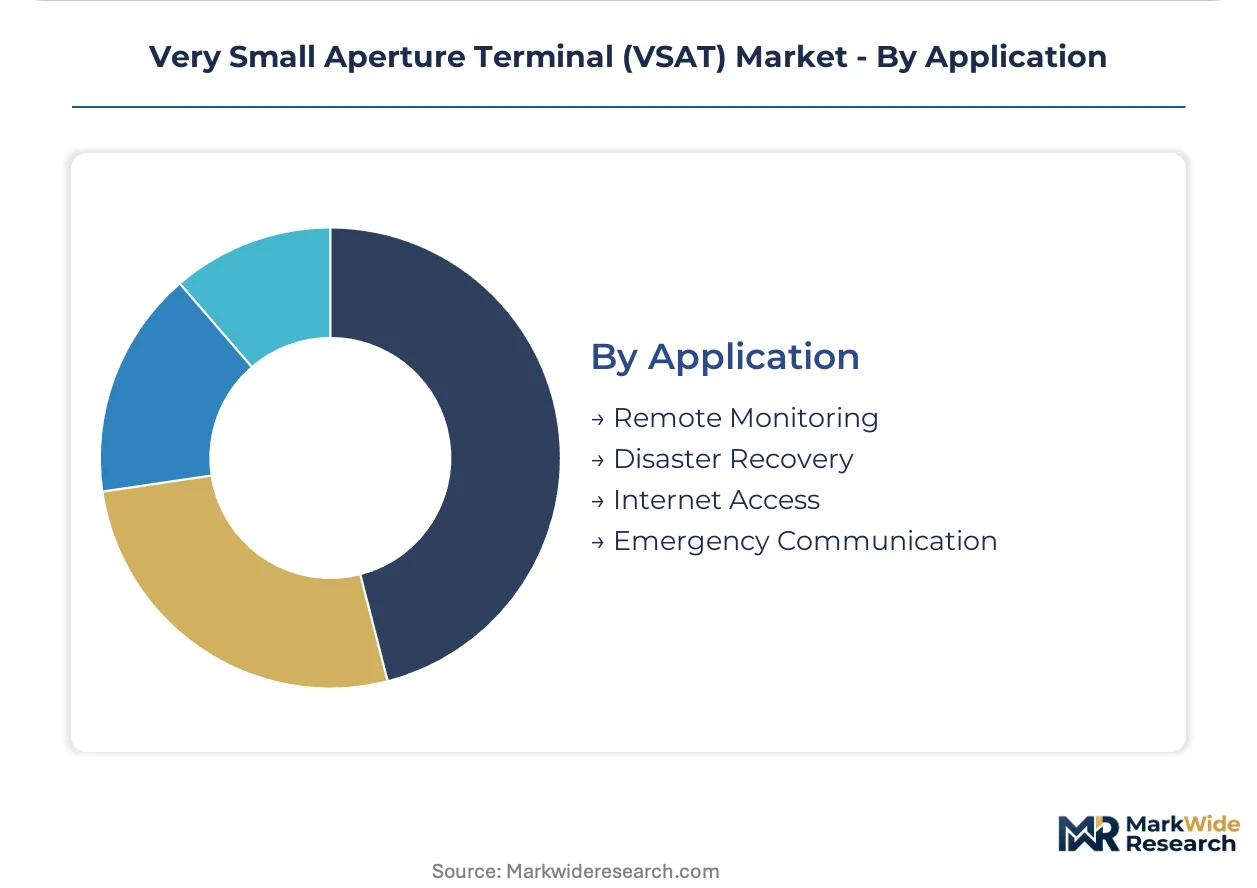
VSAT procurement patterns diverge sharply across technical architectures and end-use verticals. Terminal specifications must align with distinct regulatory regimes, orbital economics, and latency requirements that reshape buyer decision frameworks.
Product Type:
Circuit switching architectures demand FCC Part 25 licensing for dedicated satellite channels, while packet switching terminals face lighter equipment authorization burdens under modular approval frameworks.
- Circuit Switching:Dedicated channel architectures maintain fixed bandwidth allocations through geostationary transponders. Brazilian offshore platforms in the pre-salt basin rely on these systems for drilling telemetry where guaranteed throughput overrides statistical multiplexing efficiency.
- Packet Switching:IP-native architectures enable bandwidth-on-demand metering through statistical multiplexing. Maritime fleet operators favor these systems for bursty email and web traffic that tolerates variable latency.
- Hybrid Systems:Dual-mode terminals combine circuit-switched voice with packet data, serving African rural banking branches that require transactional reliability alongside voice backup.
- Low Earth Orbit Systems:Phased array terminals tracking inclined orbital shells reduce propagation delay for enterprise VPN applications.
Packet switching sits at the top of the volume ranking, with LEO systems climbing the fastest.
End User:
Customer procurement scale and mission-criticality create tiered margin structures across vertical segments.
- Energy Sector:Hazardous zone certifications under Anatel directives govern Brazilian offshore terminal deployments. Real-time drilling data transmission commands premium pricing for explosion-proof hub architectures.
- Marine Industry:Cruise line retrofit programs favor low-profile flat panel antennas that eliminate stabilized pedestal maintenance. Carnival Corporation vessel superstructure modifications demonstrate this specification shift.
- Government:NATO expeditionary requirements drive MIL-STD-810G certification for tactical Ka-Band flat panels.
- Telecommunications:Rural cellular backhaul contracts concentrate buyer power among fleet-scale aggregators.
Marine industry deployments dominate current procurement volume, with government applications expanding most quickly.
Technology:
Frequency band selection determines antenna size, rain fade tolerance, and transponder lease economics across deployment scenarios.
- Ku-Band:Mature ecosystem with largest installed base and established hub infrastructure. FCC spectrum reallocation mandates are compressing availability and forcing retest protocols for maritime link budgets.
- Ka-Band:Higher throughput density per transponder enables consumer broadband economics. REACH restrictions on lead-free solder create compliance pressure for high-volume European production runs.
- C-Band:Resilient to rain fade for tropical maritime routes but facing terrestrial fiber substitution in West African cable landing zones.
- Q-Band:Experimental deployments for ultra-high throughput enterprise applications with limited commercial terminal availability.
Ku-Band retains the largest installed base, with Ka-Band gaining share fastest among new deployments.
Application:
Use case urgency and uptime requirements stratify pricing structures across deployment scenarios.
- Remote Monitoring:Agricultural telemetry in Mato Grosso soy operations combines solar-powered terminals with integrated LoRa gateways for autonomous harvester predictive maintenance.
- Disaster Recovery:Sub-60-second activation protocols command dedicated backup link premiums. Mission-critical uptime requirements justify circuit-switched architectures over shared packet infrastructure.
- Internet Access:Consumer broadband economics rely on high-volume subscriber bases and thin terminal margins.
- Emergency Communication:First responder networks require rapid-deploy flyaway terminals with autonomous pointing capabilities.
Internet access represents the largest addressable volume, with disaster recovery showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VSAT technology first achieved commercial scale in the United States during the 1980s when hub-and-spoke architectures revolutionized rural banking connectivity. The industry subsequently diffused across maritime corridors and energy extraction zones, with regulatory frameworks now determining deployment economics in distinct national markets.
United States
FCC spectrum reallocation mandates are compressing Ku-Band availability for maritime operators while accelerating Ka-Band terminal certification timelines. The regulator's orbital debris mitigation rules are reshaping antenna pointing accuracy specifications for next-generation deployments. Houston hosts the largest concentration of energy-sector VSAT procurement teams, with offshore drilling contractors retesting fleet-wide link budgets against new interference profiles.
Brazil
Offshore pre-salt field expansion requires real-time drilling data transmission across the Santos Basin. Anatel certification requirements for hazardous zone terminals are standardizing ruggedized VSAT specifications across South American energy corridors. The Macaé industrial cluster anchors manufacturing partnerships for explosion-proof hub architectures serving deepwater platforms.
Germany
Container fleet operators are retrofitting vessel superstructures with low-profile flat panel antennas to satisfy EU Green Deal emissions monitoring mandates. ETSI technical specifications enforce terminal interoperability thresholds that gate market access for non-European manufacturers. Hamburg's maritime engineering cluster drives adoption of electronically steered arrays that eliminate stabilized pedestal maintenance.
Japan
Rural banking branches in sub-Saharan Africa are sourcing hybrid GEO-LEO terminal architectures from Japanese trading houses to ensure transactional reliability. METI technology export frameworks shape compound semiconductor substrate licensing for high-efficiency block upconverters. Tokyo's RF engineering talent pipeline concentrates microwave circuit design expertise for phased array antenna development.
United Arab Emirates
Desert mining camps and remote construction sites are driving demand for solar-powered VSAT terminals with integrated IoT gateways. The country's national telecom regulator mandates local certification for satellite terminals deployed in critical infrastructure zones. Dubai's logistics corridor serves as the primary distribution hub for African and South Asian terminal shipments.
Very Small Aperture Terminal (VSAT) Market Vendor Landscape
The competitive structure tilts toward vertically integrated satellite operators with captive transponder capacity. Three distinct archetypes populate the vendor landscape: satellite fleet owners controlling end-to-end service margins, compact hub specialists reducing ground infrastructure footprints, and managed service providers capturing multi-year connectivity contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players seeking orbital slot access and regional certification capabilities.
Within the integrated-operator tier, Viasat, Inc. and Intelsat S.A. exemplify business models built on captive satellite capacity. Hughes Satellite Systems Corporation occupies a position among North American consumer broadband providers leveraging high-volume subscriber economics. Gilat Satellite Networks Ltd. and Marlink Group represent specialists in compact hub architectures and maritime managed services respectively.
| Leading Market Players |
|---|
| Cobham Satcom Ltd. |
| ST Engineering Ltd. |
| Viasat, Inc. |
| L3Harris Technologies Inc. |
| Intelsat S.A. |
| Hughes Satellite Systems Corporation |
| Marlink Group |
| SpeedCast International Limited |
| Gilat Satellite Networks Ltd. |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate costs cascade through RF front-end manufacturing into three distinct pricing tiers for maritime, enterprise, and consumer broadband terminal buyers. FCC spectrum reallocation mandates are compressing Ku-Band equipment margins while Ka-Band module premiums reflect Taiwan foundry capacity constraints.
Pricing Analysis
Subscription-based managed service bundling now dominates enterprise procurement, separating premium maritime contracts with sub-60-second disaster recovery activation from standard agricultural telemetry packages and economy consumer broadband tiers. Price differentiation hinges on hazardous zone certification grades under Anatel directives and volume scale across fleet deployments. Pricing pressure stems from terrestrial fiber substitution in West African cable landing zones where C-Band backhaul contracts face price-per-megabit compression. Agricultural cooperatives in Brazil exhibit highest price sensitivity due to thin operating margins, while offshore energy operators absorb premium pricing for guaranteed throughput.
Supply Chain Analysis
Refurbishment flows for stabilized pedestal systems are accelerating as cruise lines retrofit vessels with solid-state flat panel antennas, creating secondary markets for legacy Ku-Band hardware. Gallium nitride power amplifier foundries cluster in Taiwan and the United States, drawing from compound semiconductor substrate suppliers in Japan and Germany. Single-source vulnerability in high-efficiency block upconverters creates structural risk under geopolitical export controls. Distribution runs through Dubai's logistics corridor for African and South Asian terminal shipments, with Hamburg and Houston anchoring regional hub operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VSAT market has entered a late-cycle quality phase where premium specifications for multi-orbit integration and MIL-STD-810G certification command sustainable margin premiums over commodity consumer broadband terminals.
For Market Incumbents: Acquire orbital slot licenses and Anatel certification capabilities to defend against LEO constellation disruption. Consolidate compact hub architecture specialists in Brazil and Germany to control ground infrastructure footprints. Prioritize backward integration into gallium nitride foundry partnerships to secure block upconverter supply against Taiwan export restrictions. For New Entrants and Emerging Players: Launch via solar-powered terminal-as-a-service models targeting Brazilian Mato Grosso soy operations lacking terrestrial connectivity for autonomous harvester telemetry. White-space opportunities concentrate in precision agriculture predictive maintenance subscriptions and NATO expeditionary Ka-Band flat panel deployments. Partner with Japanese trading houses for hybrid GEO-LEO terminal architectures serving sub-Saharan African rural banking branches. For Investors and Strategic Acquirers: Consolidation pressure builds where managed service providers lack captive satellite capacity and face margin compression from fleet-scale aggregator buyer power. Five-to-ten year viability favors vertically integrated operators with orbital slot grandfathered filings and multi-orbit firmware capabilities. Monitor FCC orbital debris mitigation rulemaking and ITU-R coordination timeline delays as inflection signals for terminal power requirement and antenna pointing accuracy specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Terminal Certification | Anatel and FCC dual-approval opens Brazilian offshore energy and US maritime fleet contracts. |
| Managed Service Contract Aggregation | Speedcast and Marlink demonstrate multi-year connectivity contract capture from Australian mining camps. |
| Flat Panel Antenna Manufacturing Scale-Up | Carnival Corporation retrofits validate sixty percent below-deck volume reduction for coastal ferry expansion. |
| LEO Constellation Partnership | Hybrid GEO-LEO architectures address latency requirements for enterprise VPN and rural banking applications. |
| REACH Compliance Repositioning | Lead-free solder transitions in European-sourced RF assemblies gate market access for high-volume Ka-Band production. |
Methodological Framework
Bottom-up maritime and energy sector modeling reconciled against top-down satellite capacity and terminal shipment tracking forms the analytical core of this study. Primary interviews with RF engineering directors at terminal manufacturers, Anatel certification officers, offshore drilling procurement leads, and maritime fleet technology managers combined with secondary validation from FCC equipment authorization databases, ITU-R frequency coordination filings, ETSI technical specification registries, and Brazilian customs terminal import records.
Historical trendline analysis of Ku-Band and Ka-Band deployment trajectories informed projection frameworks across the analysis window. Segmentation dimensions encompassed circuit versus packet switching architectures, frequency band technology, end-use verticals spanning marine and energy sectors, and application types from disaster recovery to precision agriculture telemetry. CAGRs derived from installed base replacement cycles, LEO constellation deployment timelines, and managed service contract renewal patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated terrestrial fiber substitution in West Africa and geopolitical gallium nitride substrate export restrictions. Practitioners should monitor FCC spectrum auction timelines, Anatel hazardous zone certification queue depths, and ITU-R orbital debris mitigation rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
OTN Hardware Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Subscriber Identity Module (SIM) Market