
 Global NPK Fertilizer Market | 2026-2036
Global NPK Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global NPK Fertilizer Market Foresight
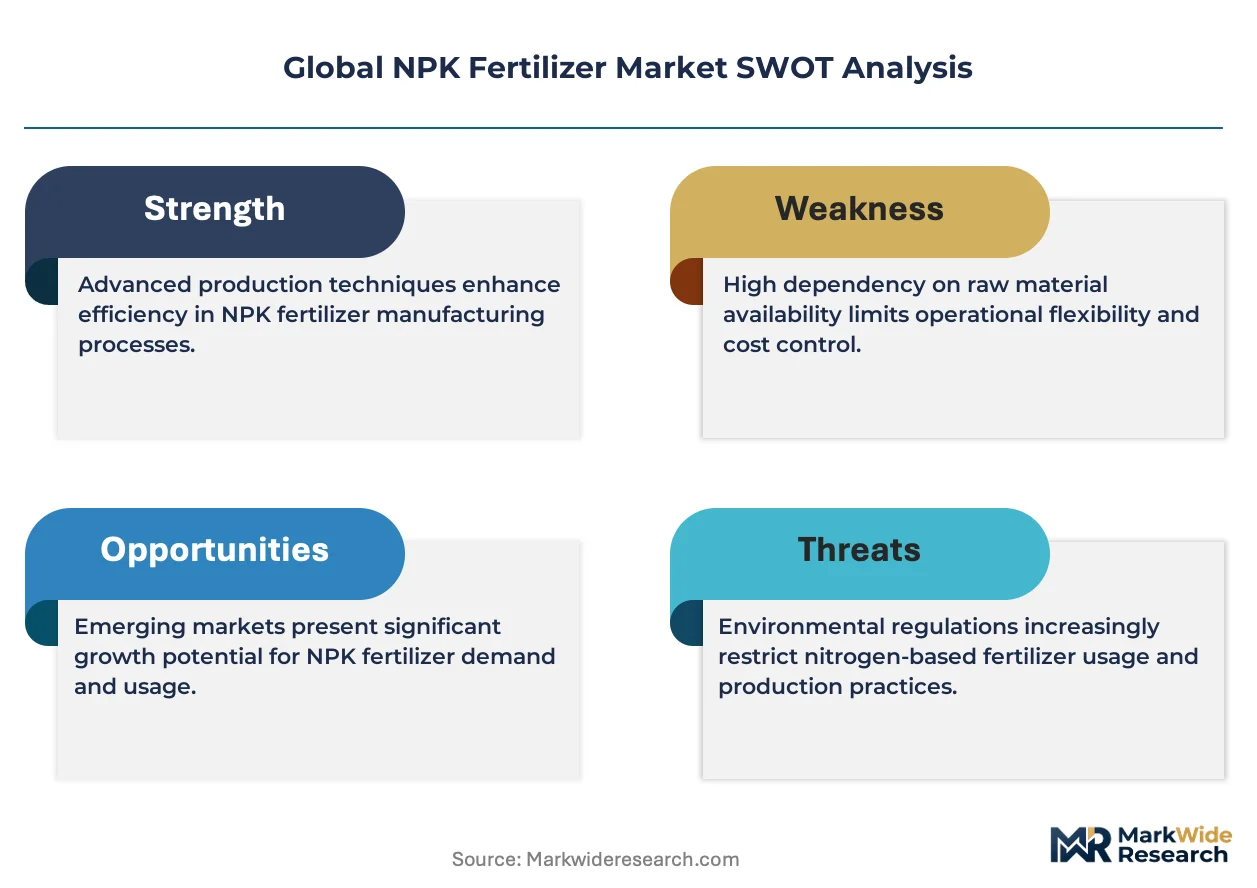
The EU Green Deal is recalibrating nitrogen management standards across European agriculture, compelling fertilizer manufacturers to reformulate blends with reduced ammonia volatilization. Yara International ASA leverages its integrated ammonia and nitrate production network to supply low-carbon footprint NPK variants. Nutrien Ltd. anchors North American distribution through its extensive retail agronomy network. The Mosaic Company competes on phosphate rock access and downstream processing scale.
NPK fertilizers are compound fertilizers containing nitrogen, phosphorus, and potassium in varying ratios, typically manufactured through steam granulation or slurry granulation processes that blend ammonium phosphate, urea, and potash into homogeneous granules with controlled release characteristics. Their primary purpose is to deliver balanced macronutrient supply that corrects soil deficiencies and optimizes crop yield response per hectare. Granular formulations dominate volume due to mechanical spreading compatibility and storage stability, while liquid NPK is gaining traction in horticulture where fertigation systems require rapid nutrient solubility. Cereal crops absorb the largest share of NPK tonnage, though plantation crops in Southeast Asia generate higher per-hectare value margins for specialized coated granule products.
The EPA regulates nutrient runoff under the Clean Water Act, constraining phosphorus application rates in watersheds with impaired water quality and pushing manufacturers toward enhanced-efficiency coatings. REACH and the EU F-Gas Regulation indirectly shape NPK trade flows by embedding carbon intensity metrics into import standards. India's FSSAI and state-level agricultural departments enforce fertilizer quality control through mandatory BIS certification of nutrient content claims. Stakeholders must monitor how carbon border adjustments and soil carbon measurement protocols redefine competitive advantage in fertilizer sourcing decisions.
Market Dynamics
Precision agriculture adoption in Brazil is recalibrating application rates and blend specifications across the NPK value chain, forcing manufacturers to reformulate for variable-rate spreading compatibility.
Growth Catalysts
- India's Soil Health Card Initiative:Government-mandated soil testing is driving demand for balanced NPK formulations tailored to micronutrient deficiencies at the district level.
- EU Green Deal Nutrient Management:The regulation is compelling reformulation toward lower-emission ammonia blends with enhanced-efficiency coatings.
- Steam Granulation Advancements:Process automation is reducing energy intensity per ton while improving granule uniformity for mechanical spreading.
Market Restraints
- Phosphate Rock Concentration:Moroccan and Chinese state-controlled suppliers dominate upstream phosphate concentrate, creating geopolitical supply vulnerability.
- Natural Gas Price Volatility:Ammonia synthesis depends on natural gas feedstock, exposing margins to European and Asian energy market swings.
- Organic Substitution Threat:Compost and biofertilizer alternatives are capturing share in high-value horticulture segments with premium pricing tolerance.
Strategic Opportunities
- Sub-Saharan Africa Underpenetration:Fertilizer application rates below 20 kilograms per hectare in Nigeria and Ethiopia present volume expansion potential.
- Fertigation System Convergence:Integration of liquid NPK with drip irrigation infrastructure is opening specialty horticulture channels in Vietnam and Indonesia.
- Carbon Border Adjustment Mechanism:The EU CBAM is creating first-mover advantage for low-carbon ammonia producers with verified lifecycle assessments.
Industry Challenges
- Enhanced-Efficiency Coating Certification:Validating polymer and sulfur coating performance claims requires multi-season field trials with inconsistent regulatory recognition.
- Legacy Blending Equipment Retrofit:Converting dry granulation lines to handle hygroscopic urea alternatives demands capital outlay with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global NPK Fertilizer Market |
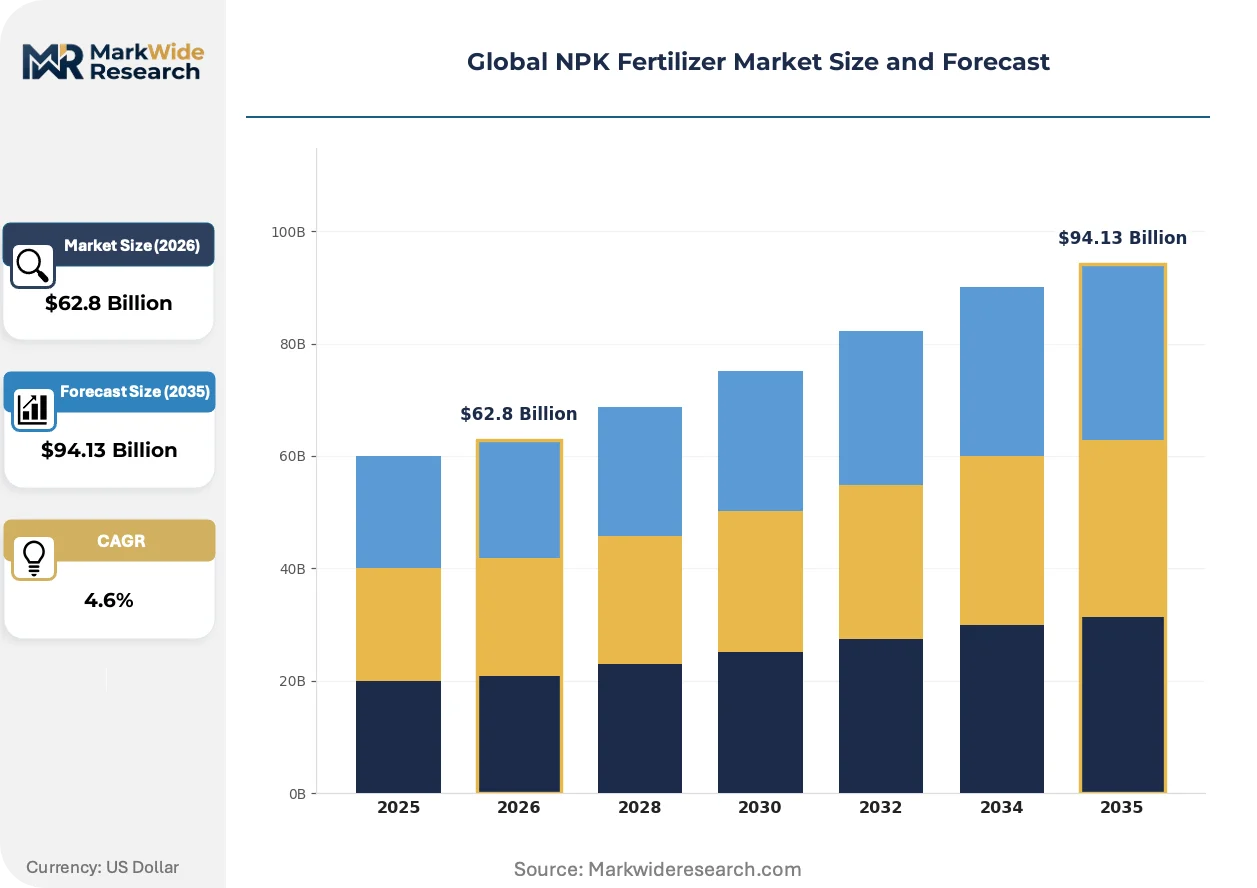
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $94.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triple Superphosphate, Diammonium Phosphate, Ammonium Sulfate, Potassium Chloride Application: Cereal Crops, Horticulture, Plantation Crops, Legumes Form: Granular, Liquid, Powder, Coated Granules End Use Industry: Agrochemical Companies, Agricultural Cooperatives, Contract Farming, Fertilizer Retailers |
| Companies Covered | Yara International ASA, Nutrien Ltd., The Mosaic Company, EuroChem Group AG, ICL Group Ltd., OCP Group, PhosAgro, K+S Aktiengesellschaft, Haifa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global NPK Fertilizer Market Shifts & Advancements
Sensor-based variable-rate application is compressing traditional broadcast spreading models, while regulatory carbon accounting and specialty crop precision dosing are simultaneously reshaping formulation priorities.
Controlled-release polymer coatings are automating nutrient synchronization with crop uptake curves, reducing leaching losses. Large-scale corn and soybean operators in the US Midwest are retrofitting spreaders with prescription-map compatibility. This technology is automating the shift from commodity bulk sales to specification-driven contract supply.
REACH carbon intensity metrics are embedding lifecycle emissions into import standards for ammonia-derived products. Manufacturers must now document Scope 1-3 emissions or face market access restrictions. European compounders are responding by sourcing certified low-carbon ammonia from renewable hydrogen projects.
Soil-test-based prescription purchasing is displacing standard-grade bulk orders among commercial farming cooperatives. Agronomy service providers are bundling testing, recommendation, and product fulfillment into annual contracts. This pattern is most visible in Australia's wheat belt and India's Punjab rice-wheat systems.
Global NPK Fertilizer Market Segmentation
NPK fertilizer segmentation reveals how formulation chemistry, physical state, and distribution channel each dictate margin structure and competitive intensity. Understanding these axes exposes where manufacturers can command specification premiums versus where volume commoditization dominates procurement decisions.
Product Type:
Specification chemistry determines nutrient density, manufacturing energy intensity, and compatibility with downstream blending operations.
- Diammonium Phosphate:Contains nitrogen and phosphorus in an 18-46-0 ratio, manufactured through ammoniation of phosphoric acid. Indian agricultural cooperatives absorb the largest volumes under government subsidy programs, though natural gas price swings compress compounder margins.
- Potassium Chloride:Delivers potassium at 60-62% K2O concentration, typically imported from Canadian or Belarusian mine operations. Brazilian soybean producers are expanding application rates as precision agriculture spreads, driving demand for high-analysis blends.
- Triple Superphosphate:Single-nutrient phosphate source at 46% P2O5, produced through acidulation of phosphate rock. Granulation energy costs disadvantage this format against integrated NPK compounds.
- Ammonium Sulfate:Byproduct of caprolactam and steel processing, supplying nitrogen and sulfur in 21-0-0-24S formulation. Southeast Asian rice systems favor this segment for sulfur-deficient soils.
Mature deployment sits with Diammonium Phosphate. Newer deployment is concentrated in Ammonium Sulfate as sulfur deficiency mapping expands.
Application:
Crop physiology and harvest value per hectare segment the market between volume commodity sales and precision formulation premiums.
- Cereal Crops:Wheat, rice, and corn systems consume the majority of NPK tonnage through broadcast spreading of balanced formulations. Brazilian cerrado expansion and Indian soil health card initiatives are accelerating demand for tailored macronutrient ratios.
- Plantation Crops:Oil palm, rubber, and coffee operations in Indonesia and Vietnam generate higher per-hectare margins, justifying coated granule premiums for controlled nutrient release.
- Horticulture:Protected cultivation of vegetables and fruits requires rapid nutrient solubility for fertigation systems. Greenhouse clusters in the Netherlands and Almeria, Spain drive liquid NPK demand.
- Legumes:Nitrogen-fixing crops require phosphorus and potassium emphasis with minimal nitrogen supplementation. Australian wheat-belt rotations and Argentine soybean systems shape this niche.
Volume leadership belongs to Cereal Crops. Margin expansion is climbing the fastest in Plantation Crops as specialty coating adoption accelerates.
Form:
Physical state governs application equipment compatibility, storage logistics, and nutrient release kinetics.
- Granular:Homogeneous particles manufactured through steam or slurry granulation, optimized for mechanical spreading uniformity. Midwest US corn operations and Ukrainian wheat producers anchor demand for this format.
- Coated Granules:Polymer or sulfur encapsulation synchronizes nutrient release with crop uptake curves. EU Green Deal nitrogen management rules are compelling enhanced-efficiency coating adoption in German and French cereal systems.
- Liquid:Fully soluble concentrates for injection or foliar application, requiring compatible irrigation infrastructure. Vietnamese and Indonesian drip irrigation expansion is opening specialty horticulture channels.
- Powder:Fine-ground blends for manual application or dissolution, concentrated in smallholder markets with limited mechanization. Sub-Saharan African distribution networks favor this format for last-mile accessibility.
Equipment-installed base favors Granular. Technology transition is gaining share fastest in Coated Granules as regulatory pressure intensifies.
End Use Industry:
Channel structure segments procurement scale, technical service requirements, and price sensitivity.
- Agricultural Cooperatives:Member-owned purchasing entities aggregate smallholder demand for bulk negotiation. Indian state-level cooperative federations and Ukrainian agricultural holdings dominate procurement volume.
- Agrochemical Companies:Integrated crop protection providers bundle fertilizer with seed and chemical offerings. Bayer CropScience and Syngenta distribution networks in Brazil and Argentina exemplify this channel.
- Fertilizer Retailers:Independent dealers stock standard grades for walk-in farmer purchases. US farm supply cooperatives and Australian rural merchandisers operate this fragmented tier.
- Contract Farming:Processor-controlled supply chains specify input standards for quality-assured output. Thai sugar miller networks and Kenyan tea estate outgrower schemes illustrate this structure.
Procurement scale concentrates in Agricultural Cooperatives. Service integration is expanding most quickly in Agrochemical Companies as bundled agronomy offerings proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in ammonia-rich regions with natural gas access, while consumption clusters in agricultural zones with intensive cultivation. This geographic mismatch shapes trade flows and regional competitive dynamics.
Brazil
Cereal crop producers in the Cerrado and southern states are expanding NPK application rates as precision agriculture spreads across soybean and corn operations. ANVISA regulates fertilizer quality standards while federal subsidy programs support smallholder access. The Ribeirão Preto agronomy cluster anchors formulation and distribution networks serving the country's grain belt.
India
Government subsidy programs and soil health card initiatives are accelerating balanced fertilizer use among smallholder farmers in Punjab and Haryana. BIS certification enforces nutrient content claims under the Fertilizer Control Order. The Gujarat industrial corridor hosts major compounding facilities supplying western and central agricultural zones.
United States
Midwest corn and soybean operators are retrofitting spreaders with prescription-map compatibility for variable-rate application. EPA regulations under the Clean Water Act constrain phosphorus application rates in impaired watersheds. The Illinois-Iowa agricultural corridor dominates domestic consumption while Louisiana ammonia terminals anchor import infrastructure.
Germany
EU Green Deal nitrogen management rules are compelling reformulation toward lower-emission ammonia blends with enhanced-efficiency coatings. REACH carbon intensity metrics embed lifecycle emissions into import standards for ammonia-derived products. The Rhine-Ruhr chemical complex hosts integrated production and formulation facilities serving northwest European demand.
China
State-controlled suppliers dominate upstream phosphate concentrate while domestic ammonia synthesis serves massive internal cereal crop demand. The country's national environmental regulator enforces discharge standards on fertilizer manufacturing facilities. The Yangtze River Delta industrial zone concentrates granulation and coating technology production for domestic and export markets.
Global NPK Fertilizer Market Competitive Landscape
The competitive structure tilts toward integrated producers with captive ammonia and phosphate rock access. Tier-one players command specification premiums through low-carbon certification and enhanced-efficiency coatings, while regional compounders compete on logistics proximity and subsidy program alignment. Three archetypes dominate: vertically integrated nitrogen-phosphate producers, potash-specialist distributors with retail agronomy networks, and regional blenders serving government procurement channels. Capacity expansion in low-carbon ammonia and strategic partnerships for coating technology licensing represent the dominant competitive moves.
Within the integrated producer tier, Yara International ASA exemplifies the nitrogen-phosphate integration archetype, while Nutrien Ltd. anchors the potash-distributor model. The Mosaic Company occupies a position representing phosphate rock access scale. These three entities collectively illustrate how upstream resource control and downstream retail presence define competitive positioning in compound fertilizer supply.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien Ltd. |
| The Mosaic Company |
| EuroChem Group AG |
| ICL Group Ltd. |
| OCP Group |
| PhosAgro |
| K+S Aktiengesellschaft |
| Haifa Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU Green Deal-compliant low-carbon ammonia blends and standard commodity formulations splits pricing power along carbon-intensity lines, with premium-tier producers commanding offtake premiums through verified lifecycle assessments while commodity compounders absorb natural gas volatility in margin compression.
Pricing Analysis
Margin tightening in standard-grade NPK traces to natural gas feedstock volatility and Moroccan phosphate rock concentration, compressing compounder spreads against fixed subsidy ceilings in India and Brazil. Three-tier pricing structure across premium certified-low-carbon, standard enhanced-efficiency, and economy bulk grades differentiates on carbon footprint verification and coating technology. Price differentiation hinges on REACH-compliant lifecycle documentation and EU CBAM positioning. Smallholder cooperatives in India exhibit highest price sensitivity through government-procurement channels, while German cereal operators accept premium tiers for regulatory compliance.
Supply Chain Analysis
Domestic-content mandates in India's Fertilizer Control Order and Brazil's ANVISA quality standards reshape sourcing toward local compounding facilities, reducing import dependency for finished blends. Upstream ammonia synthesis concentrates in Trinidad, Qatar, and Russia; phosphate rock extraction dominates Morocco and China; potash extraction centers on Saskatchewan and Belarus. Raw material dependencies span natural gas feedstock, phosphate concentrate, and muriate of potash. Single-source vulnerability in Moroccan phosphate rock creates geopolitical exposure. Distribution runs through agricultural cooperative federations in India, retail agronomy networks in North America, and processor-controlled contract farming channels in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NPK fertilizer market functions as a vertical-integration race where captive ammonia production and certified low-carbon ammonia access determine margin sustainability against commodity price cycles.
For Market Incumbents: Cement ammonia supply security through backward integration into natural gas offtake or renewable hydrogen partnerships, locking in feedstock cost predictability against European energy volatility. Fortify coating technology portfolios through exclusive licensing agreements with polymer encapsulation specialists, creating switching costs as EU Green Deal nitrogen management rules harden. Defend against organic substitution threats in high-value horticulture by bundling precision agronomy services with enhanced-efficiency product lines. For New Entrants and Emerging Players: Capture Sub-Saharan Africa's underpenetrated volume opportunity in Nigeria and Ethiopia, where application rates below 20 kilograms per hectare present expansion potential without incumbent saturation. Target Vietnamese and Indonesian specialty horticulture channels through liquid NPK-fertigation system integration, riding drip irrigation infrastructure buildout. Pursue carbon-border-arbitrage positioning by sourcing certified low-carbon ammonia from renewable hydrogen projects ahead of EU CBAM full implementation. For Investors and Strategic Acquirers: Re-rating potential sits with integrated producers possessing verified low-carbon ammonia certification and captive phosphate rock access, given EU carbon border adjustment mechanism implementation and REACH lifecycle embedding trends. Long-term viability over the analysis window favors backward-integrated compounders with retail agronomy network anchoring. Acquisition focus should target regional blenders with government procurement alignment in subsidy-heavy markets. Monitor renewable hydrogen ammonia project commissioning announcements as inflection signals for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Hydrogen Ammonia Partnership | Secures EU CBAM-compliant feedstock for low-carbon NPK variants ahead of carbon border enforcement. |
| Polymer Coating Technology Licensing | Enables controlled-release granule production meeting EU Green Deal nitrogen efficiency mandates. |
| Precision Agronomy Service Bundling | Creates subscription revenue streams displacing commodity bulk sales in Brazilian soybean operations. |
| Sub-Saharan Distribution Network Buildout | Captures volume expansion in Nigeria and Ethiopia where application rates remain below 20 kg/hectare. |
| Soil Health Card Data Integration | Aligns formulation output with India's district-level micronutrient mapping for subsidy program access. |
Research Methodology
Document review covered customs and trade flow databases, EU ETS carbon intensity disclosures, and Indian Fertilizer Control Order regulatory filings, complemented by interviews with ammonia plant operations managers, agricultural cooperative procurement directors, and precision agronomy service providers. Secondary validation drew from SEC 10-K filings of listed compounders, BIS certification registries, and ANVISA quality standard updates. Bottom-up volume modeling triangulated against top-down macroeconomic agricultural output projections.
Cross-referencing historical price series against expert panel input on natural gas feedstock trajectories and phosphate rock contract structures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included formulation chemistry grade, physical state, crop application type, and regional regulatory cluster. CAGRs derived from trend extrapolation of subsidy program enrollment, precision agriculture adoption curves, and carbon border mechanism phase-in schedules. Industry-specific forecast inputs encompassed soil health card distribution rates in India and variable-rate spreader retrofit penetration in the US Midwest.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to renewable hydrogen ammonia project delays, EU CBAM implementation scope revisions, and Moroccan phosphate rock export policy shifts. Forecasts reflect documented assumptions on subsidy continuity, natural gas price normalization trajectories, and coating technology adoption elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
United States Fertilizers Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Soil Conditioners Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market