
 Soil Conditioners Market | 2026-2036
Soil Conditioners Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Conditioners Market Intelligence
The shift from traditional agriculture towards specialized applications like turf management and land reclamation is broadening the market's end-user base. BASF SE leverages its chemical synthesis expertise to offer advanced polymer-based conditioners for industrial uses. Syngenta Group focuses on integrated crop solutions, bundling conditioners with seeds and crop protection products. UPL Limited differentiates through its extensive distribution network in emerging agricultural economies like India and Brazil, reaching small and large farms.
Soil conditioners are materials added to soil to improve its physical properties, such as structure, aeration, and water-holding capacity. They function by aggregating soil particles, which distinguishes them from fertilizers that primarily add nutrients. Organic products like compost and biochar are gaining share due to sustainability trends in horticulture and landscaping. In agriculture, mineral-based conditioners like gypsum remain essential for managing soil salinity and compaction in large-scale farming operations across arid regions.
Regulations from the USDA and the EU's REACH framework govern the composition and safety of synthetic soil conditioners. In parallel, national soil health initiatives in countries like China create market opportunities for products aiding in land reclamation and pollution remediation. The key decision for manufacturers will be balancing investment in biodegradable, organic-certified products against the performance and cost advantages of established synthetic formulations.
Market Dynamics
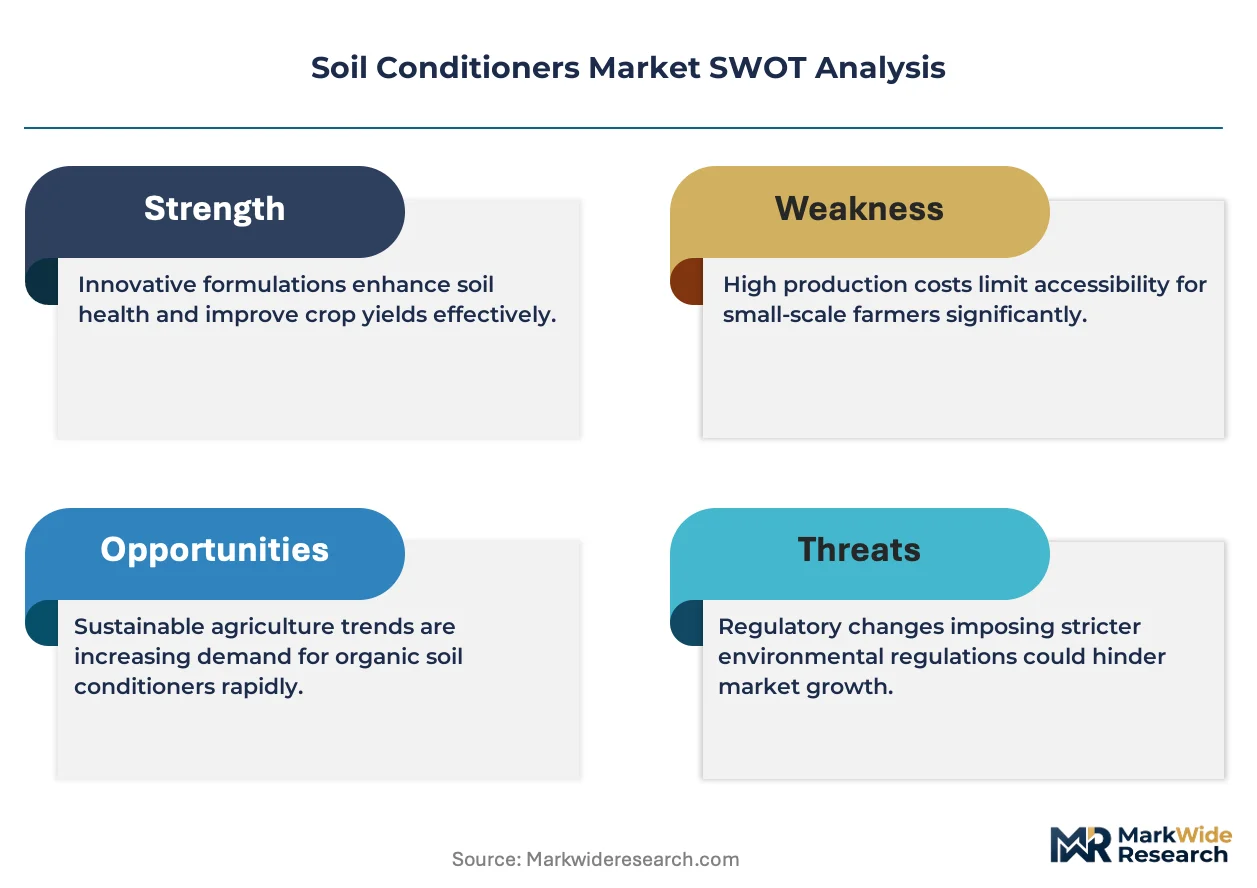
The central dynamic in the soil conditioners market is the tension between the performance-cost advantages of established synthetic products and the rising regulatory and consumer mandate for sustainable, organic alternatives. This conflict shapes investment, product development, and geographic market access.
Growth Catalysts
- Regulatory Frameworks:The EU Green Deal and similar soil health programs from the USDA are mandating improved land management, directly stimulating demand for conditioners that enhance soil structure and reduce erosion in commercial agriculture.
- Specialty Crop Expansion:The growth of high-value horticulture and specialty crop farming in regions like Southeast Asia requires advanced soil management, creating new applications for polymer-based and organic conditioners to optimize growing media.
- Food Security Initiatives:National programs in agricultural powerhouses like Brazil and India aimed at increasing crop yields and reclaiming degraded land are driving the large-scale adoption of mineral conditioners like gypsum to combat soil salinity and compaction.
Market Restraints
- Raw Material Volatility:The cost of synthetic polymers, key inputs for many high-performance conditioners, is subject to fluctuations in petrochemical markets, creating price instability and margin pressure for manufacturers.
- Performance Gaps:Certain organic conditioners, such as compost, exhibit lower efficacy and slower action in correcting severe soil issues like high salinity in arid, large-scale farming compared to mineral-based alternatives.
- Product Substitution:Advanced fertilizer formulations are increasingly incorporating ingredients with soil conditioning properties, presenting a substitution threat and blurring the lines between nutrient management and soil structure improvement.
Strategic Opportunities
- Biodegradable Polymers:There is a significant opportunity to develop and commercialize biodegradable polymer-based conditioners that offer the performance of synthetics with the environmental profile required for organic certification and sustainable farming.
- Industrial Remediation:Expanding applications in land reclamation and environmental remediation for industrial sites, mines, and construction zones opens a new, high-value end-user segment beyond traditional agriculture and landscaping.
- Emerging Market Penetration:Targeting underpenetrated agricultural economies in Africa and Southeast Asia with cost-effective, locally-produced organic conditioners like biochar presents a major volume growth pathway.
Industry Challenges
- Certification Complexity:Manufacturers face significant hurdles navigating the fragmented and costly landscape of organic and environmental certifications, with varying standards between the USDA, the EU, and other national bodies.
- Farmer Education Gap:Driving adoption, particularly in emerging economies, requires substantial investment in farmer education and field support to demonstrate the long-term value and correct application of conditioners versus traditional tillage practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Conditioners Market |
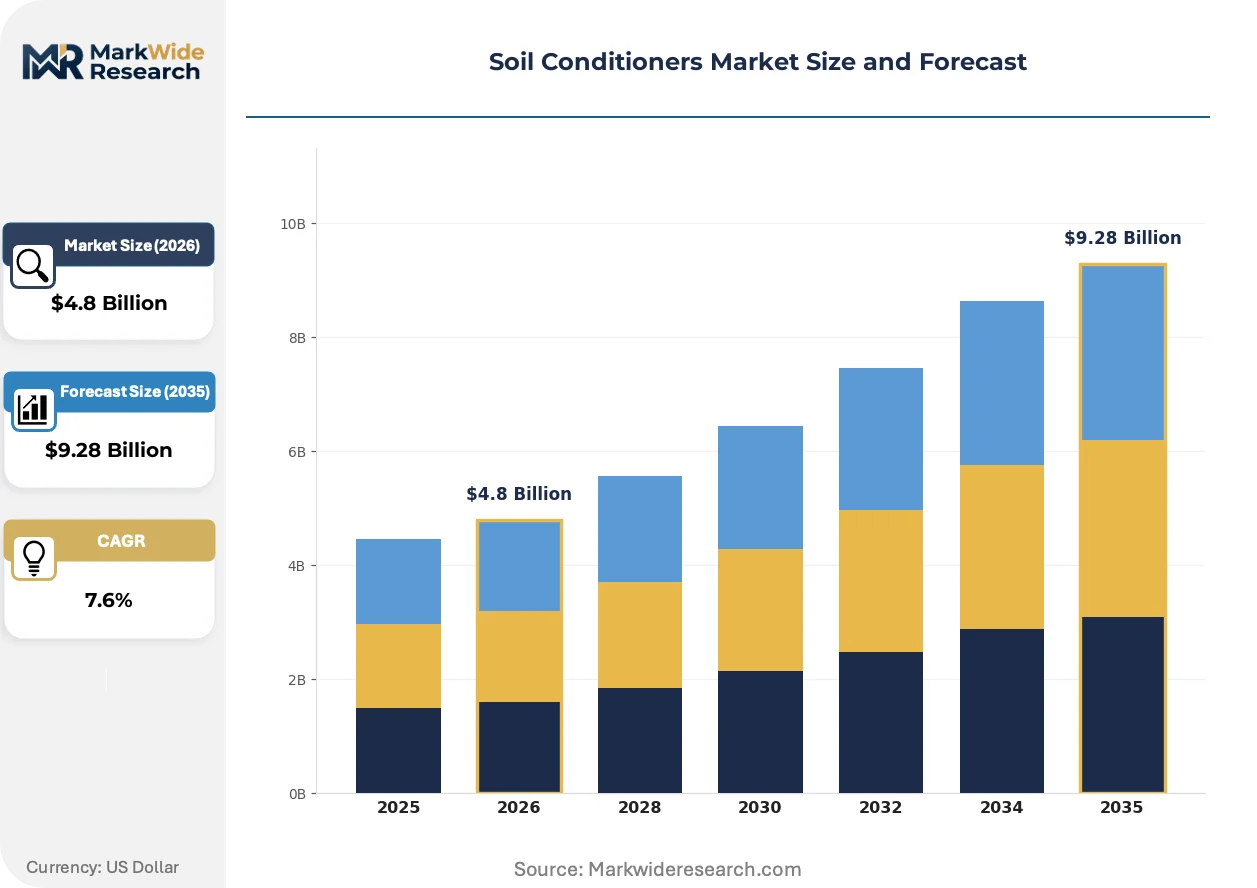
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Peat Moss, Biochar, Vermiculite, Gypsum, Perlite Application: Horticulture, Turf Management, Golf Courses, Landscaping, Erosion Control, Reclamation End User: Plant Nurseries, Greenhouses, Agricultural Farms, Landscape Contractors, Golf Course Managers, Environmental Agencies Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Bales, Drums, Loose |
| Companies Covered | BASF SE, Syngenta Group, UPL Limited, Novozymes, Solvay, Clariant, Evonik Industries, Eastman Chemical Company, FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Conditioners Market Strategic Shifts & Innovations
The convergence of material science and agronomy is defining the next generation of soil conditioners. Innovation is focused on creating specialized products that deliver targeted environmental benefits, such as carbon sequestration and water conservation, alongside traditional improvements in soil structure.
Biochar and microbial inoculants function as advanced organic conditioners that improve soil porosity and biological activity. These products are being adopted by specialty horticulture and regenerative agriculture operations seeking to enhance soil health without synthetic inputs. This trend is decentralizing product innovation away from centralized chemical synthesis toward localized, biomass-based production systems.
China's national soil health policies, overseen by the Ministry of Ecology and Environment (MEE), establish strict guidelines for remediating contaminated land. This framework compels the use of approved soil conditioners in projects aimed at reducing heavy metal toxicity and agricultural pollution. Consequently, product development is shifting toward formulations that meet specific government criteria for environmental remediation in key industrial regions.
Large agricultural enterprises and cooperatives are changing their purchasing behavior from acquiring standalone products to demanding integrated soil management solutions. This disrupts the conventional distributor-led sales channel, creating an advantage for suppliers offering comprehensive packages that include soil analysis, custom-blended conditioners, and ongoing agronomic consulting. This model is gaining traction in the large-scale farming belts of the Americas.
Soil Conditioners Market Segmentation
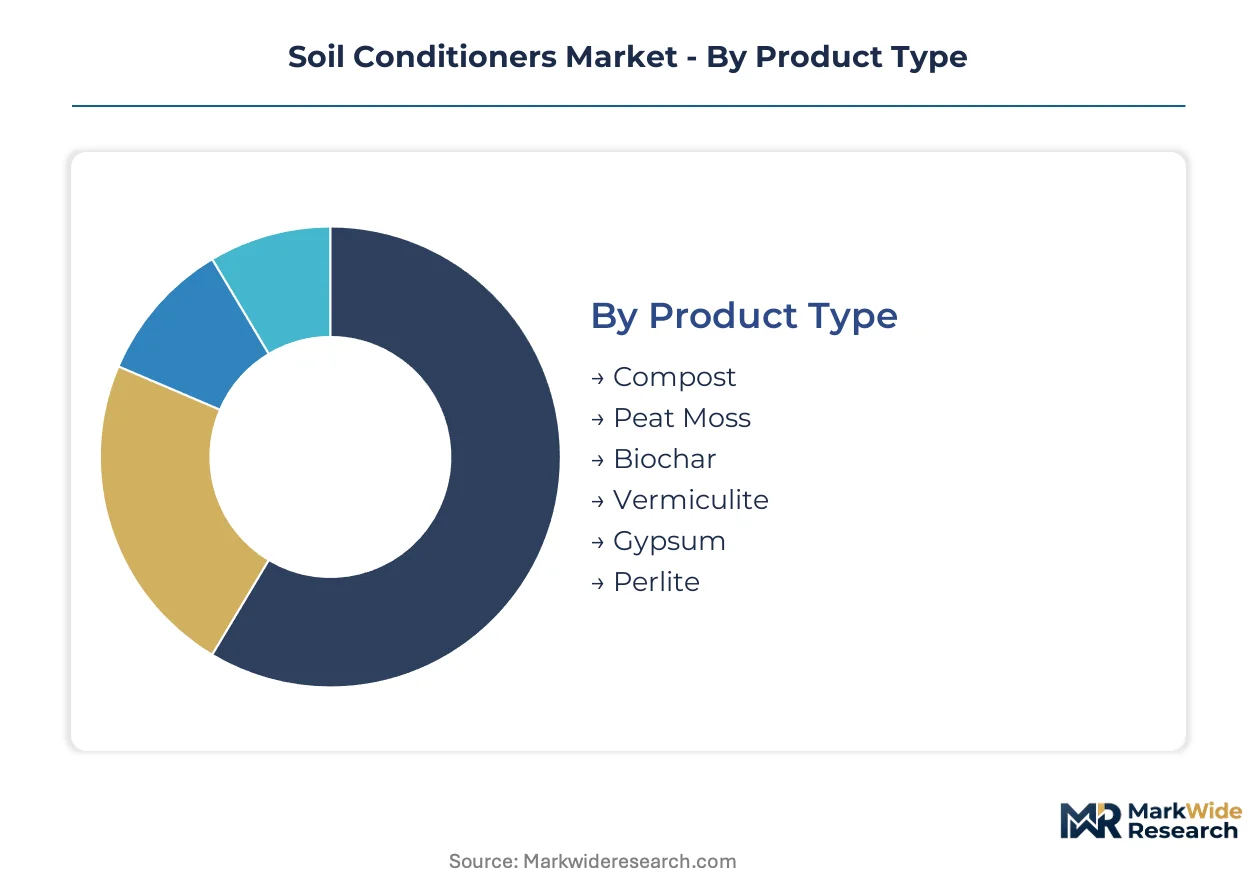
The Soil Conditioners Market is analyzed across various dimensions, revealing how product innovation, application specificities, and end-user requirements influence market dynamics. Understanding these segments provides clarity on demand drivers and competitive positioning for manufacturers.
Product Type:
Product composition and functional characteristics define the core offerings in the soil conditioners market.
- Gypsum:This mineral-based conditioner, calcium sulfate dihydrate, is crucial for managing soil salinity and improving soil structure in large-scale farming. Demand concentrates in arid agricultural regions like Brazil for land reclamation and yield enhancement.
- Biochar:Produced through biomass pyrolysis, this carbon-rich material enhances soil porosity, water retention, and microbial activity. Its adoption is increasing within specialty horticulture and regenerative agriculture dueven to sustainability mandates.
- Compost:Decomposed organic matter, compost improves soil structure and nutrient availability, finding widespread use in landscaping and organic farming.
- Peat Moss:Decomposed sphagnum moss offers high water retention and aeration, commonly incorporated into potting mixes and growing media.
- Vermiculite:A hydrated magnesium aluminum silicate, this lightweight mineral improves aeration and moisture capacity in various horticultural applications.
- Perlite:This volcanic glass is lightweight and porous, providing excellent drainage and aeration for container gardening and hydroponic systems.
Gypsum leads on scale; Biochar leads on momentum.
Application:
End-use applications dictate the specific performance requirements and formulation of soil conditioners.
- Horticulture:This segment involves intensive cultivation of fruits, vegetables, and ornamental plants, requiring precise soil conditioning for optimal growth and yield. High-value specialty crop farming in Southeast Asia drives significant demand.
- Reclamation:Focuses on restoring degraded land, often requiring specialized conditioners to remediate contaminated sites or improve soil structure. China's national soil health policies, overseen by the MEE, mandate specific formulations.
- Turf Management:Conditioners are utilized to maintain healthy, resilient grass surfaces for sports fields, public parks, and commercial properties.
- Golf Courses:This application demands specific soil conditioners for consistent playing surfaces, water retention, and drainage across greens and fairways.
- Landscaping:Conditioners enhance soil quality in gardens, public spaces, and residential areas for aesthetic appeal and plant establishment.
- Erosion Control:These products stabilize soil, reduce runoff, and prevent the loss of topsoil in vulnerable and sloped areas.
The largest volume is seen in Horticulture, while Reclamation exhibits the most dynamic expansion.
End User:
Different end-user groups possess distinct purchasing behaviors, scale requirements, and regulatory compliance needs.
- Agricultural Farms:This segment represents the largest consumer, utilizing conditioners for large-scale crop production to enhance soil structure and combat issues like salinity. Farms in Brazil and India drive significant adoption.
- Environmental Agencies:These agencies drive demand for conditioners in land remediation and pollution control projects, adhering to strict regulatory frameworks. China's MEE mandates specific formulations for contaminated sites.
- Plant Nurseries:Nurseries depend on conditioners for consistent growing media, supporting seedling development and overall plant health.
- Greenhouses:Greenhouses utilize specialized conditioners to optimize controlled growing environments for various high-value crops.
- Landscape Contractors:These professionals integrate conditioners into commercial and residential projects for soil improvement and plant establishment.
- Golf Course Managers:Managers purchase conditioners to maintain turf quality, drainage, and playability across their facilities.
Agricultural Farms command the majority share, with Environmental Agencies showing rapid growth in specialized applications.
Packaging Type:
Packaging solutions reflect the scale of use, distribution channels, and logistical requirements of different market segments.
- Bulk Bags:These large containers facilitate high-volume distribution for industrial and agricultural clients, optimizing logistics and reducing handling costs. Large agricultural enterprises prefer this format for efficiency.
- Plastic Bags:Offering convenience and protection for smaller quantities, plastic bags serve retail customers and smaller-scale horticultural applications. This packaging type supports diverse distribution channels.
- Paper Bags:Paper bags provide an environmentally conscious option for smaller quantities, often preferred for organic-certified products in retail settings.
- Bales:Commonly used for compressed organic materials like peat moss, bales offer efficient storage and transport for nurseries and garden centers.
- Drums:Drums contain liquid or specialized granular conditioners, suitable for precise application in controlled environments.
- Loose:This unpackaged material is typically used for very large-scale projects or direct delivery from production sites.
Bulk Bags dominate industrial procurement, while Plastic Bags demonstrate consistent expansion in consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks, particularly those imposing stringent environmental standards, are prompting a re-evaluation of soil conditioner production locations. This dynamic creates a cost-of-compliance gap, influencing manufacturing investment and market access strategies. Certain regions are attracting investment due to less restrictive policies or abundant raw material access.
Brazil
Brazil's vast agricultural lands demand soil conditioners for land reclamation and yield enhancement in large-scale farming. National food security initiatives prioritize soil health to boost crop production. The Mato Grosso region sees extensive adoption of mineral conditioners like gypsum for soil structure improvement.
India
India's agricultural sector requires significant soil conditioning to increase crop yields and reclaim degraded land. National soil health programs, aligned with food security goals, stimulate the adoption of various conditioners. Farmers in states like Punjab and Haryana increasingly use mineral conditioners to combat soil compaction.
China
China's extensive land reclamation and pollution remediation efforts drive demand for specialized soil conditioners. The Ministry of Ecology and Environment (MEE) enforces strict guidelines for remediating contaminated land. Industrial regions like the Yangtze River Delta focus on formulations reducing heavy metal toxicity.
Indonesia
Southeast Asian nations like Indonesia exhibit growing demand for advanced soil conditioners in high-value horticulture and specialty crop farming. Local sustainable agriculture initiatives encourage the use of organic and polymer-based conditioners. Intensive horticultural production on Java island benefits from these specialized products.
United States
The United States market for soil conditioners is driven by mandates for improved land management and erosion reduction in commercial agriculture. USDA soil health programs directly stimulate demand for products enhancing soil structure. California's Central Valley adopts integrated soil management solutions for specialty crops.
Soil Conditioners Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the soil conditioners market. The industry structure shows a blend of large chemical conglomerates and niche organic product providers. These archetypes compete through strategic partnerships and continuous portfolio diversification. Geographic expansion, especially into emerging agricultural economies, remains a primary competitive move for many players.
Within the diversified chemical solutions archetype, BASF SE exemplifies a global player leveraging its chemical synthesis expertise to offer advanced polymer-based conditioners. Syngenta Group, a Swiss-based agricultural technology company, represents the integrated crop solutions model, bundling conditioners with seeds and crop protection products. UPL Limited, an Indian multinational, anchors the emerging market penetration strategy through an extensive distribution network across agricultural economies like India and Brazil, reaching both small and large farms. These companies demonstrate distinct approaches to market capture and product delivery.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| UPL Limited |
| Novozymes |
| Solvay |
| Clariant |
| Evonik Industries |
| Eastman Chemical Company |
| FMC Corporation |
Cost & Logistics Intelligence
The EU Green Deal and USDA soil health programs gate qualified supply and premium-tier pricing access for sustainable soil conditioners. Manufacturers meeting these mandates command higher prices due to enhanced environmental profiles and regulatory compliance. This dynamic incentivizes investment in certified organic and biodegradable formulations.
Pricing Analysis
Distributor margins significantly influence retail pricing for soil conditioners, especially for specialty horticulture products. Hybrid pricing models combine contract-based long-term offtake for large agricultural farms with per-unit transactional sales for smaller buyers. Price differentiation stems from certification levels, such as organic or MEE-approved, and the volume scale of procurement. Cost compression in economy tiers is intensifying due to raw material volatility, particularly in petrochemical markets for synthetic polymers. Large agricultural farms exhibit high price sensitivity for bulk purchases, while specialty horticulture and landscaping segments are less sensitive for premium, performance-driven products.
Supply Chain Analysis
Logistics and freight costs represent a substantial component of the final price for bulk soil conditioners, impacting regional competitiveness. Supply concentration for mineral conditioners like gypsum is high in Brazil, while biochar production is expanding across China and Southeast Asia. The market depends on petrochemical inputs for polymer-based conditioners, biomass for organic products, and specific mineral deposits. Commodity price volatility for petrochemicals and biomass presents a structural supply chain risk for manufacturers. Distribution runs through specialized agricultural distributors and direct-to-farm channels for large-scale operations, with retail channels serving smaller horticultural and landscaping segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story, driven by the shift towards high-value organic-certified products and specialized industrial remediation applications. These segments offer superior profitability compared to traditional bulk agriculture.
For Market Incumbents: Hedge against raw material price volatility by diversifying feedstock sourcing for polymer-based conditioners and exploring biomass integration. Invest heavily in research and development for biodegradable polymer formulations to align with evolving regulatory shifts. Reinforce existing distribution networks in agricultural powerhouses like Brazil and India to counter emerging market entrants. Pursue strategic partnerships for certification investment, securing access to premium organic and environmentally compliant markets.
For New Entrants and Emerging Players: Begin with localized biochar production, leveraging regional biomass resources to serve specialty horticulture and regenerative agriculture. Target underpenetrated agricultural economies in Africa and Southeast Asia with cost-effective, organic-certified conditioners. Focus on a go-to-market strategy centered on farmer education and field support to demonstrate the long-term value proposition. Develop specialized formulations for niche applications like heavy metal remediation in industrial zones, meeting specific MEE guidelines.
For Investors and Strategic Acquirers: Roll-up economics work for niche organic conditioner producers because fragmented local supply chains and varied regional certifications create consolidation opportunities. The market offers strong long-term viability, driven by global soil health mandates and food security initiatives over the next decade. Target acquisition archetypes include companies with proprietary organic formulations, established distribution in emerging markets, or specialized remediation technologies. A signal to watch is increased government funding for soil health programs and land reclamation projects in key agricultural regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Boosts production of biochar to meet sustainability-driven demand in horticulture. |
| Green Manufacturing Transition | Aligns production with EU Green Deal mandates, opening premium market access. |
| Long-term Supply Agreement | Secures stable access to biomass feedstocks for organic conditioner production. |
| Joint Venture | Facilitates market entry into emerging agricultural economies like Africa with local partners. |
| Product Launch | Introduces new biodegradable polymer conditioners for high-value specialty crops. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust mixed-methods approach. Primary research involved discussions with agronomists, farm managers, environmental agency officials from the USDA and MEE, and chemical engineers. Secondary data sources included USDA reports, EU REACH documents, national agricultural census data, and academic research on soil science. This process enabled bottom-up market sizing, which was then validated through top-down industry estimates.
The segment-weighting approach systematically modeled market dynamics across the analysis window. Product type, application, end user, packaging type, and regional regulatory frameworks were key dimensions for granular market analysis. Compound annual growth rates derive from historical trends, identified market drivers, and strategic initiatives by industry players. Key forecast inputs included global crop yield targets, planned land reclamation project pipelines in China, and evolving regulatory compliance costs.
Several conditions sit outside the modeled scope, including micro-scale hobby gardening or non-commercial applications. Forecasts reflect assumptions on global regulatory stability and raw material supply chain resilience. A model refresh is warranted upon material change in global agricultural policies or climate change impacts influencing soil degradation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
Fertilizer Tester Market