
 China Controlled Release Fertilizer Market | 2026-2036
China Controlled Release Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
China Controlled Release Fertilizer Market Outlook
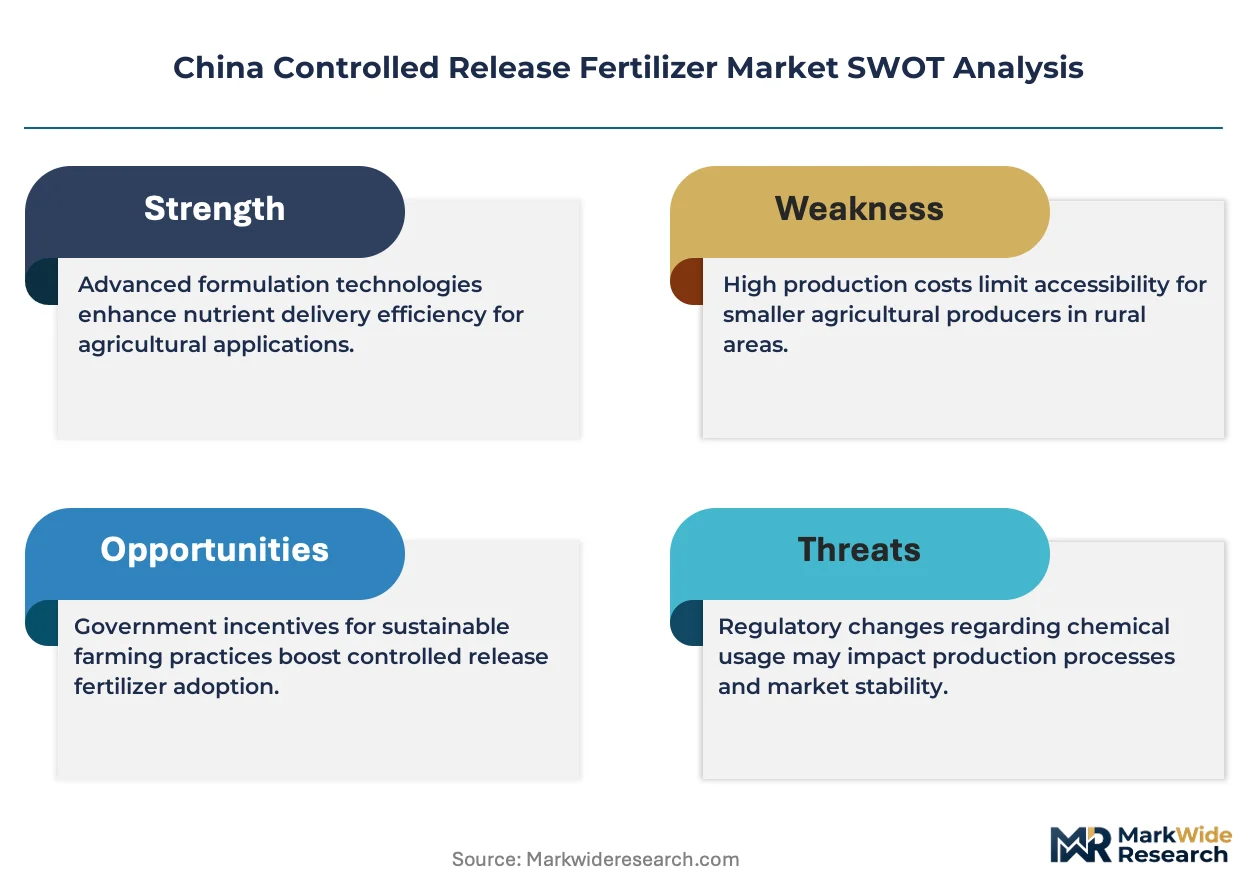
Polymer resin coatings are displacing conventional sulfur-based encapsulation in premium controlled release fertilizer grades, which is realigning unit economics toward higher-margin product lines. Kingenta Ecological Engineering Group leverages its integrated polymer compounding capacity to sustain cost advantages across sulfur-coated and polymer-coated portfolios. Shikefeng Chemical Industry anchors its position through deep specialization in urea-based controlled release formulations for the North China Plain. Stanley Agriculture Group competes by controlling extensive agricultural cooperative distribution networks that reach county-level procurement points.
Controlled release fertilizer comprises granulated or prilled nutrient cores enveloped by semi-permeable membranes—typically sulfur, polymer, or composite layers—that modulate dissolution via osmotic diffusion and temperature-dependent degradation, delivering nitrogen, phosphorus, and potassium over weeks or months to match crop uptake curves and minimize leaching losses. Polymer-coated variants command the most concentrated margin pools due to their precision release profiles in high-value greenhouse and turf applications, while sulfur-coated grades retain volume leadership in broad-acre agricultural crops where cost sensitivity dominates farmer selection. Nutrient-enriched formulations represent the fastest-expanding structural segment as manufacturers integrate micronutrient packages to differentiate within saturated urea-based markets.
China's Ministry of Agriculture and Rural Affairs, the Ministry of Ecology and Environment, and GB standard-setting bodies under SAMR collectively enforce escalating limits on fertilizer runoff intensity and mandate efficiency benchmarks that directly shape product registration requirements and farm subsidy eligibility. The national dual carbon policy framework further compresses acceptance of conventional uncoated fertilizers by embedding carbon intensity metrics into provincial agricultural planning targets. Stakeholders must monitor how county-level subsidy reallocation toward certified low-emission inputs reshapes channel economics and distributor inventory commitments across China's fragmented agricultural supply base.
Market Dynamics
Polymer coating chemistry is compressing the cost gap with sulfur-based alternatives, forcing manufacturers to recalibrate production footprints around Heilongjiang and Shandong clusters where feedstock integration and provincial subsidy density overlap.
Growth Catalysts
- Dual carbon policy framework:Beijing's carbon intensity targets embed controlled release fertilizer eligibility into provincial agricultural planning, redirecting county-level procurement toward certified low-emission inputs.
- North China Plain vegetable operations:High-value greenhouse producers in Shandong and Hebei are converting acreage to polymer-coated formulations to match precision irrigation systems and reduce nitrogen leaching penalties.
- Watershed protection rule tightening:The Ministry of Ecology and Environment's escalating non-point source pollution standards are disqualifying conventional urea from subsidy pools in Taihu and Chao Lake basins.
Market Restraints
- Polymer resin import dependency:Specialty coating materials concentrate among Korean and Japanese petrochemical suppliers, exposing margin compression when yuan-denominated feedstock costs fluctuate.
- Technical release-rate inconsistency:Temperature-sensitive polymer degradation performs unpredictably across Heilongjiang's sub-zero spring planting versus Jiangsu's milder conditions, limiting formulation standardization.
- Conventional urea substitution threat:Un coated granular nitrogen retains dominant acreage coverage in broad-acre corn and wheat belts where cost-per-unit-nitrogen dominates farmer selection criteria.
Strategic Opportunities
- Micronutrient-integrated formulations:Manufacturers are bundling zinc and boron packages into polymer-coated cores to capture premium positioning in specialty fruit districts around Yantai and Dalian.
- Agricultural cooperative channel expansion:County-level procurement consolidation creates direct-to-farm distribution bypassing legacy wholesale layers in Anhui and Henan provinces.
- GB standard certification acceleration:Early alignment with SAMR's evolving efficiency benchmarks secures preferential placement in state-backed demonstration farm programs.
Industry Challenges
- Coating technician skill scarcity:Polymer compounding expertise concentrates among senior engineers at state-owned petrochemical institutes, constraining talent mobility to private fertilizer manufacturers.
- Multi-year certification timelines:Product registration through the Ministry of Agriculture and Rural Affairs requires extensive field trial documentation that delays commercialization of next-generation release profiles.
- Legacy blending equipment incompatibility:Existing rotary drum facilities designed for sulfur-coated urea require substantial retooling to handle temperature-sensitive polymer coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Controlled Release Fertilizer Market |
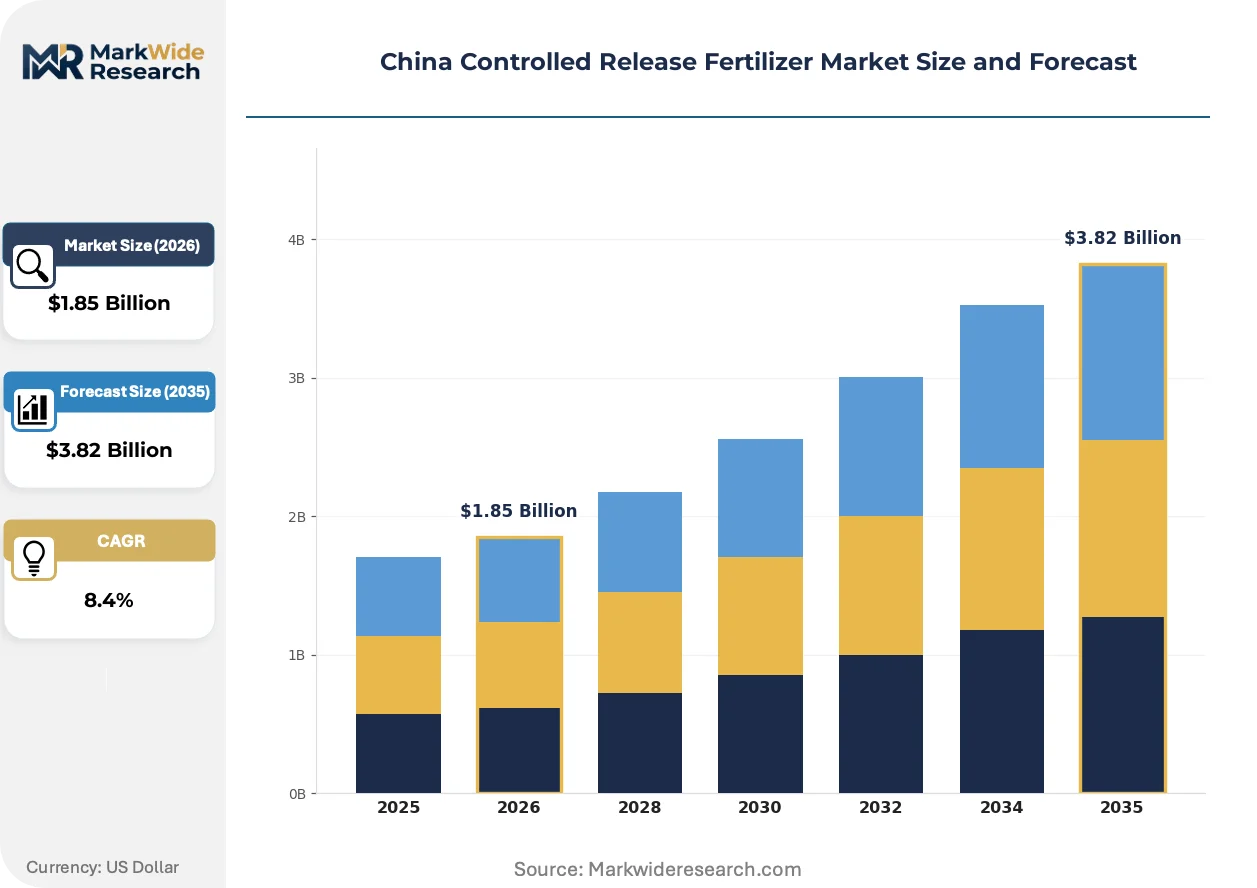
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Based, Sulfur-Coated, Polymer Coated, Nutrient-Enriched Application: Agricultural Crops, Ornamental Plants, Turf Management, Greenhouse Customer Type: Farmers, Agricultural Distributors, Greenhouse Operators, Retailers Distribution Channel: Online Retail, Agricultural Cooperatives, Direct Sales, Wholesale |
| Companies Covered | Kingenta Ecological Engineering Group Co., Ltd., Shikefeng Chemical Industry Co., Ltd., Shandong Humon Agro-chemical Co., Ltd., Stanley Agriculture Group Co., Ltd., Luxi Chemical Group Co., Ltd., China BlueChemical Ltd., Beijing Green Agrosino Plant Nutrition Technology Co., Ltd., Shandong Mingbei Agrochemical Co., Ltd., Hanfeng Evergreen Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Controlled Release Fertilizer Market Strategic Shifts
Coating technology convergence with digital agriculture platforms is redefining how nutrient release synchronization gets specified, purchased, and verified across China's fragmented farm base.
Biodegradable polymer formulations derived from starch-polymer composites are modularizing the controlled release fertilizer value chain. Greenhouse operators in Shandong are piloting these materials to eliminate microplastic soil accumulation concerns while maintaining 90-day nitrogen release curves. The technology is modularizing supplier relationships by enabling regional biopolymer processors to enter coating chemical supply previously dominated by petrochemical incumbents.
GB standard 23348-2009 revisions under SAMR review are tightening dissolution-rate testing protocols and mandating third-party verification for products claiming extended-release certification. The industrial consequence compresses registration timelines for sulfur-coated variants while elevating polymer-coated grades with established laboratory documentation. Shandong and Jiangsu manufacturers with captive testing facilities are accelerating product line conversions to maintain shelf placement in state procurement catalogs.
County-level agricultural bureaus are consolidating fertilizer procurement into volume-based cooperative frameworks that displace independent distributor networks. Vegetable and fruit cooperatives in Hebei are negotiating directly with manufacturers for season-long nutrient programs bundled with technical advisory services. This channel compression is most visible in the North China Plain corridor where high-value crop density justifies dedicated agronomist deployment and inventory pooling across member farms.
China Controlled Release Fertilizer Market Segmentation
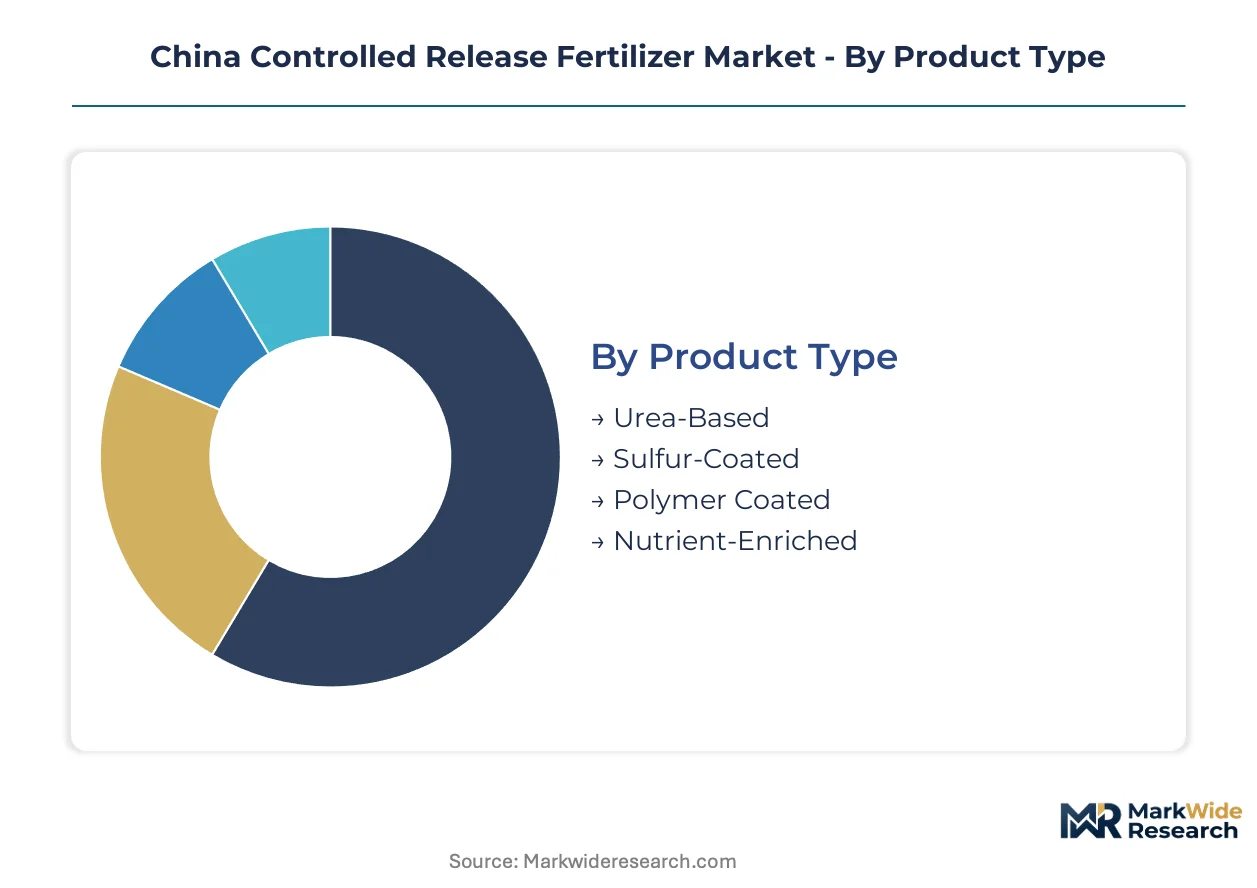
Controlled release fertilizer segmentation in China reflects divergent technical requirements across crop value tiers and procurement consolidation pressures reshaping channel economics. Manufacturers configure coating chemistry, nutrient density, and packaging specifications to match distinct agronomic and commercial workflows.
Product Type:
Customization intensity spans from commodity sulfur encapsulation to precision-engineered polymer matrices with embedded micronutrient payloads.
- Polymer Coated:Multi-layer thermoplastic or thermoset membranes enable temperature-responsive nitrogen diffusion calibrated to specific crop uptake curves. Shandong greenhouse operators specify 60-120 day release profiles for tomato and cucumber rotations to synchronize with drip irrigation schedules and minimize leaching penalties under MEE watershed rules.
- Sulfur-Coated:Molten sulfur encapsulation of urea prills provides cost-controlled release through microbial degradation and physical fracture. Heilongjiang grain producers deploy these formulations across broad-acre corn and soybean belts where cost-per-unit-nitrogen dominates procurement decisions and polymer premiums face resistance.
- Urea-Based:Conventional uncoated or minimally treated granules retain dominant acreage coverage in wheat and rice systems.
- Nutrient-Enriched:Zinc, boron, and iron integration into polymer or composite matrices targets micronutrient-deficient orchard soils.
Most installed capacity flows through Sulfur-Coated. Expansion is steepest in Polymer Coated.
Application:
Margin architecture separates high-frequency greenhouse turnover from seasonal broad-acre deployment cycles.
- Greenhouse:Controlled environment agriculture demands release precision matched to short-cycle vegetable production and substrate-based growing media. Shandong and Hebei protected agriculture clusters specify polymer-coated formulations with 90-day curves for tomato, pepper, and cucumber rotations under intensive fertigation management.
- Agricultural Crops:Open-field grain and oilseed production prioritizes cost efficiency and mechanical spreading compatibility across large contiguous acreages. North China Plain wheat-corn double-cropping systems deploy sulfur-coated urea for basal dressing applications where labor constraints favor single-application nutrient programs.
- Turf Management:Golf courses and municipal landscaping specify extended-release nitrogen for aesthetic maintenance with reduced mowing frequency.
- Ornamental Plants:Nursery and floriculture operations utilize specialized formulations for container production and transplant establishment.
Revenue concentrates in Greenhouse applications. Volume scales fastest in Agricultural Crops as cooperative procurement consolidates.
Customer Type:
Procurement sophistication varies from price-sensitive individual farmers to technically demanding cooperative aggregators.
- Agricultural Distributors:County-level supply houses manage inventory pooling across multiple townships and negotiate manufacturer rebates based on aggregate volume commitments. These intermediaries increasingly bundle controlled release products with soil testing services and credit facilities to defend position against direct cooperative purchasing.
- Greenhouse Operators:Protected agriculture specialists specify precision release profiles and demand technical advisory support for fertigation integration. Shandong tomato cooperatives conduct joint procurement of polymer-coated formulations with synchronized delivery to centralized packing facilities.
- Farmers:Individual smallholders rely on distributor recommendations and subsidy eligibility criteria for product selection.
- Retailers:Agricultural input shops serve last-mile distribution with limited technical consultation capacity.
Transaction volume flows primarily through Agricultural Distributors. Technical specification authority is shifting toward Greenhouse Operators.
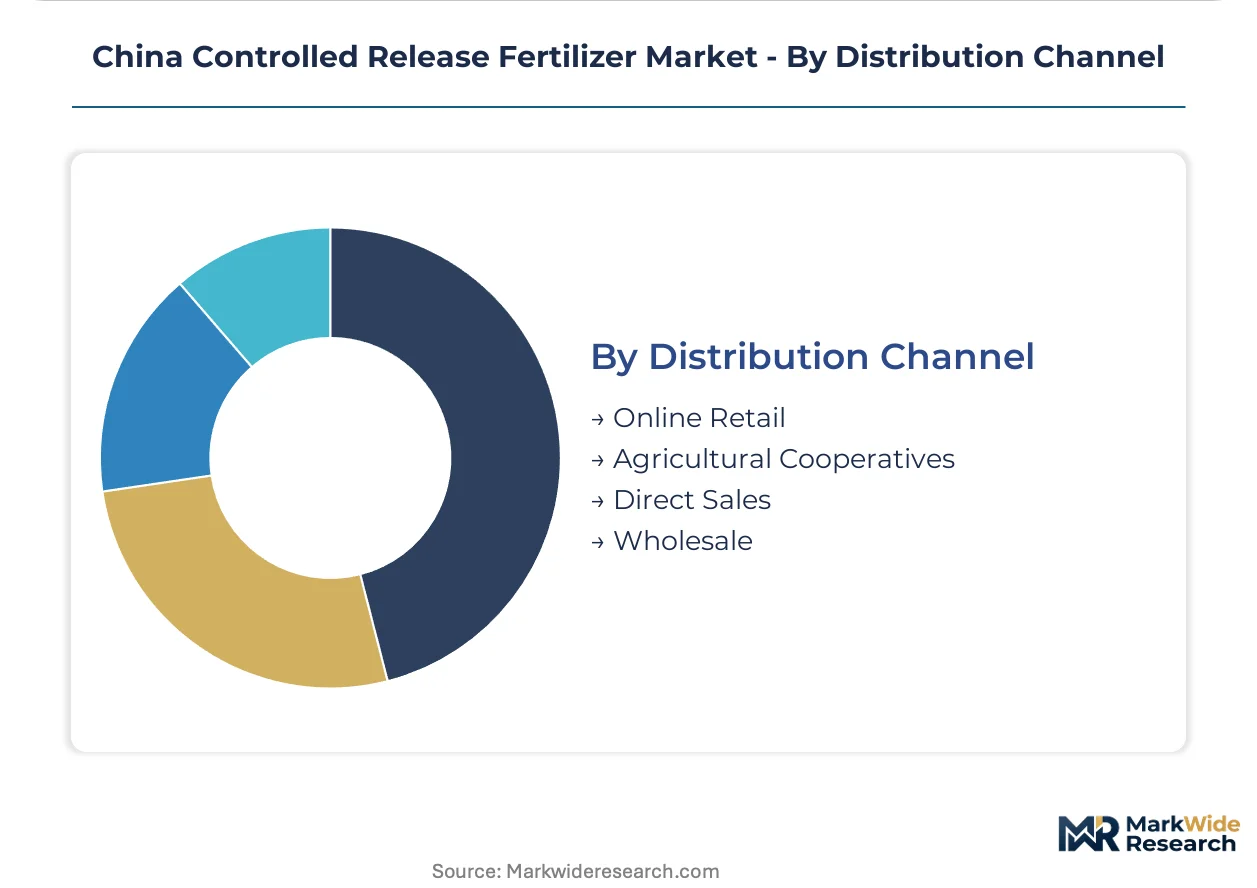
Distribution Channel:
Channel structure reflects the tension between legacy wholesale layering and emerging direct-to-farm consolidation.
- Agricultural Cooperatives:County-level farmer associations aggregate demand across member holdings and negotiate direct manufacturer contracts bypassing traditional distributor markups. Hebei vegetable cooperatives consolidate season-long nutrient programs with technical advisory bundled into volume-based procurement frameworks.
- Direct Sales:Large-scale greenhouse enterprises and state-backed demonstration farms purchase through manufacturer agronomist relationships with customized formulation and delivery scheduling. Kingenta and Stanley maintain dedicated sales teams for direct engagement with high-acreage operators in Shandong and Jiangsu.
- Wholesale:Legacy distributor networks retain penetration in fragmented county markets with limited cooperative organization.
- Online Retail:E-commerce platforms facilitate small-lot procurement for specialty crop producers and input comparison.
Order value concentrates in Agricultural Cooperatives. Direct Sales channels are expanding most quickly as technical service integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North China Plain corridor concentrates procurement gravity for controlled release fertilizer, with Shandong and Hebei provinces anchoring premium-grade demand from greenhouse vegetable operations and provincial subsidy density reshaping distribution economics across county-level agricultural bureaus.
Shandong Province
Greenhouse tomato and cucumber rotations drive polymer-coated formulation specifications matched to drip irrigation systems. The Ministry of Ecology and Environment's watershed protection rules disqualify conventional urea from subsidy pools in Taihu-adjacent catchments. Yantai fruit districts negotiate micronutrient-integrated bundles directly with manufacturers.
Hebei Province
Vegetable cooperatives consolidate season-long nutrient programs through direct manufacturer contracts bypassing legacy wholesale layers. Provincial agricultural planning targets embed carbon intensity metrics that redirect procurement toward certified low-emission inputs. Shijiazhuang corridor distributors bundle controlled release products with soil testing services to defend position against cooperative purchasing.
Heilongjiang Province
Broad-acre corn and soybean belts deploy sulfur-coated urea where cost-per-unit-nitrogen dominates farmer selection criteria. Sub-zero spring planting conditions create technical release-rate inconsistency for temperature-sensitive polymer formulations. Harbin-based grain producers expand acreage under provincial watershed protection compliance programs.
Jiangsu Province
Specialty grain producers around Taihu Lake accelerate uptake of polymer-coated alternatives to reduce nitrogen runoff under tightening non-point source pollution standards. Milder climatic conditions support more predictable polymer degradation curves than northern provinces. Nanjing and Suzhou agricultural bureaus reallocate county-level subsidies toward certified low-emission inputs.
Sichuan-Chongqing Region
Orchard operations in the Red Basin pilot nutrient-enriched formulations targeting micronutrient-deficient citrus soils. Provincial dual carbon implementation compresses acceptance of conventional uncoated fertilizers through embedded carbon intensity metrics. Chengdu agricultural cooperatives negotiate volume-based procurement frameworks with technical advisory bundled.
China Controlled Release Fertilizer Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers recalibrate production footprints around feedstock-integrated clusters in Shandong and Heilongjiang. The vendor base organizes into three tiers: state-backed petrochemical conglomerates with captive sulfur supplies, private specialists with polymer compounding capabilities, and regional blenders serving fragmented county markets. Two strategic archetypes define competitive positioning — integrated manufacturers controlling upstream coating chemistry and distribution-focused operators leveraging agricultural cooperative networks. Geographic expansion into county-level procurement points and portfolio diversification toward micronutrient-integrated formulations represent the dominant competitive moves.
Among Shandong-based integrated manufacturers, Kingenta Ecological Engineering Group Co., Ltd. and Shandong Humon Agro-chemical Co., Ltd. occupy positions exemplifying captive polymer compounding capacity and provincial subsidy alignment. Stanley Agriculture Group Co., Ltd. represents the distribution-centric archetype, with its cooperative network reach illustrating how county-level channel control secures shelf placement in state procurement catalogs. These three companies anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Kingenta Ecological Engineering Group Co., Ltd. |
| Shikefeng Chemical Industry Co., Ltd. |
| Shandong Humon Agro-chemical Co., Ltd. |
| Stanley Agriculture Group Co., Ltd. |
| Luxi Chemical Group Co., Ltd. |
| China BlueChemical Ltd. |
| Beijing Green Agrosino Plant Nutrition Technology Co., Ltd. |
| Shandong Mingbei Agrochemical Co., Ltd. |
| Hanfeng Evergreen Inc. |
| Others |
Value Chain & Pricing Dynamics
County-level agricultural cooperatives in Hebei and Shandong concentrate procurement volume, forcing manufacturers toward contract-based long-term offtake models with technical advisory bundled into premium polymer-coated formulations.
Pricing Analysis
Specialty polymer resin feedstock costs from Korean and Japanese petrochemical suppliers pass through directly into sulfur-coated and polymer-coated tier differentials. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified micronutrient-integrated grades from baseline sulfur-coated urea and uncoated commodity nitrogen. Pricing pressure stems from yuan-denominated import volatility and provincial subsidy reallocation toward certified low-emission inputs. Grain producers in Heilongjiang exhibit highest price sensitivity, while Shandong greenhouse operators absorb polymer premiums for precision release synchronization.
Supply Chain Analysis
Regional distribution centers in Jinan and Harbin anchor hub-and-spoke patterns reaching county-level agricultural bureaus across the North China Plain. Manufacturing concentrates in China, with specialty coating chemicals sourced from South Korea and Japan. Raw material dependencies span sulfur from domestic petrochemical complexes, urea prills from coal-gasification facilities, and thermoplastic resins from Northeast Asian suppliers. Single-source vulnerability in polymer resin imports exposes margin compression during currency fluctuations. Distribution runs through agricultural cooperative procurement frameworks displacing legacy wholesale layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's controlled release fertilizer market represents a late-cycle quality story as watershed protection rules and dual carbon targets redirect procurement toward certified low-emission polymer-coated specifications.
For Market Incumbents: Deploy captive polymer compounding capacity to sustain cost advantages across sulfur-coated and polymer-coated portfolios against emerging regional blenders. Accelerate GB standard certification alignment to secure preferential placement in state-backed demonstration farm programs before county-level subsidy reallocation hardens. Defend against technical release-rate inconsistency risks by establishing field trial documentation across Heilongjiang's sub-zero conditions and Jiangsu's milder climates. For New Entrants and Emerging Players: Launch via direct-to-farm distribution partnerships with vegetable cooperatives in Hebei and Shandong bypassing legacy distributor markups. Target micronutrient-integrated formulation white space in Yantai and Dalian fruit districts where orchard operators negotiate bundled nutrient programs. Exploit coating technician skill scarcity by recruiting senior engineers from state-owned petrochemical institutes into private manufacturing operations. For Investors and Strategic Acquirers: State-backed agricultural conglomerates are the most active acquirer in this space, consolidating regional blenders to secure county-level procurement access. Long-term viability hinges on dual carbon policy durability and watershed protection rule enforcement intensity. Watch for inflection in provincial agricultural planning targets embedding carbon intensity metrics into fertilizer subsidy eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Kingenta's captive resin capacity insulates margin pressure from Korean petrochemical import volatility. |
| GB Standard Certification Acceleration | Early SAMR alignment secures shelf placement in state procurement catalogs before protocol tightening. |
| Agricultural Cooperative Channel Expansion | Stanley's county-level network reach defends position against direct manufacturer contracting in Hebei. |
| Micronutrient-Integrated Formulation Launch | Zinc-boron bundling captures premium positioning in Yantai orchard districts with deficient soils. |
| Biodegradable Polymer R&D Partnership | Starch-polymer composite pilots in Shandong greenhouse operations address microplastic accumulation concerns. |
Study Parameters
Multiple input streams — primary interviews with coating technology directors, provincial agricultural bureau procurement officers, and greenhouse cooperative managers; secondary validation through SAMR GB standard filings, Ministry of Agriculture and Rural Affairs subsidy allocation records, and customs polymer resin import data — were reconciled through bottom-up and top-down triangulation.
Historical consumption patterns were cross-referenced against panel input from fertilizer manufacturers and distributor networks across the projection horizon. Segmentation dimensions modeled include coating chemistry tier, crop application type, customer procurement sophistication, and regional subsidy density. CAGRs were derived from fitted growth curves incorporating dual carbon policy implementation pace and watershed protection rule enforcement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt provincial subsidy reallocation or polymer resin supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Spreader Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Global Urea Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Middle East and Africa Fertilizers Market