
 Global Urea Market | 2026-2036
Global Urea Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urea Market Outlook
Buyer concentration in the global urea market is broadening as state-backed agricultural cooperatives and large-scale agribusinesses displace fragmented smallholder purchasing across key consuming regions. CF Industries Holdings leverages its North American natural gas feedstock advantage to sustain cost-competitive ammonia-to-urea output. Qatar Fertiliser Company anchors Middle Eastern supply through integrated gas-field access and export-terminal control. Yara International differentiates via precision agriculture services bundled with fertilizer distribution.
Urea is a white crystalline organic compound with the chemical formula CO(NH2)2, synthesized industrially through the Bosch-Meiser process combining ammonia and carbon dioxide at pressures exceeding 140 bar and temperatures near 180°C, serving primarily as the world's most concentrated solid nitrogen fertilizer for crop nutrition. Granular urea dominates volume trade flows due to superior handling characteristics and reduced dust generation during bulk shipment. Prilled urea retains structural importance in markets with established blending infrastructure, while liquid urea and urea ammononium nitrate formulations capture growth in mechanized farming systems demanding direct-injection application compatibility.
EPA regulations in the United States govern ammonia plant emissions and water discharge from urea manufacturing facilities, while REACH and the EU Green Deal in Europe impose carbon-intensity thresholds on imported fertilizer products. China's MEE enforces dual carbon goals that constrain coal-based ammonia capacity expansion, redirecting investment toward gas-based and blue-hydrogen routes. Stakeholders must monitor evolving border-adjustment mechanisms and low-carbon certification schemes that will increasingly determine market access and procurement eligibility across major importing jurisdictions.
Market Dynamics
The EU F-Gas Regulation and Green Deal frameworks are compressing margins for coal-based ammonia producers while redirecting capital toward gas-based and blue-hydrogen manufacturing routes across the European supply base.
Growth Catalysts
- India's Nutrient-Based Subsidy scheme:Government procurement mandates sustain large-volume urea offtake from state-backed agricultural cooperatives, insulating demand from global price volatility.
- Precision agriculture bundling:Fertilizer distributors are integrating soil-sensor analytics and variable-rate application services with bulk urea sales, locking in multi-year supply contracts.
- Blue-hydrogen feedstock transition:Carbon capture integration at ammonia plants is qualifying output for low-carbon certification schemes in import-dependent jurisdictions.
Market Restraints
- Natural gas price volatility:Ammonia synthesis consumes 70-80% of production costs in gas feedstock, exposing margins to Henry Hub and TTF benchmark swings.
- Middle Eastern supply concentration:Qatar, Saudi Arabia, and Iran control roughly half of globally traded urea volumes, creating single-source dependency risks for importers.
- Controlled-release fertilizer substitution:Polymer-coated urea and stabilized nitrogen products are capturing share in high-value horticulture and specialty crop segments.
Strategic Opportunities
- Brazilian Cerrado expansion:Mechanized soybean and corn operations in Mato Grosso and Goiás are converting from ammonium nitrate to liquid urea-ammonium nitrate for direct-injection compatibility.
- EU Carbon Border Adjustment Mechanism:Importers with verified low-carbon ammonia production will gain preferential procurement eligibility under forthcoming fertilizer certification protocols.
- Digital agronomy platforms:Mobile-based prescription tools are enabling smallholder cooperatives in Bangladesh and Vietnam to aggregate demand and access import-parity pricing.
Industry Challenges
- Process safety engineering scarcity:Ammonia plant operators face acute shortages of pressure-vessel specialists certified to ASME and EN standards for high-pressure Bosch-Meiser synthesis loops.
- Legacy blending infrastructure lock-in:Prilled urea handling systems at port terminals and inland depots require capital-intensive retrofitting to accommodate granular product flows.
- Dual-carbon compliance timelines:China's MEE enforcement of carbon intensity targets is forcing coal-based producers to accelerate asset write-downs ahead of technical lifecycles.
Report Scope
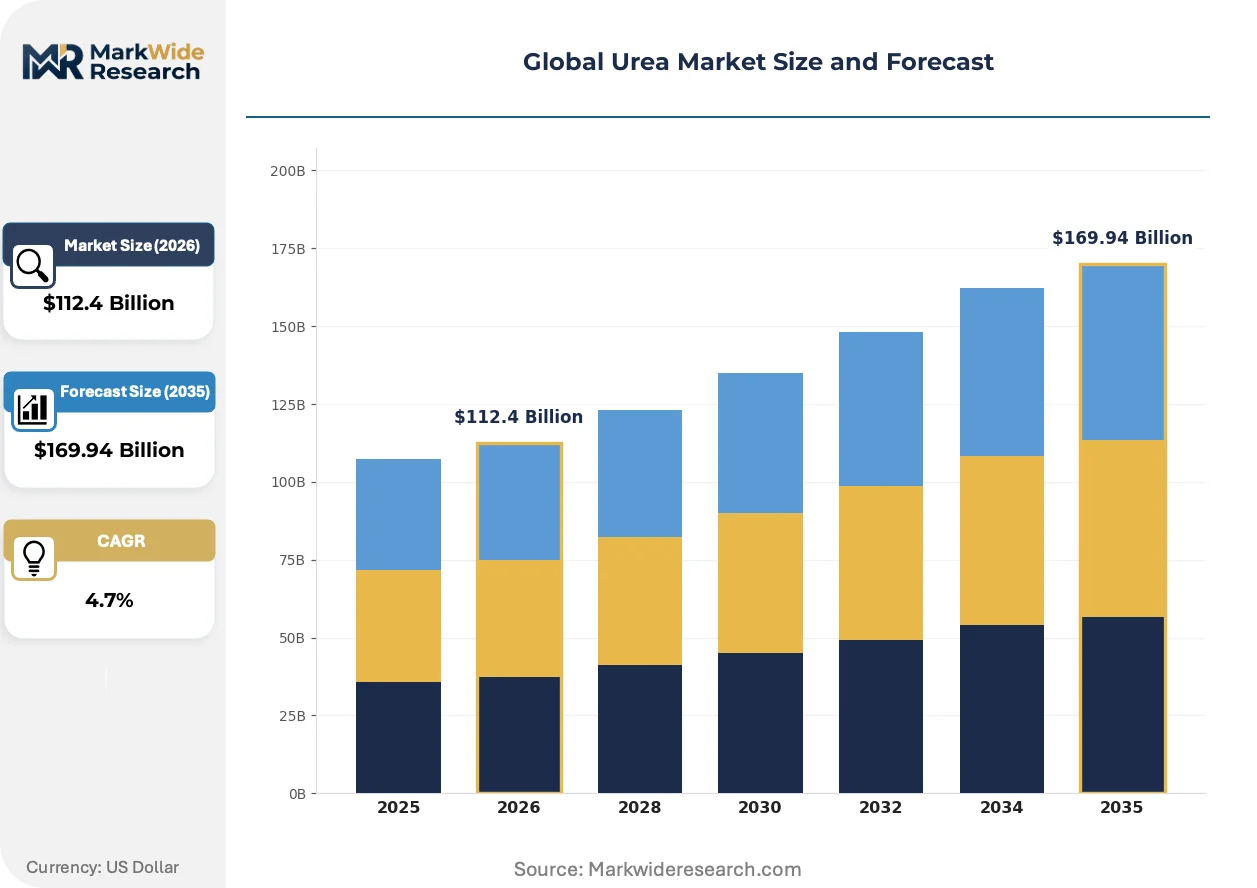
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urea Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Urea, Prilled Urea, Liquid Urea, Urea Ammonium Nitrate Application: Agriculture, Industrial, Fertilization, Animal Feed Formulation: Coated Urea, Slow-Release Urea, Fertilizer Blends, Standard Urea End User: Farmers, Agribusinesses, Chemical Manufacturers, Livestock Producers |
| Companies Covered | Nutrien Ltd., Pupuk Indonesia, CF Industries Holdings, Inc., Qatar Fertiliser Company, EuroChem Group, Yara International ASA, OCI, BASF SE, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urea Market Strategic Shifts
Automation of manufacturing processes, carbon-accounting integration, and procurement centralization are restructuring how urea moves from ammonia synthesis to farm-gate application.
Electrolytic hydrogen feedstock systems are automating ammonia production scheduling by enabling modular, demand-responsive synthesis units that bypass conventional reformer economics. Nordic fertilizer producers are piloting 20 MW PEM electrolyzer stacks integrated with small-scale Haber-Bosch loops, compressing batch-cycle times from continuous reformer dependency to hourly load-following. This architecture is automating capacity utilization decisions based on real-time renewable power pricing rather than long-term gas supply contracts.
REACH authorization requirements for ammonia plant catalysts and corrosion inhibitors are forcing reformulation of process chemicals across European manufacturing assets. ECHA substance evaluation deadlines in 2025-2027 are accelerating substitution of hexavalent chromium coatings in high-pressure vessel maintenance protocols. German and Dutch producers are responding by qualifying nickel-based alternatives through joint industry consortia to preserve equipment warranties and insurance coverage.
State-backed cooperative procurement is displacing spot-market purchasing across South Asian import channels. India's National Fertilizers Limited and Bangladesh Agricultural Development Corporation are consolidating annual tenders into multi-year framework agreements with Qatari and Saudi suppliers, compressing price discovery volatility. This concentration is most visible in Kandla and Chittagong port clusters, where dedicated berth allocations and inventory financing now accompany volume commitments.
Global Urea Market Segmentation
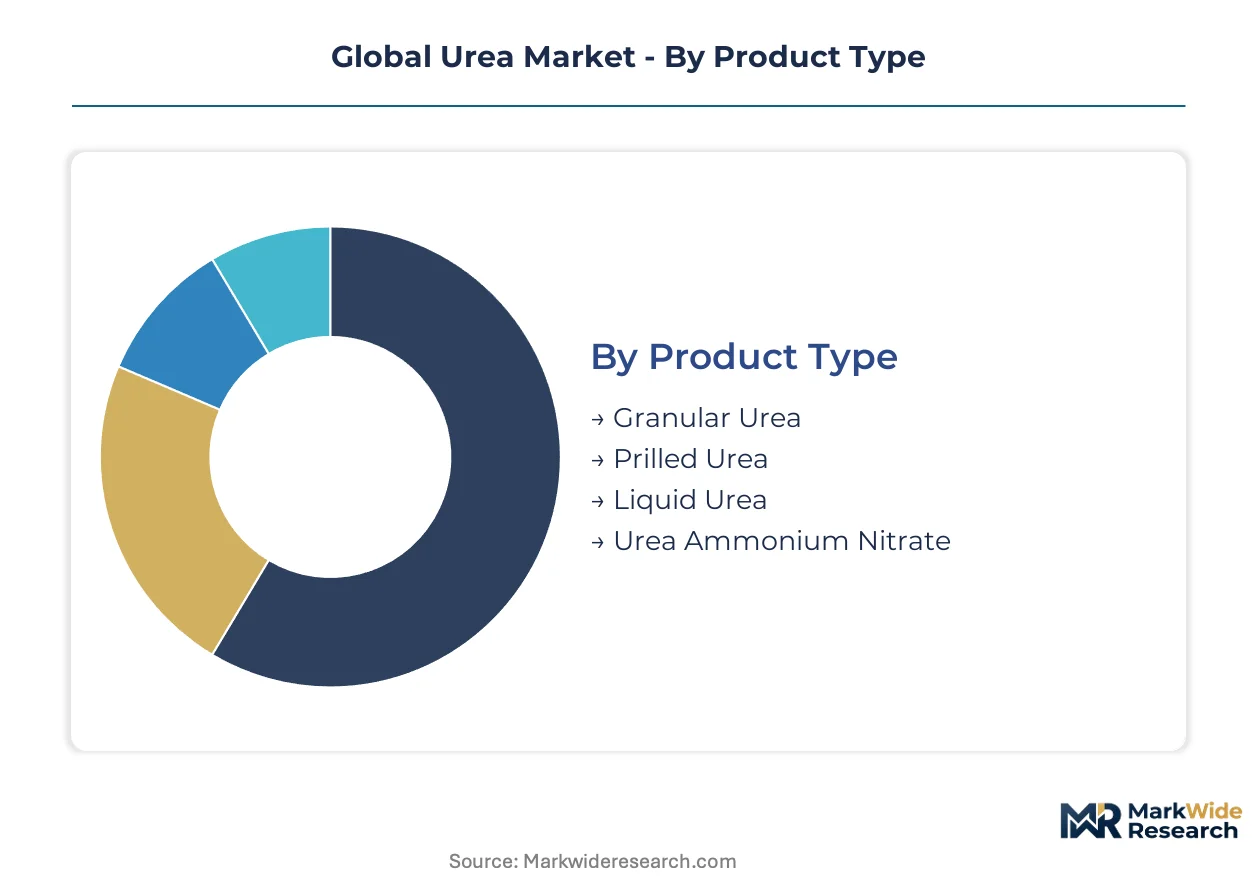
Urea demand fragments across physical forms, application intensities, and user procurement scales. Each segment carries distinct logistics requirements, pricing benchmarks, and regulatory exposure that shape supplier positioning.
Product Type:
Granular formats command volume flows while liquid derivatives capture premium mechanization markets.
- Granular Urea:Spherical pellets manufactured through fluidized-bed cooling deliver superior crush strength and reduced dust generation during bulk ocean freight. Port terminals at Kandla, Mundra, and Chittagong now dedicate specialized handling infrastructure to granular flows as Indian and Bangladeshi procurement consolidates around this format.
- Prilled Urea:Solid droplets formed by spraying molten urea into cooling towers retain dominance in markets with legacy blending infrastructure. Russian and Ukrainian export terminals continue shipping prilled product to Brazilian and Turkish compounders whose rotary drum blenders require specific particle size distributions.
- Liquid Urea:Aqueous solutions enable direct-injection application through precision agriculture equipment.
- Urea Ammonium Nitrate:Blended nitrogen formulations serve mechanized farming operations demanding uniform nutrient distribution.
Mature deployment sits with prilled urea. Newer deployment is concentrated in granular formats.
Application:
Crop nutrition absorbs the dominant volume share while industrial gas treatment commands technical specifications.
- Agriculture:Basal and top-dressing applications for cereal, oilseed, and fiber crops constitute the foundational demand base. Indian state procurement through the Nutrient-Based Subsidy scheme and Chinese spring planting campaigns synchronize seasonal offtake patterns across the Northern Hemisphere.
- Industrial:Diesel exhaust fluid production for NOx abatement in heavy-duty vehicles and selective catalytic reduction systems at power plants requires automotive-grade urea with strict biuret limits. German automotive suppliers and Korean shipbuilders enforce ISO 22241 purity certifications that disqualify agricultural-grade material.
- Fertilization:Direct soil amendment and foliar feeding applications in horticulture and specialty crops.
- Animal Feed:Ruminant nutrition applications utilize feed-grade urea as a non-protein nitrogen source.
Volume concentration remains with agriculture. Technical margin expansion is climbing the fastest in industrial applications.
Formulation:
Standard commodity grades face substitution pressure from enhanced-efficiency variants targeting environmental compliance.
- Coated Urea:Polymer or sulfur encapsulation delays nitrogen release to match crop uptake curves and reduce leaching losses. Dutch and Danish distributors bundle coated products with nitrate directive compliance services for farms in vulnerable groundwater zones.
- Slow-Release Urea:Chemical stabilization through urease or nitrification inhibitors extends soil residence time. Japanese golf course managers and California almond growers absorb price premiums to meet runoff restrictions imposed by regional water quality control boards.
- Fertilizer Blends:Physical mixtures with phosphate and potassium sources tailored to soil test recommendations.
- Standard Urea:Unmodified crystalline product for immediate nitrogen availability.
Standard formulations dominate procurement tonnage. Value-added deployment is gaining share fastest in coated variants.
End User:
Procurement scale separates price-takers from price-makers across the demand base.
- Farmers:Individual smallholders and family operations purchase through cooperative aggregators or retail dealer networks. Vietnamese rice growers and Bangladeshi vegetable producers access import-parity pricing through mobile-enabled cooperative platforms that consolidate village-level demand.
- Agribusinesses:Large-scale farming enterprises and integrated food producers negotiate direct supply contracts with Qatari and Saudi exporters. Mato Grosso soybean operators and Australian wheatbelt corporations secure dedicated vessel charters and inventory financing arrangements.
- Chemical Manufacturers:Industrial gas treatment and resin synthesis operations requiring certified purity grades.
- Livestock Producers:Feedlot and dairy operations incorporating non-protein nitrogen into ration formulations.
Fragmented procurement characterizes farmer segments. Consolidated contracting defines agribusiness engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas fields in Qatar and the Permian Basin anchor urea production economics, while import-dependent agricultural zones in South Asia and Brazil absorb traded volumes. Regional differentiation stems from feedstock access, subsidy regimes, and port infrastructure maturity.
India
State procurement through the Nutrient-Based Subsidy scheme sustains annual offtake exceeding 30 million tonnes. The Department of Fertilizers mandates indigenous production quotas and imports through designated canalizing agencies. Kandla and Mundra port clusters on the Gujarat coast handle granular urea flows from Qatari and Saudi suppliers under long-term framework agreements.
China
Coal-based ammonia capacity in Shandong and Shanxi provinces faces enforced curtailment under MEE dual-carbon compliance timelines. The Ministry of Ecology and Environment redirects investment toward gas-based and blue-hydrogen routes in coastal zones. Yangtze River Delta fertilizer complexes are retrofitting carbon capture to qualify for low-carbon export certification schemes.
Brazil
Mechanized soybean operations in Mato Grosso convert from ammonium nitrate to liquid urea-ammonium nitrate for direct-injection compatibility. ANVISA and environmental licensing frameworks govern storage terminal construction in Amazon-adjacent zones. Paranaguá and Santos port terminals receive granular shipments from Middle Eastern producers under seasonal import windows synchronized with planting calendars.
United States
Henry Hub gas pricing determines ammonia plant operating rates across Louisiana and Iowa production corridors. EPA emissions standards for ammonia synthesis loops and water discharge permits constrain capacity expansion in the Gulf Coast petrochemical belt. Corn Belt distribution cooperatives in Illinois and Iowa negotiate volume commitments with domestic producers to manage inventory exposure.
Germany
REACH authorization deadlines for catalysts and corrosion inhibitors force reformulation of process chemicals at Ludwigshafen and Brunsbüttel manufacturing sites. ECHA substance evaluation timelines accelerate substitution of hexavalent chromium coatings in high-pressure vessel maintenance. German producers qualify nickel-based alternatives through joint industry consortia to preserve equipment warranties.
Global Urea Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue low-carbon certification and precision agriculture bundling. The market structures around integrated gas-field operators, North American gas-feedstock specialists, and European precision-service bundlers. Three archetypes dominate: feedstock-integrated exporters, cost-optimized regional suppliers, and agronomy-service integrators. Capacity expansion and strategic partnerships constitute the dominant competitive vectors, with carbon-capture retrofitting and digital platform alliances gaining traction.
Within the feedstock-integrated tier, Qatar Fertiliser Company and SABIC anchor Middle Eastern supply through captive gas-field access and export-terminal control. CF Industries Holdings exemplifies the North American gas-feedstock model, leveraging Permian Basin and Appalachian supply proximity. Yara International occupies the service-integration position, bundling soil-sensor analytics and variable-rate application protocols with bulk product distribution.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Pupuk Indonesia |
| CF Industries Holdings, Inc. |
| Qatar Fertiliser Company |
| EuroChem Group |
| Yara International ASA |
| OCI |
| BASF SE |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Captive natural gas feedstock integration anchors both the supply position and the pricing power of Middle Eastern producers, insulating Qatar Fertiliser Company and SABIC from Henry Hub volatility that compresses margins for North American competitors. This upstream control enables long-term offtake contracting at indexed premiums while coal-based Chinese producers face margin erosion under MEE dual-carbon enforcement.
Pricing Analysis
Warranty and application-service bundling separates premium contract tiers from unbundled spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon-certification grade and volume-commitment scale. Pricing pressure stems from natural gas feedstock volatility exposing non-integrated producers to TTF benchmark swings. Smallholder cooperatives in Bangladesh and Vietnam exhibit highest price sensitivity; state-backed Indian procurement through the Nutrient-Based Subsidy scheme demonstrates lowest sensitivity due to government volume guarantees.
Supply Chain Analysis
Empty container repositioning and bulk vessel cleaning cycles create reverse-logistics cost layers at port terminals handling both fertilizer and non-fertilizer cargoes. Production concentrates in Qatar, Saudi Arabia, and Russia; China and the United States anchor secondary supply bases. Feedstock draws from associated gas fields, Permian Basin wet gas, and Australian coal seams. Single-source dependency on Middle Eastern export terminals creates vulnerability to Red Sea route disruptions. Distribution runs through dedicated berth allocations at Kandla, Mundra, and Chittagong serving state procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Carbon Border Adjustment Mechanism erects a compliance-cost moat that favors producers with verified low-carbon ammonia certification, locking out coal-based entrants from European procurement eligibility.
For Market Incumbents: Extend carbon-capture retrofitting timelines at coastal ammonia complexes to secure EU CBAM-compliant certification ahead of enforcement windows. Consolidate framework agreements with Indian state procurement agencies to lock in volume commitments before Bangladesh and Vietnam cooperative platforms mature. Defensive positioning against precision-agriculture bundlers requires integrating soil-sensor analytics with bulk urea distribution.
For New Entrants and Emerging Players: Capture mechanized farming conversion in Brazil's Cerrado region where Mato Grosso soybean operators shift from ammonium nitrate to liquid urea-ammonium nitrate. Target digital agronomy platform partnerships in Bangladesh and Vietnam that aggregate smallholder demand into import-parity purchasing power. Go-to-market execution should anchor on mobile-based prescription tools bundled with inventory financing.
For Investors and Strategic Acquirers: Exit pathways concentrate in feedstock-integrated Middle Eastern assets with captive gas-field access and long-term offtake visibility. Five-to-ten-year viability favors producers with blue-hydrogen transition roadmaps and carbon-capture operational experience. Monitor EU CBAM implementation pace and low-carbon certification scheme mutual-recognition agreements as inflection signals for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofitting | Qualifies output for EU CBAM compliance and low-carbon procurement eligibility. |
| Backward Integration into Gas Fields | Secures feedstock cost advantage against Henry Hub volatility exposure. |
| Precision Agriculture Platform Partnership | Locks multi-year supply contracts through bundled soil-sensor analytics. |
| Long-term Supply Agreement | Compresses price discovery volatility with Indian state procurement channels. |
| Blue Hydrogen Feedstock Transition | Redirects capital from coal-based routes under MEE dual-carbon enforcement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with ammonia plant operators, procurement leads at Indian state fertilizer agencies, port terminal managers, and precision-agriculture platform developers supplied operational validation. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis from import-export databases and production corridor assessments.
Reconciling shipment-level customs data with plant-level production disclosures generated volume estimates across the projection horizon. Segmentation dimensions encompassed physical form tier, application intensity, end-user procurement scale, and regional regulatory cluster. CAGRs derived from trend extrapolation of feedstock cost trajectories, subsidy policy continuity assumptions, and mechanization adoption curves in target agricultural zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU CBAM implementation timing, Middle Eastern export route security, and renewable hydrogen cost parity breakthroughs. Practitioners should monitor Qatari and Saudi framework agreement renewal patterns, Indian Nutrient-Based Subsidy allocation adjustments, and PEM electrolyzer deployment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Compound Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
India Urea Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
South Africa Fertilizer Market