
 Ammonium Thiosulfate Fertilizer Market | 2026-2036
Ammonium Thiosulfate Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Thiosulfate Fertilizer Market Insights
Direct-to-farm distribution is reshaping how ammonium thiosulfate reaches end users, bypassing traditional dealer networks in favor of volume contracts with large cooperatives. Koch Fertilizer leverages its integrated pipeline and terminal infrastructure to control last-mile delivery economics across the Plains states. Nutrien Ltd. anchors its position through retail agronomy networks that bundle ATS with prescription nitrogen programs. Tessenderlo Kerley specializes in liquid sulfur chemistry, sustaining technical differentiation through proprietary corrosion inhibitors that extend storage compatibility.
Ammonium thiosulfate is a crystalline inorganic salt with the formula (NH₄)₂S₂O₃, containing 12% nitrogen and 26% sulfur by weight, manufactured via reaction of ammonia with sulfur dioxide in aqueous solution. It serves primarily as a sulfur-bearing fertilizer and as an effective nitrification inhibitor when co-applied with urea-ammonium nitrate solutions. Liquid formulation dominates volume shipments due to compatibility with fertigation systems and sidedress equipment, while specialty crops command premium positioning through precision sulfur timing protocols. Granular forms occupy a narrower niche in dry-blend operations where equipment limitations preclude liquid handling.
The EPA oversees nutrient management under the Clean Water Act, pressuring states to adopt phosphorus and nitrogen reduction strategies that elevate sulfur-balanced fertilization practices. OSHA and DOT frameworks govern anhydrous ammonia handling and liquid fertilizer transport, directly affecting storage infrastructure investments and carrier certification requirements. Stakeholders must monitor evolving state-level 4R nutrient stewardship mandates and their integration with carbon intensity scoring for agricultural inputs.
Market Dynamics
Reduced atmospheric sulfur deposition across North American agricultural zones has triggered a structural dependency on applied sulfur inputs, repositioning ammonium thiosulfate from specialty additive to core nutrient program component in corn and soybean operations.
Growth Catalysts
- Clean Water Act phosphorus mandates:EPA pressure on states to reduce nitrogen runoff elevates sulfur-balanced fertilization as a compliance pathway, expanding ATS co-application with urea-ammonium nitrate.
- Fertigation infrastructure expansion:Pivot irrigation retrofits across the Plains states enable liquid ATS delivery during critical reproductive growth stages, improving sulfur use efficiency.
- Corn Belt soil sulfur deficits:Illinois, Iowa, and Indiana soils exhibit intensified sulfur deficiency, concentrating grower demand for mid-season sidedress applications.
Market Restraints
- Anhydrous ammonia price volatility:ATS production economics hinge on ammonia feedstock costs, exposing margins to natural gas price swings and fertilizer commodity cycles.
- Limited granular production capacity:Liquid formulation dominance constrains dry-blend market access where equipment incompatibility blocks liquid handling adoption.
- Elemental sulfur substitution:Low-cost elemental sulfur products compete in fall application windows, pressuring ATS volume in price-sensitive wheat geographies.
Strategic Opportunities
- Carbon intensity scoring integration:State-level 4R nutrient stewardship programs in Minnesota and Wisconsin create premium positioning for precision sulfur timing protocols that reduce environmental loss.
- Controlled-release coating convergence:Polymer-sulfur coating technology paired with ATS enables synchronized nitrogen-sulfur release, opening specialty crop and vegetable market expansion.
- Direct cooperative contracting:Volume agreements with large Midwestern grain cooperatives bypass dealer markup structures, capturing margin and securing offtake commitments.
Industry Challenges
- Liquid fertilizer handling certification:OSHA and DOT carrier requirements create driver scarcity and training bottlenecks for last-mile delivery scaling.
- Storage infrastructure capex:Corrosion-resistant tank installations and secondary containment systems demand capital commitments that strain regional distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Thiosulfate Fertilizer Market |
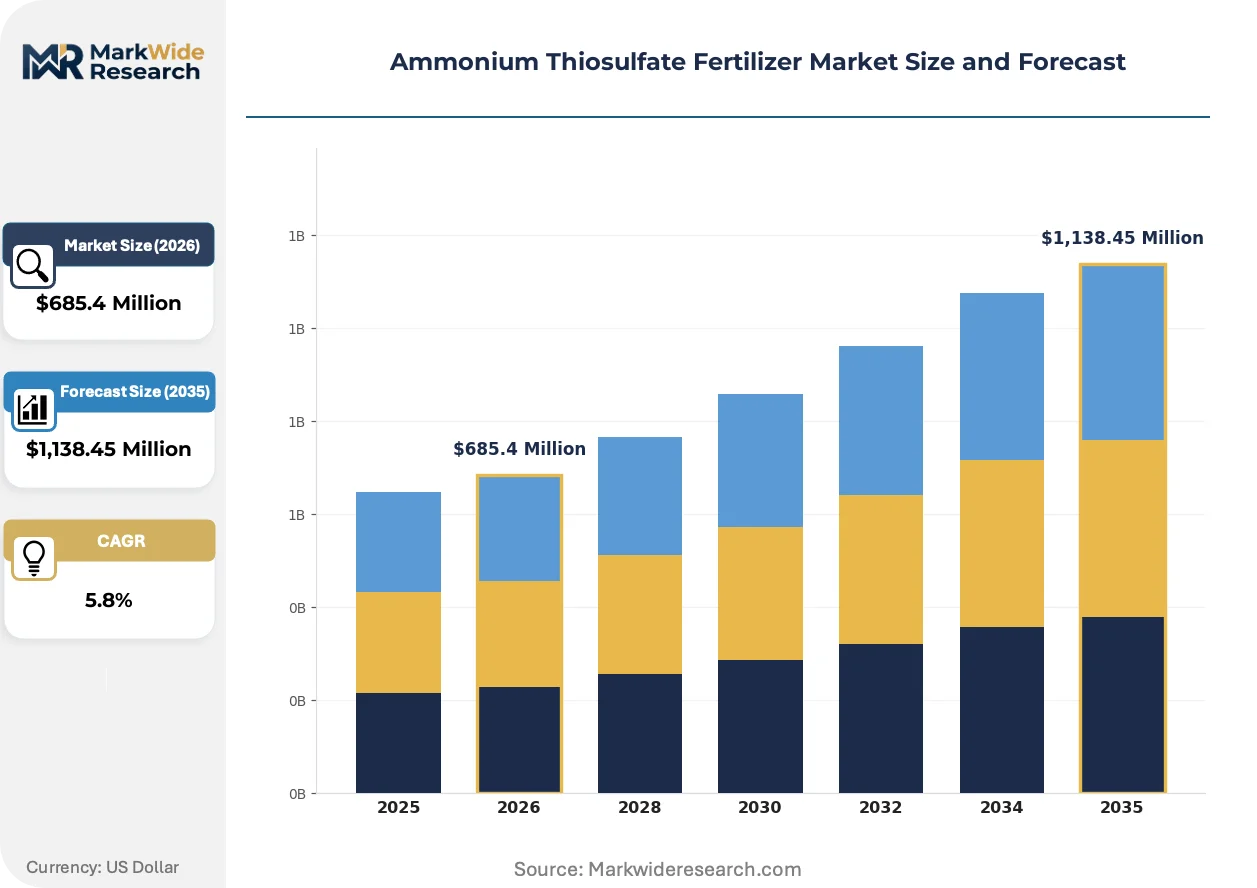
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Horticulture, Turf Management, Specialty Crops Formulation Type: Liquid, Granular, Powder, Suspension Distribution Channel: Direct Sales, Wholesalers, Retail, E-commerce End User: Farmers, Agricultural Cooperatives, Fertilizer Dealers, Research Institutions |
| Companies Covered | Tessenderlo Kerley, Inc., Koch Fertilizer, LLC, Nutrien Ltd., TIB Chemicals AG, Kugler Company, Martin Midstream Partners L.P., Esseco UK, Poole Chem, Mears Fertilizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Thiosulfate Fertilizer Market Trends and Innovations
Digital agronomy platforms are compressing the sulfur recommendation cycle from annual soil tests to in-season tissue monitoring, enabling real-time ATS rate adjustments that align with crop uptake curves.
Variable-rate application technology paired with prescription sulfur algorithms is rendering obsolete flat-rate broadcasting methods that ignore within-field variability. Large Nebraska and Kansas operations adopt sensor-guided sidedress equipment at accelerating pace. The shift compresses per-acre sulfur waste while elevating ATS volume concentration in high-response zones.
EPA's evolving nutrient reduction strategy under the Clean Water Act pressures states to adopt numeric water quality criteria for nitrogen and phosphorus. Agricultural retailers respond by bundling ATS with enhanced efficiency nitrogen products to demonstrate stewardship compliance. The Corn Belt states face the steepest compliance timelines, accelerating technical service investment by distributors.
Volume contracting between growers and fertilizer cooperatives is displacing spot purchasing through independent dealers. Large Iowa and Illinois grain handlers consolidate nutrient procurement under single-supplier agreements that lock in ATS volumes across multi-year terms. The concentration shifts pricing power toward cooperatives with terminal access and integrated logistics networks.
Ammonium Thiosulfate Fertilizer Market Segmentation
Segmentation in ammonium thiosulfate reveals how sulfur delivery modes and procurement pathways diverge across farm scales and crop systems. Understanding these splits exposes where formulation investments concentrate and which channels capture margin.
Application:
Mature commodity cropping dominates volume, while emerging specialty protocols command premium positioning.
- Agriculture:Corn and soybean operations across Illinois, Iowa, and Indiana drive bulk consumption through sidedress programs timed to reproductive growth stages. EPA Clean Water Act phosphorus mandates elevate sulfur-balanced fertilization as a compliance pathway, expanding ATS co-application with urea-ammonium nitrate in these watersheds.
- Specialty Crops:Precision sulfur timing protocols for vegetables and permanent crops enable premium pricing through tissue-monitoring integration. California Central Valley almond and pistachio growers adopt fertigation-compatible liquid ATS to address mid-season sulfur deficits during nut fill.
- Horticulture:Nursery and greenhouse operations require micronutrient-compatible formulations.
- Turf Management:Golf course and sports field maintenance programs emphasize rapid green-up response.
Agriculture handles the majority of throughput; Specialty Crops is the fastest mover on share.
Formulation Type:
Cost tiers separate high-volume liquid infrastructure from capital-light dry alternatives.
- Liquid:Dominant formulation containing 12% nitrogen and 26% sulfur by weight, manufactured via ammonia-sulfur dioxide reaction in aqueous solution. Compatibility with pivot irrigation retrofits across Nebraska and Kansas Plains enables delivery during critical reproductive stages, improving sulfur use efficiency.
- Granular:Dry-blend compatible form occupies equipment-limited operations where liquid handling infrastructure is absent.
- Powder:Niche applications in research and precision blending operations.
- Suspension:Intermediate viscosity products for specific application equipment requirements.
Liquid commands absolute volume leadership; Suspension is climbing the fastest as equipment manufacturers broaden compatibility specifications.
Distribution Channel:
Customer type determines whether procurement flows through integrated networks or fragmented intermediaries.
- Direct Sales:Volume contracts with large Midwestern grain cooperatives displace spot purchasing, locking in multi-year ATS commitments. Iowa and Illinois grain handlers consolidate nutrient procurement under single-supplier agreements that shift pricing power toward cooperatives with terminal access.
- Wholesalers:Regional distributors maintain inventory positions for dealer networks lacking storage infrastructure.
- Retail:Independent agronomy outlets serve smaller operations with bundled prescription programs.
- E-commerce:Emerging channel for specialty crop inputs and technical documentation access.
Direct Sales handles the majority of throughput; E-commerce is gaining share fastest among specialty crop segments.
End User:
Scale concentration divides integrated procurement from fragmented purchasing.
- Farmers:Large operations above 2,000 acres adopt variable-rate application technology and sensor-guided sidedress equipment, compressing per-acre sulfur waste while elevating ATS concentration in high-response zones.
- Agricultural Cooperatives:Consolidated buyers with integrated logistics networks bypass traditional dealer markups.
- Fertilizer Dealers:Regional distributors face margin pressure from direct cooperative contracting.
- Research Institutions:University extension programs and USDA stations evaluate nitrification inhibition protocols and sulfur response curves.
Farmers handle the majority of throughput; Agricultural Cooperatives is expanding most quickly as consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Koch Industries' integrated pipeline terminals across the Plains states anchor North American ammonium thiosulfate distribution, enabling cost-competitive liquid fertilizer delivery to Iowa and Illinois corn operations.
United States
EPA Clean Water Act phosphorus mandates drive sulfur-balanced fertilization adoption across the Corn Belt. The agency pressures Illinois, Iowa, and Indiana to adopt numeric nitrogen reduction targets. Terminal infrastructure at Sioux City and St. Louis concentrates liquid ATS blending capacity for sidedress programs.
Canada
Prairie canola growers expand ATS use for sulfur-responsive oilseed production. Health Canada's PMRA evaluates nitrification inhibitor claims under fertilizer registration frameworks. Alberta's Red Deer corridor hosts regional distribution hubs serving Saskatchewan and Manitoba farm cooperatives.
Brazil
Cerrado soybean expansion intensifies applied sulfur demand as native soil reserves deplete. ANVISA regulates fertilizer quality standards under national agricultural input legislation. Mato Grosso grain terminals integrate liquid handling infrastructure for precision nutrient delivery.
Germany
EU Green Deal nitrogen reduction targets elevate enhanced-efficiency fertilizer positioning. ECHA oversees chemical safety classifications affecting storage and transport protocols. The Rhine River chemical corridor maintains sulfur derivative production clusters near Ludwigshafen.
Australia
Wheat belt sulfur deficiency triggers ATS adoption in Western Australia and South Australia. The country's national agricultural chemical regulator administers fertilizer efficacy and environmental risk assessments. Perth-based distribution networks serve broadacre dryland cropping operations.
Ammonium Thiosulfate Fertilizer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sulfur chemistry and corrosion inhibitor formulation. The market structures around three tiers: integrated fertilizer majors with terminal networks, regional liquid specialists with technical service capabilities, and commodity blenders competing on price. Dominant competitive moves include direct cooperative contracting that bypasses dealer markups and proprietary additive development that extends storage compatibility.
Within the integrated platform tier, Koch Fertilizer and Nutrien exemplify terminal-network dominance through captive pipeline and retail agronomy infrastructure. Tessenderlo Kerley occupies the specialist position, representing technical differentiation through liquid sulfur chemistry expertise. These three entities anchor competitive dynamics across North American distribution channels.
| Leading Market Players |
|---|
| Tessenderlo Kerley, Inc. |
| Koch Fertilizer, LLC |
| Nutrien Ltd. |
| TIB Chemicals AG |
| Kugler Company |
| Martin Midstream Partners L.P. |
| Esseco UK |
| Poole Chem |
| Mears Fertilizer |
| Others |
Pricing and Supply Chain Analysis
Sioux City terminal infrastructure anchors liquid ammonium thiosulfate blending capacity for the Corn Belt, concentrating supply-side leverage among pipeline-integrated operators who dictate volume-discount tiering to large agricultural cooperatives. This geographic concentration enables feedstock-advantaged majors to compress margins for regional distributors lacking captive ammonia supply.
Pricing Analysis
Volume-discount tiering structures separate contract-based cooperative procurement from spot-market dealer purchases, with pricing stratifying across premium precision-sulfur protocols, standard sidedress programs, and economy fall-application grades. Price differentiation rests on corrosion inhibitor formulation quality and EPA stewardship certification bundling. Pricing pressure stems from elemental sulfur substitution in wheat geographies. Large grain cooperatives above 50,000 acres exhibit lowest price sensitivity; sub-500-acre operations face acute cost compression.
Supply Chain Analysis
Anhydrous ammonia feedstock availability from Gulf Coast petrochemical corridors and Alberta natural gas processing centers anchors production economics for US and Canadian manufacturers. Ammonia, sulfur dioxide, and corrosion inhibitor additives constitute critical input dependencies. Supply chain risk centers on DOT carrier certification bottlenecks constraining last-mile liquid fertilizer delivery. Distribution runs through integrated pipeline terminals to cooperative offtake agreements, bypassing traditional wholesale dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Iowa and Illinois grain cooperatives consolidate nutrient procurement under single-supplier volume agreements, fragmenting dealer influence and shifting margin capture toward terminal-access operators.
For Market Incumbents: Entrench terminal-network dominance through captive pipeline capacity additions at Sioux City and St. Louis hubs, countering elemental sulfur substitution threats with proprietary corrosion inhibitor R&D that extends storage compatibility and locks in cooperative switching costs.
For New Entrants and Emerging Players: Establish a beachhead in specialty crop fertigation segments where precision sulfur timing protocols command premium positioning, leveraging tissue-monitoring integration partnerships with California almond and pistachio operations as the most penetrable white-space target.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative procurement concentration favors scaled terminal operators with integrated logistics networks; watch for EPA numeric nitrogen criteria adoption timelines as the inflection signal for stewardship-compliant product premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Supply | Captive feedstock from Gulf Coast petrochemical corridors insulates margin from natural gas price volatility. |
| Direct Cooperative Contracting | Multi-year volume agreements with Iowa grain handlers displace dealer markups and secure offtake commitments. |
| Corrosion Inhibitor Formulation Investment | Proprietary additive development extends liquid ATS storage compatibility and creates technical switching costs. |
| Precision Sulfur Timing Protocol Development | Tissue-monitoring integration for California specialty crops opens premium pricing tiers above commodity corn applications. |
| Terminal Infrastructure Expansion | Secondary containment and corrosion-resistant tank installations at St. Louis blending facilities capture Corn Belt sidedress demand. |
Research Methodology
Operator-level perspectives from fertilizer plant managers, agricultural cooperative procurement leads, liquid fertilizer distribution channel partners, and EPA regional compliance officers anchored the qualitative base, triangulated against USGS mineral commodity summaries, EPA Clean Water Act enforcement data, USDA NASS crop production statistics, and SEC 10-K filings from listed fertilizer majors. Bottom-up volume modeling across application segments converged with top-down macroeconomic demand drivers.
Scenario-bracketing framed low, baseline, and high-growth pathways across the projection horizon, with segmentation dimensions spanning formulation type, distribution channel, end-user scale tier, and regional watershed compliance status. CAGRs derived from historical volume trajectories adjusted for EPA regulatory timeline acceleration and atmospheric sulfur deposition recovery curves. Corn yield response elasticity to applied sulfur and natural gas price feedthrough coefficients served as industry-specific forecast inputs.
Sensitivities concentrate around EPA numeric nitrogen criteria adoption pace, anhydrous ammonia feedstock cost volatility, and DOT liquid fertilizer carrier certification expansion rates. Cross-checking against USDA agricultural chemical expenditure surveys and state-level 4R nutrient stewardship program enrollment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Global Urea Market
Fertilizers
Vietnam Fertilizers Market