
 India Organic Fertilizer Market | 2026-2036
India Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
India Organic Fertilizer Market Insights
Horticultural practice demand is hardening as commercial fruit and vegetable growers shift from chemical-intensive regimes. Coromandel International dominates the South Indian market through extensive dealer networks and captive composting infrastructure. Indian Farmers Fertiliser Cooperative leverages its cooperative membership base to sustain bulk procurement contracts across Gujarat and Rajasthan. UPL anchors the biological inputs segment through specialized microbial formulation capabilities developed for high-value export crops.
India organic fertilizer encompasses plant and animal-derived nutrient amendments processed through aerobic composting, anaerobic digestion, or microbial fermentation to deliver nitrogen, phosphorus, and potassium with measurable organic carbon content above fifteen percent. These inputs restore soil microbial biomass and improve cation exchange capacity in degraded agricultural soils. Granular formulations lead volume sales due to mechanical spreading compatibility, while liquid biofertilizers represent the fastest-expanding category driven by drip irrigation integration and foliar application adoption. Seaweed extracts command premium positioning in horticultural practices where trace element bioavailability determines produce quality grades.
BIS certification requirements for organic fertilizer labeling and the CEA's nutrient-based subsidy modifications shape product registration pathways and pricing structures for domestic manufacturers. FSSAI organic integrity standards and state-level agricultural department procurement quotas determine market access for branded versus unorganized suppliers. Stakeholders must monitor evolving PLI scheme disbursement timelines and state organic mission budget allocations to align capacity expansion with institutional offtake commitments.
Market Dynamics
The PLI scheme for agrochemical manufacturing is compressing investment timelines for domestic organic fertilizer producers while FSSAI certification mandates force unorganized suppliers toward formal registration pathways.
Growth Catalysts
- Maharashtra's grape belt:Export-oriented horticultural clusters are mandating organic input documentation for EU market access, creating institutional pull for certified products.
- FSSAI organic integrity standards:Food safety certification requirements for farm-level traceability are extending upstream to input suppliers, formalizing procurement channels.
- Anaerobic digestion infrastructure:Compressed biogas plants under the SATAT scheme are generating digestate streams that processors convert to standardized organic fertilizer formulations.
Market Restraints
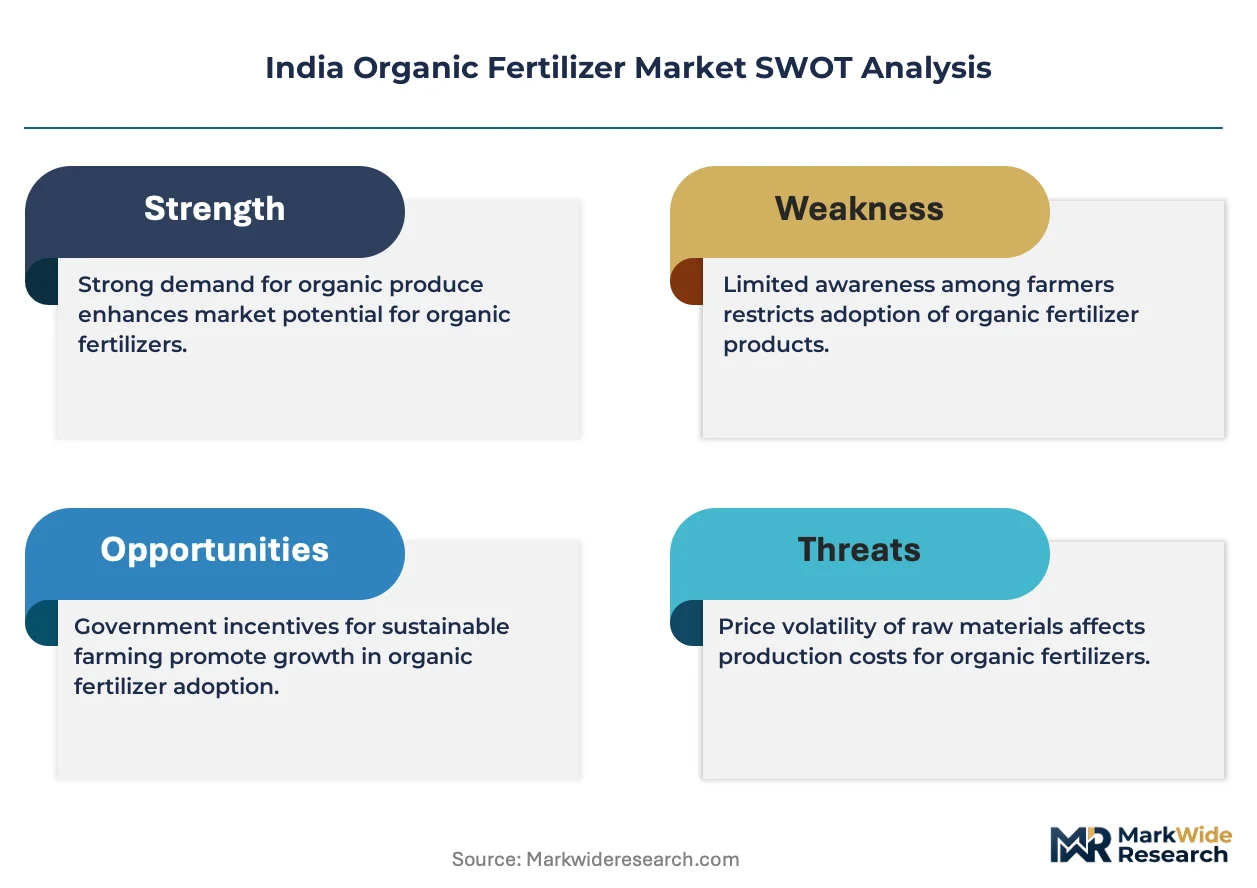
- Input cost volatility:Poultry litter and press mud prices fluctuate with sugarcane crushing cycles and broiler farm economics, compressing processor margins during off-seasons.
- Supply concentration risk:Over half of biomass feedstock availability clusters in Gujarat and Punjab, exposing national distributors to monsoon-dependent logistics disruptions.
- Technical limitation:Variable nutrient density across batch-produced compost limits formulation precision for high-value horticultural clients requiring guaranteed NPK specifications.
Strategic Opportunities
- Northeastern hill states:Organic mission budget allocations in Assam and Meghalaya remain underpenetrated by organized suppliers despite favorable agro-climatic conditions for specialty crop production.
- CEA nutrient-based subsidy modifications:Proposed inclusion of organic fertilizers under modified subsidy structures would restructure price competitiveness against chemical alternatives.
- Drip irrigation convergence:Liquid biofertilizer compatibility with micro-irrigation hardware creates bundled service opportunities with equipment manufacturers penetrating Karnataka's coffee districts.
Industry Challenges
- Microbiologist talent scarcity:Formulation development requires specialized expertise in strain selection and carrier material compatibility that agricultural universities are not producing at sufficient scale.
- BIS certification timelines:Laboratory testing queues for organic carbon verification and heavy metal screening extend product launch cycles by eight to fourteen months.
- Dealer network reconfiguration:Cooperative procurement systems in Gujarat and Rajasthan resist onboarding new suppliers due to entrenched commission structures and credit relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Organic Fertilizer Market |
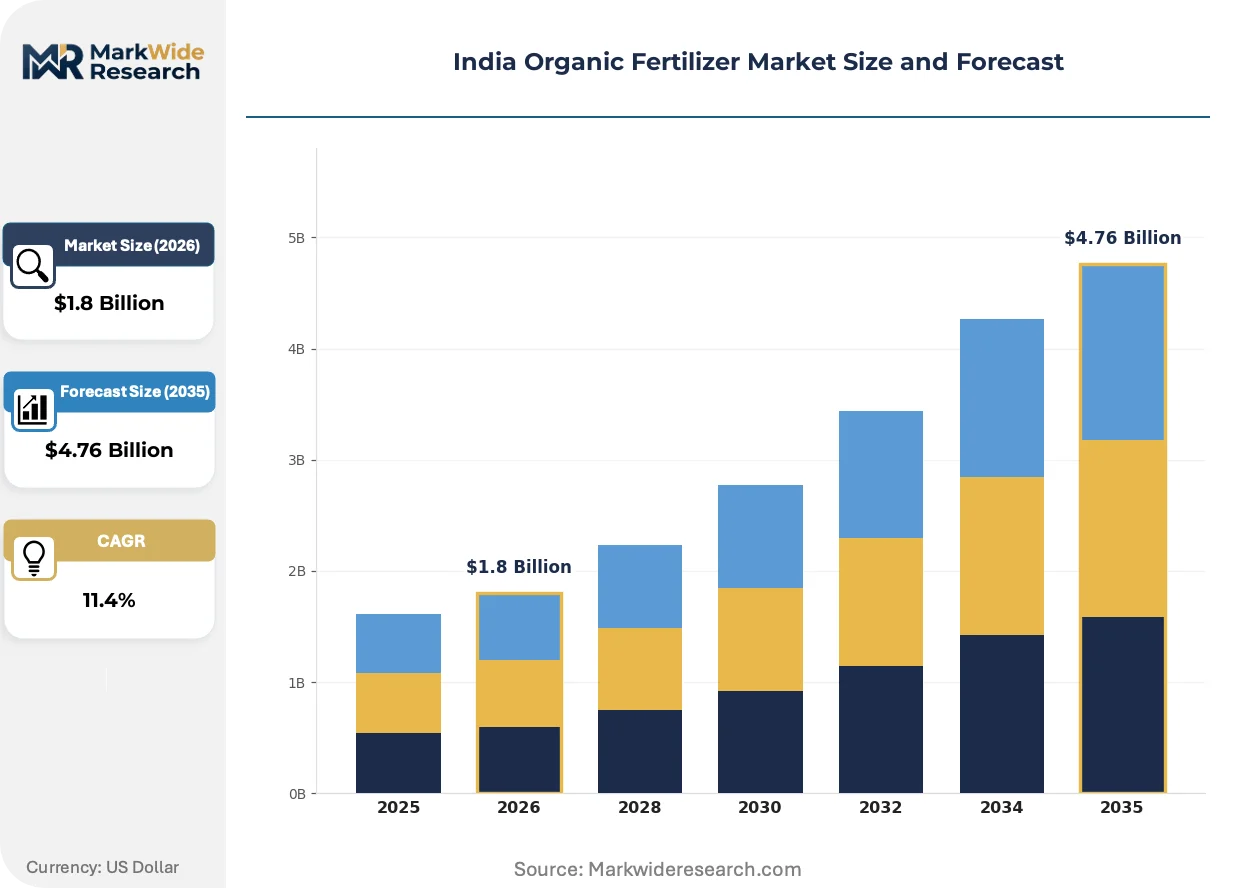
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Green Manure, Biofertilizers, Seaweed Extracts Source: Animal Manure, Plant Residues, Microbial Sources, Seaweeds Form: Granular, Liquid, Powder, Spreader-Ready Application: Agricultural Crops, Gardening, Landscaping, Horticultural Practices |
| Companies Covered | Swaroop Agrochemical Industries, Rashtriya Chemicals and Fertilizers, Coromandel International, Amruth Organic Fertilizers, UPL, Deepak Fertilizers and Petrochemical Corporation, Gujarat Narmada Valley Fertilizers and Chemicals, Ajay Bio-Tech (India), Indian Farmers Fertiliser Cooperative, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Organic Fertilizer Market Trends and Innovations
Microbial fermentation technology is consolidating production economics while regulatory pressure on chemical residue limits accelerates input substitution across export-oriented crop zones.
Consortia-based biofertilizer technology is consolidating competitive positioning among mid-scale manufacturers. Multi-strain formulations combining nitrogen-fixing, phosphate-solubilizing, and potassium-mobilizing microbes reduce application frequency for commercial fruit growers. The technology is consolidating supply relationships as grape and pomegranate producers in Maharashtra's Nashik district shift from single-function products to integrated soil health programs.
BIS certification requirements for organic fertilizer labeling are tightening market access standards. Mandatory disclosure of organic carbon percentage, heavy metal limits, and microbial count specifications is disqualifying unorganized suppliers from institutional procurement channels. State agricultural departments in Karnataka and Andhra Pradesh are now requiring BIS-marked products for subsidy-linked distribution schemes.
Certification-driven preference shifts are restructuring buyer-seller relationships in high-value crop segments. Export-oriented horticultural producers are demanding FSSAI-traceable organic input documentation to satisfy EU retailer audit protocols. This behavior is most visible in Maharashtra's grape belt, where integrated packhouses are consolidating supplier panels to three to four certified manufacturers with captive laboratory testing capabilities.
India Organic Fertilizer Market Segmentation
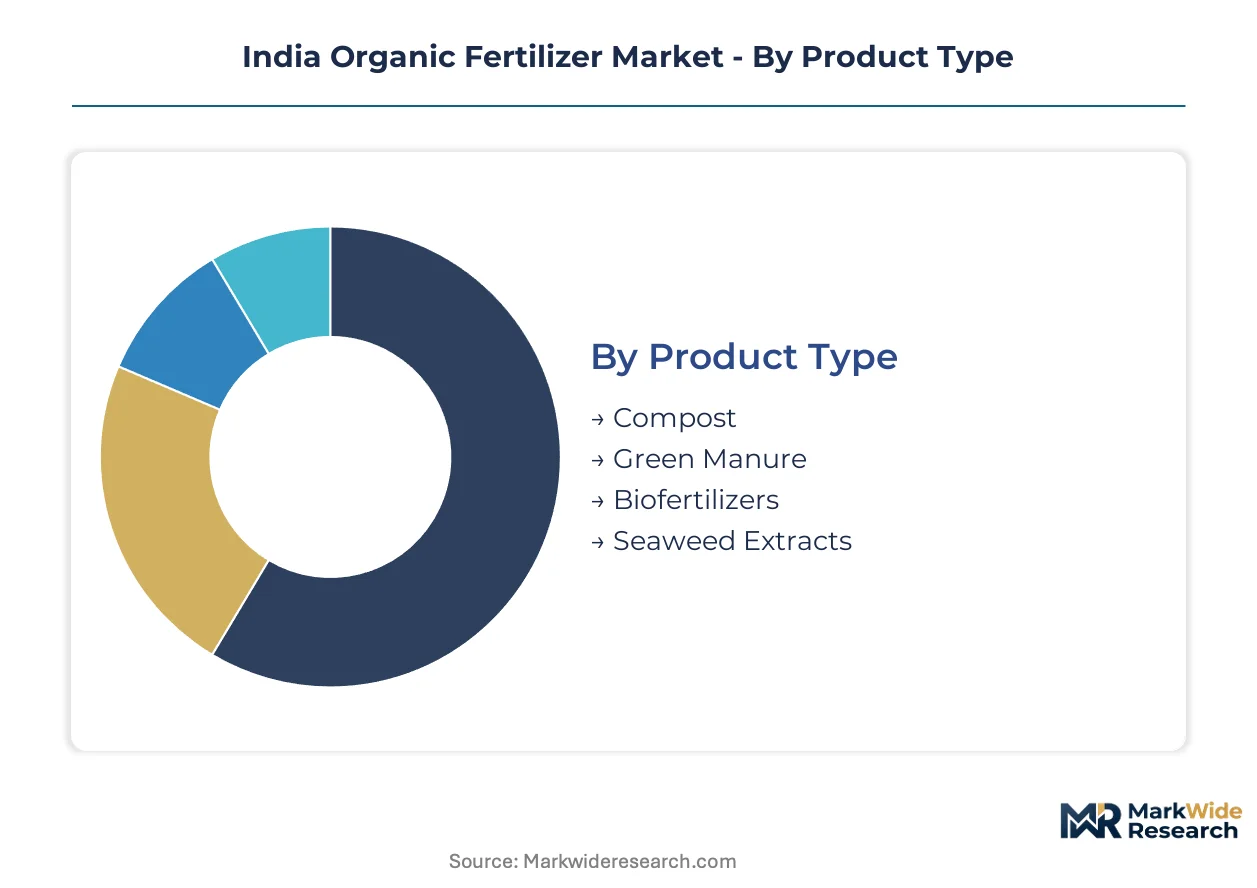
India's organic fertilizer market fragments across four critical axes that determine manufacturing investment, distribution economics, and farmer adoption patterns. Product chemistry dictates processing infrastructure requirements while application context shapes certification and pricing thresholds.
Product Type:
Microbial fermentation intensity and carbon-to-nitrogen processing ratios define the technical differentiation across product categories.
- Compost:Aerobically decomposed organic matter from agricultural residues and animal waste delivers stable humus with organic carbon exceeding 15 percent. Maharashtra's grape belt and Karnataka's coffee districts drive institutional procurement of BIS-certified compost for export crop documentation. Input cost volatility from poultry litter and press mud supply cycles compresses processor margins during off-seasons.
- Biofertilizers:Microbial consortia combining nitrogen-fixing, phosphate-solubilizing, and potassium-mobilizing strains reduce application frequency for commercial fruit growers. Nashik district grape and pomegranate producers are shifting from single-function products to integrated soil health programs, consolidating supply relationships around multi-strain formulations.
- Green Manure:Leguminous biomass incorporation restores nitrogen fixation capacity in degraded soils across Gujarat and Rajasthan cooperative farming systems.
- Seaweed Extracts:Marine-sourced bioactive compounds command premium positioning in horticultural practices where trace element bioavailability determines produce quality grades.
Compost leads on scale; biofertilizers lead on momentum.
Source:
Feedstock geography constrains national distribution reach and exposes supply chains to monsoon-dependent logistics disruptions.
- Animal Manure:Poultry litter and cattle dung supply concentrates in Gujarat and Punjab, creating concentration risk for processors serving distant markets. Broiler farm economics and sugarcane crushing cycles generate price volatility that national distributors must hedge through multi-source contracting.
- Plant Residues:Press mud from sugar mills and crop stubble provide carbon-dense inputs for aerobic composting facilities. CEA nutrient-based subsidy modifications are restructuring procurement economics for plant-residue processors serving state agricultural department quotas.
- Microbial Sources:Strain selection and carrier material compatibility expertise from agricultural universities supports formulation development for specialized biofertilizer manufacturers.
- Seaweeds:Coastal harvesting operations in Tamil Nadu and Gujarat supply marine biomass for premium extract production targeting export-oriented horticulture.
Animal manure dominates volume throughput; microbial sources are climbing the fastest on technology premium capture.
Form:
Mechanical spreading compatibility and irrigation infrastructure integration determine farmer adoption economics across form factors.
- Granular:Compacted pellets enable mechanical broadcasting compatibility with existing farm equipment across Maharashtra's mechanized grape vineyards. BIS certification requirements for particle size uniformity and moisture content are tightening quality standards for institutional procurement channels.
- Liquid:Microbial suspension formulations integrate with drip irrigation hardware, creating bundled service opportunities with equipment manufacturers penetrating Karnataka's coffee districts. FSSAI organic integrity standards for farm-level traceability extend upstream to liquid biofertilizer suppliers.
- Powder:Fine-ground compost serves manual application contexts in smallholder farming systems across northeastern hill states.
- Spreader-Ready:Pre-blended formulations with optimized moisture and particle distribution reduce field preparation labor for commercial operations.
Granular formulations anchor current volume; liquid biofertilizers are gaining share fastest on irrigation convergence.
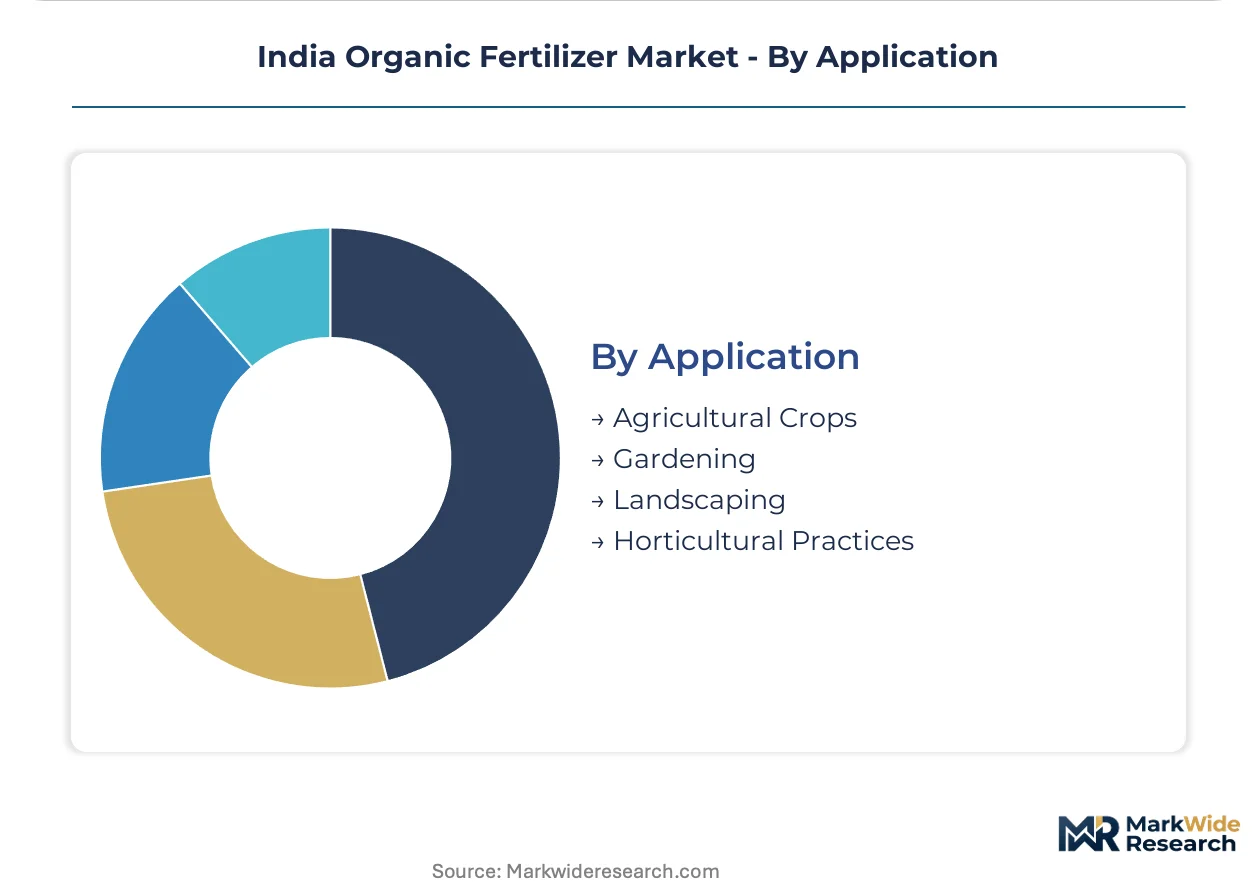
Application:
Certification stringency and price tolerance diverge sharply between subsistence farming and export-oriented commercial operations.
- Horticultural Practices:Export-oriented fruit and vegetable producers mandate FSSAI-traceable organic input documentation to satisfy EU retailer audit protocols. Maharashtra's grape belt integrated packhouses are consolidating supplier panels to three to four certified manufacturers with captive laboratory testing capabilities.
- Agricultural Crops:Food grain and oilseed producers respond to state organic mission budget allocations and procurement quotas that determine market access for branded versus unorganized suppliers.
- Gardening:Urban consumer segments in Bangalore and Pune drive retail channel development for packaged organic fertilizers.
- Landscaping:Municipal and commercial green space maintenance contracts generate institutional demand for bulk compost in metropolitan regions.
Horticultural practices command premium pricing; agricultural crops represent the deepest volume reservoir.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's grape belt anchors national organic fertilizer consumption through export-oriented horticultural clusters demanding certified input documentation for EU market access.
Maharashtra
Nashik district grape and pomegranate producers mandate FSSAI-traceable organic input documentation to satisfy EU retailer audit protocols. The state's agricultural department requires BIS-marked products for subsidy-linked distribution schemes. Integrated packhouses in the grape belt consolidate supplier panels to three to four certified manufacturers with captive laboratory testing capabilities.
Gujarat
Cooperative farming systems across Gujarat drive bulk procurement contracts for compost and green manure through entrenched commission structures. The state's organic mission budget allocations determine market access for branded versus unorganized suppliers. Poultry litter supply concentrates in Gujarat's broiler farm belts, creating feedstock cost volatility that processors must hedge through multi-source contracting.
Karnataka
Coffee-growing districts in Karnataka generate institutional demand for BIS-certified compost and liquid biofertilizers compatible with drip irrigation hardware. State agricultural departments mandate BIS-marked products for subsidy-linked distribution schemes. Equipment manufacturers penetrating Karnataka's coffee districts create bundled service opportunities with liquid biofertilizer suppliers.
Punjab
Cattle dung supply concentrates in Punjab's dairy belts, exposing national distributors to monsoon-dependent logistics disruptions when serving distant markets. The CEA's nutrient-based subsidy modifications restructure procurement economics for plant-residue processors serving state agricultural department quotas. Biomass feedstock availability in Punjab clusters with sugarcane crushing cycles, generating price volatility for press mud processors.
Assam
Organic mission budget allocations in Assam remain underpenetrated by organized suppliers despite favorable agro-climatic conditions for specialty crop production. The state's northeastern hill states generate demand for powder-form compost serving manual application contexts in smallholder farming systems. FSSAI organic integrity standards extend upstream to input suppliers formalizing procurement channels in previously informal markets.
India Organic Fertilizer Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic manufacturers align facility additions with PLI scheme disbursement timelines and state organic mission budget allocations. The vendor base clusters around three strategic archetypes: cooperative-backed incumbents with entrenched procurement networks, agrochemical conglomerates diversifying into biological inputs, and specialized microbial formulation developers. M&A activity and backward integration into captive composting infrastructure represent the dominant competitive moves reshaping supply relationships.
Among cooperative-backed incumbents, Indian Farmers Fertiliser Cooperative and Gujarat Narmada Valley Fertilizers and Chemicals occupy positions anchored by bulk procurement relationships across western India. Coromandel International exemplifies the agrochemical conglomerate archetype with extensive dealer networks and captive composting infrastructure serving southern markets. UPL represents the specialized microbial formulation segment through biological input capabilities developed for high-value export crops.
| Leading Market Players |
|---|
| Swaroop Agrochemical Industries |
| Rashtriya Chemicals and Fertilizers |
| Coromandel International |
| Amruth Organic Fertilizers |
| UPL |
| Deepak Fertilizers and Petrochemical Corporation |
| Gujarat Narmada Valley Fertilizers and Chemicals |
| Ajay Bio-Tech (India) |
| Indian Farmers Fertiliser Cooperative |
| Others |
Pricing and Supply Chain Analysis
EU retailer audit protocols mandating FSSAI-traceable organic input documentation are compressing procurement options for Maharashtra's grape belt packhouses, forcing supply consolidation around certified manufacturers with captive laboratory testing capabilities and amplifying price premiums for BIS-marked formulations.
Pricing Analysis
Input-cost pass-through from poultry litter and press mud volatility dominates pricing dynamics for compost processors serving institutional channels. Three-tier pricing structure across premium certified, standard BIS-marked, and economy unbranded levels separates export-oriented horticultural producers from state-subsidy recipients and smallholder segments. Cost compression in the economy tier is intensifying because monsoon-dependent logistics disruptions expose distributors to feedstock scarcity in distant markets. State agricultural department procurement quotas render smallholder cooperatives most price-sensitive, while integrated packhouses absorb premiums for guaranteed NPK specifications.
Supply Chain Analysis
Dual-sourcing requirements from national distributors are mandating multi-supplier qualification across Gujarat, Punjab, and Maharashtra feedstock belts to hedge monsoon logistics exposure. Raw material dependencies center on poultry litter from broiler farm belts, press mud from sugarcane crushing cycles, and cattle dung from dairy clusters. Single-source vulnerability concentrates in Gujarat's biomass availability, where over half of national poultry litter supply clusters. Distribution runs through cooperative procurement systems in western India and dealer networks anchored by agrochemical conglomerates in southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories for domestic manufacturers rest on PLI scheme disbursement timelines compressing capital recovery periods, while certification-driven buyer consolidation in export horticulture shifts volume toward premium-tier suppliers with captive testing infrastructure.
For Market Incumbents: Hedge feedstock cost volatility through multi-source contracting across Gujarat, Punjab, and Rajasthan poultry belts while deepening backward integration into captive composting infrastructure near Maharashtra's grape districts. Defend dealer network positions against cooperative commission structure resistance by embedding technical agronomists within state agricultural department subsidy-linked distribution schemes. Prioritize BIS certification investment to disqualify unorganized competitors from institutional procurement channels. For New Entrants and Emerging Players: Begin with underpenetrated northeastern hill states where Assam and Meghalaya organic mission budget allocations lack organized supplier presence despite favorable specialty crop conditions. Target liquid biofertilizer formulation for Karnataka's coffee district drip irrigation convergence, bundling with equipment manufacturers penetrating micro-irrigation hardware markets. Anchor go-to-market strategy through state agricultural department procurement quota alignment rather than cooperative channel displacement. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized microbial formulation developers possessing strain selection expertise and carrier material compatibility capabilities that agricultural universities are not producing at sufficient scale. Five-to-ten-year viability favors manufacturers integrating anaerobic digestion infrastructure with SATAT scheme compressed biogas plants to secure standardized digestate streams. Monitor CEA nutrient-based subsidy modification announcements as inflection indicators for organic fertilizer price competitiveness restructuring against chemical alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Composting | Coromandel International's dealer network consolidation secures supply certainty for BIS-certified export crop documentation. |
| Multi-Strain Microbial Formulation Development | UPL's biological input capabilities address Nashik district grape producer demand for integrated soil health programs. |
| State Organic Mission Procurement Alignment | Indian Farmers Fertiliser Cooperative leverages Gujarat and Rajasthan cooperative membership for bulk contract sustainability. |
| Liquid Biofertilizer Irrigation Convergence | Karnataka coffee district equipment manufacturers create bundled service channels for foliar application adoption. |
| BIS Certification Laboratory Investment | Integrated packhouse supplier panel consolidation mandates captive heavy metal screening and organic carbon verification capabilities. |
Research Methodology
Direct dialogue with organic fertilizer plant managers, state agricultural department procurement officers, cooperative society secretaries, and export-oriented horticultural packhouse agronomists grounded qualitative insights, cross-referenced with BIS certification registries, FSSAI organic integrity standards documentation, CEA nutrient-based subsidy modification filings, and state organic mission budget allocation records, with bottom-up manufacturer capacity assessments triangulated against top-down demand modeling from crop acreage and input intensity trends.
Bottom-up volume aggregation across compost, biofertilizer, green manure, and seaweed extract product types, segmented by granular, liquid, powder, and spreader-ready forms, and further disaggregated by horticultural practices, agricultural crops, gardening, and landscaping applications, generated baseline demand estimates across the projection horizon, with CAGRs derived from trend extrapolation of PLI scheme disbursement timelines and state procurement quota expansion trajectories, incorporating drip irrigation penetration rates and EU export certification velocity as industry-specific forecast inputs.
Caveats apply where monsoon-dependent logistics disruptions, BIS certification timeline extensions, or PLI scheme disbursement delays could materially shift the outlook for domestic manufacturer capacity expansion alignment with institutional offtake commitments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Fertilizers Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Global Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Global Green Fertilizers Market