
 Brazil Organic Fertilizer Market | 2026-2036
Brazil Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Organic Fertilizer Market Insights
Specialty-grade organic fertilizer certification is unwinding price resistance among export-oriented growers. Yara International leverages its Brazilian distribution network to push premium formulations into the southern soybean belt. Grupo Fertipar anchors regional supply through backward integration into poultry litter processing. Novozymes differentiates via enzymatic digestion platforms that accelerate nutrient release timelines.
Organic fertilizer comprises plant or animal-derived matter processed to deliver nitrogen, phosphorus, and potassium through microbial mineralization rather than direct chemical solubility. These inputs rebuild soil organic carbon while reducing salinity damage common to synthetic salt-based products. Compost dominates volume flows due to mature collection infrastructure around São Paulo's urban waste streams, while liquid fertilizer captures faster growth from fertigation expansion in irrigated fruit orchards. The horticultural application segment commands margin premiums as greenhouse operators near urban centers pay for precise nutrient dosing and residue-free certification.
ANVISA governs maximum contaminant thresholds for heavy metals and pathogens in commercial organic inputs, while the Ministry of Agriculture's MAPA organic certification program shapes market access for export-bound producers. State-level environmental agencies in Paraná and Rio Grande do Sul enforce buffer zone requirements that effectively mandate organic transition near water bodies. Stakeholders must track how pending updates to Brazil's National Fertilizer Policy reshape import dependencies for organic base materials.
Market Dynamics
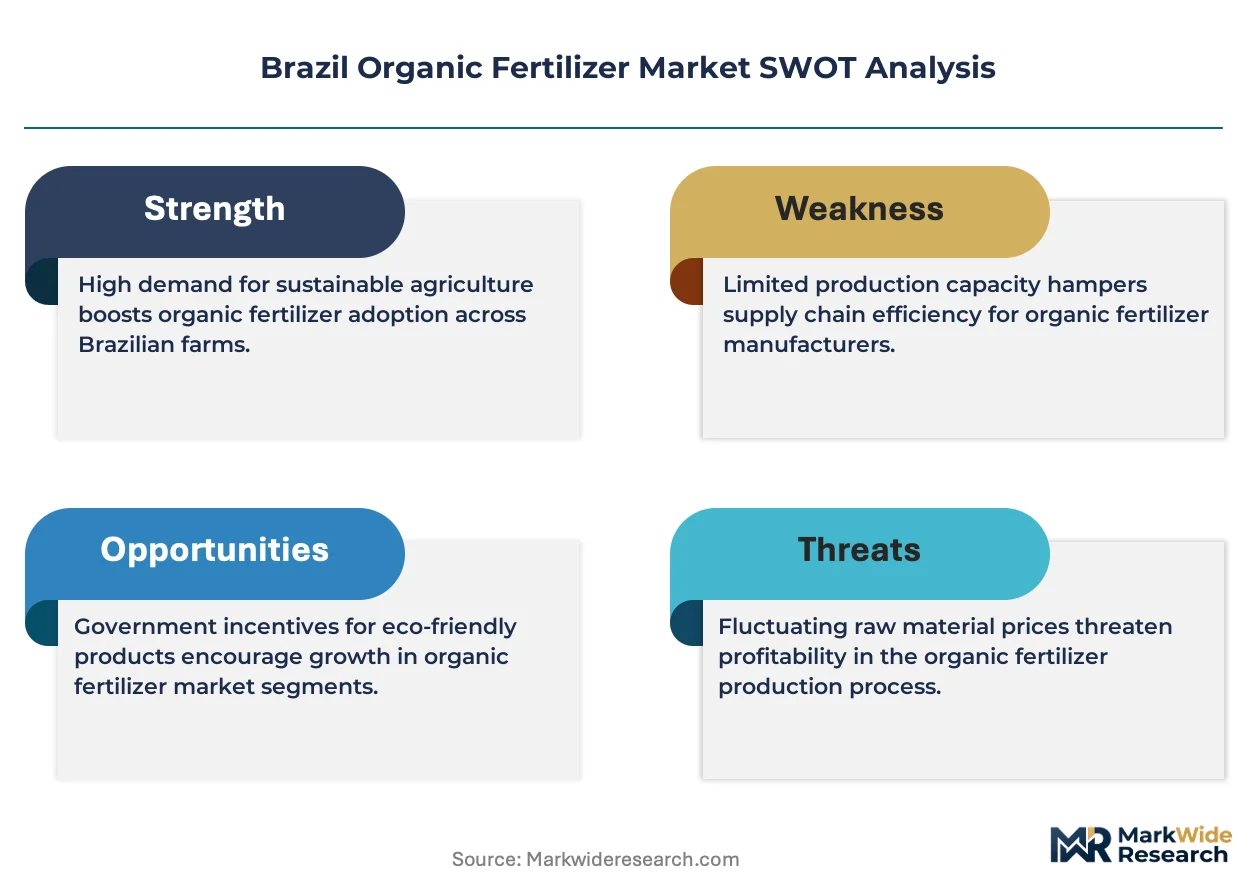
ANVISA's tightening contaminant thresholds and MAPA's organic certification mandates are forcing producers to reconfigure processing infrastructure, while the ABC+ Plan's runoff limits accelerate grower migration from synthetic salts. This regulatory compression collides with EU deforestation compliance requirements to create simultaneous demand pull and supply friction.
Growth Catalysts
- ABC+ Plan enforcement:Synthetic fertilizer runoff limits in Mato Grosso soybean belts are compelling large-scale no-till operations to certify organic alternatives for watershed buffer compliance.
- EU Deforestation Regulation:Export-bound Cerrado corridor growers require certified organic inputs to maintain access to European commodity buyers under traceability mandates.
- Compost infrastructure maturity:São Paulo's urban waste collection networks now supply consistent feedstock volumes for commercial-scale organic fertilizer production.
Market Restraints
- Poultry litter supply concentration:Regional dependence on Paraná and Rio Grande do Sul integrators creates input volatility when avian disease cycles disrupt litter availability.
- Heavy metal threshold compliance:ANVISA's maximum allowable arsenic and cadmium levels in commercial organic inputs force costly preprocessing upgrades at composting facilities.
- Synthetic fertilizer price anchoring:Urea and MAP pricing benchmarks in the Cerrado corridor limit organic premium capture during commodity downturns.
Strategic Opportunities
- Greenhouse horticulture expansion:Urban-proximate protected agriculture near Belo Horizonte and Curitiba demands residue-free certification that organic liquid formulations can command at margin premiums.
- Fertigation system retrofitting:Irrigated fruit orchards in the São Francisco Valley present conversion potential as drip infrastructure spreads beyond traditional synthetic dependency.
- State-level water body mandates:Paraná's enforced organic transition zones near reservoirs create captive demand clusters with regulatory certainty.
Industry Challenges
- Microbial inoculant formulation expertise:Shortage of technicians capable of stabilizing nitrogen-fixing consortia in solid organic matrices limits product consistency at scale.
- MAPA certification timeline compression:Organic input approval queues extending eighteen to twenty-four months delay market entry for novel composting process innovations.
- Legacy synthetic distributor conversion:Established agrochemical retail networks resist retraining sales staff on microbial mineralization timelines versus immediate solubility claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Organic Fertilizer Market |
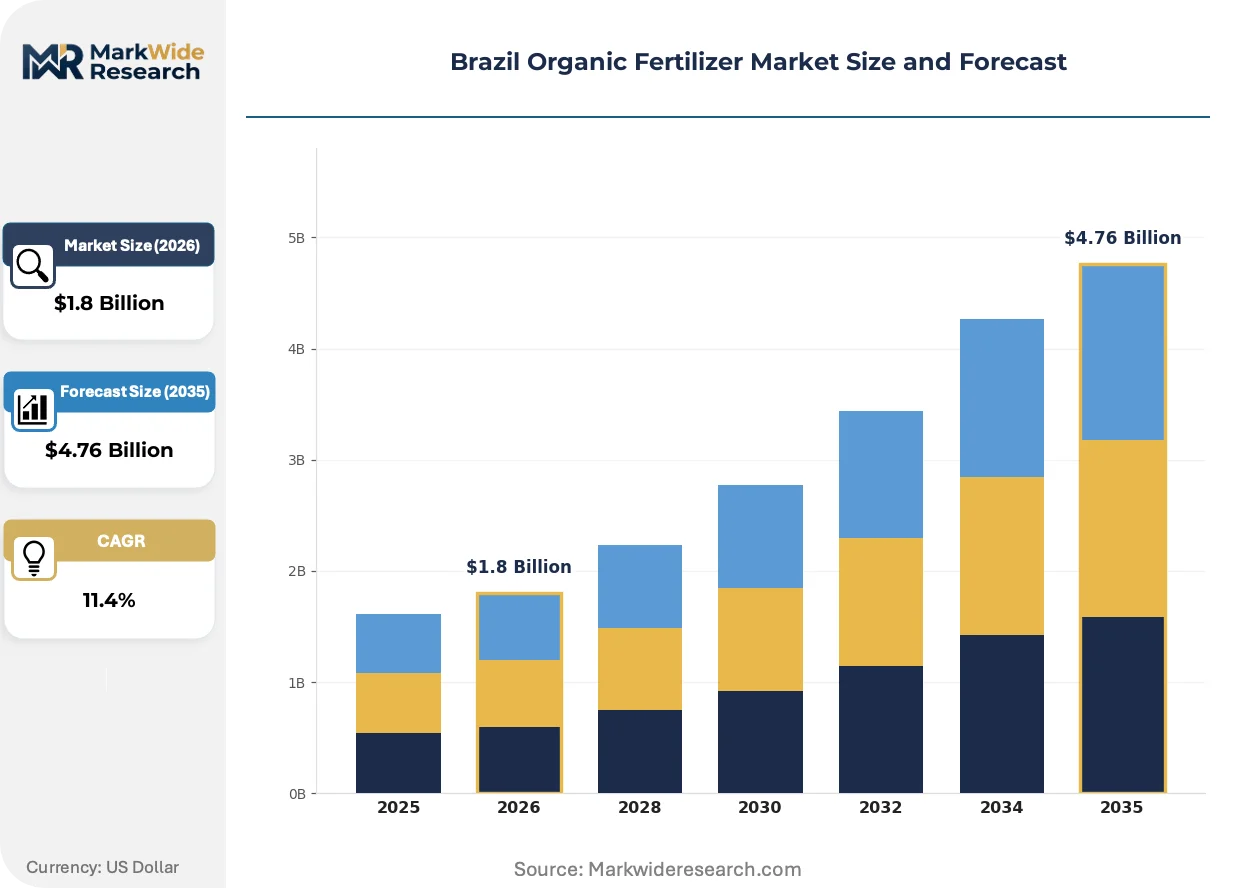
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Liquid Fertilizer, Manure, Bone Meal Application: Agronomic, Horticultural, Landscaping, Turf Management End User: Farmers, Nurseries, Landscaping Companies, Home Gardeners Distribution Channel: Retail Stores, Online Sales, Direct Sales, Wholesalers |
| Companies Covered | Yara International, Mosaic, Grupo Fertipar, Heringer, Ave Ferti, Agrivalle, Novozymes, ICL Group, Nortox, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Organic Fertilizer Market Trends and Innovations
Enzymatic digestion platforms and precision fermentation are compressing nutrient release timelines while regulatory pressure on synthetic runoff intensifies. These forces are fragmenting the competitive landscape between volume commodity compost and premium certified formulations.
Enzymatic pre-digestion of poultry litter and agricultural residues is bifurcating the market into rapid-release liquid concentrates versus slow-mineralization solid composts. Large-scale soybean operations in Mato Grosso are adopting enzymatic platforms to match synthetic fertilizer application windows. This technology is compressing the historical performance gap that kept organic adoption confined to horticultural margins.
MAPA's pending updates to the National Fertilizer Policy are reshaping import dependencies for organic base materials like bone meal and kelp extracts. Domestic processors face stranded asset risk if offshore sourcing restrictions tighten. The southern soybean belt is responding by accelerating backward integration into captive poultry litter supply.
Certification-driven procurement now dominates export-oriented buying committees, displacing price-per-unit-nutrient as the primary selection criterion. Greenhouse operators near São Paulo and Brasília are unbundling input sourcing from traditional agrochemical distributors to secure direct MAPA-certified supply relationships. This behavioral shift is most visible in the horticultural segment where residue-free credentials command shelf-space access with European retail chains.
Brazil Organic Fertilizer Market Segmentation
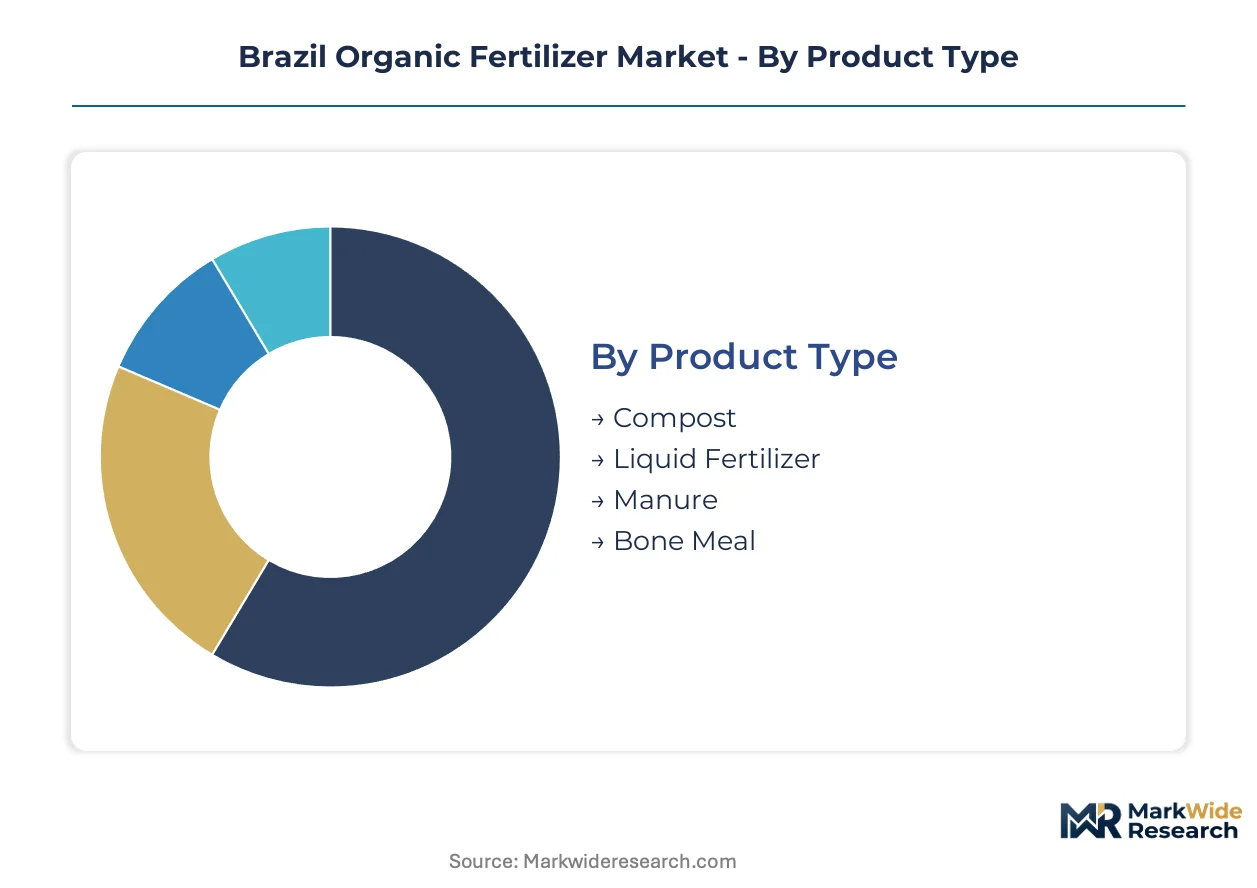
Organic fertilizer segmentation in Brazil reflects divergent pressure points from synthetic substitution, regulatory compliance, and infrastructure maturity. Understanding which segments face the most acute substitute threat clarifies where pricing power erodes fastest and where certification premiums hold firm.
Product Type:
Substitution pressure from synthetic fertilizers varies sharply by physical form and nutrient release kinetics, with slow-mineralization solids facing the steepest price anchoring from urea and MAP benchmarks.
- Compost:Decomposed organic matter from municipal waste streams and agricultural residues delivers nitrogen through microbial mineralization over extended timelines. São Paulo's urban collection networks supply consistent feedstock volumes, though ANVISA's heavy metal thresholds force costly preprocessing upgrades that compress margins against synthetic alternatives.
- Liquid Fertilizer:Enzymatically digested concentrates and fermented extracts enable precise fertigation dosing with accelerated nutrient availability. Irrigated fruit orchards in the São Francisco Valley and greenhouse operations near Belo Horizonte absorb expanding volumes as drip infrastructure spreads beyond traditional synthetic dependency.
- Manure:Poultry litter dominates regional supply from Paraná and Rio Grande do Sul integrators, creating input volatility when avian disease cycles disrupt availability.
- Bone Meal:Animal-derived phosphorus source faces import dependency risks under MAPA's pending National Fertilizer Policy updates.
Compost anchors the volume base while liquid fertilizer gains share at the steepest rate.
Application:
Margin structure across application segments tracks the distance from export compliance requirements and residue-free certification premiums.
- Agronomic:Large-scale no-till soybean and corn operations in Mato Grosso and the Cerrado corridor drive tonnage demand, where ABC+ Plan runoff limits and EU Deforestation Regulation traceability mandates compel certified organic transition. Price resistance persists during commodity downturns as urea benchmarks anchor grower expectations.
- Horticultural:Protected agriculture near urban centers commands the steepest premiums for MAPA-certified, residue-free inputs that secure shelf-space access with European retail chains. Greenhouse operators unbundle sourcing from traditional agrochemical distributors to secure direct supply relationships.
- Landscaping:Municipal and commercial turf maintenance generates steady demand with lower certification stringency.
- Turf Management:Golf courses and sports facilities prioritize rapid greening response over organic credentials, limiting penetration.
Agronomic applications absorb the majority of volume flows while horticultural commands the widest margin premiums.
End User:
Procurement sophistication and certification requirements fragment the customer base across scale and export orientation.
- Farmers:Export-bound growers in Mato Grosso and the Cerrado corridor dominate commercial demand, with buying committees now prioritizing MAPA certification and EU compliance documentation over price-per-unit-nutrient metrics. Legacy synthetic distributor relationships create friction in sales staff retraining on microbial mineralization timelines.
- Nurseries:Ornamental and native plant propagation operations near Curitiba and São Paulo require consistent, pathogen-free substrates.
- Landscaping Companies:Commercial maintenance contractors prioritize cost predictability and application convenience over organic credentials.
- Home Gardeners:Urban consumer segment remains price-sensitive and supply-constrained through retail channel fragmentation.
Farmers anchor procurement volume while nurseries expand most quickly on urban greening mandates.
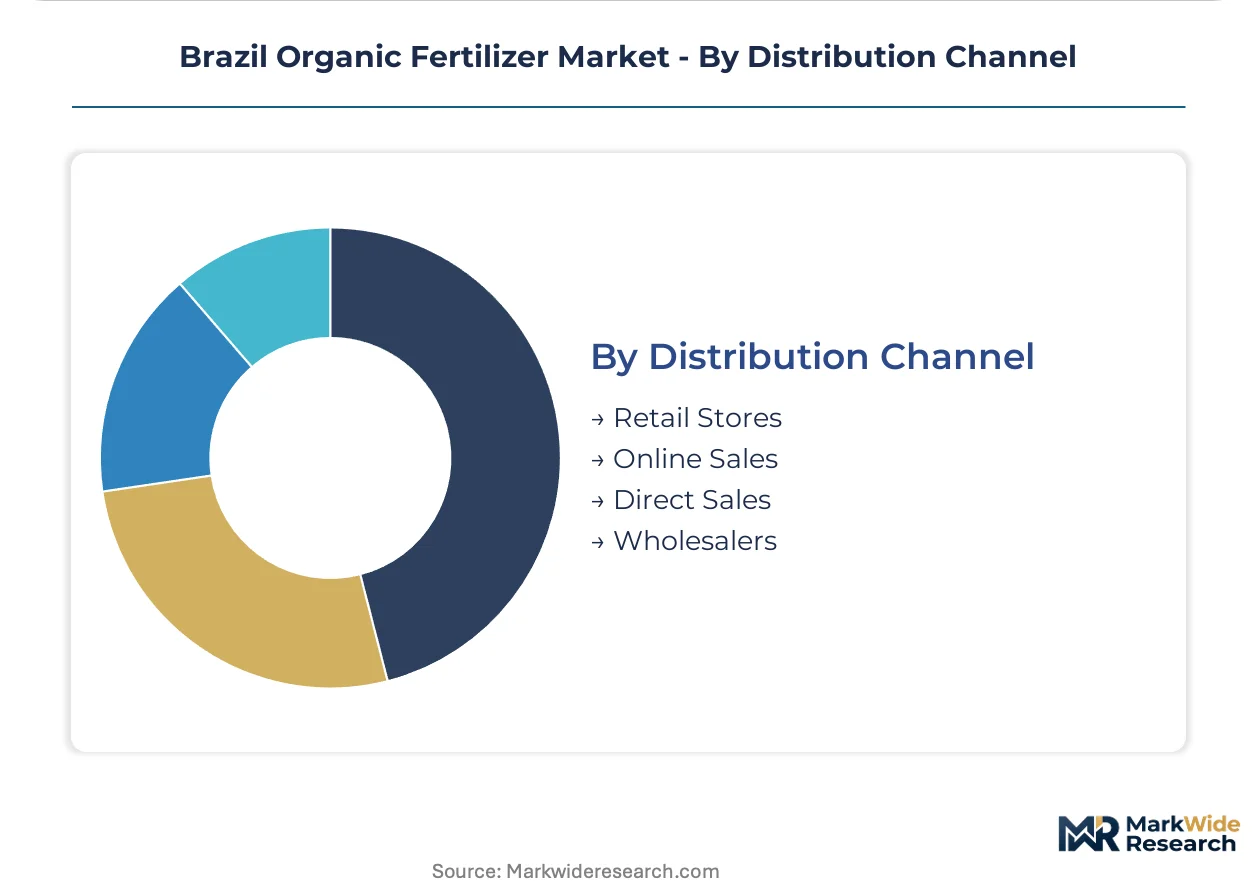
Distribution Channel:
Channel configuration determines certification chain-of-custody integrity and margin capture for premium formulations.
- Retail Stores:Traditional agrochemical networks resist retraining sales staff on organic product attributes, ceding ground in certified segments. Yara International leverages established Brazilian distribution infrastructure to push premium formulations into resistant southern soybean belt territories.
- Direct Sales:Large-scale growers bypass intermediaries to secure MAPA-certified supply relationships and documentation for export compliance.
- Online Sales:Urban home gardener segment and small-scale horticultural operations access specialized formulations outside traditional catchment areas.
- Wholesalers:Volume commodity compost flows through bulk handlers serving agronomic buyers with limited certification requirements.
Direct sales capture the steepest expansion trajectory in certified segments while retail stores retain commodity volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Brazilian states, with export-bound growers in Mato Grosso absorbing steep organic premiums while price-sensitive subsistence operations in the Northeast resist conversion despite regulatory pressure.
Mato Grosso
Large-scale no-till soybean operations drive tonnage demand as ABC+ Plan runoff limits compel watershed buffer compliance. ANVISA's contaminant thresholds force preprocessing upgrades at composting facilities serving the Cerrado corridor. Lucas do Rio Verde and Sorriso anchor certified organic procurement clusters where EU Deforestation Regulation traceability mandates dominate buying committee criteria.
São Paulo
Urban waste collection networks supply consistent compost feedstock volumes for commercial-scale production. State-level environmental agencies enforce buffer zone requirements that effectively mandate organic transition near water bodies. Piracicaba and Campinas host greenhouse horticulture operations commanding residue-free certification premiums from European retail chains.
Paraná
Poultry litter supply from regional integrators creates input concentration risk when avian disease cycles disrupt availability. The state's enforced organic transition zones near reservoirs generate captive demand clusters with regulatory certainty. Maringá and Londrina anchor backward integration into captive litter processing for domestic fertilizer manufacturing.
Rio Grande do Sul
Southern soybean belt operations face synthetic fertilizer price anchoring that limits organic premium capture during commodity downturns. MAPA's organic certification program shapes market access for export-bound producers in the region. Passo Fundo and Santa Maria concentrate precision fermentation adoption for rapid-release liquid formulations.
Minas Gerais
Protected agriculture near Belo Horizonte demands residue-free certification that organic liquid formulations command at margin premiums. Pending updates to Brazil's National Fertilizer Policy reshape import dependencies for organic base materials. The São Francisco Valley irrigated fruit orchards present fertigation system retrofitting potential as drip infrastructure spreads.
Brazil Organic Fertilizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzymatic digestion specialists commanding premium positioning while volume compost processors compete on feedstock access. The market fragments across three strategic tiers: multinational formulation platforms, regional integrators with captive raw material supply, and domestic composting specialists. Consolidation pressure intensifies as certification requirements raise capital barriers. Dominant competitive moves include backward integration into poultry litter processing and direct sales channel establishment to bypass legacy agrochemical distributors.
Among multinational platforms, Yara International leverages its established Brazilian distribution infrastructure to push premium formulations into resistant southern soybean belt territories. Grupo Fertipar anchors regional supply through backward integration into poultry litter processing, exemplifying the captive feedstock archetype. Novozymes occupies a position representing enzymatic differentiation, with its digestion platforms compressing nutrient release timelines to match synthetic application windows.
| Leading Market Players |
|---|
| Yara International |
| Mosaic |
| Grupo Fertipar |
| Heringer |
| Ave Ferti |
| Agrivalle |
| Novozymes |
| ICL Group |
| Nortox |
| Others |
Pricing and Supply Chain Analysis
Composting facility scale economies in São Paulo's urban waste corridor determine regional price floors, as preprocessing capacity utilization rates directly shape ANVISA compliance costs that feed into MAPA-certified product premiums across the Cerrado corridor.
Pricing Analysis
MAPA's organic certification program dictates the pricing tier structure across the Brazilian market. Three-tier pricing structure across premium certified, standard compost, and economy manure levels separates export-compliant formulations from domestic agronomic grades. Price differentiation rests on certification documentation depth and enzymatic processing intensity. Cost compression in standard compost tiers is intensifying because ANVISA's heavy metal thresholds force capital-intensive preprocessing upgrades. Export-bound growers in Mato Grosso demonstrate lowest price sensitivity, while subsistence operations in the Northeast exhibit acute resistance to organic premiums.
Supply Chain Analysis
Poultry litter availability from Paraná and Rio Grande do Sul integrators anchors feedstock concentration risk for solid organic fertilizer production. Raw material dependencies draw from municipal waste streams, avian agriculture residues, and imported bone meal extracts. Single-source vulnerability runs through regional integrator concentration when avian disease cycles disrupt litter flows. Distribution runs through direct sales channels for certified segments and legacy agrochemical retail networks for commodity compost volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic digestion platforms are reconfiguring the organic fertilizer value chain as interoperability standards between precision fermentation systems and fertigation infrastructure create new ecosystem control points.
For Market Incumbents: Shield MAPA-certified market position by accelerating backward integration into captive poultry litter processing in Paraná, while investing in enzymatic platform R&D to match synthetic fertilizer application windows. Consolidate distribution control through direct sales channel establishment that bypasses legacy agrochemical retail networks resistant to microbial mineralization training. For New Entrants and Emerging Players: Technical support gaps in microbial inoculant formulation expertise present white-space opportunity where incumbents under-serve. Target greenhouse horticulture operations near Belo Horizonte and Curitiba with residue-free certification demands. Establish go-to-market presence through fertigation system retrofit partnerships in São Francisco Valley irrigated orchards. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic digestion specialists with proven nutrient release acceleration. Long-term viability hinges on regulatory enforcement durability across ABC+ Plan and EU Deforestation Regulation compliance requirements. Acquisition focus should center on regional integrators with captive feedstock and MAPA-approved processing infrastructure. Monitor MAPA certification queue compression as inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Poultry Litter Processing | Captive feedstock supply from Paraná integrators insulates against avian disease volatility. |
| Enzymatic Platform Scale-Up | Novozymes-type digestion systems compress nutrient release timelines to match synthetic windows. |
| Direct Sales Channel Establishment | Bypassing agrochemical retail networks secures MAPA certification chain-of-custody integrity. |
| Greenhouse Horticulture Partnership | Residue-free certification commands shelf-space access with European retail chains. |
| Fertigation System Retrofit Program | São Francisco Valley drip infrastructure expansion displaces synthetic dependency in irrigated orchards. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, MAPA certification databases, and customs trade records. Input was gathered through structured interviews with composting facility operators, poultry integrator procurement leads, agronomic buying committee directors, and greenhouse horticulture managers. Bottom-up volume modeling triangulates against top-down macroeconomic indicators across the Brazilian agricultural sector.
Segmentation dimensions modeled include product type, application category, end-user archetype, and distribution channel across the projection horizon. CAGRs were derived from regression analysis of historical adoption curves and regulatory enforcement trajectories. Industry-specific forecast inputs incorporate ABC+ Plan implementation timelines and EU Deforestation Regulation traceability mandate adoption rates.
Underlying assumptions cover MAPA certification processing efficiency and poultry litter supply stability, with deviation risk concentrated in avian disease cycle severity and National Fertilizer Policy import restriction tightening. Practitioners should keep alternative scenarios live as ANVISA contaminant threshold enforcement intensity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Applicators Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Global Nitrogenous Fertilizer Market