
 Humate Fertilizer Market | 2026-2036
Humate Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Humate Fertilizer Market Foresight
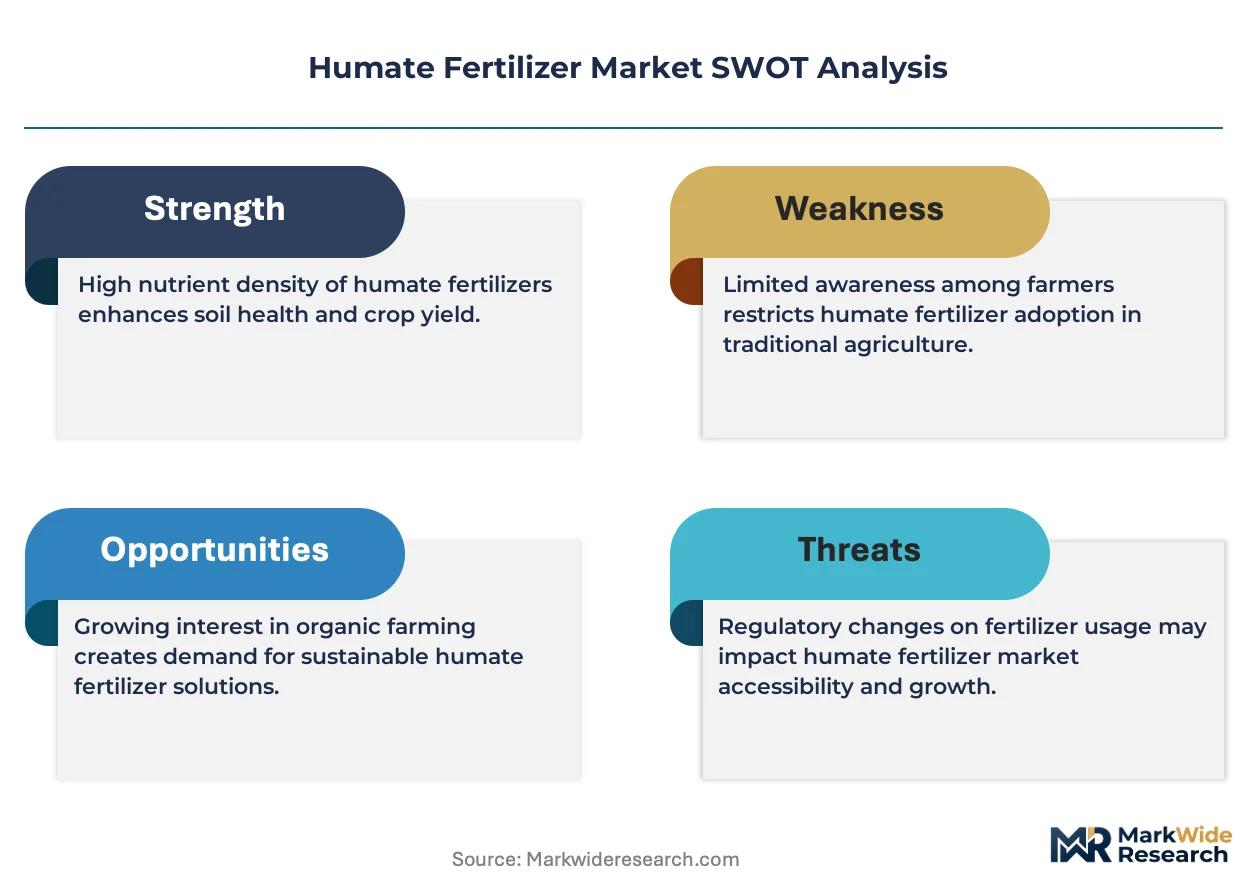
The EU Green Deal is rebalancing agricultural input priorities across European farmland, tightening synthetic fertilizer allowances and elevating soil health amendments. BASF AG leverages its crop science division to integrate humate formulations into broader biological portfolios. Syngenta sustains competitive positioning through channel depth in specialty crop regions. Humintech GmbH anchors its operations in German manufacturing scale for powdered and granulated humate exports.
Humate fertilizers comprise decomposed organic matter rich in humic and fulvic acids, typically extracted from leonardite or peat sources through alkaline solubilization processes that yield carbon-dense soil amendments. These compounds chelate micronutrients and improve cation exchange capacity in degraded soils. Liquid humates capture expanding share in fertigation systems for high-value horticultural plants, while solid formats retain margin strength among broadacre farmers purchasing through agricultural supply cooperatives. Granulated variants occupy the fastest-growth trajectory as blending compatibility with NPK fertilizers improves.
REACH registration requirements in Europe govern humic substance classifications and extraction method disclosures, while the USDA's National Organic Program certifies allowable sources for organic crop production. India's FSSAI and BIS standards increasingly scrutinize heavy metal limits in imported organic amendments. Stakeholders must monitor regulatory divergence between jurisdictions as carbon accounting methodologies mature and buyer certification requirements fragment across export markets.
Market Dynamics
Carbon accounting methodologies are tightening disclosure requirements for soil amendments across agricultural supply chains, forcing input suppliers to document humic acid provenance and extraction energy intensity. This structural pressure is rebalancing procurement criteria toward certified, traceable humate sources.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Synthetic fertilizer reduction mandates redirect commercial investment toward soil health amendments. Member state agricultural ministries accelerate subsidy programs for carbon-sequestering inputs.
- Precision fertigation adoption:High-value horticultural operations in California and the Pacific Northwest integrate liquid humates into automated dosing systems. Specialty crop growers demand water-soluble formulations compatible with drip infrastructure.
- Brazilian Cerrado expansion:Large agricultural companies embed humates into soybean fertility programs across degraded savanna soils. Domestic blending facilities multiply to serve precision agriculture contracts.
Market Restraints
- Leonardite supply concentration:Premium humate feedstock deposits cluster in Wyoming, North Dakota, and Xinjiang. Geopolitical friction and transport bottlenecks create input volatility for European and Asian processors.
- REACH registration complexity:ECHA classification disputes over humic substance definitions delay market entry for novel extraction methods. Compliance costs disproportionately burden mid-scale suppliers.
- Peat substitution pressure:Environmental opposition to peat harvesting in Ireland and the Baltic states restricts traditional sourcing channels. Synthetic soil amendments and composted alternatives capture price-sensitive volume.
Strategic Opportunities
- Indian organic certification expansion:FSSAI and BIS standards for heavy metal limits create first-mover advantage for compliant exporters. Domestic organic acreage targets outpace certified amendment supply.
- Granulated NPK compatibility:Blending technology advances enable humate integration into bulk fertilizer coatings. Broadacre cooperatives in the US Corn Belt and Ukraine wheat regions represent untapped volume.
- Carbon credit monetization:Emerging soil carbon protocols in Australia and Canada recognize humate applications as qualifying practices. Verification infrastructure investment opens premium pricing tiers.
Industry Challenges
- Extraction process standardization:Alkaline solubilization protocols vary across leonardite sources, yielding inconsistent humic acid concentrations. Quality assurance laboratories struggle to harmonize test methodologies.
- Agronomist training gaps:Soil science curricula at Brazilian and Indian universities underemphasize humate application timing and rate optimization. Extension services lack field trial data for region-specific recommendations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humate Fertilizer Market |
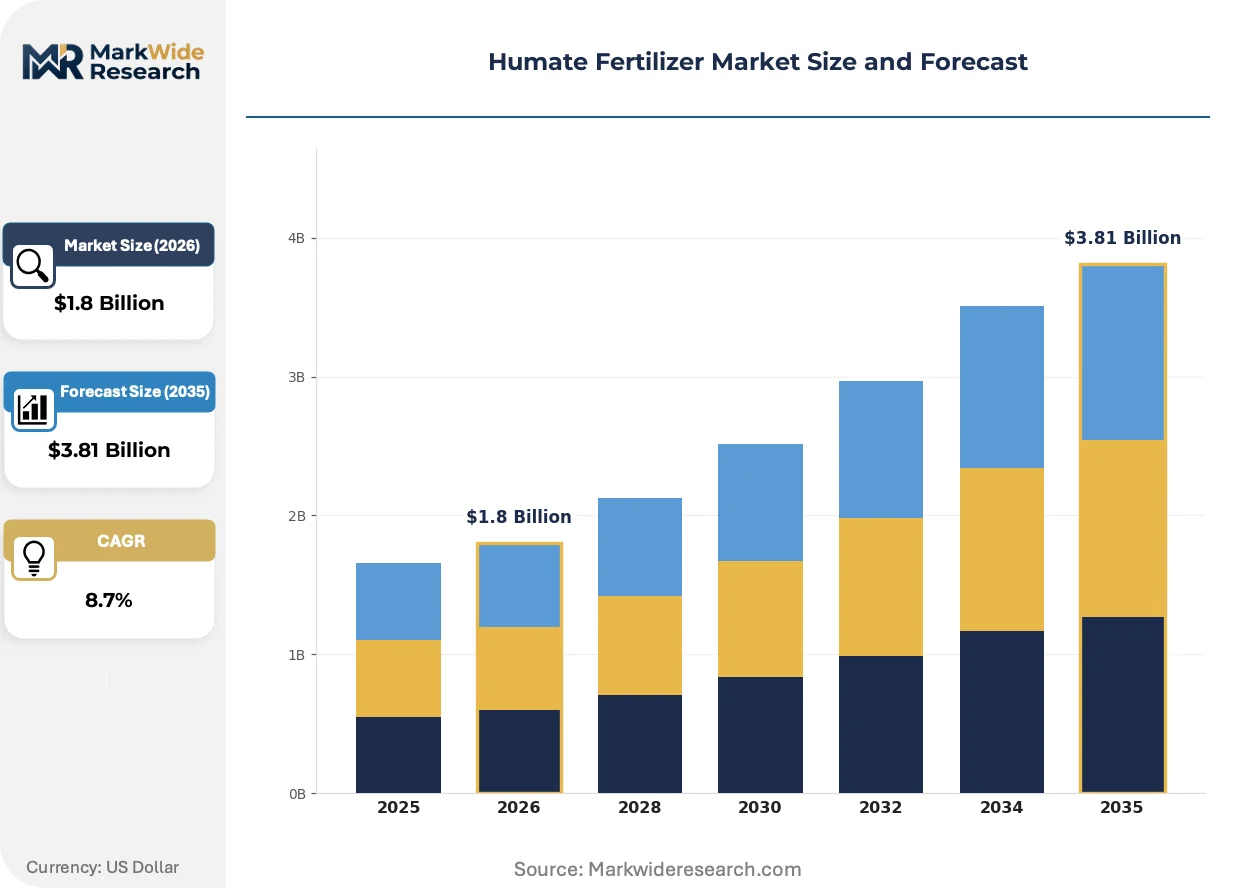
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Humates, Liquid Humates, Powdered Humates, Granulated Humates Application: Agricultural Crops, Horticultural Plants, Turf Grass, Landscaping End User: Farmers, Agricultural Companies, Gardeners, Landscape Professionals Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply, Wholesale Distributors |
| Companies Covered | BASF AG, Syngenta, Solvay SA, UPL India, Clariant AG, Evonik Industries AG, HGS BioScience Inc., The Andersons Inc., Humintech GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humate Fertilizer Market Shifts & Advancements
Biological agriculture certification requirements are compressing formulation development cycles, pushing suppliers toward multi-functional amendments that satisfy both organic compliance and performance metrics. Three distinct vectors are reshaping competitive positioning.
Microbial-humate co-formulations are electrifying the biologicals segment, combining fungal inoculants with fulvic acid carriers to improve shelf stability and root colonization rates. Large-scale vegetable producers in Spain and Italy adopt these integrated products for greenhouse operations. The technology is electrifying R&D priorities at crop science divisions, compressing standalone humate development timelines.
REACH substance evaluation deadlines for humic and fulvic acid classifications are forcing extraction method disclosures across European supply chains. ECHA data requirements compel suppliers to document alkaline solubilization parameters and heavy metal screening protocols. German and Dutch importers now demand third-party verification for leonardite sources outside OECD jurisdictions.
Direct-to-farm digital platforms are fragmenting traditional agricultural cooperative purchasing patterns in the US and Australia. Specialty crop growers bypass distributors to procure certified organic amendments through verified supplier marketplaces. This channel shift concentrates in high-value viticulture and orchard operations where traceability commands price premiums.
Humate Fertilizer Market Segmentation
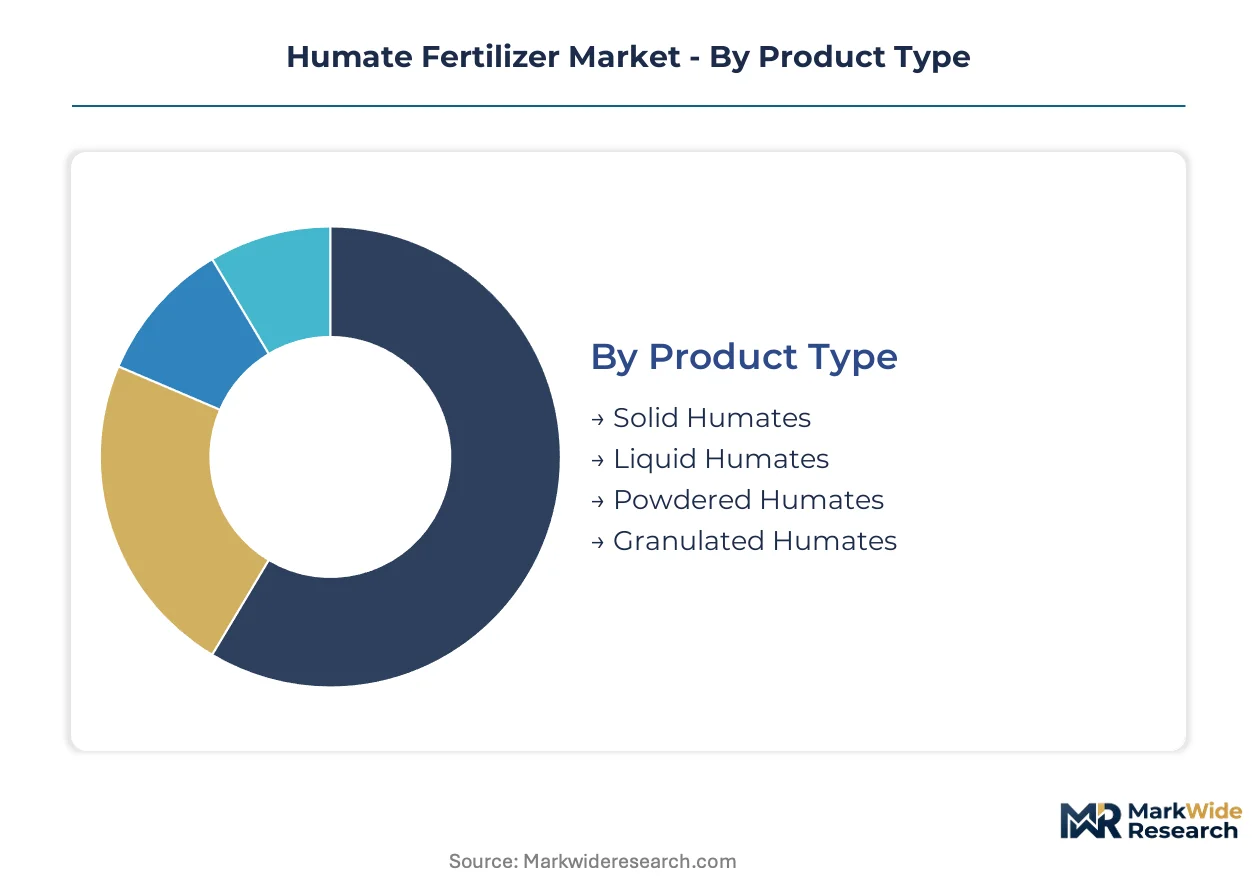
Humate fertilizer segmentation reflects divergent technical requirements across soil amendment applications. Upgrade cycles vary dramatically between broadacre commodity farming and precision horticulture, driving format innovation and channel restructuring.
Product Type:
Replacement cycles accelerate where application infrastructure modernizes, pushing growers toward formats compatible with automated systems.
- Liquid Humates:Water-soluble extracts with high fulvic acid content enable fertigation compatibility. California almond orchards and Pacific Northwest berry operations integrate these into drip-line automation, though transport costs constrain inland distribution.
- Granulated Humates:Compressed leonardite derivatives with controlled-release characteristics blend mechanically with NPK fertilizers. Brazilian soybean cooperatives and Ukrainian wheat collectives drive procurement as coating technology improves uniformity.
- Solid Humates:Raw or minimally processed carbon-dense amendments suit manual broadcast application. Price-sensitive broadacre farmers in India's Punjab and Haryana states favor this format for basal dressing.
- Powdered Humates:Fine-milled dust formulations dissolve rapidly for foliar sprays or compost inoculation. European organic greenhouse operators specify micronized grades for substrate integration.
Granulated formats sit at the top of the volume ranking, with liquid humates climbing the fastest as precision irrigation expands.
Application:
Cost tiers separate commodity crop deployment from premium horticultural specifications, fragmenting supplier pricing power.
- Agricultural Crops:Field-scale grain and oilseed programs prioritize cost-per-acre efficiency. Brazil's Cerrado soybean belt and US Corn Belt cooperatives negotiate bulk contracts based on humic acid concentration guarantees.
- Horticultural Plants:High-value fruit, vegetable, and ornamental production demands certified organic grades with heavy metal documentation. Spanish greenhouse complexes and Italian vineyard estates specify ECHA-compliant extraction methods.
- Turf Grass:Golf course and sports field maintenance requires rapid greening response with minimal burn risk. Municipal procurement in Australia's drought-prone regions emphasizes water retention properties.
- Landscaping:Commercial and residential soil conditioning for ornamental plantings favors convenience packaging. US urban tree-planting programs and Middle Eastern greening initiatives drive seasonal demand spikes.
Agricultural crops dominate absolute tonnage, while horticultural applications command the steepest expansion trajectory through certification premiums.
End User:
Customer sophistication varies across operational scale, dictating technical support intensity and channel preference.
- Agricultural Companies:Large-scale farming enterprises with precision agriculture infrastructure integrate humates into fertility management software. Brazilian and Argentinian grain operators contract directly with processors for customized formulations.
- Farmers:Individual and family operations rely on cooperative purchasing and extension service recommendations. Indian smallholders in organic transition zones seek government-subsidized certified inputs.
- Landscape Professionals:Commercial installers and maintenance contractors demand consistent product performance across project portfolios. German municipal landscaping departments specify DIN-compliant quality grades.
- Gardeners:Hobby and small-scale organic growers purchase through retail channels with label clarity priorities. North American consumer markets show rising interest in home composting amendments.
Agricultural companies anchor procurement volume, with landscape professionals gaining share fastest through urban greening contracts.
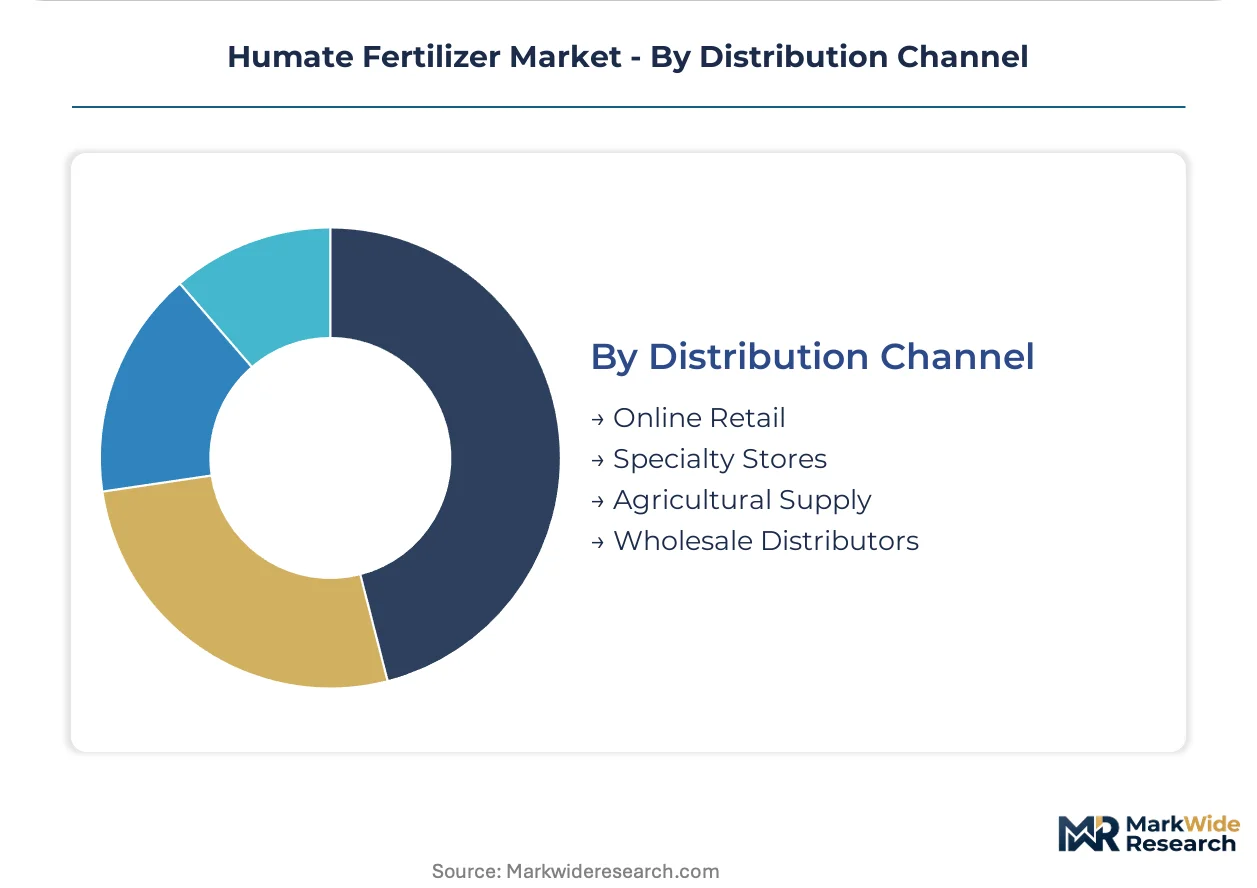
Distribution Channel:
Supply concentration in leonardite-rich regions shapes logistics economics and channel viability.
- Agricultural Supply:Cooperative-owned retail networks dominate rural fertilizer procurement in the US Midwest and Canadian prairies. Member-owners negotiate collective pricing for certified organic grades.
- Wholesale Distributors:Regional bulk handlers manage inventory across multiple manufacturer relationships. European importers source from Wyoming and Xinjiang deposits through Rotterdam and Hamburg port facilities.
- Specialty Stores:Garden center and hydroponic retailers serve high-margin niche segments with technical consultation. Australian independent chains emphasize biological certification verification.
- Online Retail:Direct-to-farm platforms fragment traditional cooperative purchasing in specialty crop regions. California viticulture operations procure traceable amendments through verified supplier marketplaces.
Agricultural supply cooperatives maintain volume leadership, while online retail expands most quickly through traceability premiums in high-value segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Humate fertilizer production originated in German peat-rich regions during the early twentieth century, with industrial-scale extraction spreading to leonardite deposits in the American West and China's Xinjiang basin by the 1980s. Today's procurement patterns trace these geological legacies.
United States
Wyoming and North Dakota leonardite deposits supply premium feedstock for domestic processors and European exporters. USDA's National Organic Program certifies allowable extraction methods for organic crop production. California's Central Valley almond orchards and Pacific Northwest berry operations integrate liquid humates into precision fertigation infrastructure.
Germany
EU Green Deal Farm to Fork strategy tightens synthetic fertilizer allowances, redirecting commercial investment toward soil amendment alternatives. ECHA REACH registration requirements govern humic substance classifications and extraction method disclosures. Humintech GmbH anchors manufacturing operations in North Rhine-Westphalia for powdered and granulated export production.
Brazil
Large agricultural companies embed humates into soybean fertility programs across the degraded savanna soils of the Cerrado belt. ANVISA and MAPA regulations scrutinize heavy metal limits in imported organic amendments. Domestic blending facilities multiply in Mato Grosso and Goiás to serve precision agriculture contracts.
India
Domestic organic acreage targets outpace certified amendment supply, creating procurement pressure for compliant exporters. FSSAI and BIS standards increasingly scrutinize heavy metal limits in imported organic inputs. Punjab and Haryana smallholders favor solid humate formats for basal dressing of field crops.
China
Xinjiang basin leonardite deposits feed both domestic processors and Asian export markets. MEE environmental standards and dual carbon goals shape extraction energy intensity disclosures. Shandong and Jiangsu provinces host granulation facilities serving domestic NPK blending operations.
Humate Fertilizer Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across divergent competitive terrain. The vendor base organizes around three strategic archetypes: integrated crop science divisions with biological portfolios, dedicated humate processors controlling leonardite feedstock, and regional blenders serving cooperative channels. Consolidation pressures concentrate among mid-scale suppliers facing REACH compliance burdens, while capacity expansion dominates in Brazilian and Indian markets. Strategic partnerships between extraction specialists and distribution cooperatives reshape channel economics in the US Corn Belt and Ukrainian wheat regions.
Among German chemical conglomerates, BASF AG and Evonik Industries AG occupy positions spanning crop science and specialty chemical divisions. Humintech GmbH exemplifies the dedicated processor archetype with captive manufacturing scale. Syngenta represents the integrated biologicals vector through channel depth in specialty crop regions. These anchors illustrate how competitive positioning fragments across feedstock control, formulation expertise, and distribution reach.
| Leading Market Players |
|---|
| BASF AG |
| Syngenta |
| Solvay SA |
| UPL India |
| Clariant AG |
| Evonik Industries AG |
| HGS BioScience Inc. |
| The Andersons Inc. |
| Humintech GmbH |
| Others |
Supply & Pricing Matrix
The EU Green Deal Farm to Fork strategy gates qualified supply and premium-tier pricing access, restricting synthetic fertilizer allowances while elevating certified humate sources. Buyers lacking ECHA-compliant extraction documentation face exclusion from subsidy-eligible procurement pools, compressing margin capture for non-certified processors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium tiers command organic program compliance with heavy metal documentation, while economy segments serve price-sensitive Indian smallholders in Punjab and Haryana. Cost compression in standard tiers is intensifying because REACH registration burdens disproportionately burden mid-scale suppliers. Agricultural companies with precision agriculture infrastructure exhibit least price sensitivity; individual farmers through cooperative channels show highest elasticity.
Supply Chain Analysis
Direct-to-farm digital platforms fragment traditional cooperative purchasing patterns in specialty crop regions. Geographic supply concentrates in Wyoming, North Dakota, and Xinjiang for premium leonardite feedstock. Raw material dependencies center on alkaline solubilization chemicals, energy inputs for extraction, and micronutrient blending components. Single-source vulnerability runs through Xinjiang deposit access for Asian processors. Distribution runs through agricultural supply cooperatives in the US Corn Belt and wholesale distributors at Rotterdam and Hamburg port facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The humate fertilizer market functions as a regulatory compounder, with EU Green Deal synthetic reduction mandates structurally elevating soil amendment demand across European farmland.
For Market Incumbents: Deploy extraction method standardization to defend against quality inconsistency challenges. Invest in captive leonardite sourcing through offtake agreements with Wyoming and North Dakota deposit operators. Strengthen ECHA pre-registration documentation to accelerate novel formulation market entry. For New Entrants and Emerging Players: Direct-to-farm digital platforms offer the most penetrable route into California viticulture and Pacific Northwest berry operations. Target certified organic segments where traceability commands price premiums. Pursue white-label granulation partnerships with Ukrainian wheat cooperatives seeking NPK blending compatibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European processors facing REACH compliance cost burdens. Long-term viability favors feedstock-integrated operators with captive leonardite access. Watch for carbon credit protocol recognition in Australia and Canada as inflection indicators for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leonardite Deposits | Wyoming and North Dakota offtake agreements secure premium feedstock supply for European and Asian processors. |
| REACH Pre-Registration Investment | ECHA-compliant extraction documentation accelerates novel humic acid formulation market entry timelines. |
| Granulated NPK Coating Partnerships | Brazilian soybean cooperatives and Ukrainian wheat collectives drive volume through blending compatibility advances. |
| Direct-to-Farm Platform Launch | California almond orchards and Pacific Northwest berry operations bypass distributors for certified organic procurement. |
| Carbon Credit Verification Infrastructure | Australian and Canadian soil carbon protocols recognize humate applications as qualifying agricultural practices. |
Research Methodology
Multiple input streams — primary interviews with humate processors, agricultural cooperative procurement managers, and precision agriculture specialists; secondary validation through USDA National Organic Program filings, ECHA REACH registration databases, and customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations with Brazilian soybean fertility program directors, Indian FSSAI compliance officers, and German DIN standard laboratory heads informed extraction protocol and certification requirement assessments. Secondary sources included ANVISA and MAPA regulatory filings, Wyoming Mining Association production statistics, and EU Farm to Fork strategy implementation documents.
Data-stream reconciliation across product format segmentation, application intensity modeling, and end-user sophistication tiers generated volume and value outputs over the projection horizon. Segmentation dimensions encompassed liquid, granulated, solid, and powdered formats; agricultural crops, horticultural plants, turf grass, and landscaping applications; and agricultural companies, farmers, landscape professionals, and gardeners as end users. CAGRs were derived from regression analysis against organic acreage expansion trajectories and synthetic fertilizer substitution elasticities, with carbon credit monetization potential and REACH compliance cost curves as industry-specific forecast inputs.
Regulatory reclassification, leonardite supply disruption, and carbon protocol non-recognition are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding EU subsidy program continuity and Brazilian Cerrado precision agriculture adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Nano Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Global Urea Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
South America Fertilizers Market