
 Organic Soybean Market | 2026-2036
Organic Soybean Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Soybean Market Outlook
Multi-source procurement is decoupling from the long-standing single-origin contracts that dominated organic soybean trading. Cargill Incorporated leverages its North American elevator network to secure identity-preserved organic streams. Bunge Limited anchors its position through South American origination partnerships with certified organic cooperatives. Louis Dreyfus Company competes by operating dedicated organic handling facilities that prevent commingling with conventional soybeans.
Organic soybeans are leguminous oilseeds grown without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, typically achieving 40% protein content and 20% oil content by weight; they serve as the primary input for non-GMO food-grade soy protein, organic vegetable oils, and livestock feed meeting certified organic standards. Whole beans command the dominant volume share as crushing feedstock for organic soy oil and meal production. Soy milk represents the fastest-growing product type as refrigerated plant-based beverage sections expand across mainstream retail channels. Tofu maintains mature demand within East Asian foodservice and vegetarian consumer segments, while soy flour occupies niche positioning in gluten-free and high-protein baking applications.
The USDA National Organic Program governs certification, labeling, and handling standards for domestic production and import eligibility. The EU Organic Regulation and its equivalence agreements determine market access for third-country suppliers shipping into European processing facilities. FDA food safety rules and FSMA traceability requirements add compliance layers for organic soybean derivatives entering human food channels. Stakeholders must monitor evolving EU deforestation-free supply chain mandates and their potential to redirect sourcing away from regions lacking geolocation verification systems.
Market Dynamics
Multi-origin procurement contracts are displacing single-source agreements as plant-based meat manufacturers demand supply resilience and traceability assurance from crushing facilities.
Growth Catalysts
- EU Organic Regulation equivalence agreements:Third-country suppliers gain streamlined market access into European processing corridors, expanding origination options for certified organic streams.
- Plant-based protein extrusion technology:Food processors achieve higher protein yield per bushel, tightening the link between organic soybean crushing and specialized ingredient manufacturing.
- Midwest crushing facility clusters:Geographic concentration of identity-preserved handling infrastructure reduces contamination risk and shortens elevator-to-processor transit times.
Market Restraints
- Petroleum-based fertilizer substitution costs:Organic cultivation requires manure and legume rotation inputs that command premium pricing against conventional synthetic alternatives.
- South American origination concentration:Certified organic cooperative dependency in Brazil and Argentina exposes buyers to port congestion and currency fluctuation risks.
- Geolocation verification system gaps:EU deforestation-free supply chain mandates threaten market exclusion for regions lacking satellite-tracked farm boundary documentation.
Strategic Opportunities
- India organic acreage expansion:FSSAI organic certification alignment with EU equivalence standards positions Indian farmers for export origination into European crushing facilities.
- Refrigerated plant-based beverage channels:Mainstream retail dairy case resets create dedicated shelf space for soy milk derivatives with certified organic labeling.
- Blockchain-enabled traceability platforms:Integration with elevator networks allows real-time lot tracking from farm gate to processor, satisfying FSMA recordkeeping requirements.
Industry Challenges
- Certified organic agronomist scarcity:Crop rotation planning and natural pest management expertise lags behind acreage conversion timelines in emerging origination regions.
- Identity-preserved handling infrastructure:Dedicated organic silo construction and equipment segregation demands capital deployment that smaller elevator operators struggle to finance.
- USDA National Organic Program audit backlogs:Certification timeline delays create planting season uncertainty for farmers transitioning from conventional cultivation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Soybean Market |
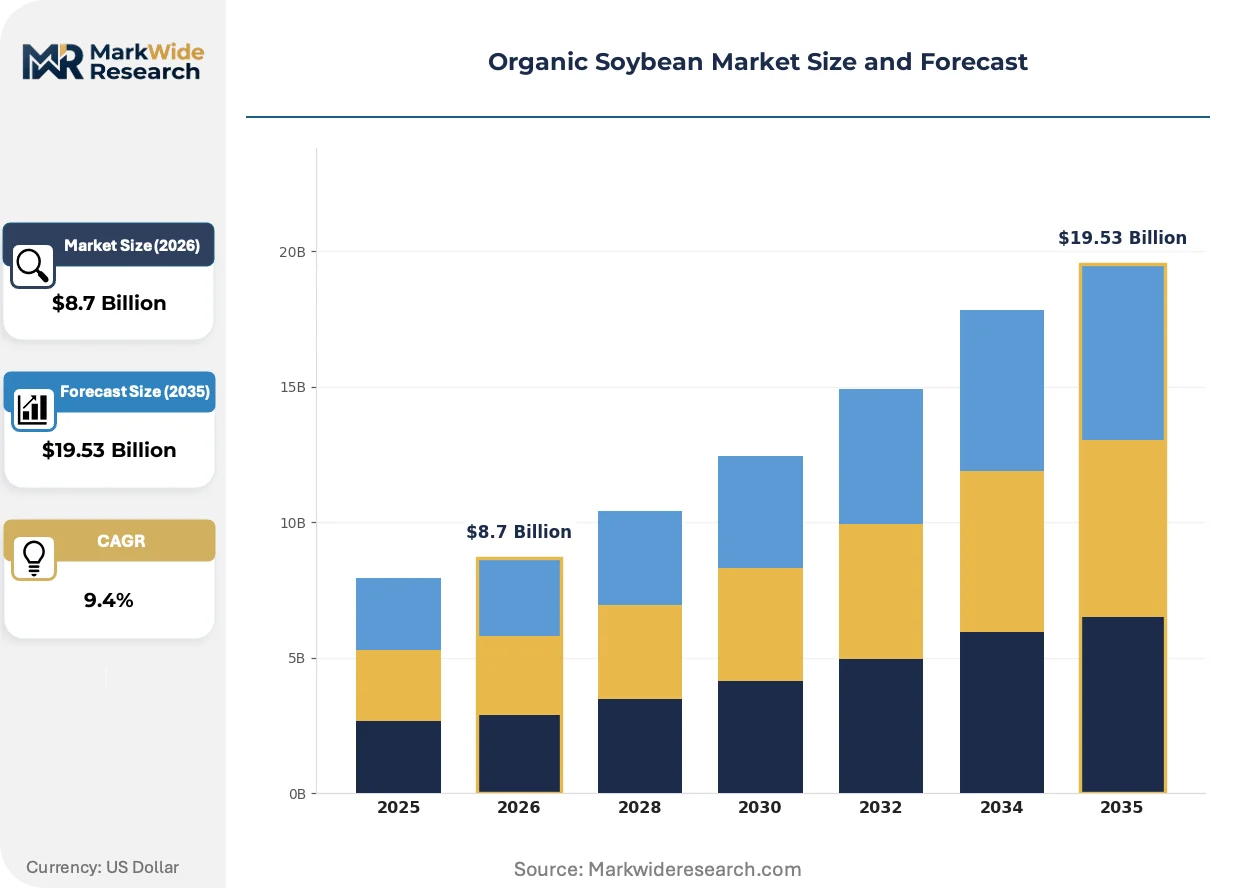
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Soy Milk, Tofu, Soy Flour Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Farmers' Markets End User: Food Industry, Health-conscious Consumers, Restaurants, Nutraceuticals Packaging Type: Bulk Packaging, Retail Bags, Tetra Packs, Cans |
| Companies Covered | Bunge Limited, Louis Dreyfus Company, Cargill Incorporated, SunOpta Inc., CHS Inc., Archer Daniels Midland, COFCO International, Grain Millers, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Soybean Market Strategic Shifts
Near-infrared spectroscopy and automated sorting systems are compressing quality-assurance timelines at receiving elevators, while regulatory pressure on deforestation-free sourcing reconfigures origination geography.
Optical sorting technology with real-time protein and oil analysis is automating intake segregation decisions at organic soybean receiving facilities. Crushing operators in Iowa and Illinois deploy these systems to separate food-grade from feed-grade lots without manual sampling delays. The compression of intake-to-contract matching timelines is squeezing spot-market premiums for ungraded deliveries.
EU deforestation-free supply chain mandates are tightening eligibility for organic soybean shipments into Rotterdam and Hamburg crushing terminals. The regulation requires geolocation coordinates for every production plot, disqualifying aggregated smallholder deliveries lacking farm boundary documentation. Brazilian cooperatives are deploying satellite mapping partnerships to preserve European market access ahead of enforcement deadlines.
Long-term offtake agreements now dominate procurement between plant-based meat manufacturers and organic protein suppliers. Impossible Foods and Beyond Meat negotiate multi-year crushing commitments directly with Midwest processors, bypassing traditional commodity merchants. This channel consolidation concentrates volume planning power with food-grade protein specialists in Minnesota and Indiana processing corridors.
Organic Soybean Market Segmentation
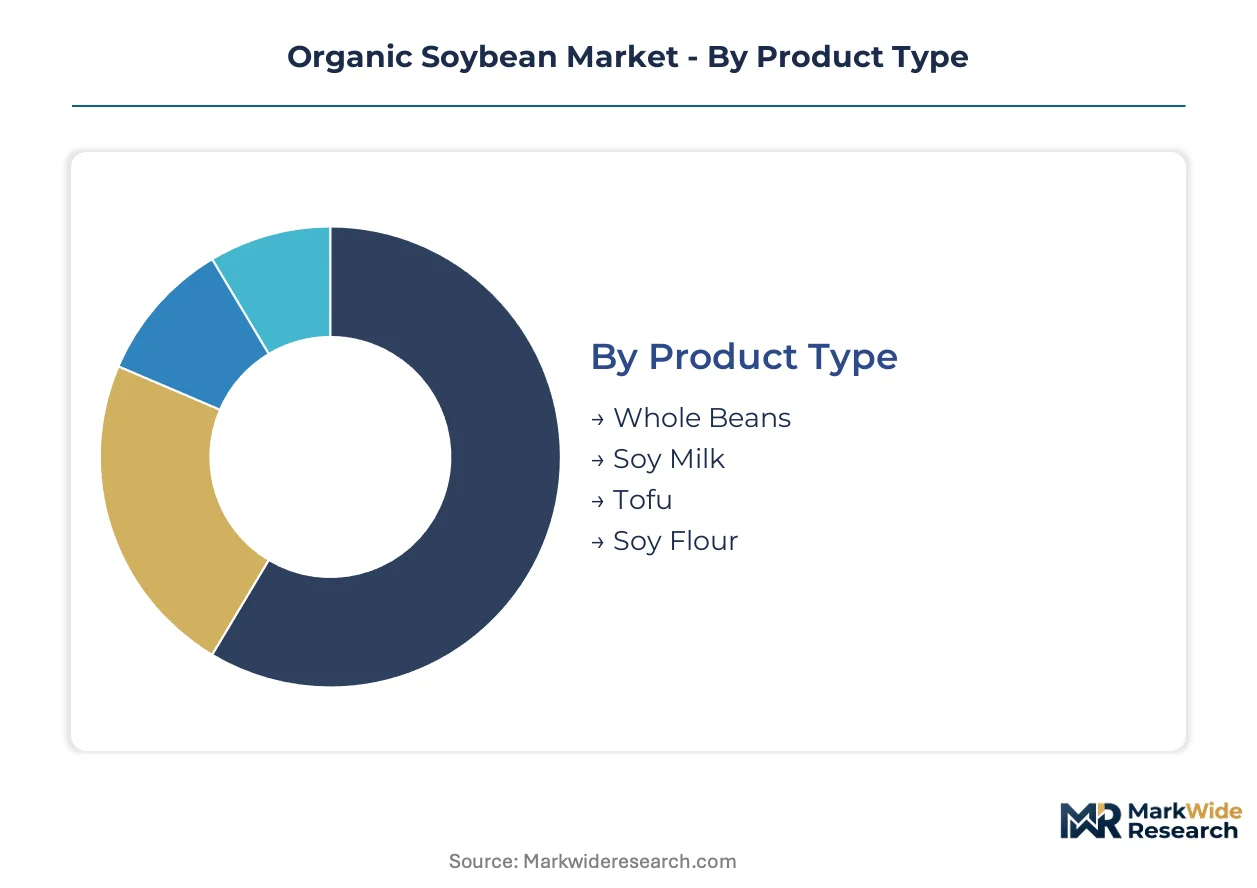
Organic soybean segmentation reveals how certification tiers, handling requirements, and channel economics partition buyers into distinct procurement behaviors. Each category exposes different margin structures and compliance burdens that shape supplier strategy.
Product Type:
Buyers differentiate by processing intensity and margin capture potential across the value chain.
- Whole Beans:Raw organic soybeans with 40% protein and 20% oil content serve as crushing feedstock for organic meal and oil extraction. Demand concentrates around Midwest processing corridors in Iowa and Illinois, where identity-preserved elevator networks reduce commingling risk for food-grade protein manufacturers.
- Soy Milk:Refrigerated plant-based beverages command expanding shelf space in mainstream retail dairy resets. North American supermarket chains are resetting cooler layouts to accommodate certified organic labeling, tightening supply contracts with dedicated crushing facilities.
- Tofu:Coagulated curd products maintain established demand within East Asian foodservice channels and vegetarian consumer bases.
- Soy Flour:Defatted powder occupies niche positioning in gluten-free and high-protein baking formulations.
Whole Beans leads volumes today; Soy Milk is gaining share fastest.
Distribution Channel:
Channel selection correlates with buyer price sensitivity and traceability verification requirements.
- Supermarkets:Mainstream retail chains with dedicated organic sections and refrigerated dairy case resets. Volume procurement concentrates through direct processor agreements, bypassing traditional commodity merchants for plant-based beverage SKUs.
- Health Food Stores:Specialty retailers emphasizing certified organic labeling and non-GMO verification. Premium positioning supports smaller-batch tofu and soy flour SKUs with identity-preserved documentation.
- Online Retail:E-commerce platforms serving dispersed health-conscious consumers with subscription-based soy milk replenishment.
- Farmers' Markets:Direct producer-to-consumer channels for local organic whole bean sales and artisan tofu products.
Supermarkets dominate revenue contribution; Online Retail shows steepest expansion trajectory.
End User:
End-use segmentation tracks how processing depth and certification stringency partition demand.
- Food Industry:Plant-based meat manufacturers and soy protein extrusion facilities. Long-term offtake agreements now bypass commodity merchants, concentrating volume planning power with Minnesota and Indiana processing specialists.
- Health-conscious Consumers:Retail purchasers prioritizing certified organic labeling in refrigerated beverage and meat alternative categories.
- Restaurants:Foodservice operators sourcing organic tofu and soy milk for vegetarian menu expansion.
- Nutraceuticals:Supplement manufacturers extracting isoflavones and protein isolates for functional health products.
Food Industry anchors procurement volumes; Nutraceuticals is climbing the fastest.
Packaging Type:
Packaging economics reflect handling scale and shelf-life requirements across the supply chain.
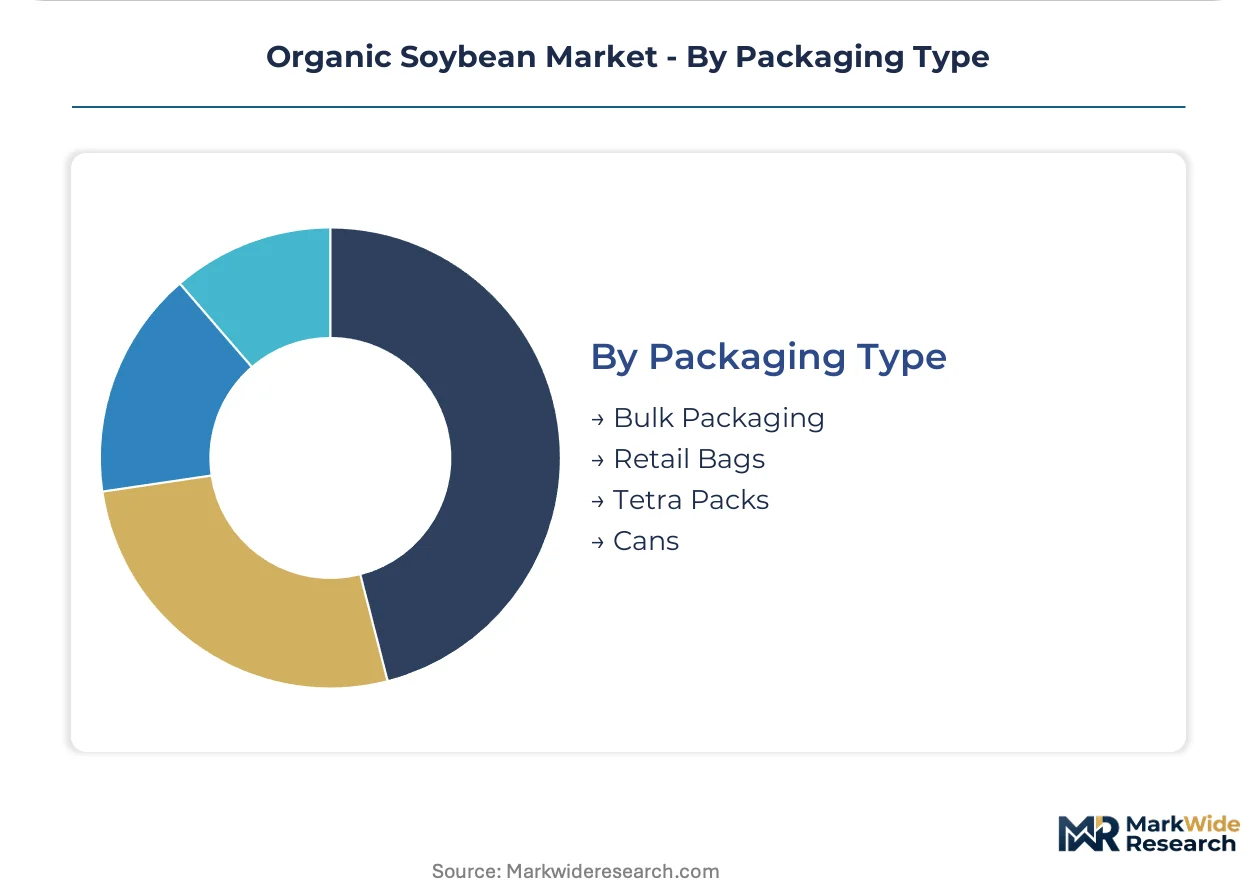
- Bulk Packaging:Railcar and container loads for crushing facilities and food manufacturers. Demand concentrates at Pacific Northwest export terminals serving Asian markets and Midwest processor intake points.
- Retail Bags:Consumer-facing whole bean and flour packaging with certified organic labeling for supermarket shelves.
- Tetra Packs:Aseptic cartons for refrigerated soy milk with extended shelf stability.
- Cans:Shelf-stable liquid and solid soy products for institutional foodservice and emergency stockpiling.
Bulk Packaging leads shipment volumes; Tetra Packs is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest crushing facility clusters in Iowa and Illinois anchor organic soybean processing capacity, drawing identity-preserved streams from elevator networks across the Corn Belt and Prairie Provinces.
United States
Plant-based meat manufacturers in Minnesota and Indiana processing corridors negotiate direct offtake agreements with crushing operators. The USDA National Organic Program governs certification and import eligibility for domestic production. Iowa and Illinois facility clusters reduce contamination risk through dedicated organic handling infrastructure.
Brazil
Certified organic cooperatives in Mato Grosso and Paraná supply export origination for European crushing terminals. Brazilian operators deploy satellite mapping partnerships to satisfy EU deforestation-free geolocation requirements. Port congestion at Santos and Paranaguá exposes buyers to currency fluctuation and shipment delays.
Argentina
Rosario crushing belt facilities process organic streams for EU and Asian export markets. The country's national agricultural regulator oversees organic certification alignment with EU Organic Regulation equivalence agreements. Pampas region farm cooperatives invest in traceability documentation to preserve Rotterdam and Hamburg terminal access.
India
FSSAI organic certification expansion positions Madhya Pradesh and Maharashtra farmers for European export origination. The Food Safety and Standards Authority of India aligns domestic standards with EU equivalence protocols. Central Indian processing clusters emerge as alternative origination sources amid South American supply concentration risks.
Canada
Prairie Provinces organic acreage supplies Pacific Northwest export terminals serving Asian markets. Canadian Food Inspection Agency organic regulations maintain equivalence with USDA National Organic Program standards. Saskatchewan and Manitoba elevator networks feed Vancouver and Prince Rupert container loading facilities.
Organic Soybean Market Competitive Environment
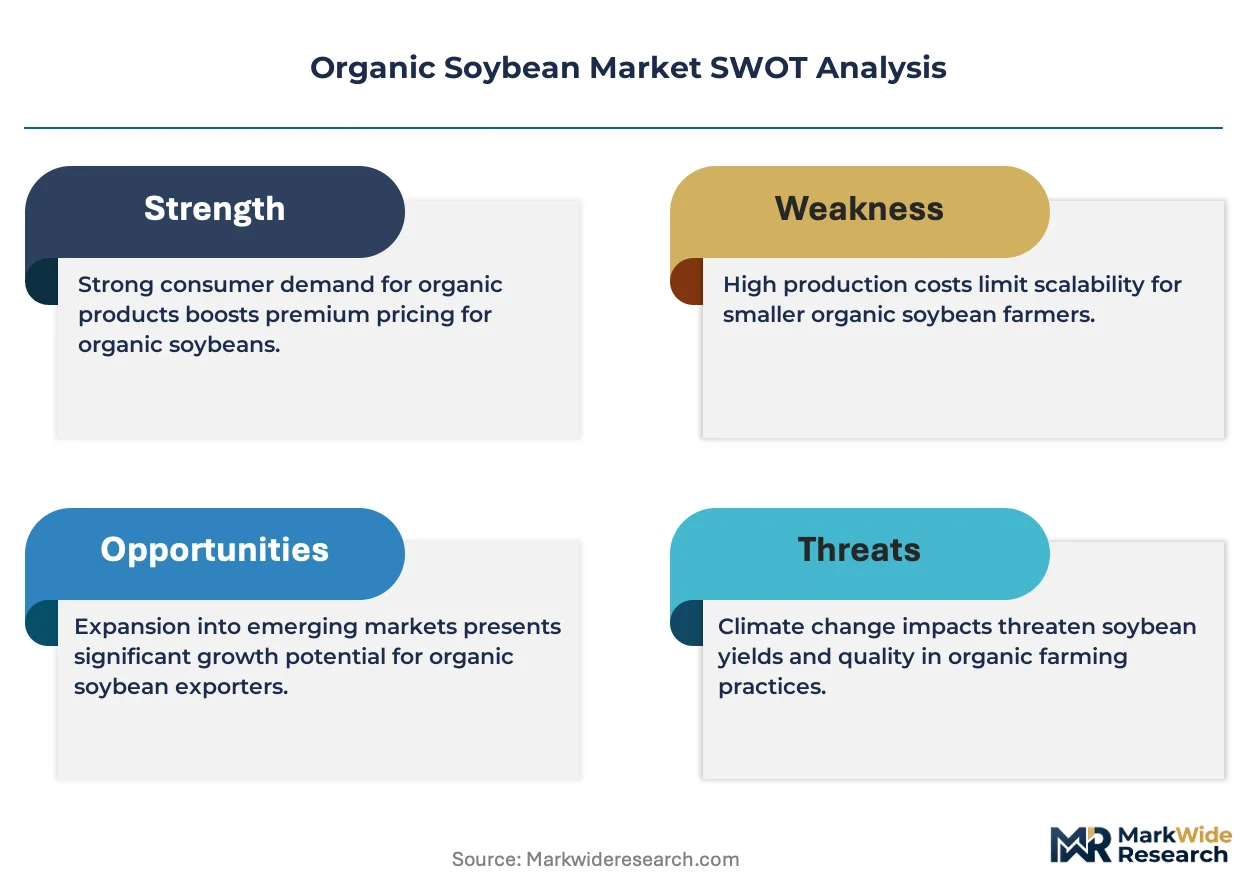
Established producers occupy the standard tier; emerging entrants pursue specialized organic handling and identity-preserved infrastructure niches. The supplier base concentrates among integrated agricultural merchants with elevator network control and dedicated organic facility operators. Three archetypes dominate: North American network-integrated merchants, South American origination specialists, and Asia-Pacific trading houses. Competitive positioning hardens through multi-year crushing commitments and satellite-enabled traceability platform deployment.
Within the network-integrated tier, Cargill Incorporated and Bunge Limited exemplify scale-driven origination and processing control. Louis Dreyfus Company occupies a position among merchants emphasizing dedicated organic handling segregation. These three entities anchor the competitive structure through elevator network leverage, cooperative partnerships, and facility specialization that prevents commingling with conventional soybean streams.
| Leading Market Players |
|---|
| Bunge Limited |
| Louis Dreyfus Company |
| Cargill Incorporated |
| SunOpta Inc. |
| CHS Inc. |
| Archer Daniels Midland |
| COFCO International |
| Grain Millers |
| Wilmar International Limited |
| Others |
Value Chain & Pricing Dynamics
Plant-based meat manufacturers' multi-year offtake agreements are compressing spot-market premiums and forcing elevator operators to choose between dedicated organic infrastructure investment and margin erosion in conventional channels.
Pricing Analysis
Input-cost pass-through from petroleum-based fertilizer substitution drives contract-based long-term offtake structures between crushing facilities and protein manufacturers. Price differentiation hinges on certification tier—USDA National Organic Program versus EU Organic Regulation equivalence—and identity-preserved handling infrastructure investment. Pricing pressure stems from South American currency fluctuation exposure at Santos and Paranaguá terminals. Food-grade protein manufacturers show lowest price sensitivity due to traceability requirements, while feed-grade buyers negotiate aggressively on ungraded deliveries.
Supply Chain Analysis
EU deforestation-free supply chain mandates are reshaping sourcing toward geolocation-verified origins in Iowa, Illinois, and Mato Grosso. Raw material dependencies center on certified organic seed stock, manure-based fertility inputs, and legume rotation acreage. Single-source vulnerability concentrates in Brazilian cooperative origination lacking satellite-tracked farm boundary documentation. Distribution runs through Pacific Northwest export terminals and Midwest processor intake points with dedicated organic silo segregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic soybean market compounds steadily as plant-based protein extrusion technology tightens the link between crushing output and specialized ingredient manufacturing.
For Market Incumbents: To counter blockchain-enabled traceability platform deployment by competitors, Cargill Incorporated and Bunge Limited should deepen backward integration into elevator network control and accelerate dedicated organic facility construction in Iowa and Illinois processing corridors. Certification investment in EU Organic Regulation equivalence agreements preserves Rotterdam and Hamburg terminal access against emerging origination rivals. For New Entrants and Emerging Players: Direct-to-processor digital procurement platforms offer the most penetrable route for bypassing traditional commodity merchant structures. Target Indian organic acreage expansion in Madhya Pradesh and Maharashtra where FSSAI certification alignment with EU standards remains underdeveloped. White-space exists in refrigerated plant-based beverage channel consolidation before mainstream retail dairy case resets mature. For Investors and Strategic Acquirers: Asymmetric upside sits with identity-preserved handling infrastructure specialists in Asia-Pacific trading corridors. Long-term viability through the projection horizon favors operators with satellite-enabled traceability platform deployment and multi-origin procurement contract execution capability. Watch EU enforcement deadlines for geolocation verification systems as the inflection indicator for South American origination viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elevator Networks | Cargill's North American infrastructure control secures identity-preserved organic stream access against cooperative competition. |
| EU Organic Regulation Equivalence Investment | Certification alignment unlocks Rotterdam and Hamburg crushing terminal eligibility for third-country suppliers. |
| Blockchain-Enabled Traceability Platform Deployment | Real-time lot tracking from farm gate to processor satisfies FSMA recordkeeping requirements for plant-based meat manufacturers. |
| Satellite Mapping Partnership Expansion | Brazilian cooperatives preserve European market access ahead of EU deforestation-free mandate enforcement deadlines. |
| Multi-Year Crushing Commitment Negotiation | Impossible Foods and Beyond Meat concentrate volume planning power with Minnesota and Indiana processing specialists. |
Study Parameters
Coverage spans North America, South America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with crushing facility operators, organic certification auditors, plant-based protein procurement directors, and elevator network managers alongside secondary validation from USDA National Organic Program filings, EU Organic Regulation equivalence agreements, FSSAI certification databases, and customs trade records. Bottom-up volume triangulation against top-down value estimates ensures cross-verification across the analysis window.
Rate-of-change decomposition separates volume growth from price movement across product type segmentation—whole beans, soy milk, tofu, and soy flour—and distribution channel tiers including supermarkets, health food stores, online retail, and farmers' markets. CAGRs derive from processor capacity utilization trends, acreage conversion timelines, and refrigerated plant-based beverage shelf-space expansion trajectories throughout the forecast period.
The model assumes a particular technology adoption path for optical sorting and automated protein analysis; alternative pathways for near-infrared spectroscopy deployment would alter the outlook. Forecasts reflect assumptions around EU deforestation-free enforcement timing and South American cooperative traceability investment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Consumer Floriculture Market