
 United States Insurtech Market | 2026-2036
United States Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
United States Insurtech Market Analytics
California's carrier licensing backlog is hardening entry barriers for new digital underwriters. Lemonade leverages proprietary AI models to sustain loss-ratio advantages in renters and homeowners lines. Root Insurance anchors its position through telematics-driven auto pricing that competes with legacy actuarial methods.
United States insurtech encompasses technology-enabled insurance distribution, underwriting, and claims processing systems that embed machine learning algorithms, API-based data aggregation, and real-time risk scoring to replace paper-bound workflows with automated policy lifecycle management. Health Insurance and Property Insurance segments dominate premium flow, while AI & Machine Learning applications capture the fastest expansion as carriers deploy natural language processing for claims triage. The Direct-to-Consumer delivery model occupies margin-rich customer relationships, though Broker-Based channels control complex commercial placements that resist full digitization.
National Association of Insurance Commissioners standards intersect with state-level DOI rate filings to shape product approval timelines and capital reserve requirements. HIPAA provisions govern health data exchange protocols, while SEC disclosure rules apply to publicly traded insurtech entities. Stakeholders must monitor evolving state-by-state regulatory fragmentation as a determinant of platform scalability and compliance architecture investment.
Market Dynamics
API-based data aggregation is compressing policy issuance cycles from weeks to minutes, forcing legacy carriers to rebuild core systems or cede small commercial lines to algorithm-native competitors. This infrastructure shift is concentrating premium flow toward platforms that embed real-time risk scoring at the point of sale.
Growth Catalysts
- NAIC Model Laws:Standardized licensing frameworks reduce state-by-state compliance friction for multi-state digital underwriters, accelerating platform expansion.
- Telematics:Usage-based auto pricing captures granular driving behavior data that traditional actuarial tables cannot replicate, pulling risk selection toward data-rich entrants.
- Texas and Florida:Catastrophe coverage gaps in homeowners markets drive policyholder switching toward platforms with faster claims settlement workflows.
Market Restraints
- California DOI Backlog:Extended carrier licensing queues harden entry barriers for new digital underwriters seeking admission in the largest state market.
- Capital Reserve Requirements:State-level statutory reserves for property-catastrophe lines tie up balance sheet capacity that algorithmic pricing models alone cannot reduce.
- Legacy Core Systems:Mainframe-dependent incumbents face integration friction when embedding machine learning modules into decades-old policy administration platforms.
Strategic Opportunities
- Small Commercial Lines:Underpenetrated general liability and workers compensation segments for businesses under 50 employees resist full digitization, leaving white space for API-first distribution.
- Embedded Insurance:Point-of-sale integration with property management software and auto financing platforms captures customers at transaction moments before traditional broker engagement.
- HIPAA-Compliant Health Data Exchange:Standardized protocols for electronic health record integration enable automated underwriting in supplemental health and short-term disability lines.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals who bridge traditional reserving methodologies with machine learning model governance complicates risk management function staffing.
- Model Validation Standards:State insurance departments lack uniform frameworks for reviewing AI-driven pricing algorithms, creating approval timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Insurtech Market |
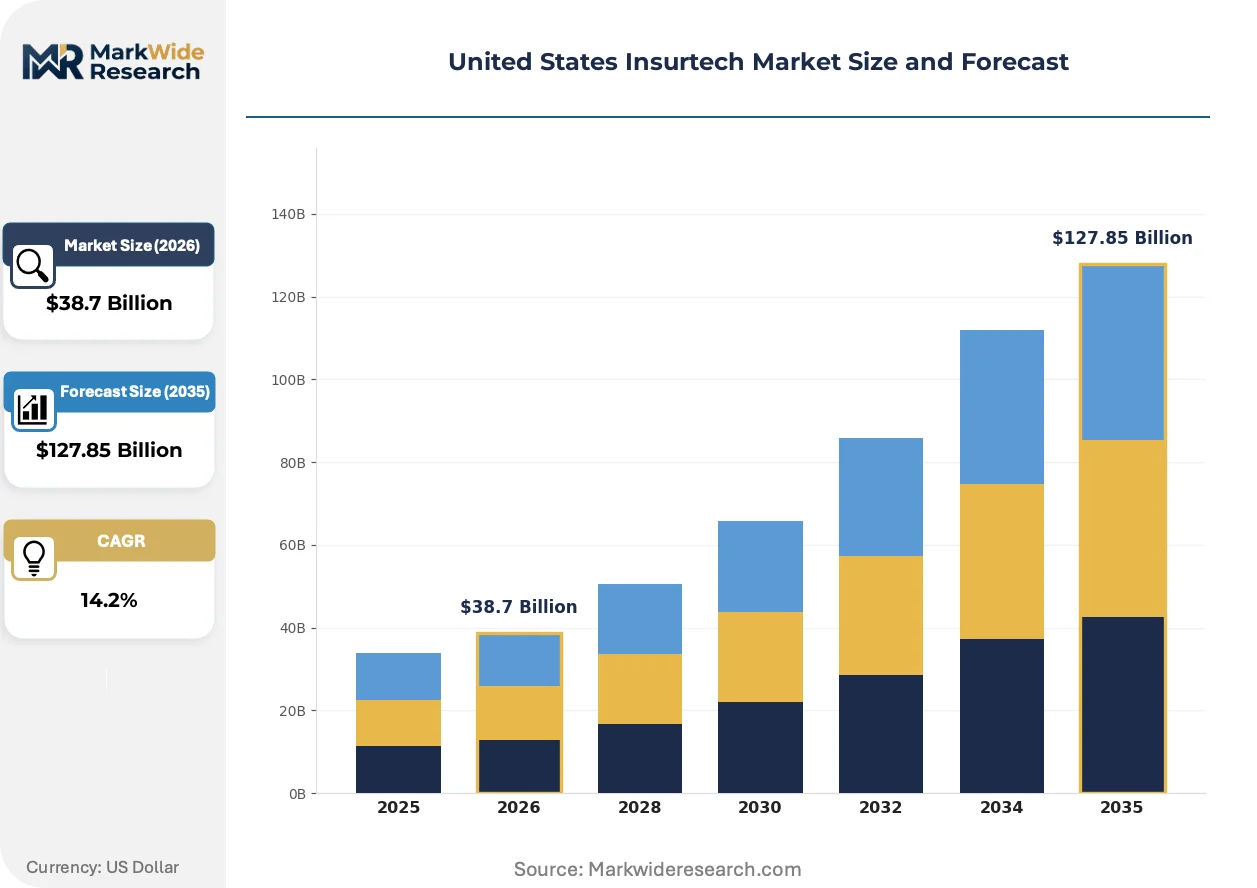
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Casualty Insurance Delivery Model: Direct-to-Consumer, Agent-Based, Broker-Based, Hybrid End User: Individual Policyholders, Small Businesses, Enterprises, Startups Technology: AI & Machine Learning, Blockchain, Telematics, Cloud Computing |
| Companies Covered | Lemonade, Root Insurance, Oscar Health, Hippo, Next Insurance, Clover Health, Bright Health, Kin Insurance, Policygenius, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Insurtech Market Evolving Landscape
Natural language processing is compressing claims settlement cycles while embedded distribution models capture customers at point-of-transaction moments. These shifts are reallocating premium flow toward technology-native carriers and away from traditional agent channels.
Computer vision algorithms trained on property imagery are automating roof-condition assessments and damage estimation for homeowners claims. Regional carriers in hail-prone Midwestern states are adopting these tools fastest, cutting adjuster dispatch costs and compressing initial reserve setting from days to hours. This capability is automating the routine claims triage that previously required human field inspection.
SEC disclosure requirements for publicly traded insurtech entities are mandating granular reporting of customer acquisition costs and retention metrics. This transparency pressure is forcing platform operators to demonstrate unit economics clarity that private competitors need not match. The direct-to-consumer segment faces the heaviest compliance burden as it seeks public capital access.
Policyholders in catastrophe-exposed coastal counties are compressing their carrier switching cycles, evaluating platforms on claims payment speed rather than premium alone. This behavior shift elevates operational excellence in loss adjustment over price competition in retention economics. Florida and Louisiana homeowners markets exhibit this pattern most acutely, with digital-native carriers capturing disproportionate switching volume.
United States Insurtech Market Segmentation
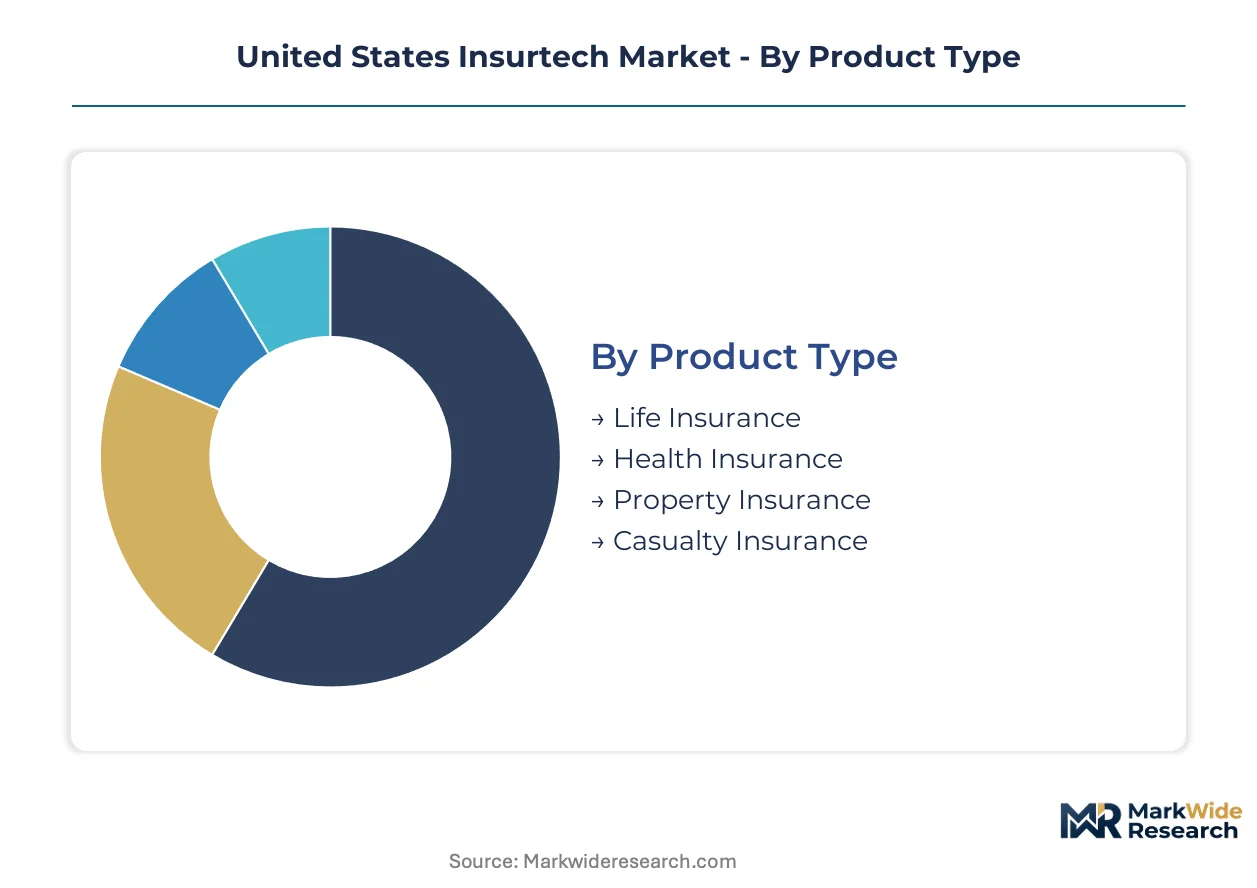
Insurtech segmentation reveals how technology deployment varies by risk complexity and buyer sophistication. Product type determines regulatory capital requirements while delivery model shapes customer acquisition economics. Understanding these dimensions clarifies where automation delivers competitive advantage versus where human intermediation retains value.
Product Type:
Buyer risk tolerance and regulatory capital intensity drive product selection decisions across personal and commercial lines.
- Health Insurance:HIPAA-governed electronic health record integration enables automated underwriting for supplemental and short-term disability products. Demand concentrates among individual policyholders in states with limited Medicaid expansion where exchange platforms capture switching volume.
- Property Insurance:Computer vision algorithms trained on aerial imagery automate roof-condition assessments and damage estimation. Texas and Florida homeowners markets exhibit the steepest platform switching as catastrophe coverage gaps drive evaluation of claims settlement speed over premium alone.
- Life Insurance:Simplified issue products leverage prescription history and electronic medical records for accelerated underwriting without paramedical exams.
- Casualty Insurance:General liability and workers compensation lines for small commercial accounts resist full digitization due to classification complexity and audit requirements.
Health Insurance leads on scale; Property Insurance leads on momentum.
Delivery Model:
Customer acquisition cost structures and relationship complexity determine channel viability for different risk segments.
- Direct-to-Consumer:Digital-native platforms capture margin-rich personal lines relationships through mobile-first policy lifecycle management. SEC disclosure requirements for publicly traded entities mandate granular customer acquisition cost reporting that private competitors need not match.
- Broker-Based:Complex commercial placements requiring coverage coordination across multiple carriers resist full automation. Small businesses under 50 employees remain underpenetrated, leaving white space for API-first distribution platforms.
- Agent-Based:Captive and independent agent networks retain strength in Medicare Advantage and final expense life products where demographic factors favor face-to-face consultation.
- Hybrid:Blended models combine digital self-service for routine transactions with human intervention for claims disputes and coverage reviews.
Direct-to-Consumer dominates premium efficiency; Broker-Based controls commercial complexity.
End User:
Organizational scale dictates policy administration sophistication and risk transfer structuring needs.
- Individual Policyholders:Renters and auto insurance buyers exhibit highest platform switching velocity as price transparency tools compress loyalty cycles.
- Small Businesses:General liability and workers compensation purchasing for firms under 50 employees concentrates in digital channels that compress quote-to-bind timelines from weeks to minutes.
- Enterprises:Fortune 1000 risk managers require structured captive programs and multinational coverage coordination that resists algorithmic placement.
- Startups:Venture-backed technology firms prioritize directors and officers coverage with venture-specific exclusions and side-A only capacity.
Individual Policyholders drive transaction volume; Small Businesses offer the steepest expansion trajectory.
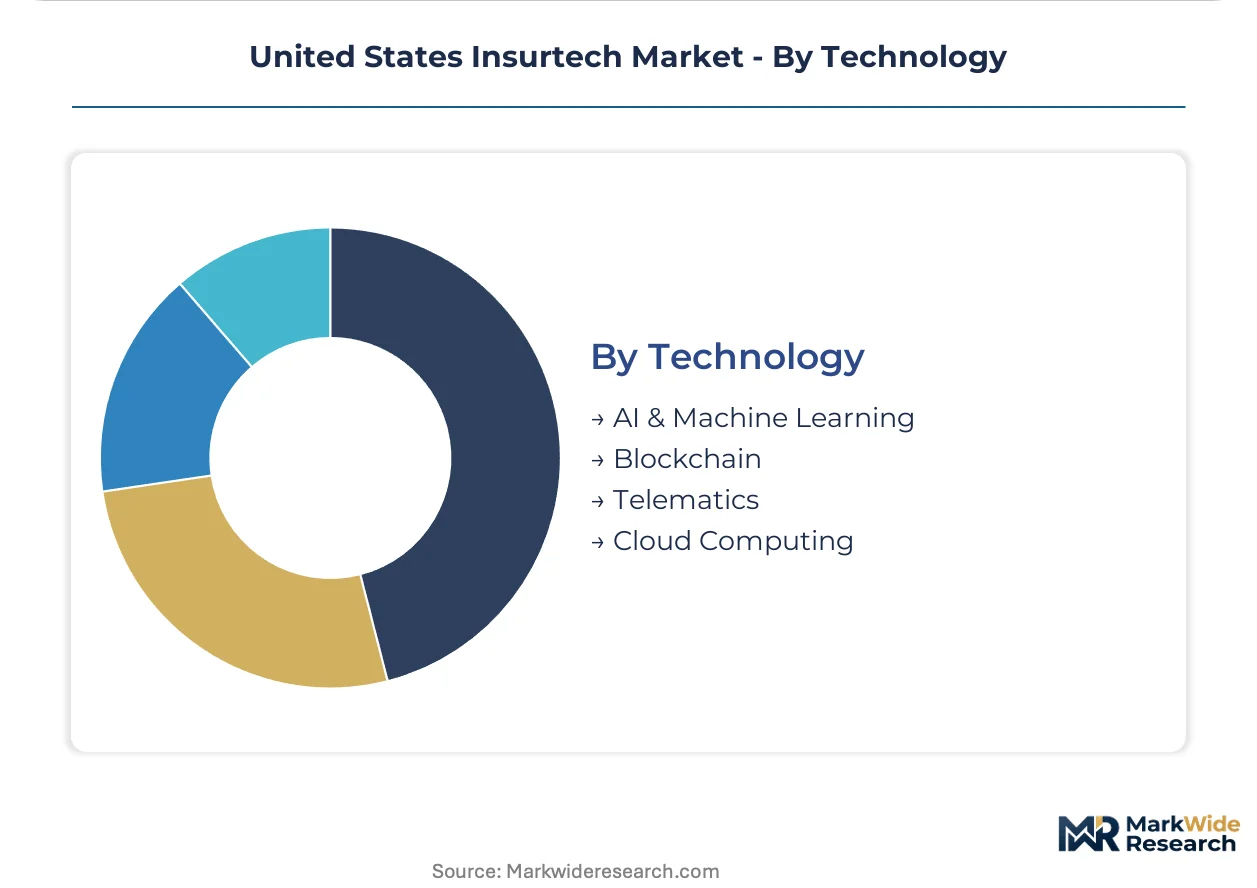
Technology:
Infrastructure investment priorities reflect competitive pressure points across underwriting, distribution, and claims functions.
- AI & Machine Learning:Natural language processing compresses claims settlement cycles while predictive models refine risk selection. State insurance departments lack uniform validation frameworks for algorithmic pricing, creating approval timeline uncertainty.
- Telematics:Usage-based auto pricing captures granular driving behavior data that traditional actuarial tables cannot replicate. Root Insurance anchors market position through smartphone-based data collection competing with legacy actuarial methods.
- Cloud Computing:API-based core system replacement enables real-time risk scoring at point of sale, forcing mainframe-dependent incumbents into expensive migration programs.
- Blockchain:Smart contract applications for parametric catastrophe coverage remain experimental with limited production deployment beyond pilot programs.
AI & Machine Learning commands the largest investment share; Telematics delivers the most measurable underwriting improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate insurtech formation in states with streamlined licensing frameworks while capital reserve requirements and catastrophe exposure push operational scale toward jurisdictions with favorable balance sheet treatment. Texas and Florida emerge as formation hubs where coverage gaps accelerate platform switching.
California
California's Department of Insurance licensing backlog stretches admission timelines for new digital underwriters, hardening entry barriers despite the state's massive premium pool. HIPAA provisions govern health data exchange protocols for Oscar Health and Clover Health operations targeting individual exchange markets. The San Francisco Bay Area anchors venture capital formation for property-catastrophe modeling startups serving national carriers.
Texas
Texas homeowners markets exhibit the steepest platform switching velocity as catastrophe coverage gaps drive evaluation of claims settlement speed over premium competitiveness alone. State-level statutory reserve requirements for windstorm lines remain below Florida thresholds, attracting Kin Insurance and Hippo to domicile underwriting operations. The Dallas-Fort Worth metroplex clusters telematics engineering talent for usage-based auto pricing development.
Florida
Florida's Citizens Property Insurance Corporation residual market expansion creates displacement volume that digital-native carriers capture through faster claims workflows. State Farm and Allstate retrenchment from coastal counties accelerates policyholder migration toward algorithmic underwriters with computer vision damage assessment capabilities. The Miami-Dade corridor concentrates insurtech customer service operations serving Latin American diaspora markets.
New York
New York's Department of Financial Services cybersecurity regulations impose compliance architecture costs that filter out undercapitalized entrants while rewarding platforms with enterprise-grade infrastructure. Policygenius anchors direct-to-consumer distribution from Manhattan, leveraging proximity to reinsurance brokerages for capacity placement. The state's limited Medicaid expansion concentrates individual health insurance demand on exchange platforms.
Illinois
Illinois regulatory frameworks for captive insurance company formation attract enterprise risk managers seeking alternative risk transfer structures for Fortune 1000 programs. Root Insurance maintains Midwest operational presence for telematics data science recruitment from University of Illinois engineering pipelines. Chicago's legacy insurance exchange infrastructure supports algorithmic trading platform development for commercial lines placement.
United States Insurtech Market Competitive Landscape
California-based platforms anchor the direct-to-consumer tier; Texas and Florida specialists hold catastrophe-exposed property lines. The market structure fragments across three operational layers: venture-backed full-stack carriers, managing general agent intermediaries, and embedded distribution enablers. Strategic archetypes include AI-native underwriters, API-first distributors, and legacy carrier digital subsidiaries. Dominant competitive moves center on M&A for talent acquisition and state-by-state licensing expansion.
Within the full-stack carrier archetype, Lemonade, Root Insurance, and Oscar Health exemplify divergent specialization strategies. Lemonade occupies a position in renters and homeowners lines where proprietary AI models sustain loss-ratio positioning. Root Insurance anchors usage-based auto pricing through smartphone telematics data collection competing with legacy actuarial methodologies. Oscar Health sits within the individual health exchange segment where electronic health record integration enables automated underwriting workflows.
| Leading Market Players |
|---|
| Lemonade |
| Root Insurance |
| Oscar Health |
| Hippo |
| Next Insurance |
| Clover Health |
| Bright Health |
| Kin Insurance |
| Policygenius |
| Others |
Value Network & Pricing Analysis
Captive in-house AI development for underwriting algorithms anchors both supply position and pricing power for full-stack carriers, creating cost structures that algorithm-native entrants exploit against legacy mainframe-dependent competitors. This integration choice compresses policy issuance cycles while sustaining loss-ratio advantages that translate into competitive premium positioning.
Pricing Analysis
Direct-to-consumer channels capture margin-rich personal lines relationships through mobile-first policy lifecycle management, while broker-based intermediaries command higher acquisition costs for complex commercial placements. Pricing stratifies across algorithmic efficiency tiers, with telematics-enabled auto products and AI-triaged homeowners claims commanding premium positioning over legacy actuarial methods. Cost compression in small commercial lines intensifies as API-first distributors compress quote-to-bind timelines, eroding incumbent agent commissions. Small businesses under 50 employees exhibit highest price sensitivity, while enterprise risk managers prioritize claims settlement speed over premium competitiveness.
Supply Chain Analysis
Direct-to-OEM embedded insurance channels handle transaction-moment customer capture through property management software and auto financing platform integrations. Core technology inputs draw from cloud infrastructure providers, telematics device manufacturers, and natural language processing API vendors concentrated in California, Texas, and Washington state. Single-source vulnerability persists in proprietary AI model training data sets and state-by-state regulatory compliance architecture. Distribution runs through API-based aggregator networks, mobile-native carrier platforms, and hybrid digital-agent intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States insurtech market compounds steadily as catastrophe coverage gaps in coastal states perpetuate policyholder switching toward faster claims settlement platforms.
For Market Incumbents: Hedge telematics-driven auto pricing erosion by acquiring smartphone-based data collection capabilities or partnering with IoT device manufacturers. Defend homeowners market share in Florida and Texas through computer vision damage assessment deployment that matches digital-native settlement speeds. Prioritize API-first core system replacement over incremental mainframe modernization to reduce integration friction with machine learning modules. For New Entrants and Emerging Players: Enter via small commercial general liability and workers compensation segments for businesses under 50 employees, where classification complexity has resisted full digitization and incumbent agent networks retain control. Target Texas and Florida homeowners markets where catastrophe coverage gaps drive platform switching velocity unmatched by price competition alone. Pursue embedded distribution partnerships with property management software and auto financing platforms to capture customers at transaction moments before traditional broker engagement. For Investors and Strategic Acquirers: Consolidation pressure builds where state-by-state licensing fragmentation creates compliance scale advantages for multi-state platforms. Frame long-term viability around regulatory technology infrastructure that reduces admission timeline uncertainty across jurisdictions. Target managing general agent intermediaries with established carrier appointments and API-first distribution capabilities. Monitor NAIC model law adoption velocity as inflection indicator for platform scalability investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core System Replacement | Enables real-time risk scoring at point of sale, forcing mainframe-dependent incumbents into expensive migration programs. |
| Telematics Data Partnership | Captures granular driving behavior that traditional actuarial tables cannot replicate, pulling auto risk selection toward data-rich entrants. |
| Computer Vision Claims Deployment | Automates roof-condition assessments and damage estimation, cutting adjuster dispatch costs in hail-prone Midwestern states. |
| Embedded Insurance Integration | Captures customers at transaction moments through property management software and auto financing platform partnerships. |
| Multi-State Licensing Expansion | Reduces state-by-state compliance friction through NAIC model law adoption, accelerating platform scalability. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down technology deployment tracking forms the analytical core of this study. Primary interviews with insurtech CEOs, chief risk officers, state insurance department examiners, and reinsurance broker placement specialists combined with secondary validation from NAIC model law filings, SEC disclosure documents, and state DOI rate filing databases. Triangulation across carrier financial statements, venture capital investment databases, and platform customer acquisition metrics ensures cross-source consistency.
Historical trendline analysis of premium flow, policy issuance velocity, and claims settlement cycle compression informs the projection framework. Segmentation dimensions modeled include product type, delivery model, end-user scale, and technology infrastructure across the analysis window. CAGRs derive from algorithmic pricing adoption curves, telematics penetration rates, and regulatory compliance cost trajectories. Forecast inputs incorporate state-by-state licensing timeline variations and catastrophe exposure concentration shifts.
Inputs from carrier financial disclosures and regulatory filing databases were available through the study window; gaps in private platform unit economics introduce uncertainty bands around customer acquisition cost projections. Forecasts reflect assumptions regarding NAIC model law adoption velocity and state DOI staffing capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Asia-Pacific Insurtech Market