
 Asia-Pacific Insurtech Market | 2026-2036
Asia-Pacific Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insurtech Market Outlook
Actuarial data science talent is bifurcating the competitive landscape, with deep technical pools concentrated in Bangalore and Singapore. Policybazaar leverages its aggregator platform to control customer acquisition costs across tier-2 and tier-3 Indian cities. ZhongAn Insurance anchors its position through captive cloud infrastructure and embedded distribution within e-commerce ecosystems. Acko General Insurance differentiates via direct-to-consumer motor products with API-first policy issuance.
Insurtech denotes technology-enabled insurance distribution, underwriting, and claims processing platforms that deploy algorithmic risk scoring, real-time telematics ingestion, and automated claims adjudication to replace legacy paper-based workflows. Health Insurance platforms currently dominate premium flow as chronic disease management and outpatient coverage expand across Indonesia and Vietnam. Artificial Intelligence segments within underwriting and claims management are capturing disproportionate investment as natural language processing reduces loss-adjustment expenses. Blockchain applications in policy management remain nascent but attract pilot funding from reinsurers seeking smart-contract automation.
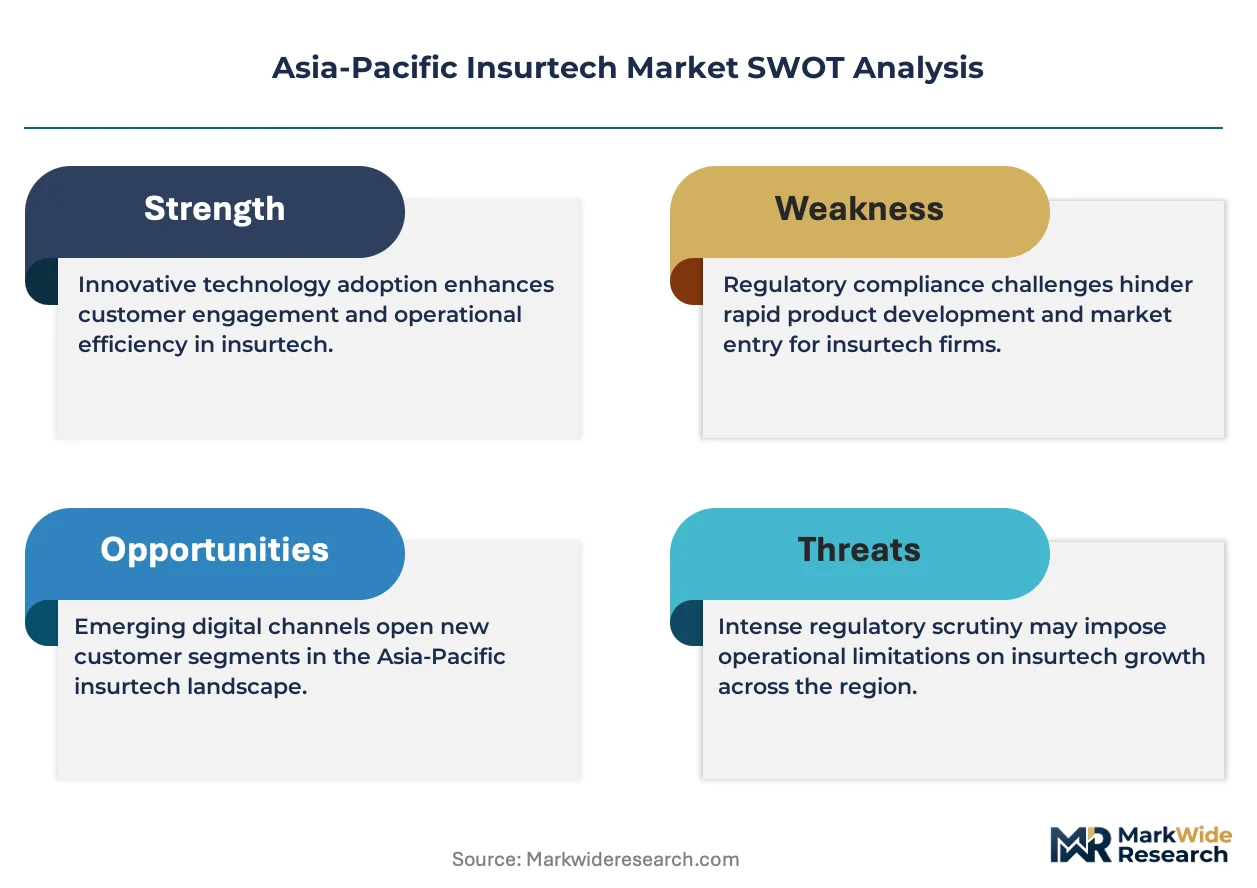
India's IRDAI, Singapore's MAS, and Australia's APRA each enforce distinct capital adequacy and consumer protection standards that shape product design and market entry pathways. India's BIS cybersecurity guidelines for financial infrastructure and Singapore's PDPA data localization requirements add compliance layers to platform architecture. Stakeholders must monitor regulatory divergence across ASEAN member states as cross-border digital passport frameworks remain unresolved.
Market Dynamics
Embedded insurance distribution through e-commerce and ride-hailing apps is collapsing traditional agent networks across Southeast Asia, forcing carriers to rebuild underwriting infrastructure around API-first policy issuance and real-time data ingestion.
Growth Catalysts
- IRDAI Sandbox Framework:India's regulatory sandbox permits controlled testing of parametric crop insurance and micro-health products, accelerating product-market fit validation for digital-first carriers in tier-2 and tier-3 cities.
- Smartphone Penetration:Mass-market mobile connectivity across Indonesia and Vietnam enables bite-sized premium collection via digital wallets, unlocking previously unreachable informal worker segments.
- Telematics Integration:Real-time driving behavior data from connected vehicles is enabling usage-based motor insurance pricing, compressing risk assessment cycles from months to seconds.
Market Restraints
- Data Localization Mandates:Singapore's PDPA and India's DPDP Act require domestic server infrastructure, inflating cloud storage costs for regional platform operators.
- Actuarial Talent Scarcity:Deep data science pools concentrate in Bangalore and Singapore, leaving carriers in Manila and Jakarta dependent on expensive expatriate hiring or outsourcing.
- Legacy Core Systems:Incumbent insurers in Thailand and Malaysia operate on decades-old policy administration platforms that resist API integration, delaying ecosystem partnerships.
Strategic Opportunities
- Parametric Agriculture:Satellite-indexed crop insurance remains underpenetrated across India's drought-prone states, with MAS-licensed reinsurers piloting automated payout triggers.
- Chronic Disease Management:Outpatient coverage platforms integrating wearable glucose monitors and blood pressure trackers are capturing employer-sponsored health segments in Vietnam.
- Cross-Border Digital Passports:ASEAN member states are negotiating mutual recognition frameworks for insurance licenses, potentially enabling single-platform distribution across multiple jurisdictions.
Industry Challenges
- Claims Fraud Detection:Synthetic identity schemes and staged accidents are proliferating on direct-to-consumer platforms, requiring continuous machine-learning model retraining.
- Interoperability Friction:Hospital information systems in Indonesia and Philippines lack standardized HL7 FHIR interfaces, blocking real-time claims adjudication for health insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insurtech Market |
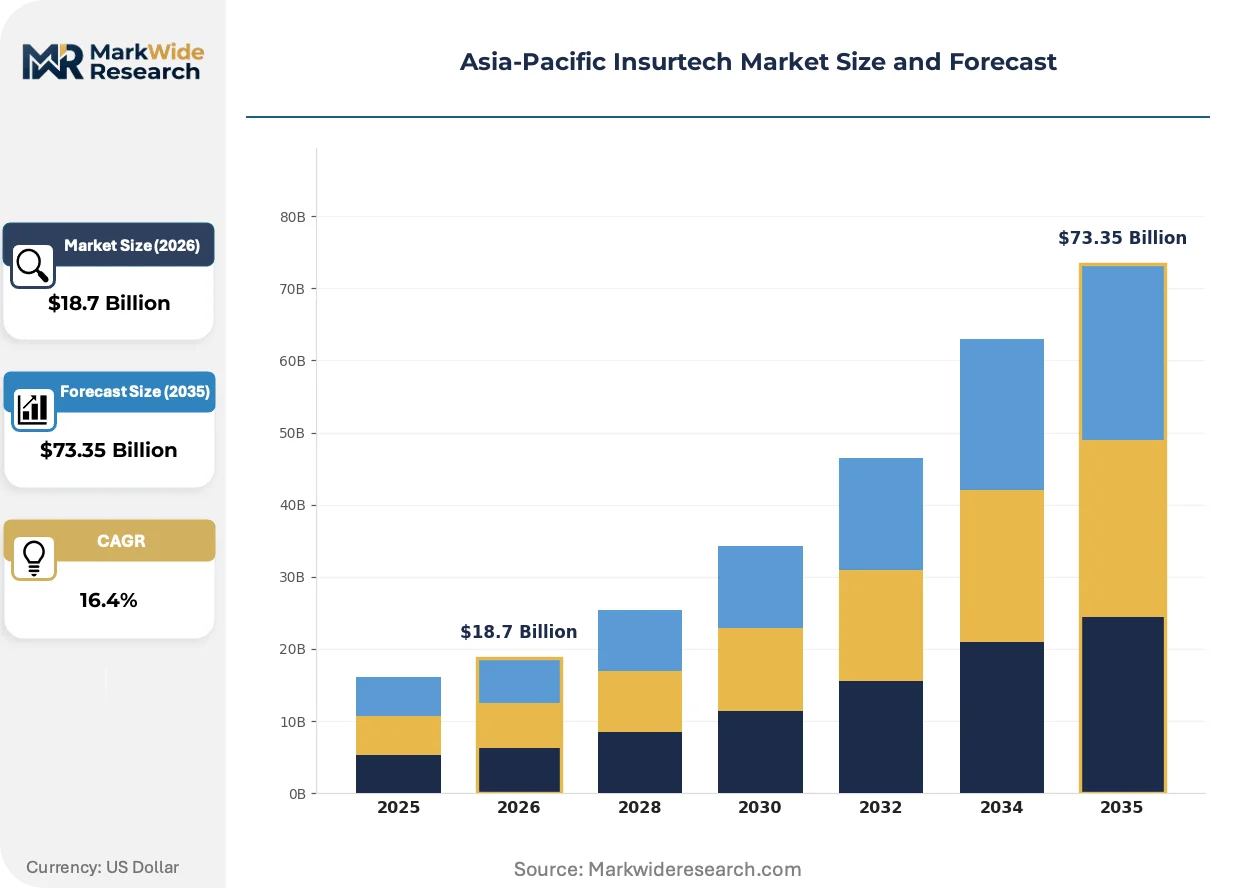
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Property Insurance, Life Insurance, Motor Insurance Technology: Blockchain, Artificial Intelligence, IoT, Big Data End User: Individuals, SMEs, Large Enterprises, Corporations Service Type: Claims Management, Underwriting, Risk Assessment, Policy Management |
| Companies Covered | ZhongAn Insurance, Policybazaar, Acko General Insurance, PasarPolis, Singlife, Bolttech, OneDegree, CXA Group, Turtlemint, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insurtech Market Strategic Shifts
Algorithmic underwriting engines are compressing policy issuance from days to minutes, while natural language processing tools are automating loss-adjustment documentation. These shifts are redrawing competitive boundaries between technology vendors and licensed carriers.
Artificial intelligence in claims adjudication is fragmenting traditional loss-adjustor roles across the region. Computer vision tools now assess vehicle damage from smartphone photos, reducing field inspection requirements. Tier-1 motor insurers in Thailand and Australia are deploying these systems at scale, compressing settlement timelines from weeks to hours and forcing independent adjustor networks into specialized catastrophe response niches.
Singapore's MAS licensing regime for digital insurers is tightening capital adequacy and business plan scrutiny, raising barriers to market entry. The framework requires demonstrated technological capabilities and sustainable unit economics before authorization. Applicants from Hong Kong and Malaysia are redirecting expansion capital toward partnership models with existing license holders rather than greenfield applications.
Aggregator platforms are capturing customer relationships that once belonged to captive agents, particularly in India's tier-2 cities. Policybazaar and similar comparison engines now originate the majority of term life and health inquiries, commoditizing carrier brands and shifting margin capture upstream. Incumbent insurers are responding by acquiring minority stakes in distribution technology providers or building proprietary direct channels.
Asia-Pacific Insurtech Market Segmentation
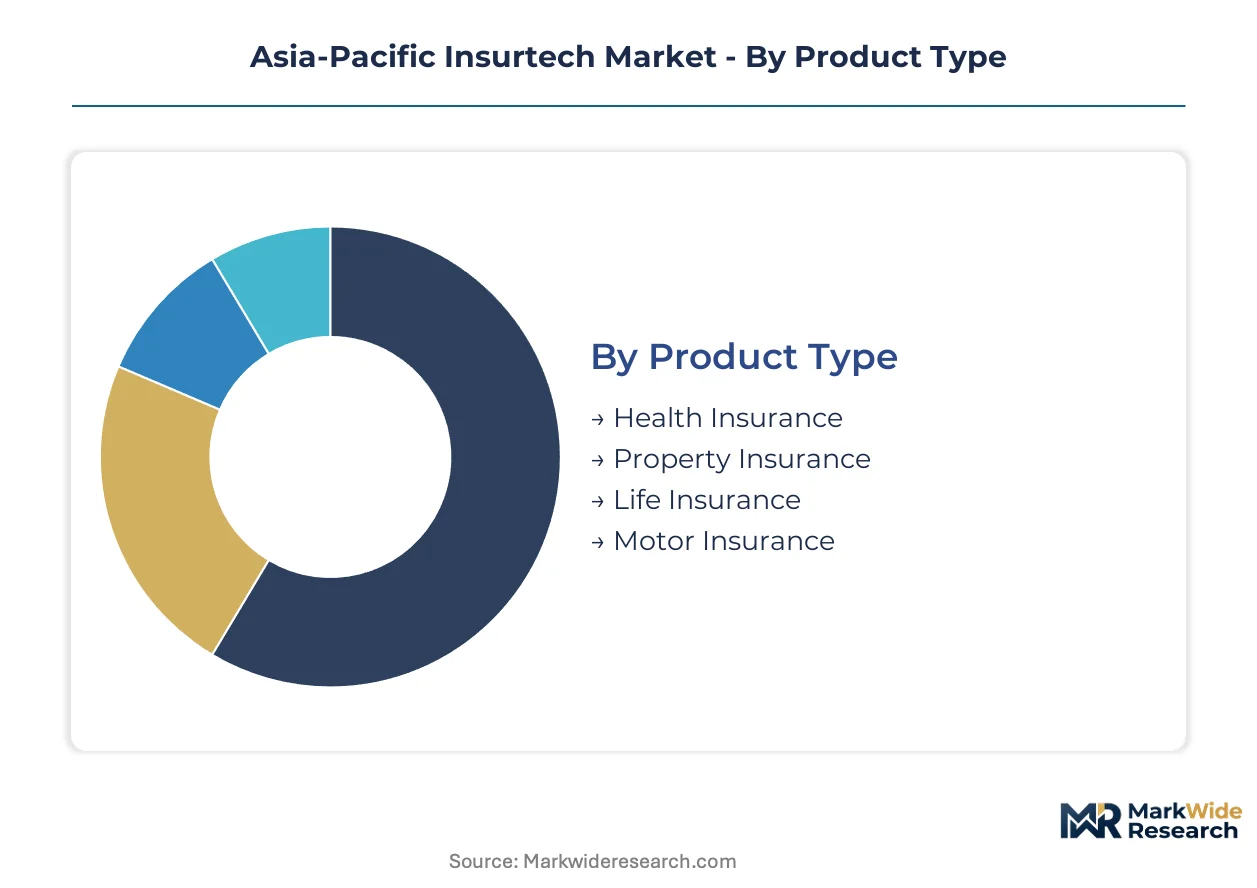
Asia-Pacific insurtech segmentation reveals how regulatory frameworks and digital infrastructure maturity create divergent growth corridors across product lines and technology stacks. Understanding these fault lines enables targeted capital deployment and partnership prioritization.
Product Type:
India's IRDAI sandbox framework and Singapore's MAS licensing regime impose distinct capital adequacy requirements that reshape product economics across each insurance vertical.
- Health Insurance:Platforms integrating outpatient coverage and chronic disease management capture employer-sponsored segments across Vietnam and Indonesia. Smartphone-enabled premium collection via UPI and digital wallets unlocks mass-market penetration in India's tier-2 and tier-3 cities where traditional agent networks underperform.
- Motor Insurance:Telematics-enabled usage-based pricing compresses risk assessment cycles from months to seconds. Thai and Australian carriers deploy computer vision for smartphone-based damage assessment, collapsing settlement timelines from weeks to hours.
- Property Insurance:Satellite-indexed parametric products address drought exposure across India's agricultural states.
- Life Insurance:Term products dominate aggregator platform flows as Policybazaar and comparable engines commoditize carrier brands.
Health Insurance handles the majority of throughput; Motor Insurance is gaining share fastest on telematics adoption.
Technology:
Cost tier differentiation separates capital-intensive infrastructure plays from lightweight application layers, with cloud storage mandates under Singapore's PDPA and India's DPDP Act inflating total cost of ownership for data-heavy segments.
- Artificial Intelligence:Natural language processing automates loss-adjustment documentation while computer vision assesses vehicle damage from smartphone photos. Investment concentrates in underwriting and claims management as carriers seek to reduce expense ratios.
- Big Data:Real-time telematics ingestion and algorithmic risk scoring enable dynamic pricing models that displace static actuarial tables. Bangalore and Singapore data science clusters supply technical talent for platform development.
- IoT:Wearable glucose monitors and blood pressure trackers feed chronic disease management platforms in employer health segments.
- Blockchain:Smart-contract automation attracts pilot funding from reinsurers seeking policy management efficiency, though production deployment remains limited.
Big Data anchors current infrastructure spend; Artificial Intelligence shows the steepest expansion trajectory on claims automation demand.
End User:
Customer type determines distribution architecture, with embedded insurance through e-commerce and ride-hailing apps collapsing traditional agent networks across Southeast Asia.
- Individuals:Direct-to-consumer platforms leverage API-first policy issuance and real-time data ingestion to serve digitally native buyers. Microinsurance products sized for informal worker budgets spread via mobile wallets across Indonesia and Vietnam.
- SMEs:Bite-sized commercial coverage packages address previously unreachable small business segments through digital distribution.
- Large Enterprises:Employer-sponsored health platforms integrate wearable monitoring for workforce risk management.
- Corporations:Customized captive arrangements and multinational policy administration require cross-border regulatory navigation.
Individuals drive volume through aggregator platforms; SMEs represent the most underpenetrated addressable base.
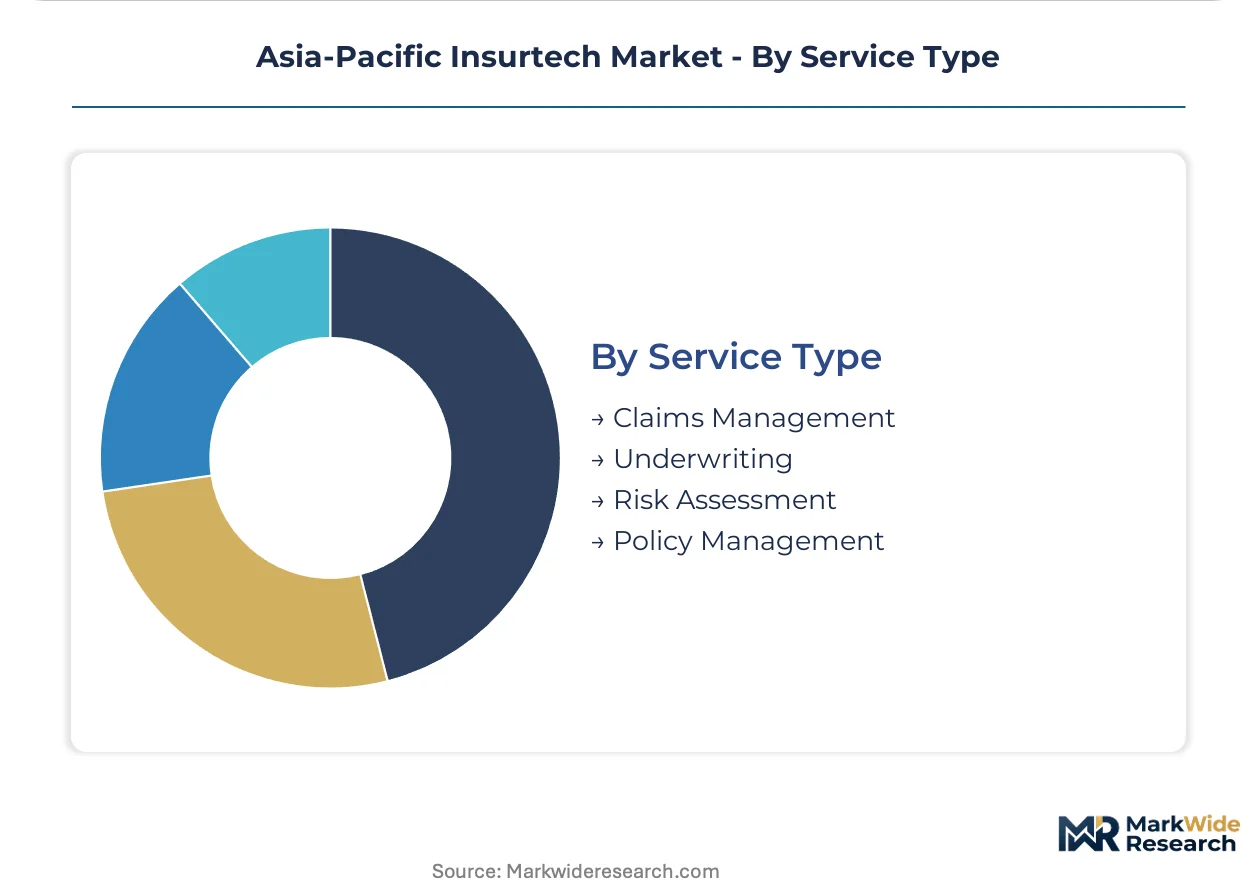
Service Type:
Maturity gradients separate established process automation from emerging cognitive capabilities, with legacy core system constraints in Thailand and Malaysia delaying ecosystem partnerships for certain workflow categories.
- Claims Management:Automated adjudication systems fragment traditional loss-adjustor roles as settlement compression forces independent networks into catastrophe response niches. Synthetic identity fraud requires continuous machine-learning model retraining.
- Underwriting:Algorithmic engines compress policy issuance from days to minutes, redrawing competitive boundaries between technology vendors and licensed carriers.
- Risk Assessment:Real-time data ingestion from connected vehicles and IoT sensors enables dynamic pricing that responds to actual behavior rather than demographic proxies.
- Policy Management:Blockchain pilots target smart-contract automation for reinsurer efficiency gains, though standardized HL7 FHIR interface gaps in Indonesian and Philippine hospital systems block real-time health claims progress.
Claims Management absorbs the largest technology investment; Underwriting is climbing fastest on algorithmic deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRDAI's sandbox framework anchors the dominant geography, enabling controlled testing of parametric crop insurance and micro-health products that accelerate product-market fit validation across India's tier-2 and tier-3 cities.
India
Smartphone penetration and UPI infrastructure enable mass-market microinsurance distribution through digital wallets. The DPDP Act mandates domestic server infrastructure, inflating cloud storage costs for platform operators. Bangalore's data science clusters supply technical talent for algorithmic underwriting engine development.
Singapore
MAS licensing regime tightens capital adequacy scrutiny for digital insurers, raising barriers to market entry. The PDPA data localization requirements add compliance layers to platform architecture. Singapore's regulatory clarity attracts regional headquarters for carriers seeking ASEAN expansion pathways.
Indonesia
Mass-market mobile connectivity enables bite-sized premium collection for informal worker segments previously unreachable by traditional agents. The country's national financial regulator shapes consumer protection standards that influence product design. Jakarta's embedded insurance partnerships with ride-hailing apps collapse conventional distribution networks.
Vietnam
Outpatient coverage platforms integrating wearable health monitors capture employer-sponsored segments. National data governance frameworks require careful navigation for cross-border platform operations. Ho Chi Minh City's chronic disease management startups leverage smartphone-enabled premium collection to reach mass-market buyers.
Australia
APRA enforces distinct capital adequacy standards that shape digital-first carrier market entry pathways. Computer vision tools for smartphone-based damage assessment compress motor insurance settlement timelines. Sydney and Melbourne carriers deploy telematics-enabled usage-based pricing at scale across connected vehicle fleets.
Asia-Pacific Insurtech Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific insurtech ecosystem. The market structure fragments across three tiers: incumbent insurers rebuilding digital infrastructure, technology-native carriers with full-stack licenses, and aggregator platforms controlling customer acquisition flows. Two dominant strategic archetypes have emerged: cloud-native insurers with captive infrastructure and API-first distributors embedding policies within e-commerce ecosystems. Competitive moves concentrate on strategic partnerships with ride-hailing and retail platforms, plus minority acquisitions of distribution technology providers by legacy carriers seeking direct channel access.
Within the aggregator tier, Policybazaar and Turtlemint occupy positions that commoditize carrier brands by originating the majority of term life and health inquiries across India's tier-2 cities. Among full-stack digital insurers, ZhongAn Insurance exemplifies the cloud-native archetype through embedded distribution within e-commerce ecosystems, while Acko General Insurance anchors the direct-to-consumer vector with API-first policy issuance. These three players represent the strategic poles—distribution control, infrastructure ownership, and direct engagement—that structure competitive dynamics across the region.
| Leading Market Players |
|---|
| ZhongAn Insurance |
| Policybazaar |
| Acko General Insurance |
| PasarPolis |
| Singlife |
| Bolttech |
| OneDegree |
| CXA Group |
| Turtlemint |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure scale economies in Singapore and India compress unit economics for digital-first carriers while erecting price floors for smaller regional entrants lacking captive server capacity. IRDAI sandbox licensing and MAS capital requirements concentrate compliance costs among full-stack insurers, pushing marginal players toward API distribution partnerships that surrender pricing control to aggregator platforms.
Pricing Analysis
Price spreads between Singapore-licensed digital insurers and India-based microinsurance distributors reflect divergent regulatory capital burdens and customer acquisition cost structures. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes by smartphone penetration depth and digital wallet usage frequency. Price differentiation rests on API integration sophistication and real-time claims settlement capability as competitive moats. Cost compression in standard-tier motor products intensifies because telematics-enabled carriers compress risk assessment overhead. Informal worker segments across Indonesia and Vietnam exhibit highest price sensitivity; employer-sponsored health platforms in Australian and Singaporean corporate segments show lowest.
Supply Chain Analysis
India and Singapore anchor cloud-native infrastructure development for algorithmic underwriting engines and automated claims adjudication systems. Bangalore data science clusters and Singapore's MAS-licensed technology hubs feed platform development with actuarial talent and regulatory clarity. Raw material dependencies include domestic server capacity under DPDP Act mandates, proprietary telematics data streams from connected vehicle fleets, and satellite imagery feeds for parametric agriculture products. Single-source vulnerability concentrates in cloud storage providers subject to data localization enforcement. Distribution runs through embedded API partnerships with e-commerce and ride-hailing applications, bypassing traditional agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific insurtech sits in early-cycle expansion as smartphone penetration and UPI infrastructure unlock mass-market microinsurance segments previously unreachable by traditional distribution. Regulatory sandbox frameworks across India and Singapore accelerate product-market fit validation for digital-first carriers.
For Market Incumbents: Secure direct channel access through minority acquisitions of aggregator technology providers, defending against Policybazaar-type platforms that commoditize carrier brands. Secure API-first policy issuance capabilities to rebuild underwriting infrastructure around real-time data ingestion, countering embedded insurance distribution that collapses traditional agent networks. Channel control represents the critical lever for margin preservation.
For New Entrants and Emerging Players: Differentiate on parametric agriculture products across India's drought-prone states, where satellite-indexed crop insurance remains underpenetrated and MAS-licensed reinsurers seek pilot partners. Differentiate through chronic disease management platforms integrating wearable glucose monitors for Vietnamese employer-sponsored health segments, the most penetrable white-space target. A go-to-market angle anchored in smartphone-enabled premium collection via digital wallets unlocks informal worker segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native insurers with captive infrastructure and demonstrated sustainable unit economics under tightening MAS licensing scrutiny. Long-term viability across the next decade hinges on regulatory compliance automation and cross-border digital passport readiness. Acquisition targets should display full-stack licensing, embedded distribution partnerships, and actuarial data science depth. The signal to watch is ASEAN mutual recognition framework progress for insurance licenses as cross-border platform expansion catalyst.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Policy Issuance | Enables real-time underwriting compression from days to minutes for motor and health products. |
| Embedded Distribution Partnership | Collapses traditional agent networks by integrating microinsurance into e-commerce and ride-hailing checkout flows. |
| Telematics Infrastructure Buildout | Feeds algorithmic risk scoring with connected vehicle behavior data for usage-based pricing models. |
| Data Localization Compliance | Satisfies Singapore PDPA and India DPDP Act server mandates while inflating cloud storage cost bases. |
| Parametric Product Development | Unlocks agricultural insurance penetration through satellite-indexed automated payout triggers. |
Study Parameters
A spread of perspectives from digital insurer CTOs, IRDAI regulatory affairs leads, aggregator platform product managers, and reinsurer innovation officers converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from IRDAI sandbox filings, MAS licensing disclosures, UPI transaction data, and ASEAN regulatory harmonization documents. Bottom-up and top-down triangulation cross-checked platform transaction volumes against carrier premium disclosures and smartphone penetration statistics.
Segmentation dimensions modeled span product type, technology stack, end-user archetype, and service workflow maturity across the projection horizon. Health insurance platforms, motor telematics products, and AI-enabled claims management each carried distinct growth assumptions based on regulatory sandbox expansion and digital wallet penetration trajectories. CAGRs were derived from algorithmic deployment rates in underwriting and claims automation, weighted by capital adequacy requirements and data localization compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained smartphone penetration growth, UPI infrastructure stability, or ASEAN regulatory convergence would require recalibration. Forecasts reflect assumptions regarding sandbox framework continuity and MAS licensing regime stringency. Recalibration cycles align with material shifts in data localization enforcement, cross-border digital passport negotiations, and telematics adoption rates in connected vehicle fleets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Insurance Automation Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Global Blockchain in Insurance Market