
 United Kingdom Payment Market | 2026-2036
United Kingdom Payment Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Payment Market Analytics
Merchant buyer concentration is consolidating across mid-market retail chains and digital-native platforms. Worldpay leverages its acquiring infrastructure to anchor volume from large-format grocers and hospitality networks. Barclays competes through embedded banking propositions that tie commercial lending to payment acceptance. Adyen N.V. differentiates via unified commerce APIs that merge online, in-store, and marketplace transactions for enterprise merchants.
The United Kingdom Payment Market encompasses electronic fund transfer systems, card networks, and digital clearing infrastructure that enable consumer and commercial value exchange. Real-time gross settlement through the Faster Payments Service processes transactions under ten seconds, while ISO 20022 messaging standardizes data formats across correspondent banking rails. Digital wallets and contactless technology adoption dominate transaction growth, with NFC-enabled point-of-sale terminals now standard across UK merchant estates. Credit and debit card payment methods sustain the largest value pools, though bank transfers gain share as open banking APIs reduce friction in account-to-account settlement.
The Financial Conduct Authority enforces Payment Services Regulations and Strong Customer Authentication under PSD2, shaping product design for issuers and acquirers. The Bank of England oversees systemic payment infrastructure resilience, while the Competition and Markets Authority scrutinizes interchange fee structures and merchant service charges. Stakeholders must monitor regulatory divergence from EU payment frameworks as the UK develops domestic equivalents to SEPA instruments and digital euro preparations.
Market Dynamics
The Faster Payments Service infrastructure and open banking APIs are compressing settlement timelines from days to seconds, forcing merchant acquirers to rebuild core processing architectures around real-time clearing rather than batch-based legacy systems.
Growth Catalysts
- PSD2 Strong Customer Authentication:Regulatory mandates for multi-factor verification have standardized security protocols, reducing fraud liability and accelerating consumer trust in digital payment channels.
- Contactless NFC terminals:Merchant estate upgrades to tap-to-pay hardware have collapsed transaction friction at physical points of sale, driving volume migration from cash and chip-and-PIN methods.
- London fintech corridor clustering:Regulatory sandboxes administered by the Financial Conduct Authority have concentrated technical talent and venture capital, spawning specialized payment infrastructure startups.
Market Restraints
- Interchange fee compression:Competition and Markets Authority scrutiny of merchant service charges is squeezing acquirer margins on card-present transactions.
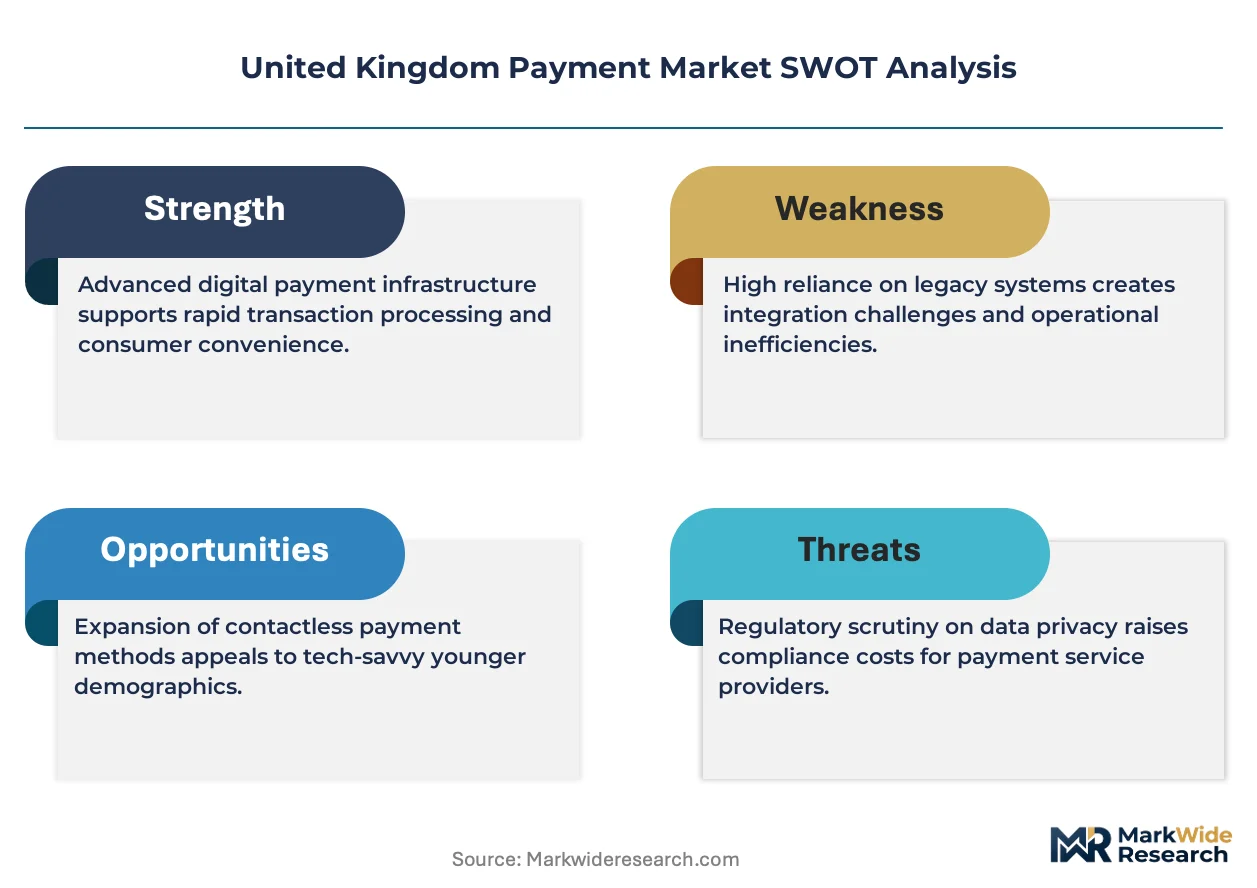
- Legacy core banking systems:Tier-one clearing banks operate on decades-old mainframe architectures that resist real-time API integration, creating technical debt.
- SEPA instrument divergence:Post-Brexit regulatory misalignment with EU payment frameworks fragments cross-border settlement standardization for UK-based merchants.
Strategic Opportunities
- Scotland and Northern England merchant penetration:Regional banking infrastructure outside London remains underdeveloped for real-time settlement, creating whitespace for specialized acquirers.
- Request-to-pay API convergence:Open banking standards enabling merchant-initiated bank transfers are merging with invoice financing workflows, displacing card rails for B2B receivables.
- ISO 20022 messaging mandate:The Bank of England's data-rich format requirements for correspondent banking are creating competitive advantage for payment service providers with advanced analytics capabilities.
Industry Challenges
- Real-time fraud detection engineering:Sub-ten-second settlement windows compress the timeframe for transaction screening, demanding machine-learning infrastructure investments that strain mid-tier acquirer balance sheets.
- API standardization fragmentation:Divergent implementation of open banking specifications across UK credit institutions forces payment service providers to maintain multiple integration codebases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Payment Market |
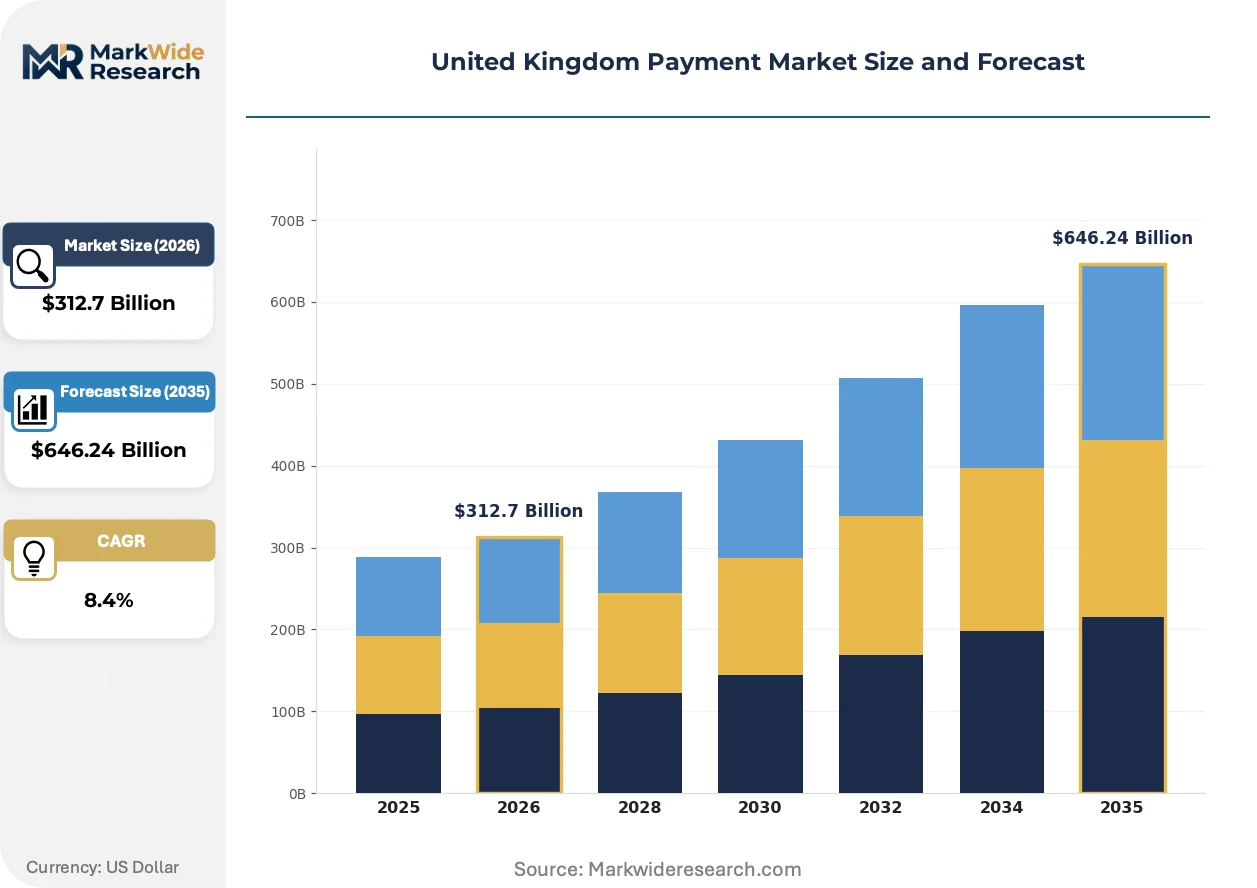
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Digital Wallets, Bank Transfers Consumer Segment: Millennials, Gen Z, Baby Boomers, Business Users Transaction Type: Online Payments, In-Store Payments, Recurring Payments, Peer-to-Peer Transfers Technology Adoption: Contactless, NFC, QR Code, Blockchain |
| Companies Covered | Worldpay, Barclays, PayPal Holdings Inc., Stripe Inc., Mastercard Incorporated, Adyen N.V., Visa Inc., Checkout.com, Lloyds Banking Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Payment Market Evolving Landscape
Payment infrastructure is fragmenting across specialized rails as merchants demand settlement velocity matched to inventory turnover cycles, compressing the dominance of card networks in favor of account-to-account alternatives.
Biometric authentication at point-of-sale is overtaking PIN entry as the primary verification layer for high-value contactless transactions. Large-format grocery and hospitality merchants are deploying fingerprint and facial recognition terminals to remove friction from checkout workflows. This shift is enabling acquirers to bypass card network authentication fees while transferring liability management to device manufacturers.
The Financial Conduct Authority's consumer duty rules are mandating transparent fee disclosure across payment product stacks. Acquirers must now itemize interchange, scheme fees, and processing margins in merchant statements, compressing opaque pricing structures. Digital-native platforms with automated reconciliation tools are capturing market share from incumbent providers with legacy billing systems.
Merchant procurement of payment acceptance is consolidating around embedded finance bundles that combine transaction processing with working capital and treasury services. Mid-market retail chains are selecting providers based on unified commerce capabilities rather than standalone acquiring rates. This pattern is most pronounced among UK hospitality networks seeking integrated reservation, payment, and inventory management from single vendors.
United Kingdom Payment Market Segmentation
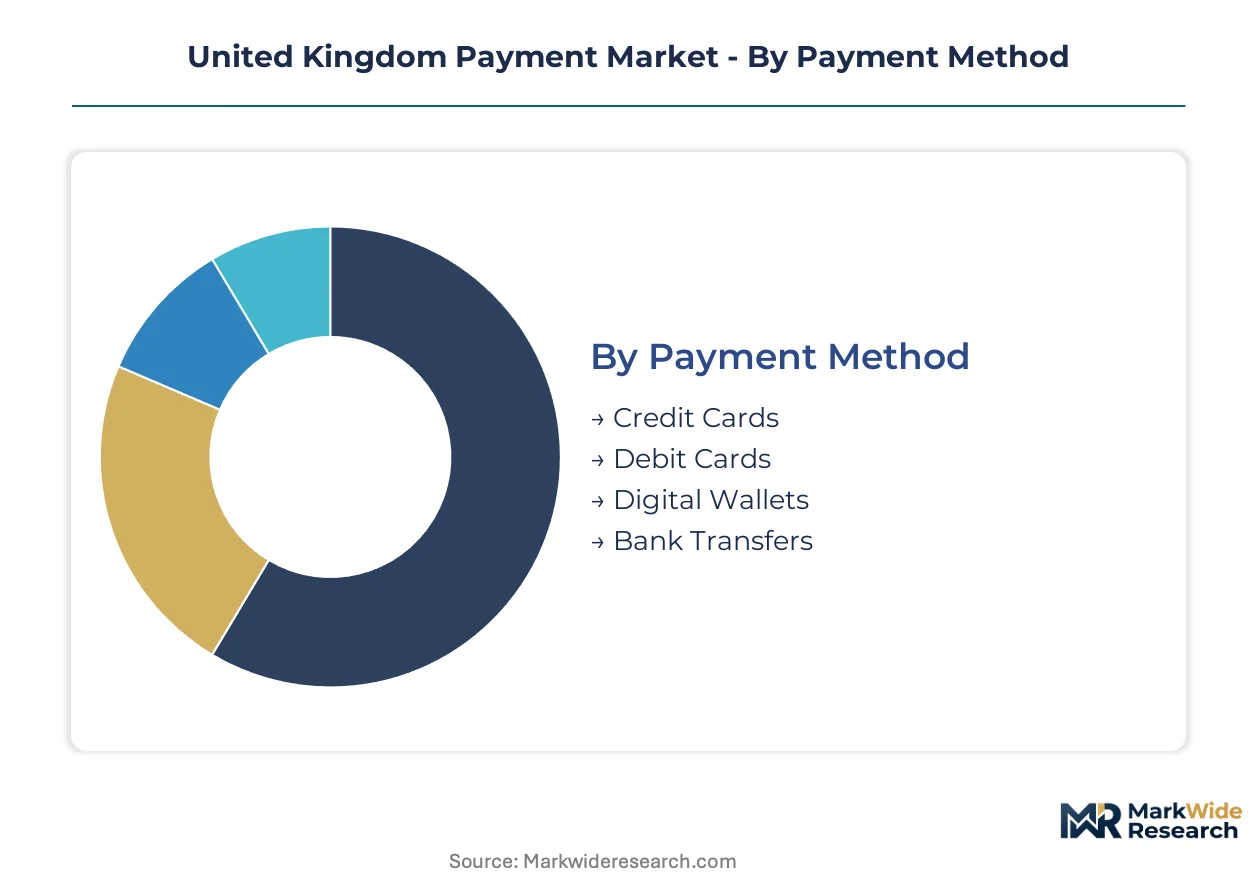
Payment infrastructure in the United Kingdom fragments across distinct technical and behavioral dimensions. Merchant acquirers and issuers must align product roadmaps with divergent settlement velocities, generational preferences, and hardware upgrade cycles.
Payment Method:
Card network dominance is eroding as Faster Payments Service rails mature and open banking APIs displace legacy clearing infrastructure.
- Credit Cards:Revolving credit instruments carry interchange premiums that sustain issuer margins. Demand concentrates among hospitality networks and premium retail chains in London's West End, where chargeback protection and rewards programs drive merchant acceptance.
- Debit Cards:Direct account-linked instruments process through Visa and Mastercard domestic schemes. Volume pools in grocery and fuel retail across England's supermarket estate, where low transaction friction supersedes credit features.
- Digital Wallets:Tokenized mobile payment credentials embed in smartphone operating systems. Apple Pay and Google Pay penetration is deepest among transit and quick-service restaurant merchants upgrading to software-based point-of-sale terminals.
- Bank Transfers:Account-to-account settlement via open banking APIs bypasses card network fees. Adoption accelerates in B2B invoice workflows and subscription billing platforms seeking to eliminate scheme charges.
Debit cards sit at the top of the volume ranking, with bank transfers climbing the fastest.
Consumer Segment:
Generational payment behavior diverges sharply across authentication tolerance, channel preference, and loyalty to incumbent banking brands.
- Millennials:Cohort aged 28-43 exhibits highest digital wallet attachment and weakest primary bank loyalty. Concentrated in London's fintech corridor and Manchester's digital economy, this segment drives demand for app-based money management and split-payment services.
- Gen Z:First fully mobile-native generation rejects physical card issuance. Demand clusters in university cities and creative industry hubs, where social commerce and embedded checkout experiences command premium merchant investment.
- Baby Boomers:Older cohort retains branch banking relationships and telephone authentication preferences. Regional banking infrastructure in Scotland and Wales sustains higher cash and cheque usage among this demographic.
- Business Users:Corporate cardholders and treasury managers prioritize spend controls and automated reconciliation. Procurement platforms and travel management companies anchor volume in this segment.
Millennials command the largest transaction value pool, though Gen Z is expanding most quickly.
Transaction Type:
Merchant infrastructure investments are bifurcating between unified commerce stacks and channel-specialized processing architectures.
- Online Payments:E-commerce checkout flows integrate fraud screening and alternative payment methods. Digital-native retailers and marketplace platforms in Birmingham and Bristol drive demand for seamless guest checkout and saved credential functionality.
- In-Store Payments:Physical point-of-sale terminals process card-present transactions with chip and contactless acceptance. Large-format grocers and hospitality networks anchor hardware refresh cycles.
- Recurring Payments:Subscription billing and utility direct debits leverage variable recurring payment mandates under open banking standards. Insurtech and SaaS providers concentrate demand.
- Peer-to-Peer Transfers:Social payment apps and banking applications enable individual-to-individual settlement. Splitting utilities and informal lending drive volume among flat-sharing demographics in urban centers.
In-store payments retain the highest absolute volume, while recurring payments gain share fastest.
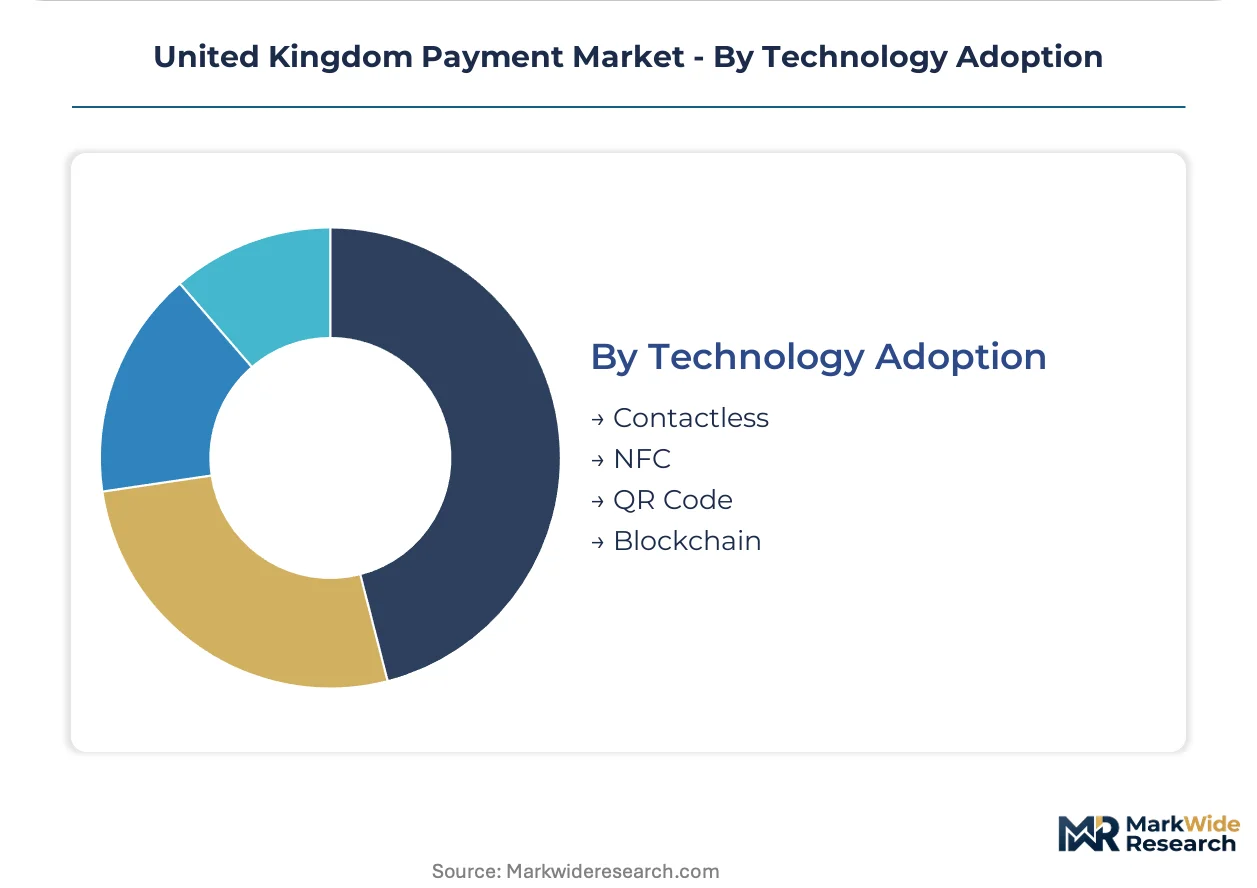
Technology Adoption:
Terminal hardware refresh cycles and mobile device penetration dictate which authentication and acceptance modalities achieve merchant scale.
- Contactless:Tap-to-pay card and device acceptance is now universal across UK merchant estates. Transport for London's fare collection system pioneered mass adoption, establishing behavioral norms that transferred to retail.
- NFC:Near-field communication enables secure element transactions within smartphones and wearables. Merchant acquirers in the hospitality sector prioritize NFC-enabled terminals to capture mobile wallet volume.
- QR Code:Optical scanning for payment initiation remains niche in consumer markets. Limited traction among small merchants and charity fundraising applications contrasts with Asian market penetration.
- Blockchain:Distributed ledger settlement for cryptocurrencies and stablecoins occupies experimental positioning. Regulatory uncertainty from the Financial Conduct Authority constrains merchant adoption.
Contactless technology sits at the top of the volume ranking, with NFC climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's fintech corridor concentrates technical talent across machine-learning engineering, regulatory compliance, and payment infrastructure architecture. This workforce density anchors the United Kingdom's position in real-time settlement innovation. Regional banking infrastructure outside the capital creates divergent adoption timelines for open banking APIs and contactless terminal penetration.
London and Southeast England
Merchant acquirers and digital wallet providers cluster around Financial Conduct Authority regulatory sandboxes in Canary Wharf and Shoreditch. The Faster Payments Service infrastructure processes peak transaction volumes through data centers in Slough and Docklands. Fintech startups compete for engineering talent against incumbent clearing banks headquartered in the Square Mile.
Midlands
Manufacturing supply chains in Birmingham and Coventry drive B2B invoice financing demand through open banking APIs. The region's automotive sector anchors corporate card volume for procurement platforms. Merchant acquirers target underpenetrated industrial estates with specialized terminals for high-value B2B transactions.
North England
Manchester's digital economy generates strong demand for app-based money management among millennial professionals. Regional banking infrastructure in Leeds and Newcastle resists real-time API integration due to legacy core systems. Specialized acquirers capture whitespace by deploying contactless terminals across hospitality networks in Liverpool and Sheffield.
Scotland
Edinburgh's asset management sector drives corporate treasury services demand for automated reconciliation tools. The country's national financial regulator enforces consumer duty rules that mandate transparent fee disclosure across payment products. Merchant acquirers in Glasgow focus on university city demographics with split-payment services for flat-sharing students.
Wales
Cardiff's public sector procurement generates recurring payment volume for subscription billing platforms. Regional cash usage persists among older demographics in Swansea and Newport. Acquirers deploy hybrid terminal estates supporting both contactless and legacy chip-and-PIN authentication.
United Kingdom Payment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across merchant acquiring and digital wallet provision. Tier-one clearing banks leverage embedded banking propositions that tie commercial lending to payment acceptance. Three strategic archetypes dominate: full-stack acquirers with unified commerce capabilities, bank-owned processors with balance sheet advantages, and API-native fintechs with developer-centric onboarding. Competitive moves concentrate on strategic partnerships with software vendors and geographic expansion into underpenetrated regional markets.
Within the full-stack acquirer tier, Worldpay and Adyen N.V. represent contrasting scale profiles. Barclays and Lloyds Banking Group plc exemplify the bank-owned processor archetype with captive deposit bases. Among API-native specialists, Stripe Inc. and Checkout.com occupy positions defined by developer experience and rapid international onboarding capabilities.
| Leading Market Players |
|---|
| Worldpay |
| Barclays |
| PayPal Holdings Inc. |
| Stripe Inc. |
| Mastercard Incorporated |
| Adyen N.V. |
| Visa Inc. |
| Checkout.com |
| Lloyds Banking Group plc |
| Others |
Value Network & Pricing Analysis
Machine-learning engineering talent concentration in London's fintech corridor widens pricing-tier spreads between premium unified-commerce bundles and commodity transaction processing, as labor-cost differentials between Tier-one clearing banks and API-native specialists reshape merchant acquisition economics.
Pricing Analysis
The bundled-vs-unbundled service split separates merchant acquirers competing on unified commerce stacks from standalone processors competing on transactional rates. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in ISO 20022 analytics capabilities, embedded finance bundling, and real-time settlement guarantees. Pricing pressure stems from Competition and Markets Authority scrutiny of interchange fee structures, compressing margins on card-present transactions. Mid-market retail chains exhibit highest price sensitivity, while enterprise hospitality networks prioritize unified capabilities over rate minimization.
Supply Chain Analysis
Regional distribution centers in Slough and Docklands anchor hub-and-spoke patterns for Faster Payments Service infrastructure, with terminal hardware flowing through specialized logistics networks to merchant estates. Core processing architectures draw from data center concentrations in Ireland, Netherlands, and domestic UK facilities. Supply chain risk centers on single-source vulnerability for NFC-enabled terminal chipsets from East Asian semiconductor foundries. Distribution runs through direct-to-merchant provisioning by acquirers and indirect channels via independent software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as merchant procurement consolidates around embedded finance bundles, with demand shifting toward premium unified-commerce specifications that merge payment acceptance with treasury and working capital services.
For Market Incumbents: Extend unified commerce capabilities into underpenetrated regional banking infrastructure in Scotland and Northern England, where legacy core systems resist real-time API integration. Build machine-learning infrastructure for sub-ten-second fraud detection to defend against API-native fintechs with cloud-native architectures. Prioritize certification investment for ISO 20022 messaging compliance to capture Bank of England correspondent banking mandates. For New Entrants and Emerging Players: PSD2 Strong Customer Authentication in the United Kingdom opens a window for biometric authentication specialists to bypass card network fees through device manufacturer partnerships. Target university city demographics in Glasgow and Manchester with split-payment services for flat-sharing students. Pursue white-label embedded finance integration with hospitality software vendors as the primary go-to-market angle. For Investors and Strategic Acquirers: Bank-owned processors with captive deposit bases are the most active acquirer in this space, consolidating specialized acquirers for unified commerce capabilities. Long-term viability hinges on regulatory divergence management as UK payment frameworks separate from EU standards. Watch for Request-to-pay API convergence with invoice financing workflows as the inflection signal for account-to-account rail displacement of card networks.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Bundle Launch | Captures mid-market hospitality networks seeking integrated reservation, payment, and inventory management from single vendors. |
| ISO 20022 Analytics Investment | Creates competitive advantage for payment service providers meeting Bank of England data-rich format requirements. |
| Regional Distribution Expansion | Addresses whitespace in Scotland and Northern England where real-time settlement infrastructure remains underdeveloped. |
| Biometric Terminal Deployment | Enables acquirers to bypass card network authentication fees while transferring liability to device manufacturers. |
| Open Banking API Convergence | Merges Request-to-pay standards with invoice financing workflows to displace card rails for B2B receivables. |
Research Methodology
Direct dialogue with merchant acquirer executives, payment infrastructure engineers, regulatory compliance officers, and hospitality procurement managers grounded qualitative insights in operational reality. Secondary validation drew from Financial Conduct Authority policy papers, Bank of England payment system reports, Competition and Markets Authority interchange fee determinations, and Faster Payments Service transaction disclosures. Bottom-up merchant adoption modeling and top-down infrastructure capacity analysis triangulated market sizing across the analysis window.
Segmented outputs by payment method, consumer demographic, transaction type, and technology adoption pattern structured the analytical framework. CAGRs derived from merchant estate upgrade cycles, open banking API penetration curves, and real-time settlement velocity benchmarks. Industry-specific inputs included contactless terminal deployment rates, embedded finance bundle attach rates, and regional banking infrastructure modernization timelines.
Revisions become necessary when regulatory divergence from EU frameworks accelerates, Faster Payments Service capacity constraints materialize, or macroeconomic conditions shift merchant working capital requirements substantially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Australia Buy Now Pay Later Services Market
Payments
Thailand Mobile Payments Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Master Recharge API Market
Payments
Denmark POS Terminals Market
Payments
Africa Mobile Money Market
Payments
Malta POS Terminal Market
Payments
Mobile Card Reader Market
Payments
Retail Point of Sale (POS) Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
Global Payments Market
Payments
Hungary POS Terminal Market
Payments
Digital Payment in Healthcare Market
Payments
Malaysia Payments Market
Payments
Japan Retail Cash Management Market
Payments
Asia-Pacific Payment Gateway Market