
 North America Insurtech Market | 2026-2036
North America Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insurtech Market Analytics
Small business commercial lines is broadening as the dominant end-use vertical for insurtech distribution platforms. Oscar Health leverages vertical integration into care delivery to differentiate its health insurance exchange products. Lemonade sustains brand strength among urban renters through AI-driven claims automation. Coalition dominates cyber insurance for mid-market enterprises by embedding risk monitoring directly into policy workflows.
Insurtech denotes technology-enabled platforms that digitize insurance distribution, underwriting, claims processing, and policy administration through cloud-native architectures, API integrations, and algorithmic risk scoring. These systems reduce acquisition costs and compress claim cycle times from weeks to minutes. Policy administration and claims management solutions capture the largest revenue pools, while blockchain-enabled smart contracts represent the fastest-growing technology segment due to parametric payout automation. Cloud-based deployment models lead adoption among P&C insurers seeking elastic infrastructure, though hybrid architectures persist at life carriers with legacy core systems.
The National Association of Insurance Commissioners coordinates state-level regulatory standards that shape product filing requirements and capital adequacy rules for insurtech carriers across the United States. Canada's Office of the Superintendent of Financial Institutions and provincial regulators enforce parallel solvency frameworks that technology entrants must navigate for market access. Stakeholders should monitor evolving state-by-state licensing reciprocity agreements and federal bank charter pathways that could reshape competitive barriers for digital-native insurers.
Market Dynamics
Digital distribution channels are compressing traditional agent networks across small business commercial lines, forcing incumbent carriers to rebuild core systems around API-first architectures while state regulators experiment with sandbox licensing frameworks.
Growth Catalysts
- State regulatory sandboxes:Arizona, North Carolina, and Vermont have enacted experimental licensing frameworks that reduce capital requirements for technology-first carriers entering property and casualty lines.
- Cloud-native core systems:Elastic infrastructure deployment enables insurtechs to scale underwriting capacity without legacy mainframe constraints during catastrophe events.
- API-enabled distribution:Embedded insurance partnerships with fintech platforms and payroll providers create direct access to small business policyholders outside traditional agency channels.
Market Restraints
- State-by-state licensing fragmentation:The National Association of Insurance Commissioners coordinates standards but lacks binding reciprocity, forcing multi-state carriers to maintain fifty separate compliance workflows.
- Legacy core system debt:Life insurers and large mutual carriers operate on decades-old policy administration platforms that resist real-time data integration with modern risk scoring engines.
- Catastrophe model opacity:Proprietary hurricane and wildfire risk algorithms from RMS and AIR Worldwide create concentration risk when multiple carriers rely on identical scenario libraries.
Strategic Opportunities
- Parametric product expansion:Blockchain-enabled smart contracts that trigger automatic payouts based on verified weather or seismic data reduce claims cycle times from weeks to minutes for agricultural and commercial property buyers.
- Texas and Florida surplus lines:Coastal property markets underserved by admitted carriers create white space for excess and surplus specialists with algorithmic pricing models.
- Canada's open banking framework:Consumer-permissioned financial data sharing enables usage-based auto and renters products with dynamic premium adjustment.
Industry Challenges
- Actuarial talent scarcity:Traditional pricing expertise remains concentrated at legacy carriers while insurtechs compete for data scientists with limited insurance domain knowledge.
- Core system integration complexity:Hybrid cloud architectures require continuous reconciliation between modern API layers and batch-processed legacy databases, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insurtech Market |
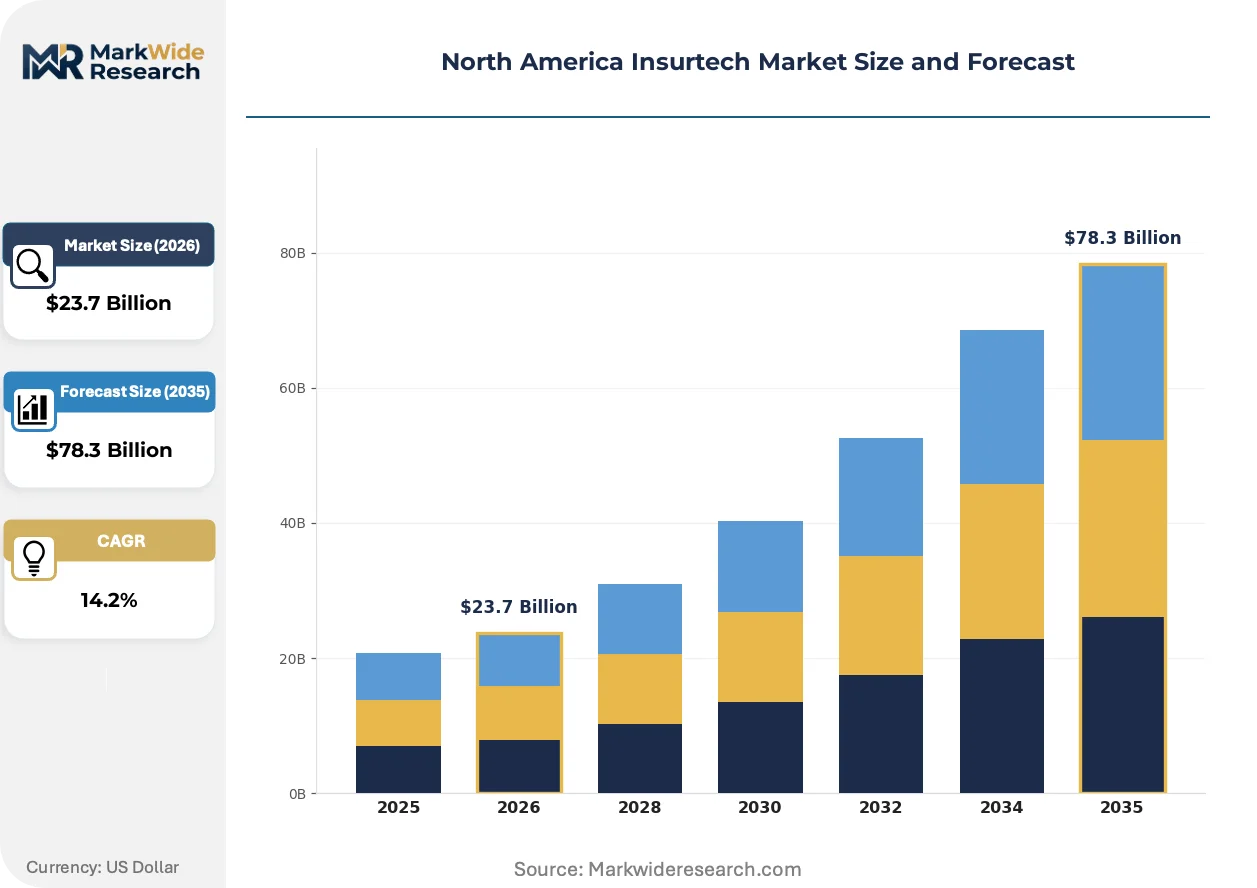
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Policy Administration, Claims Management, Risk Assessment, Customer Engagement Technology: Blockchain, AI, Machine Learning, Big Data End User: P&C Insurers, Life Insurers, Brokers, Underwriters Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile-Based |
| Companies Covered | Oscar Health, Lemonade, Root Insurance, Next Insurance, Coalition, Gusto, Bright Health, Clover Health, Pie Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insurtech Market Evolving Landscape
Algorithmic underwriting engines are compressing the traditional weeks-long policy issuance cycle into minutes, forcing carriers to rebuild data infrastructure around real-time ingestion of telematics, IoT sensors, and alternative credit signals.
Artificial intelligence is rewriting claims processing workflows across property and casualty lines. Computer vision models now assess vehicle damage and property loss from smartphone photographs without human adjuster involvement. Mid-market commercial carriers in California and Texas have deployed these systems for auto physical damage and homeowners claims. The technology is compressing loss adjustment expense ratios and enabling same-day settlement offers that previously required weeks of documentation exchange.
The National Association of Insurance Commissioners has accelerated data privacy standards that restrict carrier use of third-party consumer data in underwriting decisions. The draft model law requires explicit consent for alternative data sources and mandates algorithmic explainability for declined applications. Personal auto and homeowners segments face the steepest compliance costs as carriers audit existing pricing models for disparate impact. Several state regulators in the Northeast have indicated intent to adopt stricter versions than the national framework.
Small business buyers are abandoning annual policy cycles in favor of on-demand coverage activated by project milestones or seasonal revenue fluctuations. Construction contractors and event vendors in metropolitan Texas markets now purchase general liability in thirty-day increments through mobile applications. This consumption-pattern shift is fragmenting premium collection and forcing carriers to rebuild billing systems around micro-transaction architecture rather than traditional installment schedules.
North America Insurtech Market Segmentation
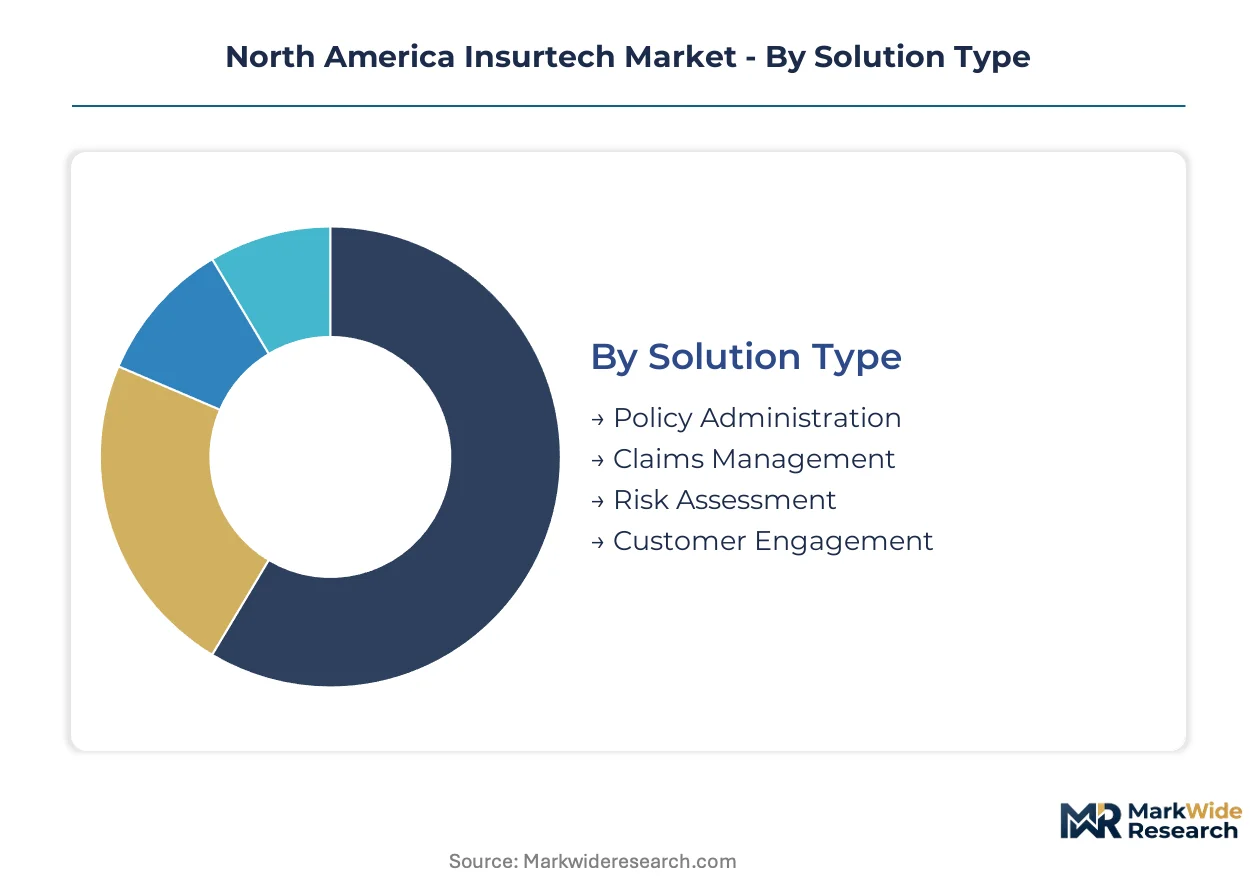
Insurtech segmentation reveals how technology investment concentrates across the insurance value chain. Solution type and deployment model decisions determine capital allocation priorities for carriers modernizing core systems.
Solution Type:
Policy administration and claims management capture the largest revenue pools, while risk assessment solutions command premium pricing for algorithmic underwriting capabilities.
- Policy Administration:Cloud-native platforms automate policy lifecycle management from quote to renewal through API-connected core systems. Demand concentrates among P&C insurers in California and Texas seeking to replace decades-old mainframe infrastructure with elastic, microservices-based architectures.
- Claims Management:AI-powered workflows compress loss adjustment cycles from weeks to hours using computer vision and natural language processing. Mid-market carriers in New York and Illinois prioritize these investments to reduce loss adjustment expense ratios and accelerate settlement velocity.
- Risk Assessment:Algorithmic scoring engines integrate telematics, IoT sensors, and alternative data for real-time underwriting decisions.
- Customer Engagement:Mobile-first portals and chatbot interfaces streamline policy servicing and reduce call center dependency for digital-native buyers.
Today's leader: Policy Administration. Tomorrow's challenger: Claims Management.
Technology:
Cost tier differentiation separates enterprise-grade AI deployments from lightweight big data implementations at regional carriers.
- AI:Deep learning models automate underwriting triage and fraud detection with minimal human intervention. Life insurers in New York and health carriers in California deploy these systems to process high application volumes during open enrollment windows.
- Machine Learning:Predictive analytics refine pricing models using historical claims patterns and external risk signals. P&C specialists in Texas leverage gradient-boosted algorithms for catastrophe-exposed property lines where traditional actuarial methods lag.
- Blockchain:Smart contracts enable parametric payouts for agricultural and commercial property coverage through automated oracle verification.
- Big Data:Data lake architectures consolidate fragmented policy and claims histories for unified customer analytics.
AI commands the largest implementation budgets. Blockchain exhibits the steepest expansion trajectory as carriers pilot parametric products.
End User:
Application patterns diverge between carriers rebuilding core systems and intermediaries seeking distribution advantages.
- P&C Insurers:Property and casualty carriers prioritize cloud migration for underwriting scalability during catastrophe events. Regional specialists in Florida and Louisiana invest heavily in exposure management platforms for hurricane and flood risk.
- Brokers:Independent agencies adopt digital quoting platforms to compete with direct-to-consumer carriers. Small commercial brokerages in Illinois and Ohio deploy these tools to serve micro-business segments below traditional carrier appetite.
- Life Insurers:Legacy carriers face acute integration challenges connecting modern engagement layers to policy administration systems dating to the 1980s.
- Underwriters:Managing general agencies and surplus lines specialists seek algorithmic pricing tools for niche or substandard risks.
P&C Insurers drive current spending. Brokers represent the fastest-growing buyer category as digital distribution displaces traditional channels.
Deployment Model:
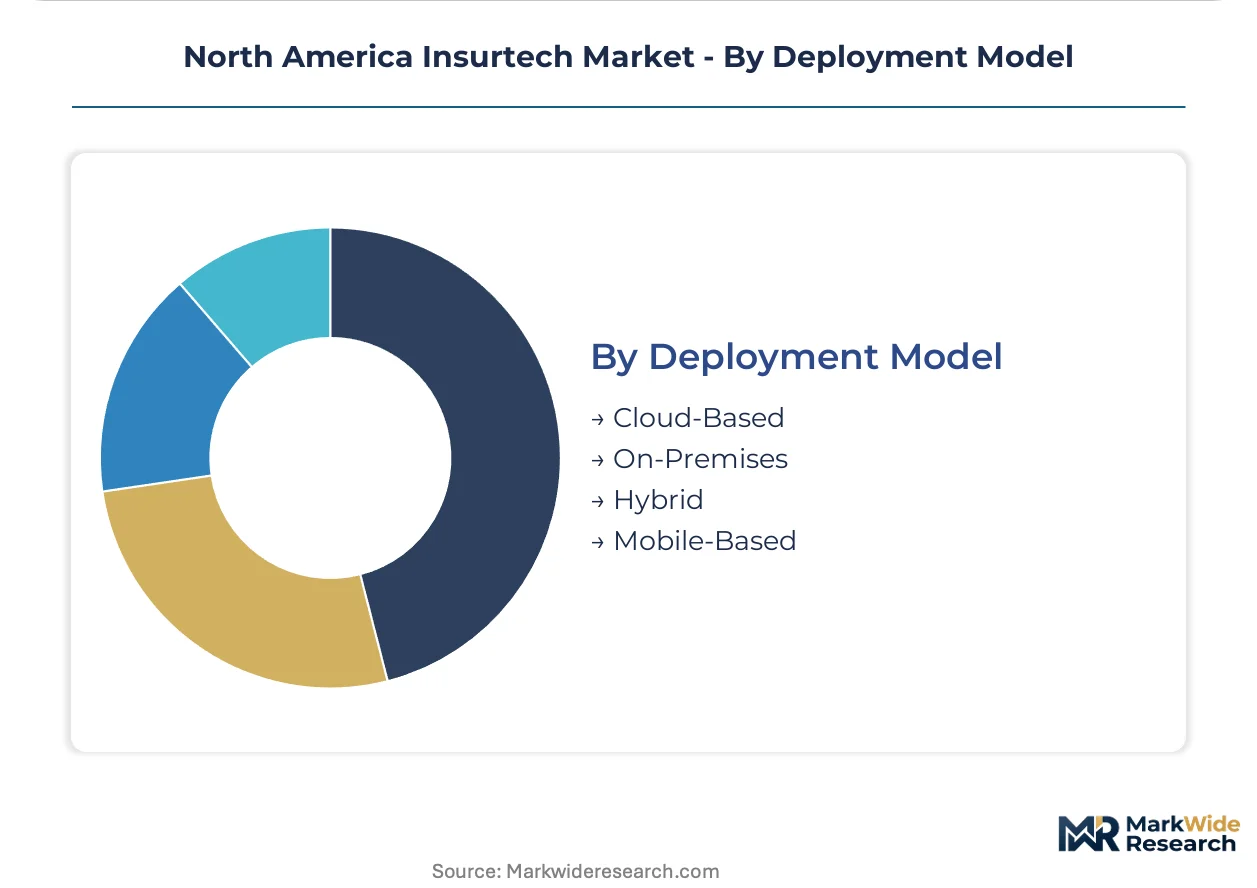
Customer type determines infrastructure choice — tech-native entrants favor cloud while mutual carriers with legacy debt require hybrid architectures.
- Cloud-Based:Fully managed SaaS platforms eliminate capital expenditure for core system replacement. Insurtech startups in Austin and San Francisco default to this model for rapid market entry without data center investment.
- Hybrid:Split architectures maintain sensitive policy data on-premises while exposing customer-facing functions through cloud APIs. Large mutual carriers in the Northeast and Midwest adopt this pattern to satisfy state regulatory data residency requirements.
- On-Premises:Self-managed installations persist at carriers with specialized compliance needs or existing data center commitments.
- Mobile-Based:Smartphone-first deployments target on-demand and micro-duration products for gig economy and seasonal workers.
Cloud-Based dominates new implementations. Hybrid architectures retain relevance for carriers navigating state-by-state regulatory fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing insurtech licensing activity toward jurisdictions with experimental frameworks and lower capital barriers, compressing formation timelines for technology-first carriers relative to traditional admitted markets.
United States
Small business commercial lines and embedded distribution partnerships with payroll platforms drive carrier formation in Texas and California. Arizona's regulatory sandbox reduces surplus lines capital requirements for property insurtechs. Austin and San Francisco anchor venture-backed startup clusters near reinsurance hubs and enterprise software talent pools.
Canada
Open banking frameworks enable usage-based auto and dynamic renters products through consumer-permissioned financial data sharing. The Office of the Superintendent of Financial Institutions coordinates solvency standards with provincial regulators. Toronto concentrates algorithmic underwriting talent alongside established P&C carrier headquarters.
Mexico
Microinsurance distribution through mobile networks targets informal workers and gig economy participants excluded from traditional agency channels. The country's national insurance regulator modernizes licensing frameworks to accommodate digital-first entrants. Mexico City anchors fintech-insurtech partnerships with payroll and ride-hailing platforms.
North America Insurtech Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer carriers commanding premium multiples in personal lines while white-label platform providers capture recurring revenue from incumbent technology migrations. The vendor base organizes around three archetypes: full-stack licensed carriers, distribution-layer intermediaries, and infrastructure-software vendors. Competitive intensity concentrates on M&A activity targeting algorithmic underwriting capabilities and strategic partnerships embedding insurance into adjacent financial workflows.
Within the full-stack carrier tier, Oscar Health and Lemonade exemplify vertical integration strategies that combine licensed underwriting with captive distribution channels. Coalition occupies a position among cyber-specialist intermediaries that embed risk monitoring into policy administration workflows. These three entities anchor distinct competitive vectors: health exchange products, AI-driven personal lines automation, and enterprise cyber risk platforms.
| Leading Market Players |
|---|
| Oscar Health |
| Lemonade |
| Root Insurance |
| Next Insurance |
| Coalition |
| Gusto |
| Bright Health |
| Clover Health |
| Pie Insurance |
| Others |
Value Network & Pricing Analysis
Actuarial data scientists concentrated in Austin and San Francisco command 40-60% compensation premiums over traditional underwriters in Hartford and Des Moines, widening spreads between algorithmic-native pricing tiers and legacy-actuarial product lines.
Pricing Analysis
Channel-margin compression in direct-to-consumer distribution eliminates traditional agent commission layers, enabling SaaS-tiered subscription models for policy administration platforms. Price differentiation rests on API integration depth and real-time claims automation capability, with enterprise buyers least sensitive and micro-businesses most price-responsive. Cost compression in the standard tier is intensifying because cloud infrastructure commoditizes core system replacement. Premium pricing persists for carriers offering embedded risk monitoring and parametric payout structures.
Supply Chain Analysis
Freight costs for on-premise hardware deployments to mutual carriers in the Midwest and Northeast inflate implementation budgets relative to cloud-native alternatives. Technology development concentrates in the United States, Canada, and Israel, with algorithmic underwriting engines drawing from reinsurance data pools, telematics streams, and alternative credit signals. Single-source vulnerability in proprietary catastrophe models from RMS and AIR Worldwide creates systemic pricing correlation risk. Distribution runs through API marketplaces, embedded fintech partnerships, and direct carrier portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive advantage, with state-level sandbox frameworks in Arizona and North Carolina accelerating licensing velocity for technology-first carriers.
For Market Incumbents: Acquire cloud-native core system assets to replace decades-old policy administration platforms. Hartford and Boston mutual carriers must integrate real-time data layers with batch-processed legacy databases or cede small commercial lines to API-first entrants. Channel control through exclusive agency networks offers temporary defense against embedded distribution partnerships.
For New Entrants and Emerging Players: Embedded payroll-platform routes unlock captive small-business policyholder access outside traditional agency channels. Texas and Florida surplus lines markets present the most penetrable white space, with coastal property risks underserved by admitted carriers. Algorithmic pricing tools for catastrophe-exposed lines offer immediate differentiation.
For Investors and Strategic Acquirers: Reinsurance carriers are the most active acquirer in this space, seeking algorithmic underwriting capabilities to enhance retrocession pricing. Long-term viability favors infrastructure-software vendors with recurring revenue from incumbent technology migrations. Watch state-by-state licensing reciprocity agreements as the signal for competitive barrier shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core System Replacement | Elastic infrastructure enables catastrophe-event scaling without mainframe constraints for P&C carriers. |
| Embedded Insurance Partnership | Payroll-platform integrations create direct small-business policyholder access outside agency channels. |
| Parametric Product Development | Blockchain-enabled smart contracts compress agricultural and commercial property claims cycles to minutes. |
| Regulatory Sandbox Licensing | Experimental frameworks in Arizona and Vermont reduce capital barriers for technology-first entrants. |
| Algorithmic Underwriting Acquisition | Deep learning models automate triage for high-volume health exchange and personal auto segments. |
Research Methodology
Multiple input streams — carrier technology executives, state insurance regulators, reinsurance pricing officers, venture capital investors — were reconciled against secondary validation from NAIC regulatory filings, state sandbox enrollment data, and SEC disclosures from publicly traded insurtech carriers. Bottom-up and top-down triangulation cross-checked platform revenue estimates against policy-in-force growth metrics and premium volume trends reported in statutory financial statements.
Data-stream reconciliation across deployment models, solution types, end-user categories, and technology tiers shaped the analytical framework. CAGRs were derived from elasticity-adjusted adoption curves and capital-formation velocity in venture-backed startup clusters. Forecast inputs included state-by-state licensing reciprocity progression, cloud infrastructure cost trajectories, and catastrophe-model licensing concentration patterns.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled parametric contracts would alter the outlook. Forecasts reflect assumptions about regulatory sandbox expansion and legacy core system replacement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Global Insurance Telematics Market