
 United States Material Handling Leasing and Financing Market | 2026-2036
United States Material Handling Leasing and Financing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Material Handling Leasing and Financing Market Analytics
E-commerce fulfillment is decoupling from traditional retail leasing patterns as automated warehouse buildouts reshape equipment procurement cycles. CIT Group Inc. leverages its captive finance structure to anchor multi-year forklift fleet contracts with national distributors. Element Fleet Management Corp competes through telematics-integrated lease products that sustain residual value predictability. Crest Capital LLC specializes in mid-market manufacturer relationships where flexible hire-purchase terms dominate capital-constrained buyers.
Material handling leasing and financing encompasses the structured provision of capital access for acquiring, operating, and returning industrial mobility equipment without full ownership transfer, typically governed by master lease agreements specifying utilization thresholds, maintenance obligations, and end-of-term residual assumptions. The primary purpose centers on converting fixed capital expenditures into operational cash flows while lessors retain title and depreciation benefits. Forklifts command the largest financing commitment volumes given their unit cost and fleet standardization, while automated guided vehicles represent the fastest-growing product type as warehouse operators pursue labor cost reduction. Operating leases capture preference from publicly traded retailers seeking off-balance-sheet treatment, whereas finance leases dominate manufacturer procurement where ownership transfer intent clarifies accounting classification.
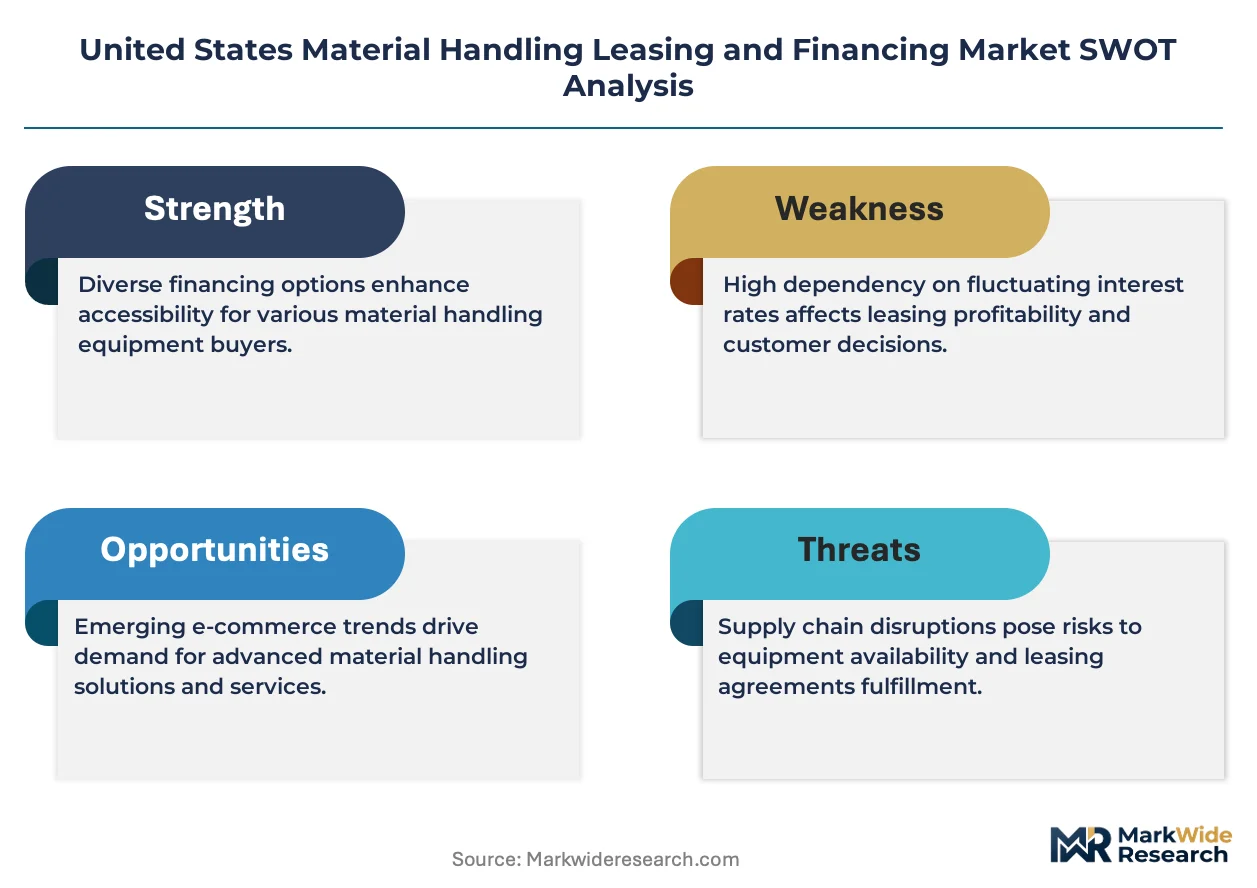
OSHA mandates equipment operator certification and workplace injury prevention protocols that directly influence lessor insurance pricing and lessee compliance documentation requirements. The EPA's Tier 4 Final emissions standards for diesel-powered forklifts restrict eligible equipment in regulated zones, compressing residual values for non-compliant units and redirecting financing toward electric alternatives. Stakeholders must monitor evolving battery technology depreciation curves and state-level zero-emission warehouse regulations to calibrate lease rate structures and end-of-term remarketing strategies.
Market Dynamics
Capital deployment patterns in material handling equipment are pivoting around warehouse automation intensity and EPA emissions compliance deadlines, forcing lessors to restructure residual value assumptions and fleet refresh cycles around electric forklift adoption curves.
Growth Catalysts
- E-commerce Fulfillment Density:Third-party logistics operators in Texas and the Great Lakes corridor are scaling automated distribution centers, generating concentrated demand for multi-year fleet leases with integrated maintenance provisions.
- OSHA Workplace Safety Mandates:Operator certification requirements and injury prevention protocols are expanding lessor service bundles to include training and compliance documentation, deepening customer stickiness.
- Electric Propulsion Transition:Lithium-ion battery systems are displacing lead-acid and internal combustion alternatives, opening lease structures that capture battery-as-a-service revenue streams alongside equipment financing.
Market Restraints
- Residual Value Compression:EPA Tier 4 Final non-compliant diesel forklifts face accelerated depreciation in regulated zones, trapping lessors with stranded inventory in California and Northeast corridor states.
- Supply Concentration Risk:Domestic forklift manufacturing concentrates in Ohio, Michigan, and Illinois, exposing lessors to regional labor disruptions and logistics bottlenecks during fleet procurement cycles.
- Interest Rate Volatility:Federal Reserve policy shifts directly transmit into lease rate pricing, compressing margins on fixed-rate contracts originated during low-rate environments.
Strategic Opportunities
- Mid-Market Manufacturer Penetration:Capital-constrained producers in Indiana and Wisconsin present untapped demand for flexible hire-purchase structures with seasonal payment adjustment clauses.
- Telematics-Integrated Pricing:Usage-based lease models leveraging real-time equipment monitoring are rewriting risk assessment frameworks and enabling dynamic rate adjustment mechanisms.
- State Zero-Emission Incentives:California's warehouse emissions regulations and New York's clean fleet mandates are creating regulatory tailwinds for electric equipment financing with accelerated depreciation schedules.
Industry Challenges
- Technician Certification Bottlenecks:Electric forklift maintenance requires specialized battery management and high-voltage systems training, constraining lessor service network expansion.
- Legacy Fleet Integration Complexity:Automated guided vehicle deployment demands interoperability with existing warehouse management systems, extending implementation timelines and inflating customer onboarding costs.
- Battery Technology Depreciation Uncertainty:Rapid advances in energy density and charging speed are obsoleting prior-generation lithium-ion assets faster than historical equipment cycles, complicating end-of-term remarketing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Material Handling Leasing and Financing Market |
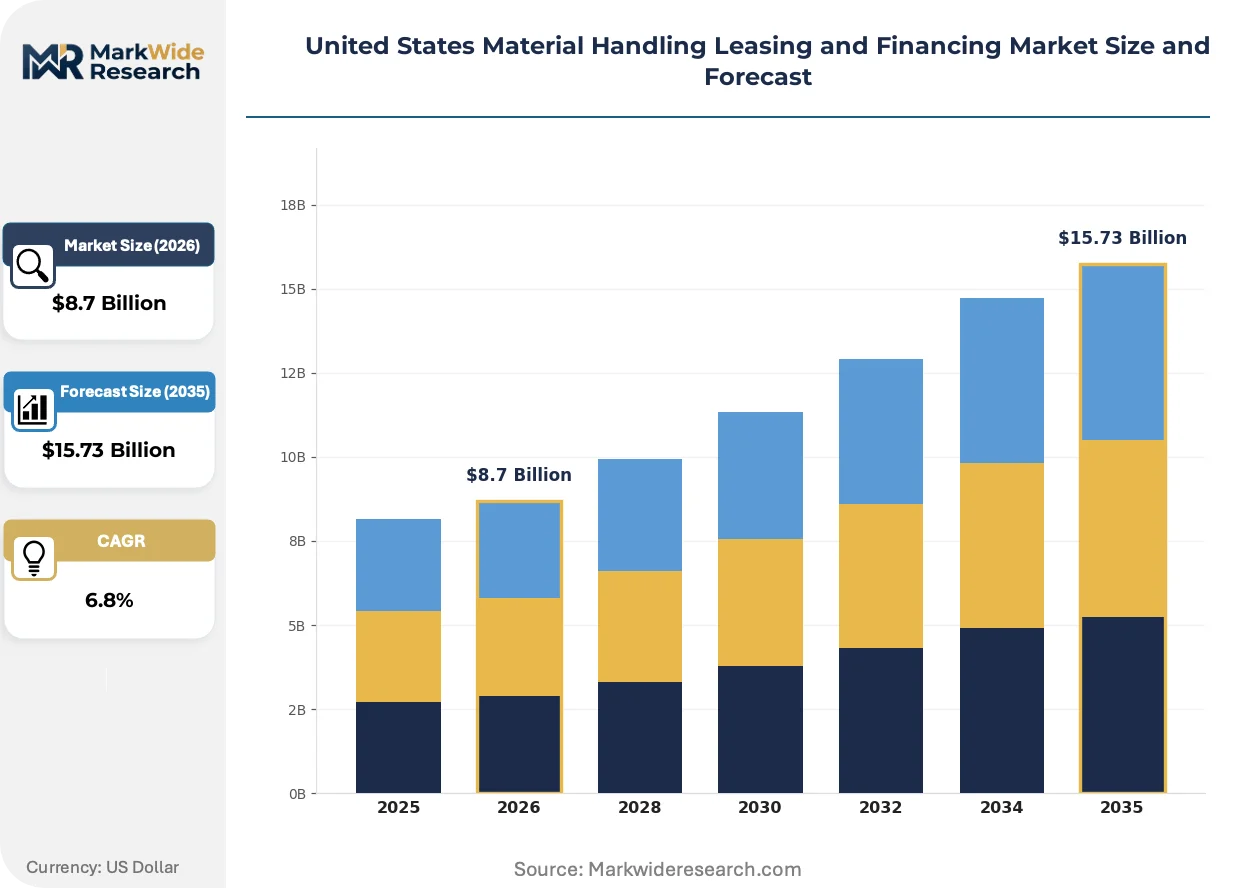
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Pallet Jacks, Hand Trucks, Automated Guided Vehicles Financing Option: Operating Lease, Finance Lease, Hire Purchase, Short-Term Rental End User: Warehouses, Retailers, Manufacturers, Distribution Centers Application: Inventory Management, Order Fulfillment, Shipping, Production Lines |
| Companies Covered | CIT Group Inc., Crest Capital LLC, Element Fleet Management Corp, Trust Capital LLC, DLL Finance LLC, Pacific Rim Capital Inc., CLARK Material Handling Company, Taylor Leasing and Rental Inc., Ascentium Capital, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Material Handling Leasing and Financing Market Evolving Landscape
Telematics penetration and predictive maintenance algorithms are restructuring how lessors price risk and manage asset lifecycles, shifting competitive advantage toward data-rich operators with integrated service platforms.
Lithium-ion battery systems are rewriting material handling fleet economics through reduced charging infrastructure requirements and opportunity charging compatibility. Regional grocery and retail distributors are adopting these systems at accelerated paces to eliminate battery room square footage. The technology is compressing total cost of ownership calculations and enabling shorter lease terms that match equipment refresh cycles to battery degradation curves rather than mechanical wear patterns.
EPA enforcement of Tier 4 Final emissions standards in non-attainment zones is accelerating diesel forklift phaseouts and redirecting capital toward electric alternatives. Industrial lessors are restructuring master lease agreements to exclude non-compliant equipment from eligible asset schedules. California's South Coast Air Quality Management District and Texas Commission on Environmental Quality regulated areas are experiencing the most acute financing redirection toward zero-emission fleets.
Usage-based contracting models are displacing traditional fixed-term leases in high-variability operations. Third-party logistics providers operating seasonal retail fulfillment are adopting metered payment structures tied to actual equipment utilization hours. This shift is most visible in Pennsylvania and Ohio distribution corridors where peak-season volume spikes create demand for payment flexibility without fleet ownership commitment.
United States Material Handling Leasing and Financing Market Segmentation
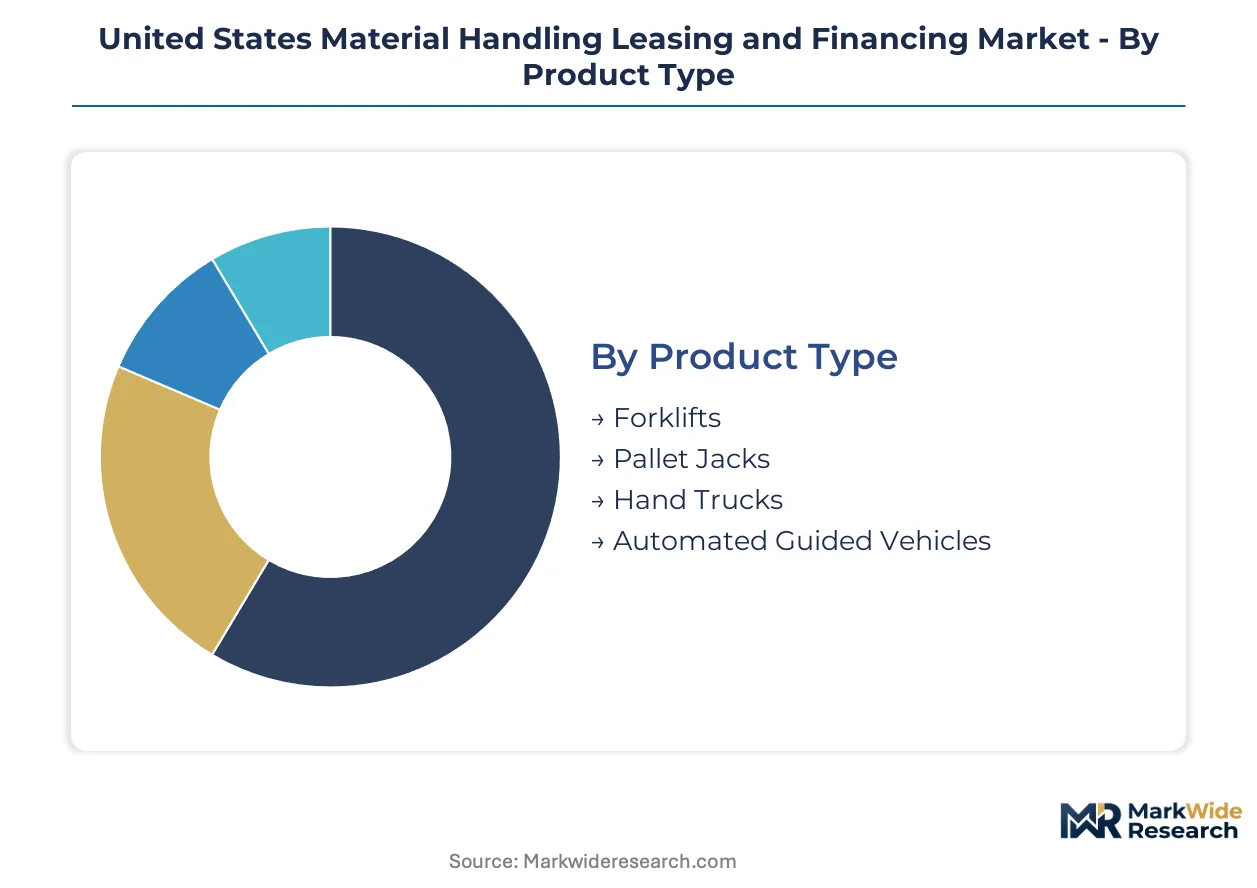
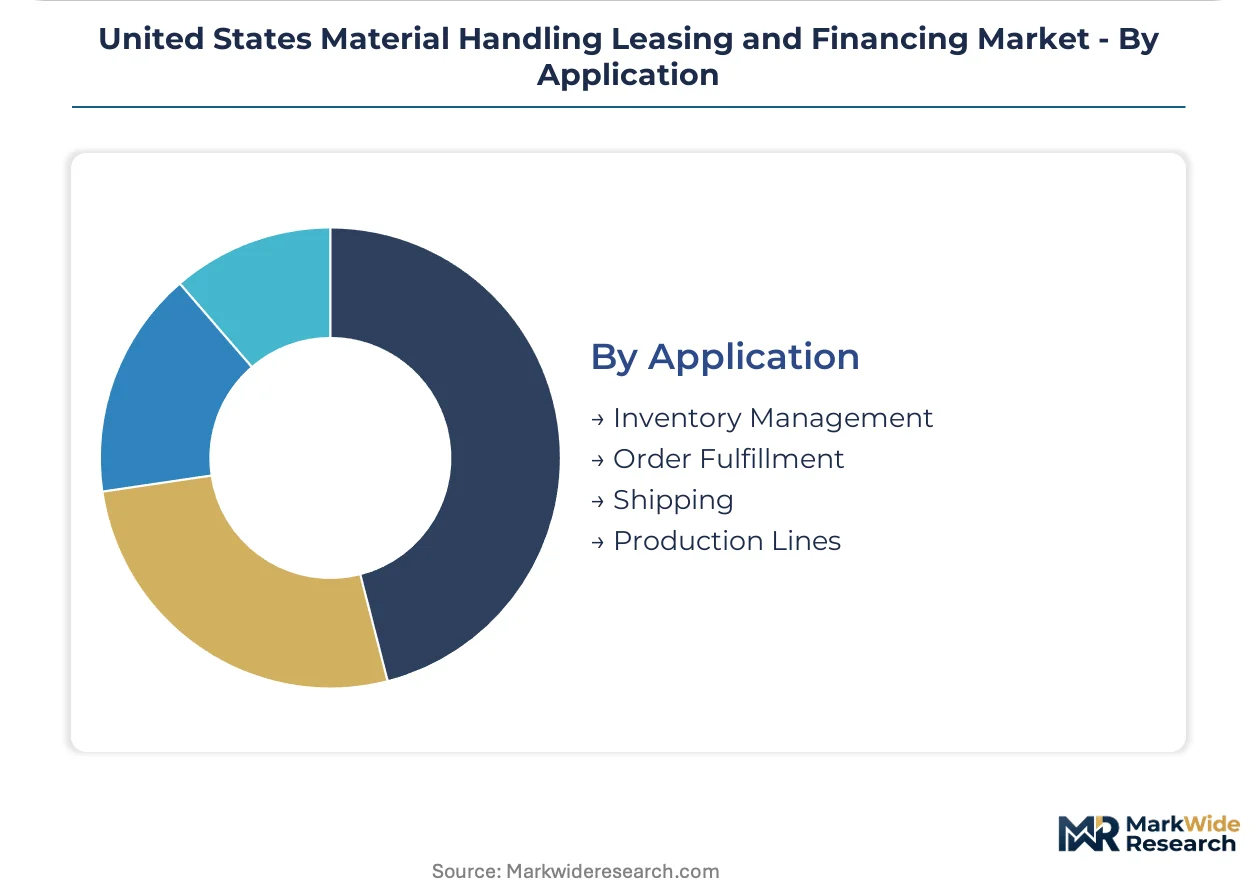
Material handling equipment financing segments reflect divergent capital intensity and regulatory exposure across the US industrial landscape. Lessors calibrate residual value models and lease rate structures differently for each segment based on equipment durability, technology obsolescence risk, and end-user credit profiles.
Product Type:
Forklifts anchor financing volume through standardized fleet procurement, while automated systems command premium pricing for technology integration complexity.
- Forklifts:Diesel, electric, and propane-powered variants constitute the core collateral base for material handling lessors. EPA Tier 4 Final compliance requirements in California and Northeast corridor states are redirecting financing toward lithium-ion electric models with battery-as-a-service attachments.
- Automated Guided Vehicles:These systems integrate with warehouse management software for autonomous pallet transport. Third-party logistics operators in Texas distribution hubs are scaling AGV fleets fastest as labor cost reduction targets intensify.
- Pallet Jacks:Manual and electric walk-behind units serve low-velocity operations with minimal capital commitment requirements.
- Hand Trucks:Light-duty material transport equipment with limited financing penetration due to low unit costs and cash purchase preference.
Mature deployment sits with forklifts. Newer deployment is concentrated in automated guided vehicles.
Financing Option:
Accounting treatment and ownership intent determine structure selection, with off-balance-sheet demand driving operating lease preference among publicly traded lessees.
- Operating Lease:Lessors retain depreciation benefits and residual risk exposure while lessees achieve off-balance-sheet treatment. National retailers with Sarbanes-Oxley compliance requirements dominate this segment for multi-year forklift fleet contracts.
- Finance Lease:Transfers substantially all risks and rewards of ownership to the lessee with capital expenditure recognition. Indiana and Wisconsin manufacturers prefer this structure for equipment with clear ownership transfer intent at term end.
- Hire Purchase:Installment payment structure with title transfer upon final payment. Mid-market producers with seasonal cash flow patterns negotiate payment adjustment clauses for production cycle alignment.
- Short-Term Rental:Daily or weekly equipment access without residual value commitment. Peak-season retail fulfillment operations in Ohio and Pennsylvania distribution corridors utilize this for volume spike accommodation.
Operating leases dominate balance-sheet-conscious enterprises. Hire purchase structures are expanding fastest among capital-constrained regional manufacturers.
End User:
Facility scale and automation intensity separate high-volume fleet lessors from single-unit equipment financiers.
- Warehouses:E-commerce fulfillment centers with automated storage and retrieval systems generate concentrated demand for integrated maintenance provisions and telematics monitoring. Great Lakes corridor facilities are refreshing fleets around electric propulsion mandates.
- Distribution Centers:Regional consolidation hubs serving multi-channel retail networks require flexible fleet scaling. Texas-based operators are negotiating usage-based contracts tied to actual equipment utilization hours.
- Retailers:Store-level receiving and stockroom operations with limited equipment sophistication and shorter replacement cycles.
- Manufacturers:Production line integration requirements create specialized equipment specifications with captive maintenance capabilities.
Established financing relationships center on warehouses. Distribution centers are driving contract innovation around dynamic pricing mechanisms.
Application:
Throughput velocity and labor substitution potential determine equipment specification and lease term structure.
- Order Fulfillment:Pick-and-pack operations with seasonal volume variability demand flexible fleet access. Third-party logistics providers are adopting metered payment structures that scale with actual throughput rather than fixed asset commitment.
- Inventory Management:Cycle counting and put-away operations with steady-state equipment utilization profiles support traditional fixed-term lease economics.
- Shipping:Dock-level loading and cross-docking with high equipment turnover and exposure to outdoor operating conditions.
- Production Lines:Just-in-time manufacturing integration with specialized attachments and uptime guarantee requirements.
Conventional lease structures prevail in inventory management. Order fulfillment applications are generating the steepest expansion trajectory for usage-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment leasing demand concentrates in manufacturing-intensive states and logistics corridors, while financing origination gravitates toward metropolitan banking centers with specialized asset-backed lending expertise.
Texas
Dallas-Fort Worth distribution hubs are scaling automated fulfillment centers that require multi-year forklift fleet leases with integrated maintenance provisions. The Texas Commission on Environmental Quality enforces emissions standards that redirect financing toward electric equipment in regulated zones. Houston's petrochemical corridor sustains heavy-duty material handling demand for port and intermodal operations.
Illinois
Chicago's rail and trucking nexus generates concentrated demand for short-term rental structures accommodating seasonal inventory surges. The Illinois Environmental Protection Agency aligns with federal Tier 4 Final compliance timelines that compress residual values for non-compliant diesel units. Rockford and Peoria manufacturing clusters favor hire-purchase arrangements with production-aligned payment schedules.
California
Los Angeles and Inland Empire warehouse operators face the nation's strictest zero-emission mandates, accelerating lithium-ion electric forklift adoption. The South Coast Air Quality Management District enforces warehouse emissions regulations that disqualify diesel equipment from new lease originations. Central Valley agricultural processors utilize seasonal lease structures for harvest-period material handling capacity.
Ohio
Cleveland and Columbus manufacturing bases sustain finance lease preference for production-line integrated equipment with ownership transfer intent. The Ohio Environmental Protection Agency administers diesel emissions programs that affect fleet refresh timing in non-attainment areas. Cincinnati's distribution corridor supports telematics-integrated lease products with usage-based pricing components.
Michigan
Detroit automotive supplier networks demand specialized material handling attachments with captive maintenance capabilities and uptime guarantees. The Michigan Department of Environment, Great Lakes, and Energy oversees industrial emissions compliance affecting forklift fleet composition. Grand Rapids furniture and appliance distribution centers are adopting automated guided vehicle financing for labor cost reduction.
United States Material Handling Leasing and Financing Market Competitive Landscape
Top-tier vendors anchor captive finance and fleet management, while mid-market specialists compete through relationship depth and geographic focus. The market exhibits moderate concentration with national lessors commanding multi-state fleet contracts and regional players dominating single-state manufacturer relationships. Three archetypes define competitive positioning: captive finance arms of equipment manufacturers, independent fleet management platforms with telematics integration, and specialized mid-market lessors with flexible term structures. Consolidation through portfolio acquisition and technology licensing partnerships represent the dominant competitive moves reshaping market structure.
Among national-scale lessors, CIT Group Inc. and Element Fleet Management Corp exemplify the captive finance and integrated fleet management archetypes respectively. Crest Capital LLC occupies a position within the mid-market specialization tier, representing flexible hire-purchase structures for capital-constrained regional manufacturers. These three entities collectively illustrate the competitive spectrum from standardized national fleet programs to customized regional financing relationships.
| Leading Market Players |
|---|
| CIT Group Inc. |
| Crest Capital LLC |
| Element Fleet Management Corp |
| Trust Capital LLC |
| DLL Finance LLC |
| Pacific Rim Capital Inc. |
| CLARK Material Handling Company |
| Taylor Leasing and Rental Inc. |
| Ascentium Capital |
| Others |
Value Network & Pricing Analysis
Lithium-ion battery cell costs cascade through electric forklift lease rate structures, compressing monthly payment differentials between premium telematics-enabled fleets and standard equipment tiers as lessors absorb upstream energy storage price volatility.
Pricing Analysis
Margin tightening in mid-market hire-purchase structures reflects residual value compression on EPA Tier 4 Final non-compliant diesel units stranded in California and Northeast corridor states. Three-tier pricing structure across premium telematics-integrated, standard electric, and economy-grade propane equipment segments buyers by compliance certification level and bundled maintenance intensity. Cost-down pressure on standard-tier contracts accelerates because regional manufacturers in Indiana and Wisconsin negotiate seasonal payment adjustment clauses. Capital-constrained producers exhibit highest price sensitivity, while publicly traded retailers prioritize off-balance-sheet treatment over rate minimization.
Supply Chain Analysis
Single-source vulnerability sits with domestic forklift manufacturing concentration in Ohio, Michigan, and Illinois, exposing lessors to regional labor disruption and logistics bottleneck risk during fleet procurement cycles. Raw material dependencies span steel for chassis fabrication, lithium carbonate for battery systems, and semiconductor components for telematics modules. Tariff exposure on Chinese-sourced battery management systems amplifies procurement cost uncertainty. Distribution runs through national distributor networks anchored by equipment manufacturers' captive finance arms, with regional lessors accessing inventory through secondary wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified electric forklift technician scarcity props lease rate pricing by constraining lessor service network expansion and deepening incumbent maintenance bundling power.
For Market Incumbents: Deepen vertical integration into lithium-ion battery lifecycle management to capture battery-as-a-service revenue streams and defend against emerging telematics-native fleet disruptors. Expand captive maintenance capabilities in EPA non-attainment zones where compliance documentation requirements deepen customer switching costs. Prioritize certification investment for high-voltage systems training to lock in technician scarcity advantages. For New Entrants and Emerging Players: California's warehouse emissions regulations open a window for pure-play electric equipment lessors to penetrate the Inland Empire fulfillment center cluster with zero-emission fleet offerings unburdened by legacy diesel inventory. Target mid-market manufacturers in Wisconsin with flexible hire-purchase structures featuring production-aligned payment schedules. Lead go-to-market through regional equipment distributor partnerships rather than direct sales force buildout. For Investors and Strategic Acquirers: Accelerated master lease agreement restructuring by national lessors to exclude non-compliant diesel equipment is the leading indicator that residual value risk transfer to specialized remarketing platforms will intensify. Long-term viability favors vertically integrated operators with captive battery supply and telematics data assets. Monitor EPA enforcement patterns in Texas Commission on Environmental Quality regulated areas as the inflection signal for electric equipment financing demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time utilization monitoring enables dynamic rate adjustment and residual value predictability for lessors. |
| Battery-as-a-Service Attachment | Lithium-ion lifecycle management captures recurring revenue beyond equipment financing margins. |
| Regional Distributor Partnership | Multi-state fleet contracts with national distributors anchor origination scale for captive finance arms. |
| Zero-Emission Fleet Specialization | California Air Resources Board compliance positions lessors for regulatory tailwind in warehouse automation clusters. |
| Technician Certification Program | High-voltage systems training scarcity deepens maintenance bundling stickiness and competitive moats. |
Research Methodology
Independent corroboration across equipment lessor portfolio managers, OEM procurement directors, and third-party logistics fleet operators underwrites the qualitative findings on lease structure evolution. Secondary validation draws from EPA enforcement action databases, OSHA workplace injury statistics, and SEC 10-K filings of publicly traded equipment finance entities. Bottom-up triangulation across state-level forklift registration data and top-down reconciliation with national industrial equipment production indices anchor volume estimates.
Rate-of-change decomposition across the projection horizon segments growth by financing structure type, equipment propulsion technology, and end-user facility automation intensity. Segmentation dimensions modeled include lease accounting classification, product type tier, and regional regulatory compliance cluster. CAGRs derive from equipment replacement cycle analysis, e-commerce fulfillment center buildout pipelines, and electric propulsion adoption curve calibration. Forecast inputs incorporate battery technology depreciation schedules and state zero-emission mandate implementation timelines.
Caveats apply where Federal Reserve policy shifts or lithium supply chain disruptions could materially shift the outlook for lease rate pricing and residual value assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Factoring Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Russia Car Loan Market