
 Global Commercial Insurance Software Market | 2026-2036
Global Commercial Insurance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Insurance Software Market Foresight
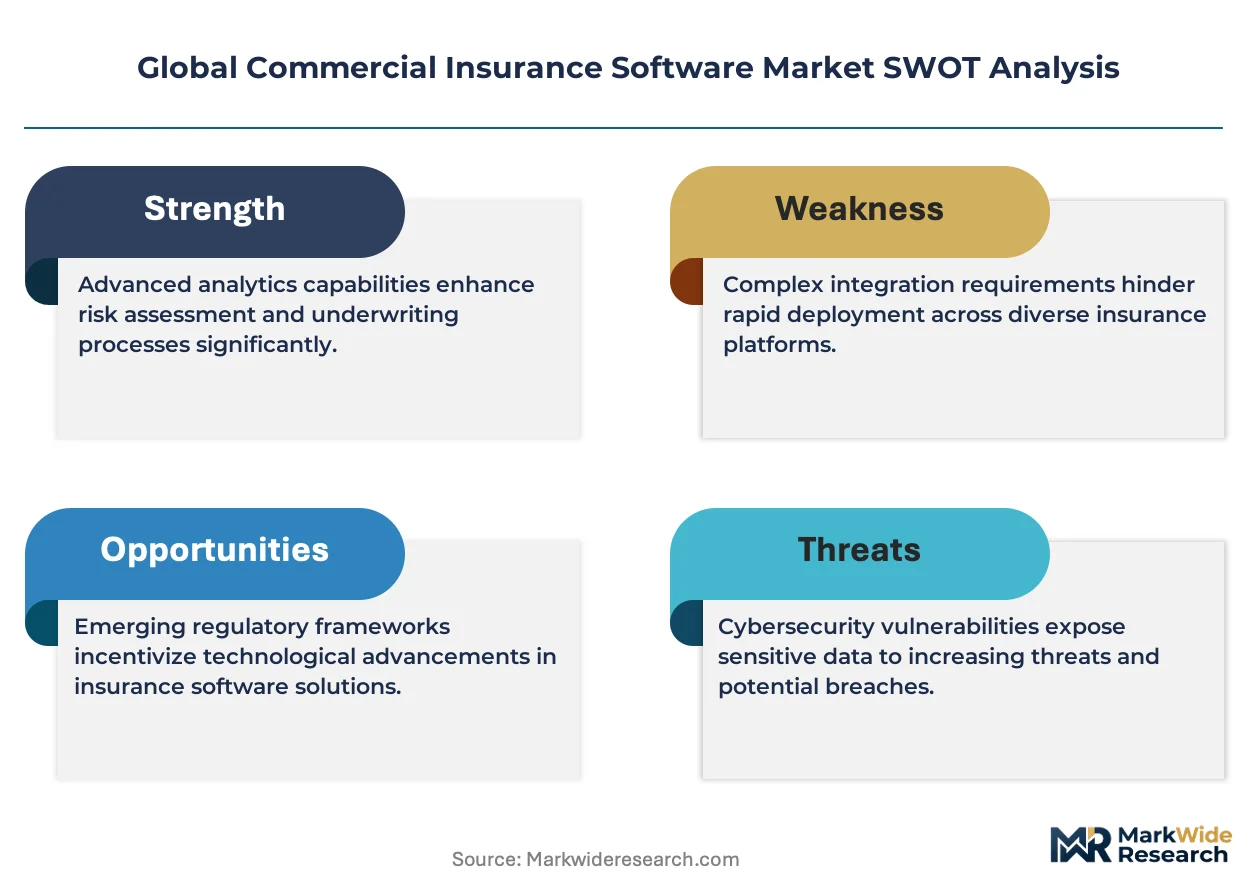
North American insurtech infrastructure is consolidating as carriers replace decades-old policy administration systems with cloud-native platforms. Guidewire Software anchors the property and casualty core systems segment through its deep vertical specialization. Salesforce competes by extending its CRM dominance into insurance-specific workflow automation. Duck Creek Technologies differentiates through modular SaaS architecture that lets mid-tier carriers deploy components incrementally.
Commercial insurance software encompasses policy administration, claims management, underwriting, billing, and risk assessment platforms that automate carrier operations and broker intermediation. These systems integrate actuarial data pipelines, regulatory reporting APIs, and document management layers to enforce compliance while accelerating quote-to-bind cycles. Cloud-based deployment leads solution offering adoption as carriers seek elastic capacity for catastrophe-season volume spikes. Claims management segments attract disproportionate R&D investment because fraud detection algorithms and IoT-driven loss prevention create recurring margin pools. On-premise installations persist among large mutual carriers with bespoke legacy data architectures, though hybrid configurations are displacing pure hosted models fastest among reinsurers.
State insurance departments across the United States enforce NAIC model laws on data security and producer licensing that shape software certification requirements. The EU AI Act and GDPR impose algorithmic transparency obligations on automated underwriting tools sold into European markets. Insurers must monitor how NHTSA telematics standards and FAA drone regulations expand commercial auto and aviation liability data feeds into rating engines.
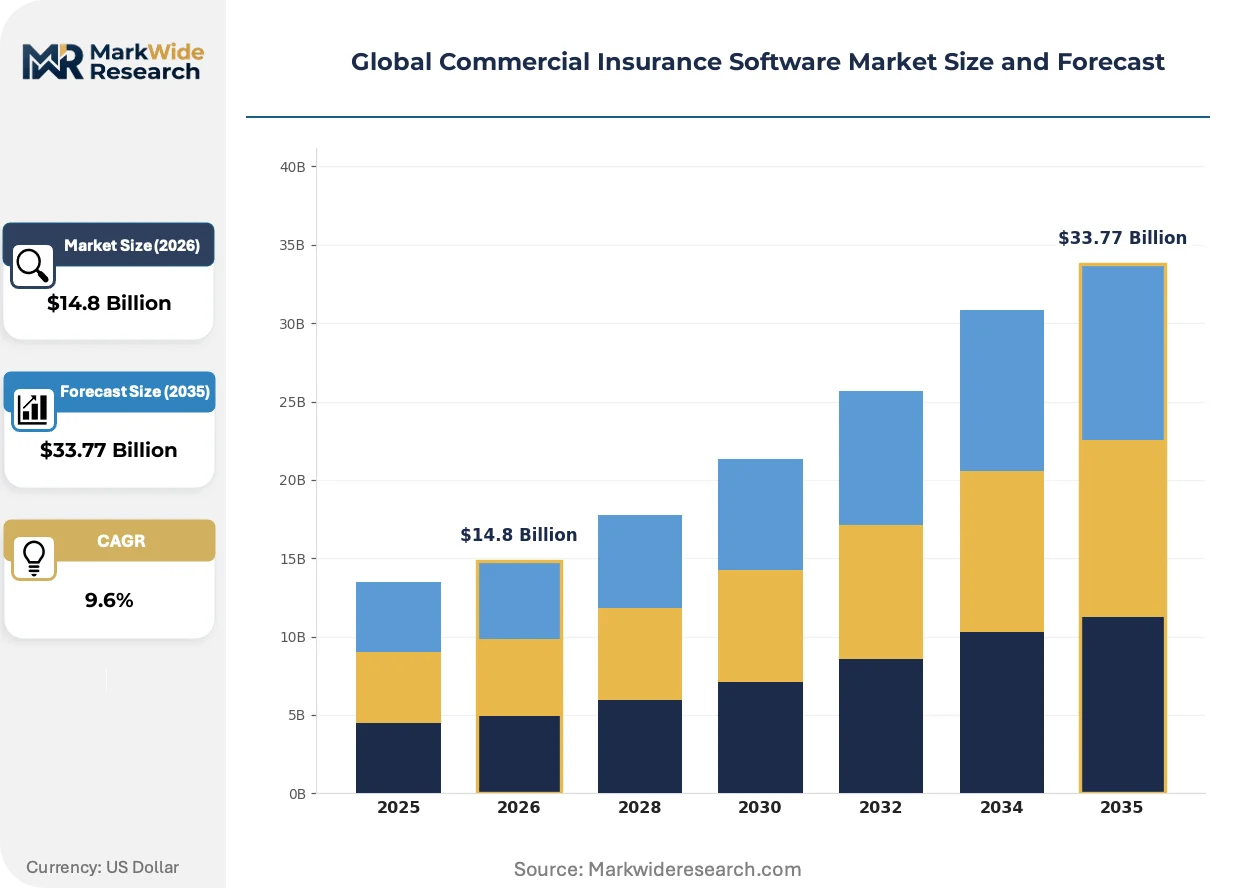
Market Dynamics
Cloud-native core system replacement is compressing carrier procurement cycles as property and casualty insurers abandon monolithic policy administration platforms for API-first architectures that integrate telematics, satellite imagery, and real-time catastrophe modeling.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated underwriting tool vendors must now document decision logic, creating certified software procurement pipelines that favor established platform providers with compliance engineering resources.
- Telematics data standardization:NHTSA commercial vehicle monitoring requirements and connected fleet adoption are embedding IoT sensor feeds directly into rating engines, expanding addressable premium volume for integrated software stacks.
- Japan legacy modernization wave:Domestic non-life carriers face METI digital transformation deadlines, accelerating replacement of 1980s-era host systems with SaaS policy administration platforms.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency creates single-point-of-failure exposure when three providers dominate carrier data center migration strategies.
- Actuarial talent scarcity:Shortage of professionals bridging statistical modeling and Python-based data engineering constrains implementation velocity for predictive analytics modules.
- State-by-state certification friction:NAIC model law adoption varies across US insurance departments, forcing vendors to maintain parallel compliance documentation for producer licensing and data security modules.
Strategic Opportunities
- Germany commercial auto expansion:KBA vehicle-type approval integration with fleet management platforms creates entry points for usage-based insurance software in Europe's largest non-life market.
- Parametric coverage algorithms:Satellite-derived index triggers for crop and flood policies demand new event-detection software categories with minimal claims adjustment overhead.
- API marketplace distribution:Embedded insurance orchestration layers let carriers distribute commercial products through accounting software and ERP procurement channels.
Industry Challenges
- COBOL-to-microservices refactoring:Decades-old rating engine logic resists containerization, forcing carriers to maintain expensive parallel systems during multi-year migration windows.
- Data lineage documentation:GDPR Article 30 record-keeping requirements and EU AI Act technical documentation obligations impose manual overhead on algorithm development workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Insurance Software Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Offering: Policy Administration, Claims Management, Risk Assessment, Underwriting, Billing & Payments Application: Small Business Coverage, Liability Coverage, Property Coverage, Workers’ Compensation, Commercial Auto Coverage End User: Insurance Carriers, Brokers, Third-Party Administrators, Reinsurers, Risk Managers |
| Companies Covered | Salesforce, Guidewire Software, Microsoft, Oracle, SAP, Duck Creek Technologies, Sapiens International Corporation, Majesco, Pegasystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Insurance Software Market Shifts & Advancements
Generative AI is rewriting software specification documents and test automation suites, compressing implementation timelines for carrier core system deployments while introducing new validation requirements for model hallucination risks in customer-facing interfaces.
Embedded machine learning inference engines are expanding into claims segmentation workflows, enabling real-time damage assessment from smartphone imagery submissions. Mid-tier carriers in the United States are adopting these modules fastest, driven by catastrophe-season volume spikes that overwhelm traditional adjuster capacity. The technology is expanding into fraud detection by cross-referencing repair estimates against historical total-loss valuations.
CSRD sustainability reporting obligations are mandating climate risk disclosure integration into European carrier ESG dashboards, forcing software vendors to embed physical risk scoring directly into underwriting workbenches. German and French regulators are enforcing granular exposure mapping requirements. Commercial property insurers are responding by procuring geospatial analytics modules that quantify flood and wildfire vulnerability at individual site levels.
Subscription-based pricing for core system components is displacing perpetual license models among mutual carriers with constrained capital budgets. MGAs and program administrators in the United Kingdom and Australia are driving this shift, preferring per-policy fees that align software costs with written premium fluctuations. The model reduces upfront implementation risk but requires vendors to master usage metering infrastructure.
Global Commercial Insurance Software Market Segmentation
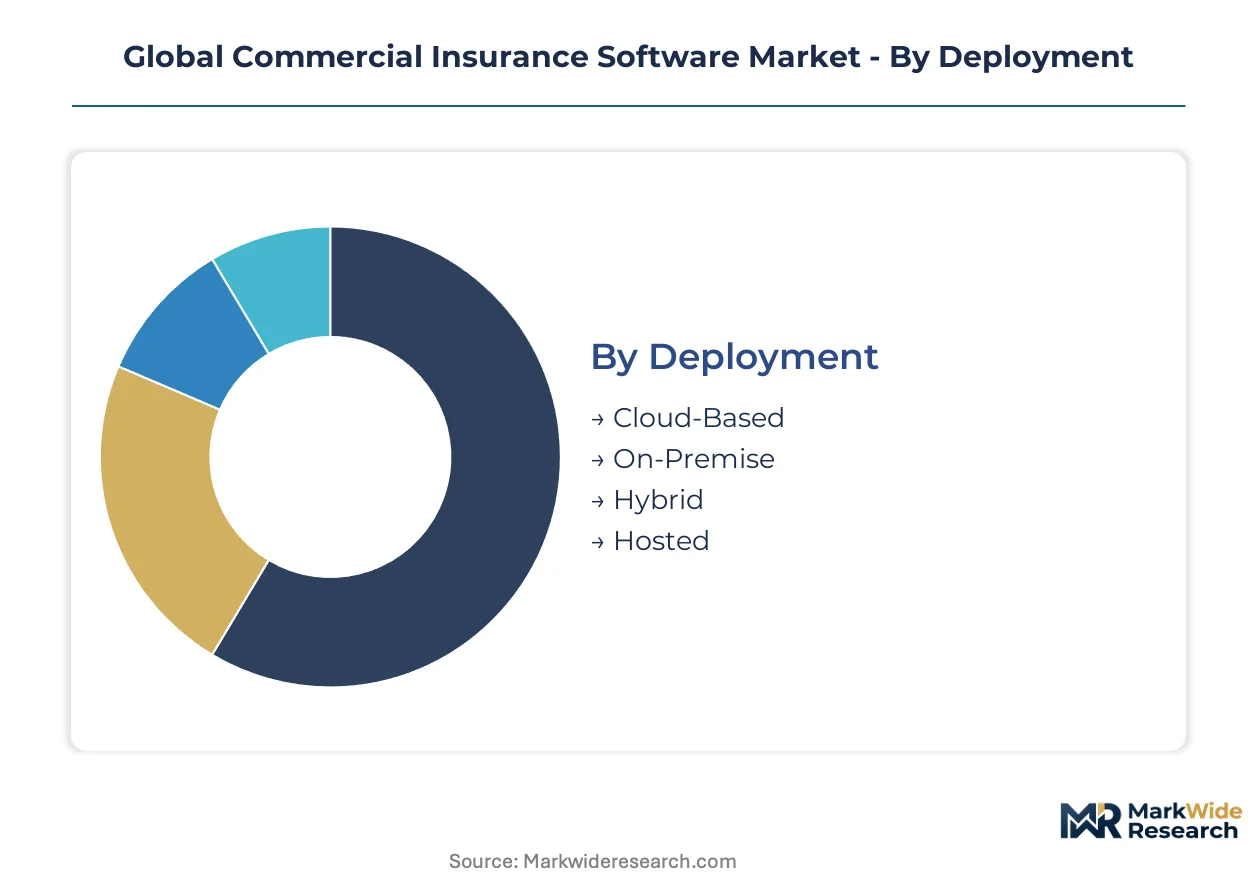
Commercial insurance software segments reflect divergent technical requirements across carrier maturity levels. Deployment preferences split between regulatory-constrained incumbents and cloud-native entrants, while solution offerings map directly to operational complexity tiers.
Deployment:
Customization-to-standardization tension manifests most acutely here, with bespoke private cloud configurations commanding premium engineering against commodity public infrastructure.
- Cloud-Based:Elastic compute architectures enable catastrophe-season capacity scaling without capital-heavy data center investments. United States property and casualty carriers dominate procurement, pressured by NAIC data security model laws that now certify specific cloud control frameworks.
- Hybrid:Split workloads maintain sensitive rating algorithms on-premise while pushing customer-facing portals to public infrastructure. German non-life carriers favor this architecture under GDPR Article 32 technical and organizational measures requirements.
- On-Premise:Large mutual carriers with COBOL-dependent legacy cores retain hosted infrastructure for actuarial system continuity.
- Hosted:Managed private cloud deployments serve mid-tier carriers lacking internal platform engineering capacity.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Solution Offering:
Margin concentration follows workflow automation depth, with modules touching claims payments capturing disproportionate vendor R&D investment.
- Claims Management:Fraud detection algorithms and IoT-driven loss prevention modules create recurring revenue pools through performance-based pricing. Japanese carriers under METI digital transformation mandates are replacing 1980s-era host claims systems fastest.
- Policy Administration:Core system replacement absorbs the largest implementation budgets, compressing quote-to-bind cycles from weeks to hours. United States mid-market carriers are abandoning monolithic platforms for API-first architectures.
- Underwriting:Automated risk scoring engines integrate telematics and satellite imagery feeds into real-time pricing decisions.
- Risk Assessment:Geospatial analytics modules quantify flood and wildfire vulnerability at individual commercial property sites.
- Billing & Payments:Embedded premium financing and commission reconciliation tools serve managing general agents with complex distribution hierarchies.
Dominating vendor revenue: Policy Administration. Gaining share fastest: Claims Management.
Application:
Premium volume scale determines software complexity requirements, with commercial auto and property coverage demanding the most sophisticated data integration layers.
- Commercial Auto Coverage:NHTSA telematics standards and connected fleet adoption embed IoT sensor feeds directly into rating engines. United States commercial auto underwriters are procuring integrated software stacks to capture usage-based premium expansion.
- Property Coverage:Satellite-derived catastrophe modeling and real-time exposure aggregation require elastic compute infrastructure. German carriers face KBA vehicle-type approval integration demands for fleet platforms.
- Liability Coverage:Long-tail claims reserving and litigation management workflows need specialized document retention systems.
- Workers' Compensation:OSHA reporting integration and medical bill review automation reduce administrative loss ratios.
- Small Business Coverage:Simplified question sets and instant binding capabilities target micro-enterprise segments through digital distribution.
Capturing largest addressable premium: Property Coverage. Climbing the fastest: Commercial Auto Coverage.
End User:
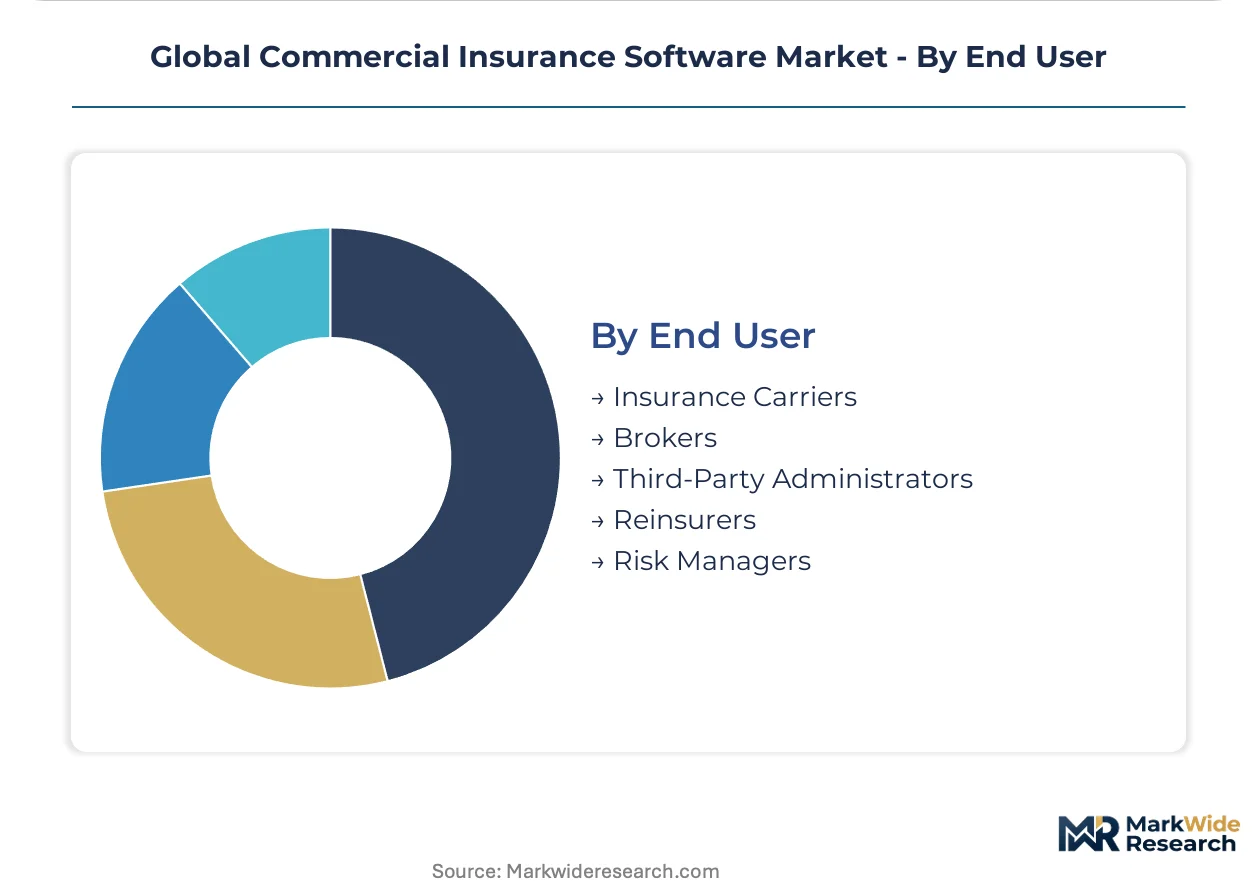
Procurement authority concentrates with carriers, though broker and MGA technology budgets are expanding fastest as distribution intermediaries verticalize into underwriting.
- Insurance Carriers:Direct writers and mutuals commission full core system replacements with multi-year implementation horizons. Japanese non-life carriers dominate current procurement cycles under regulatory modernization deadlines.
- Brokers:Digital placement platforms and client self-service portals absorb technology investment as commission compression pressures margins.
- Third-Party Administrators:Claims outsourcing specialists require multi-tenant platforms serving diverse carrier clients with segregated data architectures.
- Reinsurers:Catastrophe aggregation and retrocession administration tools demand global exposure visualization capabilities.
- Risk Managers:Corporate captive administration and loss forecasting modules serve large insureds with self-insurance programs.
Commanding largest software budgets: Insurance Carriers. Steepest expansion trajectory: Third-Party Administrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital density anchors North American insurtech formation, while Frankfurt's regulatory technology cluster shapes European compliance engineering priorities for insurance software vendors.
United States
Property and casualty carriers in Hartford and Boston are replacing 1990s-era policy administration systems with cloud-native platforms. NAIC data security model laws now certify specific cloud control frameworks, accelerating procurement cycles. The New York Metro corridor hosts the densest concentration of insurtech engineering talent.
Germany
Munich-based non-life carriers face KBA vehicle-type approval integration demands for commercial fleet platforms. GDPR Article 32 technical and organizational measures requirements favor hybrid cloud architectures over pure public deployments. The Frankfurt-Rhine-Main region concentrates regulatory technology engineering capacity.
Japan
Tokyo-headquartered non-life insurers operate under METI digital transformation deadlines that mandate replacement of 1980s-era host systems. SaaS policy administration platforms capture procurement priority as carriers abandon mainframe-dependent claims workflows. The Osaka-Kobe corridor hosts specialized system integrators for legacy migration.
United Kingdom
London's Lloyd's market drives demand for multi-tenant platforms serving managing general agents with complex distribution hierarchies. Subscription-based pricing for core system components displaces perpetual license models among capital-constrained mutuals. The City of London concentrates broker technology investment responding to commission compression.
Australia
Sydney-based program administrators prefer per-policy software fees that align technology costs with written premium fluctuations. TGA-equivalent prudential standards shape data security certification requirements for carrier software procurement. The Melbourne-Geelong corridor hosts catastrophe modeling specialists serving Asia-Pacific reinsurance markets.
Global Commercial Insurance Software Market Competitive Landscape
Global majors compete with regional champions across compliance engineering depth and vertical specialization intensity. The vendor base stratifies into three tiers: horizontal platform extenders, insurance-native specialists, and modular SaaS architects. Dominant competitive moves include strategic partnerships with hyperscaler infrastructure providers and geographic expansion through system integrator channel relationships.
Within the insurance-native specialist tier, Guidewire Software and Duck Creek Technologies exemplify vertical platform depth, while Salesforce represents horizontal CRM extension into insurance workflow automation. These three companies occupy distinct positioning vectors—Guidewire through deep property and casualty core system heritage, Duck Creek through incremental modular deployment architecture, and Salesforce through ecosystem breadth and low-code configuration capacity.
| Leading Market Players |
|---|
| Salesforce |
| Guidewire Software |
| Microsoft |
| Oracle |
| SAP |
| Duck Creek Technologies |
| Sapiens International Corporation |
| Majesco |
| Pegasystems |
| Others |
Supply & Pricing Matrix
Mid-tier property and casualty carriers in the United States and Germany concentrate procurement authority, driving subscription-based SaaS pricing that displaces perpetual licenses. This buyer concentration aligns software costs with written premium fluctuations, reducing upfront capital burden while embedding vendors in multi-year recurring revenue relationships.
Pricing Analysis
Warranty and implementation service bundling separates premium-tier offerings from standard self-service deployments, with white-glove onboarding and dedicated customer success managers commanding 40-60% price premiums. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, integration depth, and regulatory certification coverage. Pricing pressure stems from hyperscaler infrastructure commoditization compressing platform margins at the low end. Mutual carriers with constrained capital budgets exhibit highest price sensitivity, while large direct writers prioritize compliance engineering over cost minimization.
Supply Chain Analysis
Reverse-logistics for data migration and legacy system decommissioning flows through specialized system integrators in Japan, Germany, and the United States who manage COBOL-to-cloud refactoring. Software development capacity concentrates in India, Poland, and Vietnam for engineering talent, while regulatory compliance expertise clusters in Frankfurt, London, and New York. Supply chain risk centers on single-source dependency for catastrophe modeling data feeds from satellite imagery providers. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams serving carrier IT procurement officers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial talent scarcity constrains implementation velocity for predictive analytics modules, propping pricing power for vendors with certified data engineering pipelines. This supply bottleneck favors established platforms over emerging entrants.
For Market Incumbents: Acquire specialized AI/ML engineering teams to fortify automated underwriting capabilities against Salesforce's ecosystem expansion. Lock in multi-year enterprise agreements with Japanese carriers before METI digital transformation deadlines expire. Prioritize backward integration into telematics data aggregation to capture usage-based insurance premium growth. For New Entrants and Emerging Players: API-first claims segmentation tools offer the clearest technology-first wedge, targeting mid-tier United States carriers overwhelmed by catastrophe-season volume spikes. White-space concentration sits with parametric coverage algorithms for crop and flood policies, where satellite-derived index triggers demand minimal claims adjustment infrastructure. Go-to-market execution should embed through accounting software and ERP procurement channels rather than direct carrier sales. For Investors and Strategic Acquirers: The window for entry favors modular SaaS architects with incremental deployment capabilities over monolithic platform replacers. Long-term viability hinges on compliance engineering depth for EU AI Act algorithmic transparency mandates. Acquisition target archetype: claims management specialists with IoT-driven loss prevention modules. Monitor NHTSA telematics standardization timelines as inflection signal for commercial auto software demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures from Duck Creek and Guidewire enable telematics and satellite imagery feeds into underwriting workbenches. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, and GCP provide elastic catastrophe-season capacity for North American carriers. |
| Acquisition of Specialist Firm | Geospatial analytics modules for flood and wildfire vulnerability scoring address CSRD climate risk disclosure mandates. |
| Geographic Expansion | Entry into Japan's legacy modernization wave captures METI-mandated mainframe replacement cycles. |
| Product Launch | Generative AI test automation suites compress implementation timelines for carrier core system deployments. |
Research Methodology
Multi-period observation of carrier procurement cycles, cloud migration spend patterns, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with property and casualty CIOs, insurtech product managers, system integration specialists, and NAIC compliance officers. Secondary validation drew from SEC 10-K filings of publicly traded vendors, NAIC model law adoption tracking, EU AI Act implementation guidance, and METI digital transformation policy documents. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against aggregate carrier IT spend estimates ensured cross-verification.
Segment-weighting applied differential growth assumptions across cloud-based, hybrid, on-premise, and hosted deployment architectures, with organization size tiers and vertical specialization intensity as secondary stratification dimensions. CAGRs were derived from fitted trend curves applied to carrier replacement cycle data and vendor booking patterns across the projection horizon. Forecast inputs incorporated NAIC data security framework certification timelines and EU AI Act technical documentation obligation phase-ins.
Several conditions sit outside the modeled scope, including abrupt hyperscaler service disruptions, state-by-state NAIC model law adoption divergences, and generative AI hallucination liability frameworks. Forecasts reflect documented assumptions about carrier capital expenditure continuity and regulatory deadline adherence. Practitioners should monitor NHTSA commercial vehicle telematics mandates and FAA drone regulation expansions for early demand signals in commercial auto and aviation liability software segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Insurance Software Market
Insurance Technology
Insurance Automation Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
UK Insurtech Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Europe Insurtech Market