
 Insurance Fraud Detection Market | 2026-2036
Insurance Fraud Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Fraud Detection Market Intelligence
Mid-market insurers is bifurcating from tier-one carriers in platform sophistication and procurement scale. Fair Isaac Corporation leverages its FICO Falcon platform to anchor real-time transaction scoring across North American P&C portfolios. SAS Institute Inc. competes through deep statistical modeling tools that sustain insurer loyalty in complex claims environments.
Insurance fraud detection encompasses algorithmic systems that flag anomalous claims patterns, policy applications, and beneficiary behaviors using machine learning models, predictive analytics engines, and rule-based scoring thresholds to minimize loss ratios and regulatory exposure. Machine learning now leads technology investment as insurers replace static rule engines with adaptive anomaly detection that reduces false-positive rates. Cloud-based deployment is accelerating fastest among mid-tier carriers seeking to bypass capital-intensive infrastructure builds while accessing elastic compute for seasonal claims surges.
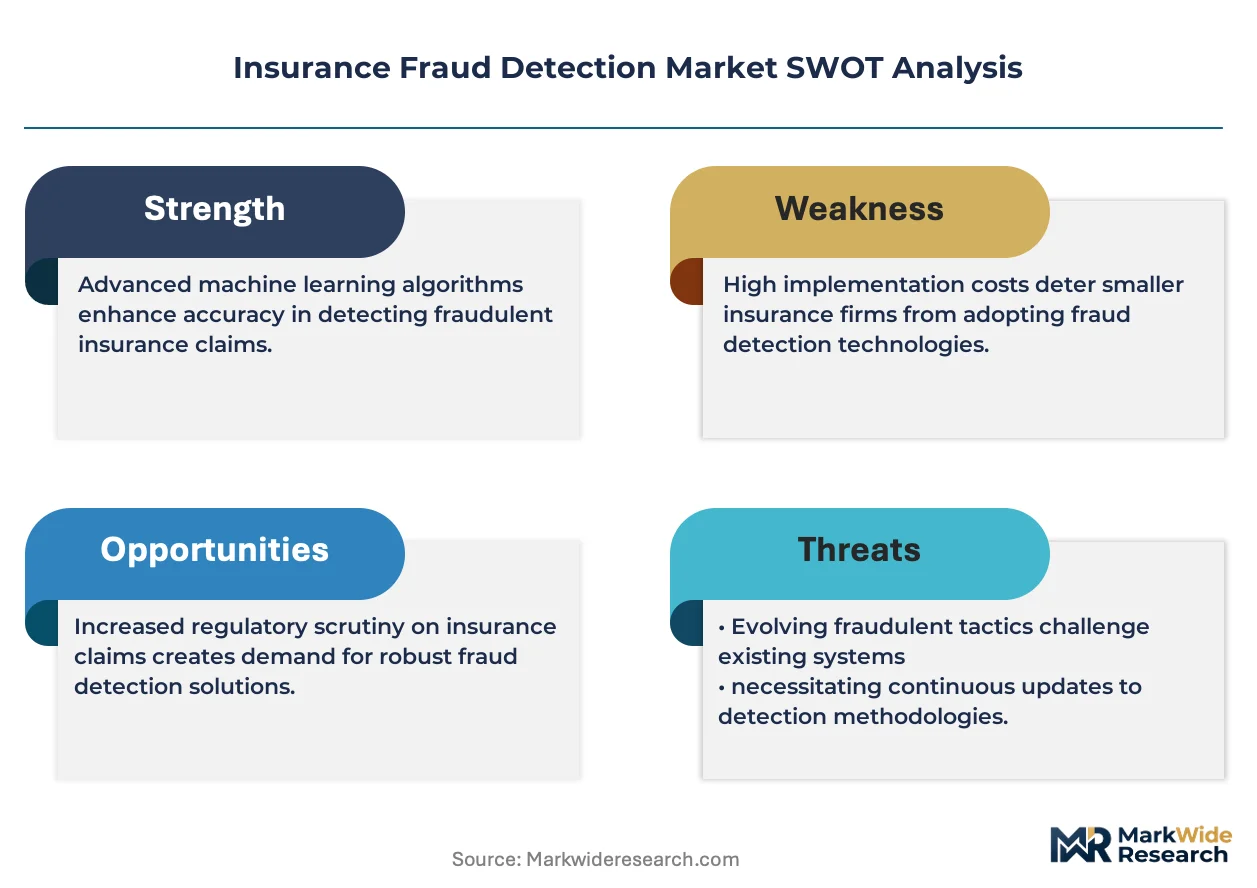
The EU AI Act imposes transparency and human-oversight requirements on automated insurance decisions, while HIPAA governs health data use in US fraud analytics and the FCA's Consumer Duty rules tighten UK claims-handling standards. These frameworks shape product roadmaps by mandating explainable model outputs and audit trails that elevate compliance costs for pure black-box vendors. Stakeholders must weigh build-versus-buy decisions for in-house model governance capabilities as regulatory divergence between jurisdictions deepens.
Market Dynamics
The EU AI Act's human-oversight mandate is decomposing black-box fraud scoring architectures, forcing insurers to rebuild model governance frameworks from inference layers upward. This regulatory compression is accelerating vendor consolidation as explainability becomes a procurement gate.
Growth Catalysts
- Real-time claims scoring:P&C carriers in the United States are embedding adaptive anomaly detection into auto and property workflows, collapsing investigation timelines from weeks to hours.
- EU AI Act compliance mandates:Automated decision systems in European insurance now require auditable model outputs, creating replacement demand for legacy rule engines.
- Cloud elasticity:Mid-tier carriers bypass capital-intensive infrastructure by accessing elastic compute for seasonal claims surges, particularly in health insurance lines.
Market Restraints
- Data fragmentation:HIPAA constraints on health data sharing in the United States limit cross-carrier pattern recognition, preserving siloed fraud intelligence.
- Model governance costs:The EU AI Act's explainability requirements elevate compliance spend for pure black-box vendors, compressing margins on standardized products.
- Legacy system debt:Mainframe-bound core systems at established carriers resist API integration with modern fraud detection stacks, extending implementation timelines.
Strategic Opportunities
- Underpenetrated health lines:Medicare Advantage and supplemental health plans in the United States show lower fraud detection automation rates than P&C, creating greenfield deployment potential.
- Behavioral biometrics convergence:Integration of device fingerprinting with claims pattern analysis enables pre-submission fraud flagging before indemnity exposure materializes.
- FCA Consumer Duty alignment:UK insurers face tightened claims-handling standards, opening advisory and audit services for vendors with compliant workflow designs.
Industry Challenges
- Actuarial-ML translation gap:Underwriting teams struggle to validate probabilistic model outputs against traditional reserving methodologies, slowing production deployment.
- Third-party data licensing:Negotiating usage rights for telematics, credit, and public records across jurisdictions consumes legal resources and delays model training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Fraud Detection Market |
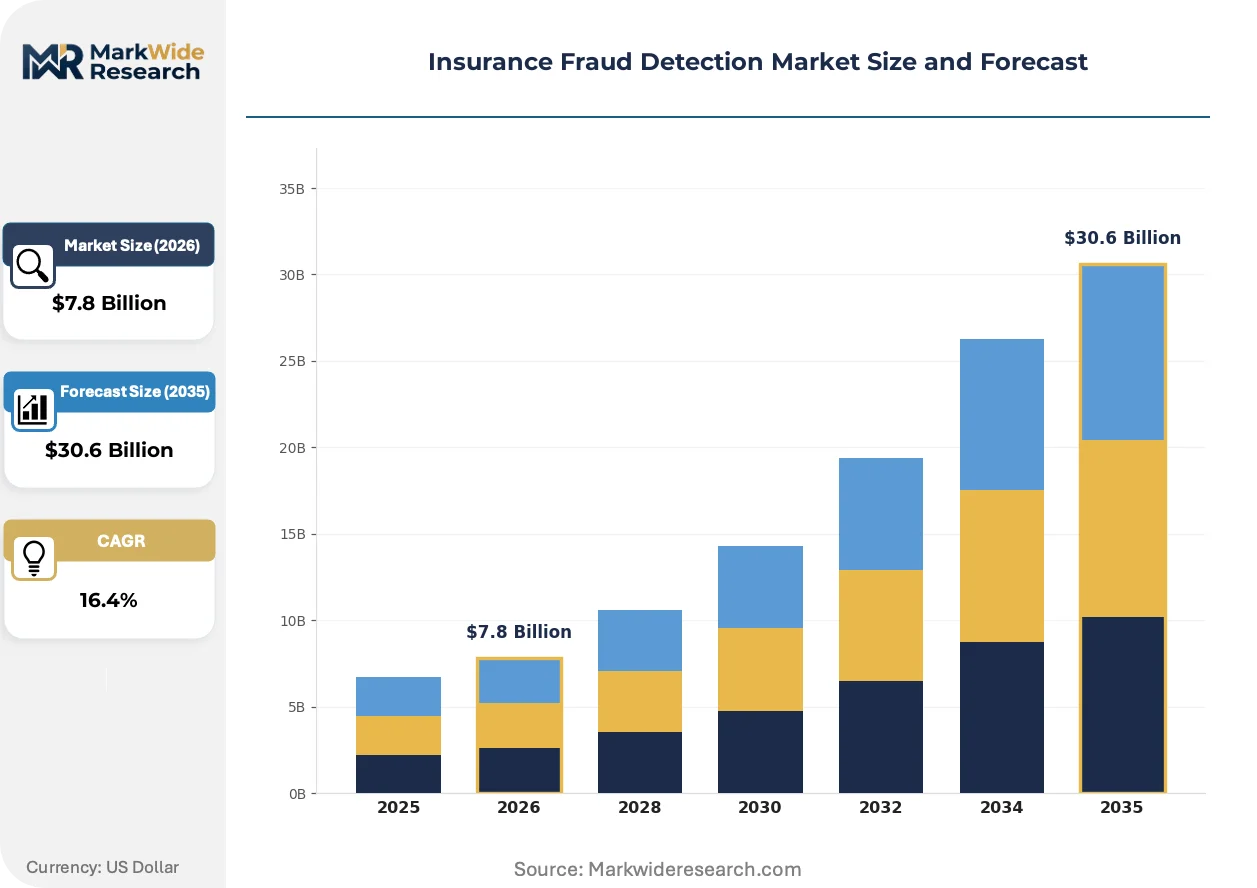
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $30.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Predictive Analytics, Natural Language Processing, Rule-Based Systems Service Type: Fraud Detection Software, Consulting Services, Data Analytics, Managed Services End User: Insurance Companies, Government Agencies, Third-Party Administrators, Financial Institutions Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Fair Isaac Corporation, IBM Corporation, SAS Institute Inc., BAE Systems, Experian plc, LexisNexis Risk Solutions, FRISS, Oracle, DXC Technology Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Fraud Detection Market Strategic Shifts & Innovations
Machine learning architectures are actively displacing static rule engines across fraud detection stacks, with insurers prioritizing adaptive systems that reduce false-positive rates without expanding investigation headcount.
Graph neural networks for fraud detection are decomposing traditional relational database approaches to claims analysis. Mid-market P&C carriers in Germany and the United Kingdom are piloting these systems for beneficiary link analysis. The technology is decomposing siloed policy and claims data into unified entity-resolution graphs that surface organized fraud rings previously invisible to threshold-based scoring.
The EU AI Act's transparency requirements are forcing insurers to document model decision paths for every flagged claim. European health and auto lines face the steepest compliance curves, with carriers investing in interpretability layers that expose feature contributions without exposing proprietary training data. Vendors are responding with modular governance tools that separate explainability infrastructure from core scoring engines.
Buyer procurement patterns are compressing vendor evaluation cycles as regulatory deadlines harden. Tier-one carriers in the United States now demand proof-of-concept deployments within ninety-day windows, displacing traditional twelve-month pilot structures. This acceleration favors vendors with pre-configured connectors to major policy administration systems, particularly in the Medicare Advantage segment where annual enrollment periods create fixed implementation windows.
Insurance Fraud Detection Market Segmentation
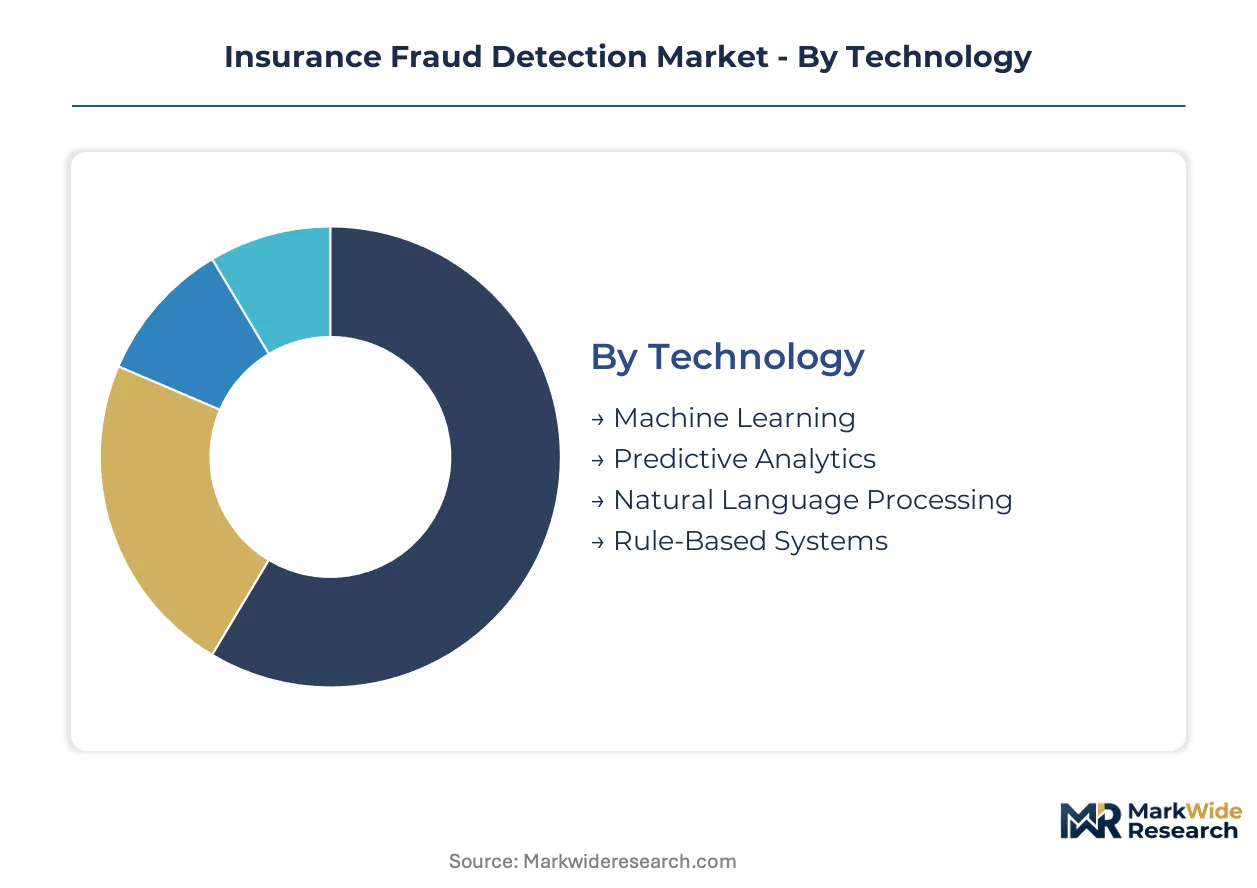
Segmentation in insurance fraud detection reveals how procurement channels, technology maturity, and regulatory exposure shape vendor selection. Carriers weigh deployment flexibility against compliance architecture when allocating budget across solution categories.
Technology:
Machine Learning platforms flow through direct enterprise sales and cloud marketplaces, while Rule-Based Systems reach buyers via legacy system integrators and maintenance renewals.
- Machine Learning:Adaptive algorithms continuously recalibrate anomaly thresholds using claims history, reducing false-positive rates without manual rule updates. United States P&C carriers concentrate procurement here, driven by pressure to collapse investigation timelines from weeks to hours. This segment dominates installed base.
- Predictive Analytics:Statistical models score fraud probability against historical loss patterns, requiring structured training datasets and actuarial validation. European health insurers under EU AI Act mandates are where expansion concentrates, as explainability requirements force replacement of opaque legacy scoring.
- Natural Language Processing:Extracts entities and sentiment from unstructured claims narratives, adjuster notes, and correspondence.
- Rule-Based Systems:Static threshold logic flags claims exceeding velocity, frequency, or monetary limits; persists in mainframe-bound carriers resisting API migration.
Machine Learning dominates installed base. Predictive Analytics is where expansion concentrates.
Service Type:
Cost tier separation shapes this category: Fraud Detection Software commands premium pricing with perpetual licensing, while Managed Services and Consulting occupy lower-margin recurring revenue tiers.
- Fraud Detection Software:Integrated platforms combining scoring engines, case management, and visualization dashboards. Tier-one carriers in the United States and Germany anchor demand, prioritizing real-time API connectivity to policy administration systems. This segment dominates installed base.
- Consulting Services:Model governance advisory, actuarial validation, and regulatory readiness assessments. European markets under EU AI Act compliance deadlines are where expansion concentrates, as carriers rebuild governance frameworks from inference layers upward.
- Data Analytics:External data enrichment, entity resolution, and cross-carrier pattern recognition services.
- Managed Services:Outsourced fraud investigation operations and alert triage for mid-tier carriers lacking specialized headcount.
Fraud Detection Software dominates installed base. Consulting Services is where expansion concentrates.
End User:
Application context varies sharply: Insurance Companies demand integrated platforms, while Government Agencies procure through specialized procurement vehicles with audit-heavy compliance requirements.
- Insurance Companies:Primary demand center spanning P&C, health, and life lines, with procurement authority residing in claims operations and enterprise risk functions. United States Medicare Advantage plans and United Kingdom personal lines show steepest automation penetration. This segment dominates installed base.
- Government Agencies:Public health programs, workers compensation funds, and fraud prosecution units requiring evidentiary-grade audit trails. United States state Medicaid programs are where expansion concentrates, as federal integrity mandates tighten.
- Third-Party Administrators:Claims processing outsourcers serving multiple carrier clients with standardized fraud screening protocols.
- Financial Institutions:Bancassurance operations and lender-placed insurance requiring cross-product anomaly detection.
Insurance Companies dominate installed base. Government Agencies is where expansion concentrates.
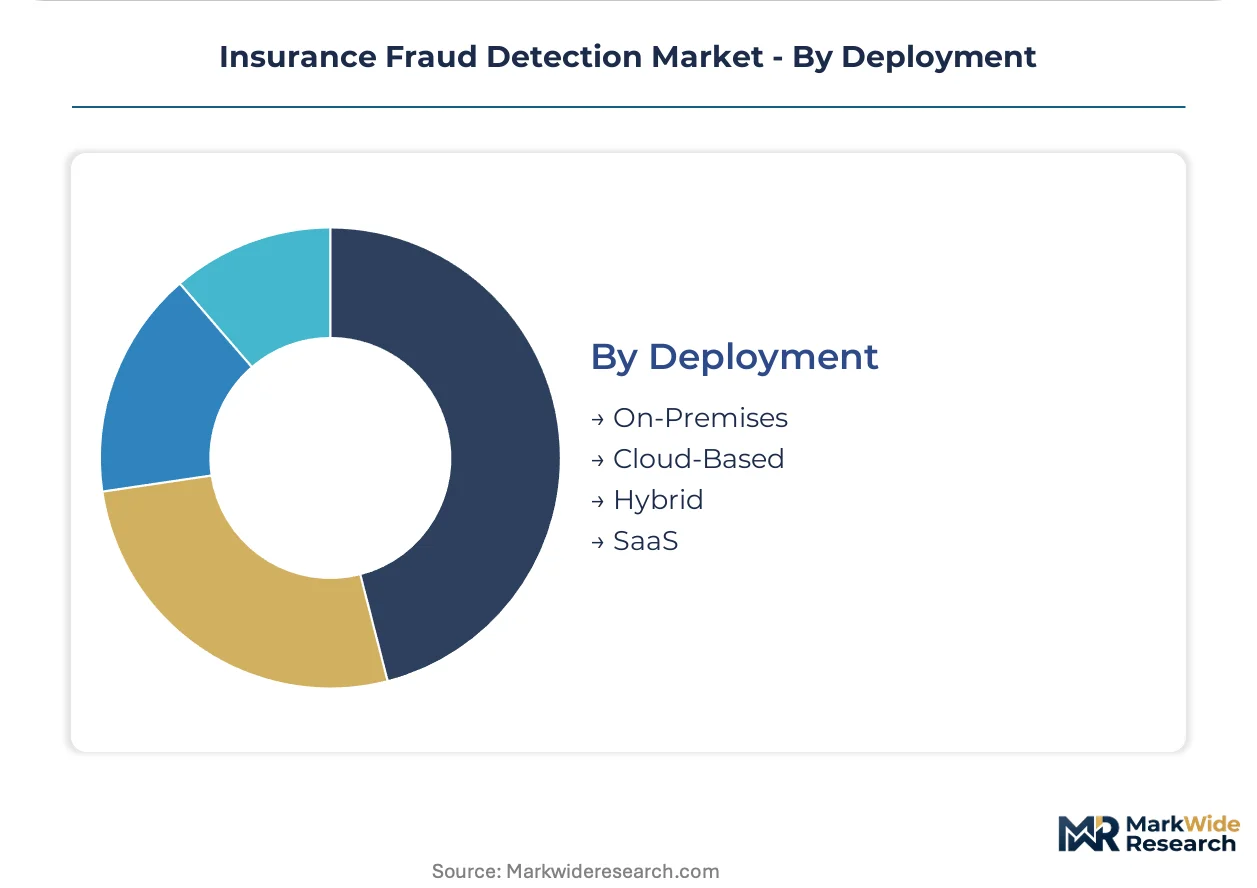
Deployment:
Volume concentration tilts toward Cloud-Based and SaaS among mid-market carriers, while On-Premises persists at tier-one carriers with captive data center infrastructure and stringent data residency requirements.
- Cloud-Based:Elastic compute resources scale with seasonal claims surges, eliminating capital-intensive infrastructure builds. Mid-tier P&C carriers in Germany and the United Kingdom anchor adoption, driven by pressure to bypass multi-year core system replacement cycles. This segment dominates installed base.
- SaaS:Pre-configured fraud scoring modules with subscription pricing and rapid implementation timelines. United States health insurers facing annual enrollment windows are where expansion concentrates, as fixed implementation deadlines compress vendor evaluation cycles.
- On-Premises:Dedicated hardware installations satisfying data sovereignty mandates and air-gapped security requirements.
- Hybrid:Split architectures retaining sensitive data on-premise while leveraging cloud compute for model training.
Cloud-Based dominates installed base. SaaS is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based fraud detection vendors export scoring platforms to United Kingdom and German carriers, while cloud delivery models enable European mid-tier insurers to access North American machine learning architectures without on-premise infrastructure commitments.
United States
Medicare Advantage plans and commercial P&C carriers drive procurement volume for real-time claims scoring. HIPAA governs health data use in fraud analytics, constraining cross-carrier intelligence sharing. Silicon Valley and Boston clusters host machine learning vendors serving national carriers with adaptive anomaly detection.
Germany
Auto and property insurers accelerate replacement of rule-based systems with explainable AI models. The EU AI Act imposes human-oversight requirements on automated claims decisions, forcing governance framework rebuilds. Munich and Frankfurt insurance hubs concentrate vendor pilot programs for graph neural network beneficiary analysis.
United Kingdom
Personal lines carriers face tightened claims-handling standards under FCA Consumer Duty rules. The same regulation opens advisory service opportunities for vendors with compliant workflow designs. London's Lloyd's market and Edinburgh insurance operations anchor demand for audit-grade fraud detection infrastructure.
France
Health mutual insurers deploy fraud screening with emphasis on model interpretability for regulatory defense. CNIL data protection authority scrutinizes automated decision systems for GDPR alignment. Paris-based health technology clusters pilot natural language processing for unstructured claims narrative analysis.
Canada
Provincial auto insurance monopolies and private health carriers split procurement approaches across deployment models. Health Canada and provincial privacy commissioners regulate cross-border data flows for cloud-based scoring. Toronto-Waterloo corridor insurtech clusters develop hybrid architectures satisfying federal data residency requirements.
Insurance Fraud Detection Market Key Industry Players
Player mix skews toward diversified analytics conglomerates with adjacent credit and risk scoring capabilities. Market structure concentrates around three to five platform vendors with established insurer relationships, while specialist fraud detection pure-plays occupy niche advisory tiers. Strategic archetypes include credit-bureau-extended risk platforms, enterprise software conglomerates with insurance modules, and vertical specialists in P&C anomaly detection. Competitive moves center on API pre-configuration for rapid deployment and modular governance tool separation from core scoring engines.
Within the diversified analytics tier, Fair Isaac Corporation and SAS Institute Inc. exemplify platform vendors with entrenched North American insurer relationships. IBM Corporation occupies a position bridging enterprise cloud infrastructure with industry-specific fraud modules. These three anchors represent distinct strategic postures: FICO leverages embedded transaction scoring heritage, SAS sustains loyalty through statistical modeling depth, and IBM integrates fraud detection within broader hybrid cloud migrations.
| Leading Market Players |
|---|
| Fair Isaac Corporation |
| IBM Corporation |
| SAS Institute Inc. |
| BAE Systems |
| Experian plc |
| LexisNexis Risk Solutions |
| FRISS |
| Oracle |
| DXC Technology Company |
| Others |
Cost & Logistics Intelligence
Cloud-native API architectures replacing legacy on-premise rule engines simultaneously redistribute supply geography toward hyperscaler data centers and compress pricing premiums for real-time scoring capabilities. This substitution dynamic concentrates vendor leverage in United States and German cloud regions while eroding margins for mainframe-dependent integrators.
Pricing Analysis
Current-gen machine learning platforms command subscription premiums against prior-gen rule-based systems and next-gen graph neural network pilots. Three-tier pricing structure across premium, standard, and economy levels segments by model explainability depth and API throughput volume. Pricing pressure stems from EU AI Act compliance costs forcing modular governance tool unbundling. Mid-tier P&C carriers in Germany exhibit highest price sensitivity; tier-one United States Medicare Advantage plans show lowest due to fixed implementation windows.
Supply Chain Analysis
Implementation timelines for fraud detection platforms stretch from ninety days to fourteen months depending on core system API readiness. Supply concentrates in United States, Germany, and United Kingdom where vendor engineering hubs cluster near insurance operations. Raw material dependencies include cloud compute credits, proprietary training datasets, and actuarial validation services. Single-source vulnerability runs through hyperscaler infrastructure concentration. Distribution runs through direct enterprise sales and cloud marketplaces with systems integrators handling legacy migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insurance fraud detection market functions as a defensive-moat story anchored in regulatory entrenchment. Switching costs escalate as EU AI Act audit trails and HIPAA compliance documentation accumulate, cementing incumbent positions.
For Market Incumbents: Shield platform market share by embedding modular explainability layers that preempt EU AI Act procurement gates. Accelerate API pre-configuration investments for United States Medicare Advantage annual enrollment windows. Vertical integration into actuarial validation services counters specialist consulting erosion.
For New Entrants and Emerging Players: FCA Consumer Duty fast-track certification opens advisory service white-space in United Kingdom personal lines. Target United States state Medicaid programs where federal integrity mandates compress vendor evaluation cycles. Go-to-market through compliant workflow design partnerships rather than scoring engine displacement.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified analytics conglomerates with adjacent credit scoring capabilities. Long-term viability hinges on cross-selling fraud modules into existing insurer relationships. Watch EU AI Act enforcement variance across member states as inflection indicator for governance tool demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API Pre-Configuration Investment | Reduces Medicare Advantage implementation from fourteen months to ninety-day windows. |
| Modular Governance Tool Separation | Isolates explainability infrastructure from scoring engines for EU AI Act compliance. |
| Graph Neural Network Pilot Expansion | Surfaces organized fraud rings invisible to threshold-based scoring in German P&C. |
| Cloud Marketplace Distribution | Bypasses capital-intensive infrastructure builds for United Kingdom mid-tier carriers. |
| Actuarial Validation Service Integration | Bridges actuarial-ML translation gap slowing production deployment at tier-one carriers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, vendor technical documentation, and carrier procurement records. Primary interviews engaged claims operations executives, enterprise risk officers, regulatory compliance leads, and fraud investigation unit heads across United States, United Kingdom, and German insurance markets. Secondary sources included SEC 10-K disclosures, EU AI Act implementation guidance, HIPAA enforcement actions, and FCA Consumer Duty consultation papers. Bottom-up sizing triangulated against top-down addressable market estimates.
Segmentation dimensions modeled span technology generation, service type, end-user category, and deployment architecture across the analysis window. CAGRs derived from historical adoption curves weighted by regulatory deadline proximity and carrier digital maturity. Industry-specific inputs included seasonal claims surge patterns, annual enrollment period constraints, and cross-carrier data sharing restrictions.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and stable cloud infrastructure pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions without contingency for abrupt HIPAA enforcement shifts or hyperscaler service discontinuation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
UK Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Europe Insurance Telematics Market