
 United States Hot Sauce Market | 2026-2036
United States Hot Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hot Sauce Market Intelligence
Mexico's chile pepper processing capacity is reshaping raw material flows into the United States hot sauce supply chain. McIlhenny Company leverages its Avery Island fermentation heritage to sustain premium positioning in aged cayenne segments. Huy Fong Foods anchors volume production through its Irwindale facility, while TW Garner Food Company dominates retail shelf space with Texas Pete's established grocery channel control.
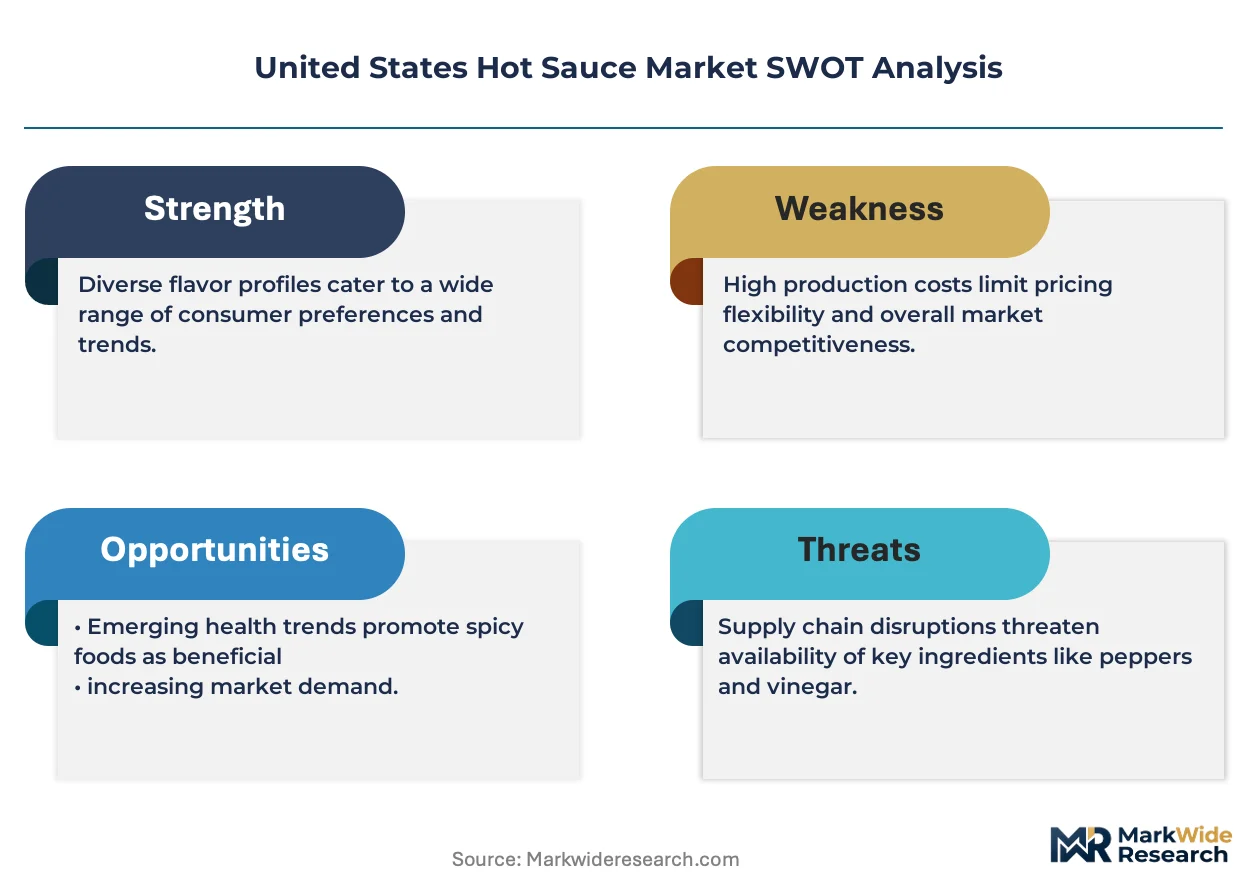
Hot sauce comprises chili pepper-based condiments formulated with vinegar, salt, and auxiliary spices, typically achieving pH levels below 4.6 for shelf-stable preservation without refrigeration. The product functions primarily as a flavor enhancement layer across foodservice and retail channels, with Scoville heat units serving as the standard functional classification parameter. Specialty and organic product types command margin premiums as clean-label formulations displace conventional preservative-heavy alternatives. Chili pepper ingredient sourcing creates structural concentration risk, with New Mexico Hatch and California Central Valley varieties defining quality benchmarks.
FDA food safety protocols and USDA organic certification standards govern labeling, pathogen control, and ingredient provenance claims across domestic production. State-level cottage food laws in Texas, Louisiana, and California create fragmented market access pathways for artisanal entrants. Stakeholders must monitor FDA enforcement priorities around imported spice adulteration and evolving sodium disclosure mandates.
Market Dynamics
Quick-service restaurant chains are embedding hot sauce as a permanent condiment fixture, forcing suppliers to scale fermentation capacity while maintaining pH stability below 4.6 for shelf-stable distribution without cold chain dependency.
Growth Catalysts
- Fast-casual expansion:Chipotle and similar chains now stock proprietary hot sauce formulations at every service counter, creating captive demand for aged cayenne and habanero mash suppliers.
- FDA Food Safety Modernization Act traceability mandates:The regulation forces spice importers to document lot-level provenance, advantaging domestic chile processors with established audit trails over opaque foreign suppliers.
- Hispanic culinary influence:Salsa and hot sauce consumption in the American Southwest now exceeds ketchup in household penetration, concentrating ingredient sourcing around New Mexico Hatch and California Central Valley growing regions.
Market Restraints
- Chile pepper supply concentration:Over sixty percent of domestic mash supply originates from California Central Valley irrigation-dependent acreage, exposing processors to drought-induced input volatility.
- Fermentation capacity scarcity:Extended aging requirements for premium cayenne segments tie up tank infrastructure for eighteen to thirty-six months, constraining rapid volume scaling.
- Imported spice adulteration risk:FDA enforcement actions against undeclared Sudan dye and lead contamination in foreign chile shipments create compliance friction for cost-sensitive brands.
Strategic Opportunities
- Texas cottage food law pathway:Artisanal producers can now commercialize pH-tested formulations without commercial kitchen overhead, lowering barrier to entry for small-batch fermented products.
- Clean-label organic certification:USDA organic standards for spice handling command thirty to fifty percent shelf price premiums as conventional preservative-heavy alternatives lose retail placement.
- Direct-to-restaurant distribution:Foodservice broadliners are ceding share to specialty distributors who bundle hot sauce with technical pH documentation and custom Scoville calibration.
Industry Challenges
- Fermentation microbiology talent scarcity:Industrial-scale lacto-fermentation expertise resides primarily with legacy Louisiana and California operators, limiting new entrant replication.
- Legacy equipment retrofit costs:Stainless steel tank farms and automated pH monitoring systems require seven-figure capital deployment before first commercial batch release.
- Scoville standardization disputes:High-performance liquid chromatography certification methods vary between laboratories, creating label claim litigation exposure for extreme-heat positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hot Sauce Market |
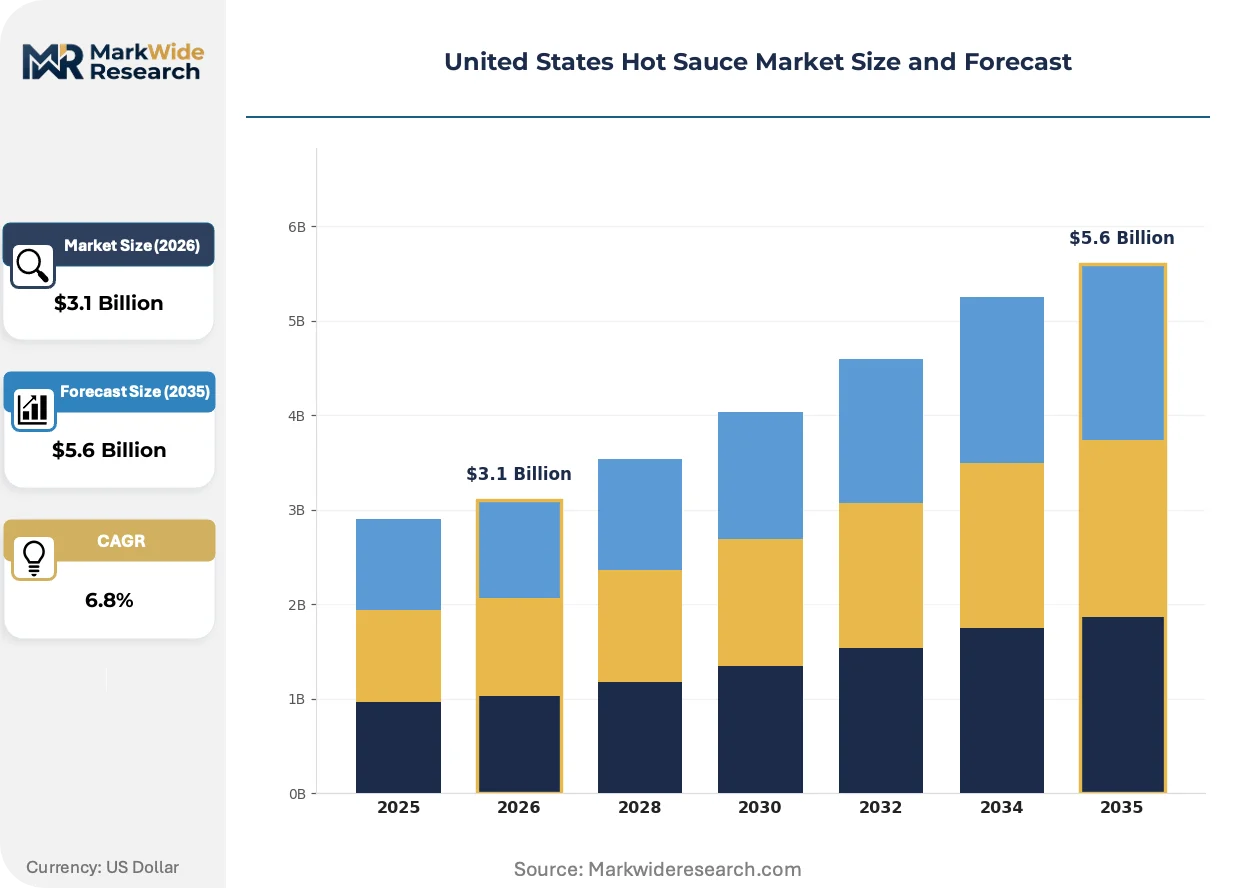
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Specialty, Organic, Gourmet Ingredient: Chili Peppers, Vinegar, Garlic, Spices Flavor Profile: Sweet, Spicy, Smoky, Tangy Packaging Type: Bottles, Pouches, Jars, Tubs |
| Companies Covered | McCormick & Company, McIlhenny Company, Huy Fong Foods, Baumer Foods, The Kraft Heinz Company, B&G Foods, TW Garner Food Company, Hormel Foods Corporation, Conagra Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hot Sauce Market Strategic Shifts & Innovations
Clean-label formulation pressures are forcing ingredient disclosure to the mash batch level, while fermentation process transparency becomes a competitive differentiator in premium positioning.
Fermentation science is migrating from legacy open-vat Louisiana methods to controlled anaerobic tank systems with real-time pH telemetry. Mid-tier processors in Texas and New Mexico are adopting these systems to reduce batch failure rates and accelerate time-to-market for aged cayenne products. This technology compression enables smaller operators to achieve consistency benchmarks previously requiring decades of Avery Island heritage.
FDA enforcement priorities around imported spice adulteration are tightening documentation requirements for foreign chile suppliers. The industrial consequence is a sourcing pivot toward domestic New Mexico Hatch and California Central Valley contract growing arrangements with third-party audit verification. Premium and organic segments are responding fastest, embedding lot-level blockchain traceability to preempt regulatory action and support clean-label marketing claims.
Foodservice procurement teams are consolidating hot sauce specifications around single-source fermentation partners with validated pH stability data. Broadline distributors are losing placement to specialty condiment houses who bundle technical documentation with volume pricing commitments. This channel compression is most visible in the American Southwest, where fast-casual chains now require quarterly Scoville calibration certificates as a condition of continued supply relationships.
United States Hot Sauce Market Segmentation
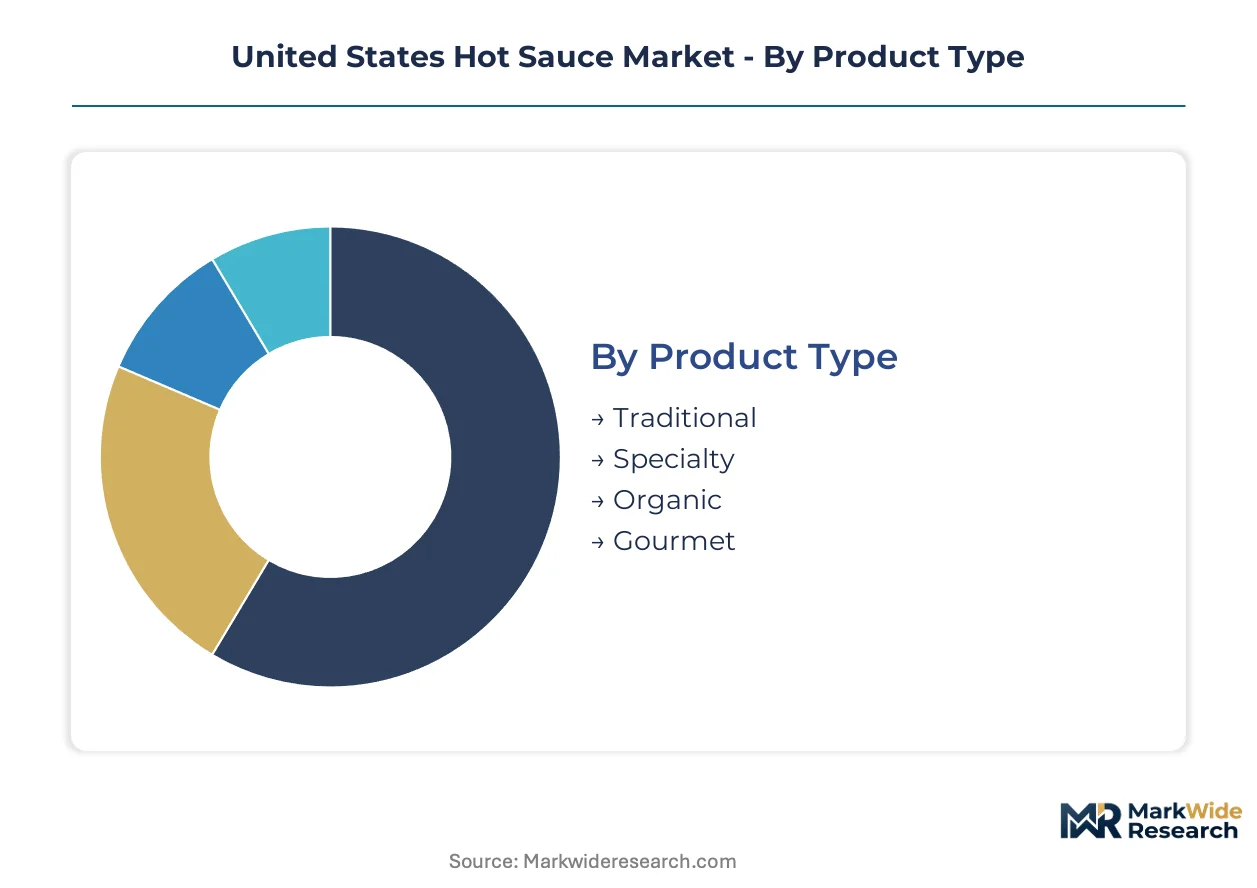
Hot sauce segmentation reflects divergent supply chain requirements across fermentation complexity, ingredient provenance, and distribution channel specifications. Each dimension carries distinct regulatory burdens and margin structures that shape competitive positioning.
Product Type:
Product type spans the use-case spectrum from commodity table condiments to chef-caliber finishing sauces with documented mash provenance.
- Traditional:Aged cayenne formulations with pH below 4.6 dominate foodservice procurement through validated shelf stability. Quick-service restaurants in Texas and the American Southwest specify traditional variants for permanent condiment placement.
- Specialty:Fermented mash products from specific chile varieties command technical documentation requirements. Fast-casual chains now mandate quarterly Scoville calibration certificates for continued supply relationships.
- Organic:USDA certification compliance adds audit trail overhead. Clean-label positioning supports thirty to fifty percent shelf price premiums.
- Gourmet:Small-batch production with controlled anaerobic fermentation. Texas cottage food law pathways enable commercialization without commercial kitchen overhead.
Established volume favors Traditional; emerging adoption favors Specialty.
Ingredient:
Ingredient sourcing determines regulatory exposure and supply concentration risk across domestic growing regions.
- Chili Peppers:California Central Valley irrigation-dependent acreage supplies over sixty percent of domestic mash. Drought-induced input volatility creates structural price pressure.
- Vinegar:Acetic acid concentration governs pH stability for shelf-stable preservation. Industrial white vinegar dominates cost-sensitive formulations.
- Garlic:Fresh bulb inclusion requires cold chain management for raw formulations. Dehydrated alternatives reduce spoilage risk in extended distribution.
- Spices:FDA enforcement against undeclared Sudan dye and lead contamination favors domestic sourcing with third-party audit verification.
Supply security favors Chili Peppers; margin expansion favors Spices.
Flavor Profile:
Flavor positioning aligns with demographic consumption patterns and menu integration depth.
- Sweet:Honey or fruit-forward formulations attract younger demographics. Fast-casual breakfast chains drive adoption for chicken and waffle applications.
- Spicy:High Scoville positioning targets heat-seeking consumers. HPLC certification methods vary between laboratories, creating label claim litigation exposure.
- Smoky:Chipotle and smoked paprika variants align with barbecue culture penetration. Texas and Louisiana operators dominate heritage production methods.
- Tangy:Elevated vinegar brightness suits seafood and fried food pairings. Coastal California and Gulf Coast foodservice channels concentrate demand.
Menu integration favors Spicy; demographic expansion favors Sweet.
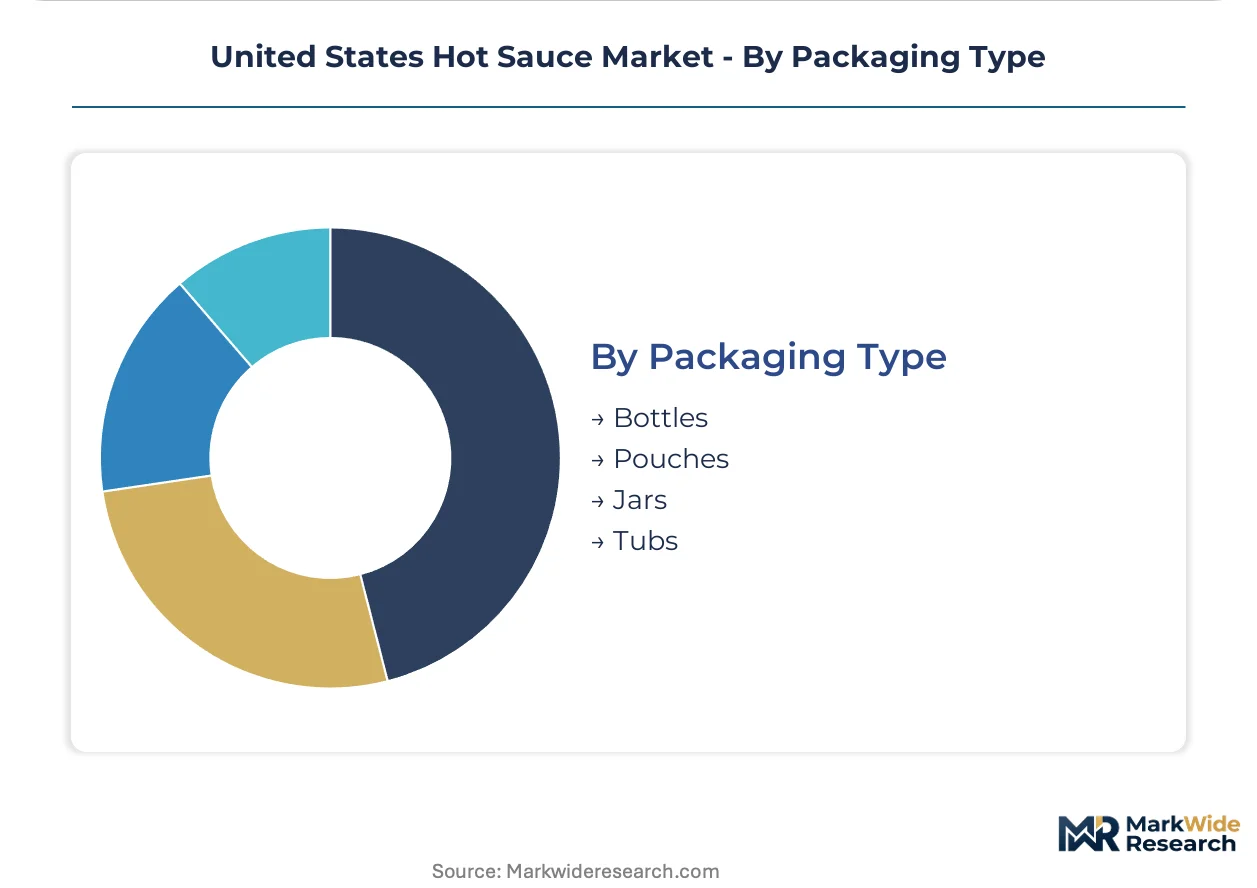
Packaging Type:
Packaging selection reflects channel economics and consumption occasion fragmentation.
- Bottles:Glass and PET formats dominate retail shelf placement with established pour control. Grocery channel control requires seven-figure slotting fee commitments.
- Pouches:Flexible formats reduce shipping cube and material cost. Foodservice single-serve applications are displacing portion cups.
- Jars:Wide-mouth formats suit salsa-style products with visible particulate. Hispanic household penetration in the American Southwest exceeds ketchup alternatives.
- Tubs:Foodservice bulk formats support back-of-house dispensing. Stainless steel pump systems require compatibility testing for acidic formulations.
Retail dominance favors Bottles; foodservice efficiency favors Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic chile processing clusters concentrate in irrigation-dependent growing regions, exposing fermentation capacity to water supply volatility. FDA traceability mandates favor processors with established lot-level documentation over foreign suppliers facing adulteration enforcement.
American Southwest
New Mexico Hatch chile cultivation anchors premium mash sourcing for aged cayenne formulations. State-level cottage food laws in Texas and New Mexico enable artisanal producers to commercialize pH-tested products without commercial kitchen overhead. Albuquerque and Las Cruces fermentation facilities are expanding controlled anaerobic tank capacity to meet fast-casual chain documentation requirements.
California Central Valley
Irrigation-dependent acreage supplies over sixty percent of domestic chile mash, creating structural drought exposure for processors. California Department of Food and Agriculture audit programs enforce third-party verification for organic certification claims. Fresno and Bakersfield processing clusters are embedding blockchain traceability to preempt FDA enforcement actions on imported spice adulteration.
Louisiana Gulf Coast
Heritage open-vat fermentation expertise concentrates in Iberia Parish and surrounding parishes with decades of lacto-fermentation tradition. Louisiana Department of Health cottage food provisions allow small-batch producers to scale without immediate commercial facility investment. Avery Island and New Orleans fermentation heritage sustains premium positioning for aged cayenne segments requiring eighteen to thirty-six month aging cycles.
Texas Triangle
Hispanic culinary influence drives household penetration exceeding ketchup alternatives in Houston, San Antonio, and Dallas-Fort Worth metro areas. Texas Department of State Health Services cottage food law amendments lowered barrier to entry for pH-tested artisanal formulations. Austin and San Antonio specialty distributors are displacing broadline foodservice channels through bundled technical documentation and custom Scoville calibration.
Southeast Atlantic
Barbecue culture penetration concentrates smoky flavor profile demand in Georgia, North Carolina, and Florida foodservice channels. State agriculture department inspection protocols govern acidified food manufacturing for interstate commerce. Atlanta and Charlotte distribution hubs are consolidating procurement around single-source fermentation partners with validated pH stability data.
United States Hot Sauce Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with fermentation capacity and provenance documentation. The vendor base stratifies across legacy heritage operators, scale-driven commodity processors, and artisanal cottage-law entrants. Three archetypes dominate: fermentation-heritage premium players, volume-scale grocery channel controllers, and clean-label organic specialists. Competitive moves concentrate on capacity expansion for controlled anaerobic systems and backward integration into contract chile growing arrangements.
Within the heritage fermentation tier, McIlhenny Company occupies a position exemplifying Avery Island legacy methods, while Huy Fong Foods anchors volume production scale. TW Garner Food Company represents grocery channel control through established retail shelf presence. These three operators collectively illustrate the competitive spectrum from premium aged positioning through mass-market distribution efficiency.
| Leading Market Players |
|---|
| McCormick & Company |
| McIlhenny Company |
| Huy Fong Foods |
| Baumer Foods |
| The Kraft Heinz Company |
| B&G Foods |
| TW Garner Food Company |
| Hormel Foods Corporation |
| Conagra Brands |
| Others |
Cost & Logistics Intelligence
Interstate 10 freight corridors linking California Central Valley chile processors to Texas and Louisiana fermentation facilities transmit drought-driven input cost volatility directly into downstream price differentiation. California irrigation scarcity and Louisiana tank farm capacity constraints together compress margins for mid-tier operators while amplifying premium capture for heritage producers with documented Avery Island aging cycles.
Pricing Analysis
FDA Food Safety Modernization Act traceability mandates dictate the pricing tier structure across the United States hot sauce market. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified products with blockchain lot documentation from conventional preservative-heavy alternatives and unbranded foodservice commodity supply. Cost compression in the standard tier intensifies because California drought-induced chile mash scarcity forces contract renegotiations every growing season. Quick-service restaurant procurement teams exhibit highest price sensitivity due to volume scale requirements, while fast-casual chains with proprietary formulation partnerships demonstrate lowest sensitivity to per-unit fluctuations.
Supply Chain Analysis
Chile pepper feedstock availability centers on Mexico, California, and New Mexico as the primary upstream sourcing anchors for United States hot sauce production. Domestic processors draw from California Central Valley irrigation-dependent acreage, New Mexico Hatch contract growing arrangements, and Mexican cross-border processing capacity for fermented mash supply. Single-source vulnerability concentrates in California water rights allocation uncertainty, exposing fermentation facilities to input interruption risk during drought declaration periods. Distribution runs through specialty condiment houses bundling technical pH documentation with volume commitments, displacing traditional broadline foodservice channels in fast-casual procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States hot sauce incumbents face substitution pressure from private-label retail formulations and restaurant-proprietary hot sauce programs that bypass branded shelf placement entirely.
For Market Incumbents: Entrench fermentation capacity advantages by retrofitting California and Louisiana facilities with controlled anaerobic tank systems featuring real-time pH telemetry. Secure backward integration into New Mexico Hatch and California Central Valley contract growing arrangements with third-party audit verification to preempt FDA enforcement exposure on imported spice adulteration. Channel control through direct-to-restaurant distribution partnerships with quarterly Scoville calibration certificates locks out specialty distributor intermediaries.
For New Entrants and Emerging Players: Southeast Atlantic barbecue culture penetration represents the most penetrable geographic underpenetration for smoky flavor profile specialists. Texas cottage food law pathways enable pH-tested artisanal commercialization without seven-figure commercial kitchen overhead, creating viable scaling routes for small-batch producers. Foodservice bulk tub formats for back-of-house dispensing offer the strongest go-to-market angle against entrenched bottle-centric retail incumbents.
For Investors and Strategic Acquirers: FDA enforcement priority shifts on imported spice adulteration reshape the acquisition landscape toward domestic fermentation operators with established lot-level documentation infrastructure. Long-term viability across the projection horizon favors controlled anaerobic tank technology adopters over legacy open-vat heritage operators facing microbiology talent scarcity. Watch for USDA organic certification audit backlogs as the inflection signal indicating clean-label premium capture sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Controlled anaerobic tank deployment reduces batch failure rates and accelerates aged cayenne time-to-market. |
| Contract Growing Arrangements | Third-party audited New Mexico Hatch and California Central Valley sourcing preempts FDA adulteration enforcement. |
| Direct-to-Restaurant Distribution | Specialty condiment houses displace broadliners through bundled pH documentation and custom Scoville calibration. |
| USDA Organic Certification Investment | Clean-label positioning commands shelf price premiums as conventional preservative alternatives lose retail placement. |
| Blockchain Traceability Implementation | Lot-level provenance documentation supports premium marketing claims and regulatory compliance verification. |
Research Approach
A spread of perspectives from fermentation facility operators, fast-casual chain procurement directors, specialty condiment distributors, and FDA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary field engagement with Louisiana heritage producers, California Central Valley chile growers, and Texas cottage food law artisans combined with secondary validation against FDA enforcement action databases, USDA organic certification audit records, and state-level cottage food statute filings. Bottom-up volume triangulation from individual fermentation facility capacity and top-down demand calibration from quick-service restaurant condiment placement data anchored the modeling framework.
Demand-supply balance dynamics across the analysis window shaped the analytical framework through segmentation across product type, ingredient provenance, flavor profile positioning, and packaging format specifications. CAGRs derived from trend extrapolation of fermentation capacity expansion rates, fast-casual chain outlet growth, and clean-label adoption curves within Hispanic household penetration data. Chile mash supply volatility from California irrigation constraints and FDA traceability mandate compliance costs served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by controlled anaerobic tank technology adopters or sudden FDA enforcement surges on imported spice shipments would shift outcomes substantially. Cross-checking against state agriculture department acidified food manufacturing inspection records and specialty distributor shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market